
 Asia Pacific Solid State Transformers Market | 2026-2036
Asia Pacific Solid State Transformers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Solid State Transformers Market Outlook
A shortage of power electronics engineers with silicon carbide and gallium nitride fabrication expertise is unwinding project timelines across the Asia Pacific Solid State Transformers Market. Hitachi ABB leverages its integrated circuit heritage to dominate high-voltage converter prototyping in Japan and Australia. Siemens AG anchors its position through modular design platforms that reduce commissioning complexity for utility clients. Schneider Electric sustains competitive differentiation by controlling distribution channels across Southeast Asian smart grid rollouts.
Solid state transformers replace conventional electromagnetic units with power semiconductor switches, typically rated between 1.2 kV and 13.8 kV, enabling bidirectional power flow and real-time voltage regulation for grid modernization. Converter segments lead current revenue contribution due to their centrality in AC-DC-AC power conditioning architectures, while inverter applications in offshore wind interconnection represent the fastest-growing margin pool. Grid-connected technology frameworks are maturing fastest in utility procurement, though hybrid framework designs are gaining traction among industrial sector buyers seeking islanding capability.
Japan's METI enforces JIS standards for grid-interactive power converters, while China's MIIT coordinates GB standards development through national smart grid demonstration zones. Australia's CEA and India's CEA impose divergent frequency and harmonic distortion thresholds that fragment certification requirements across the region. Stakeholders must monitor which national regulator moves first on unified medium-voltage SST interoperability standards, as that jurisdiction will likely shape procurement specifications for cross-border projects.
Market Dynamics
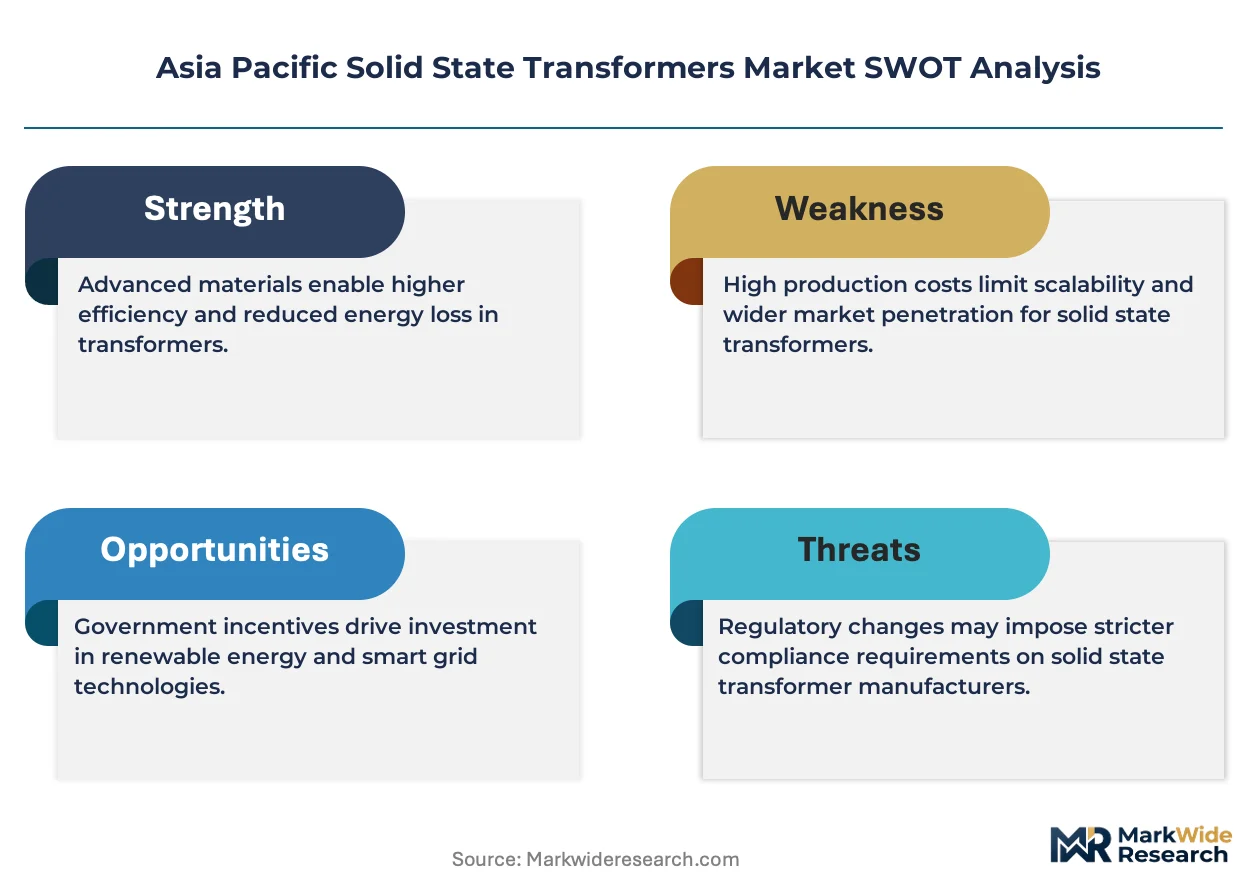
China's dual carbon goals and grid modernization mandates are compressing procurement timelines for SST deployment across state-owned power enterprises, forcing a technology transition from electromagnetic to semiconductor-based architectures.
Growth Catalysts
- Renewable Integration Mandates:China's MIIT coordinates GB standards development through national smart grid demonstration zones, accelerating utility procurement for offshore wind interconnection projects.
- Earthquake-Resilient Infrastructure Requirements:Japan's METI enforces JIS standards for grid-interactive power converters, driving pilot-to-deployment transitions in Tokyo and Osaka metropolitan networks.
- Silicon Carbide Fabrication:Power semiconductor switches rated between 1.2 kV and 13.8 kV enable bidirectional power flow, replacing conventional electromagnetic units in utility-scale installations.
Market Restraints
- Engineering Talent Scarcity:A shortage of power electronics engineers with silicon carbide and gallium nitride fabrication expertise unwinds project timelines across the region.
- Fragmented Certification Requirements:Australia's CEA and India's CEA impose divergent frequency and harmonic distortion thresholds that complicate cross-border equipment deployment.
- Converter Cost Structure:High-voltage converter prototyping requires specialized semiconductor foundry access concentrated in Japan and South Korea.
Strategic Opportunities
- Southeast Asian Smart Grid Rollouts:Distribution channel control across Thailand, Vietnam, and Indonesia creates first-mover positioning for modular SST platforms.
- Hybrid Framework Designs:Industrial sector buyers in Australia's mining corridors seek islanding capability, opening demand for dual-mode converter-inverter systems.
- Unified Interoperability Standards:Stakeholders monitoring which national regulator moves first on medium-voltage SST standards will shape procurement specifications for regional projects.
Industry Challenges
- Commissioning Complexity:Modular design platforms reduce deployment friction but require field engineering capabilities that utilities lack in-house.
- Legacy Grid Integration:Real-time voltage regulation capabilities must interface with aging electromagnetic transformer infrastructure without service interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Solid State Transformers Market |
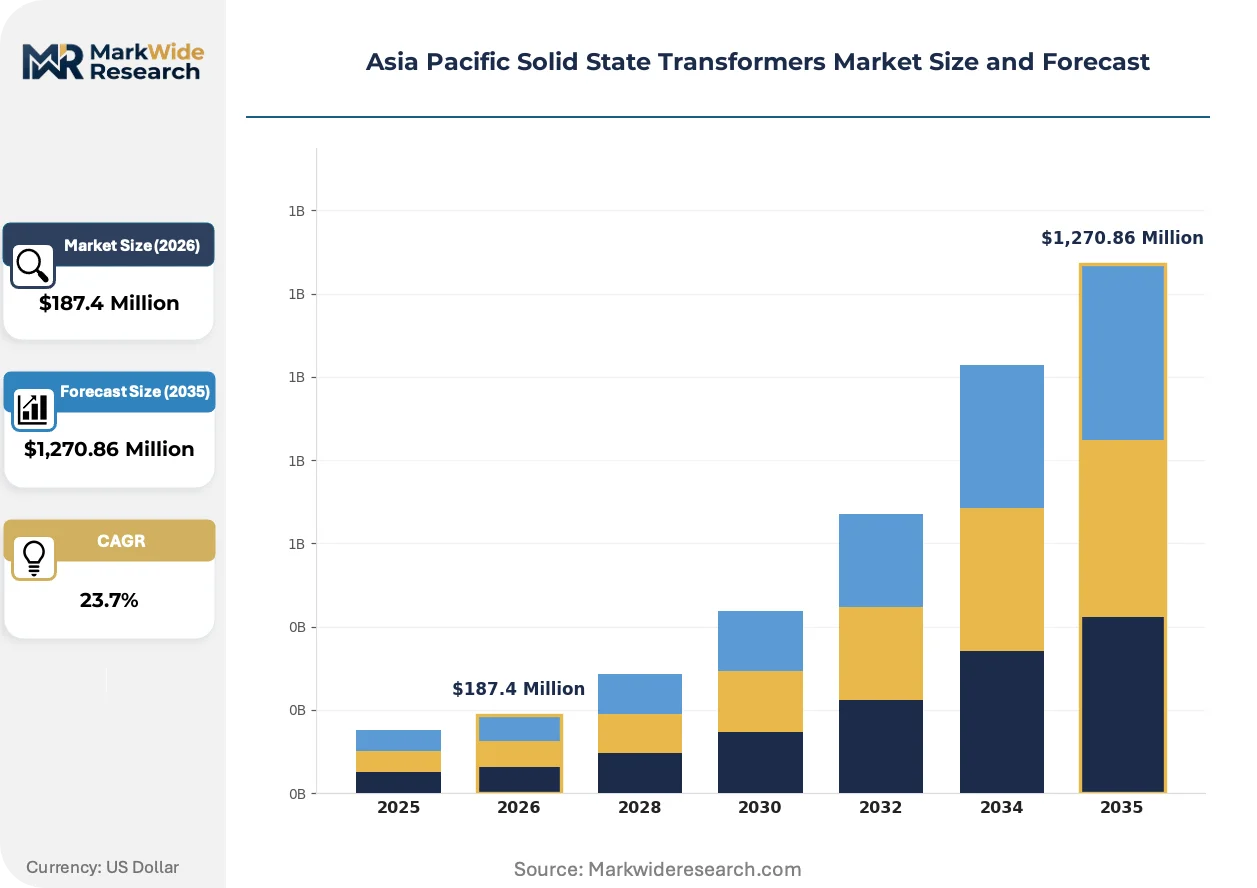
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Converter, Inverter, Rectifier, Transformer End User: Utilities, Renewable Energy, Industrial Sector, Commercial Sector Technology: Integrated Circuit, Modular Design, Hybrid Framework, Grid-Connected Application: Smart Grids, Electric Vehicles, Power Distribution, Energy Storage |
| Companies Covered | Hitachi ABB, Schneider Electric, General Electric, Mitsubishi Electric, Siemens AG, Delta Electronics, Alstom, Eaton Corporation, Synergy Transformers, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Solid State Transformers Market Strategic Shifts
Semiconductor-based power conditioning architectures are displacing conventional electromagnetic systems, with converter-inverter integration emerging as the central technical battleground for grid modernization contracts.
Gallium nitride power semiconductors enable higher switching frequencies than silicon alternatives, reducing transformer footprint and cooling requirements. Offshore wind developers in Japan and South Korea are adopting these devices for subsea interconnection projects. The technology is bifurcating procurement specifications between premium high-frequency systems and cost-optimized silicon carbide alternatives.
METI's smart grid roadmaps in Japan mandate real-time grid monitoring capabilities that conventional transformers cannot provide. This regulatory pressure forces utilities to accelerate SST pilot programs beyond original timelines. Converter segments lead revenue contribution as a direct consequence of these procurement specifications.
Utility buyers now demand performance-based commissioning contracts that transfer operational risk to equipment suppliers. This restructuring displaces traditional equipment-purchase models in Tokyo and Osaka metropolitan networks. Australia's mining sector follows a similar pattern, requiring islanding guarantees for remote site installations.
Asia Pacific Solid State Transformers Market Segmentation
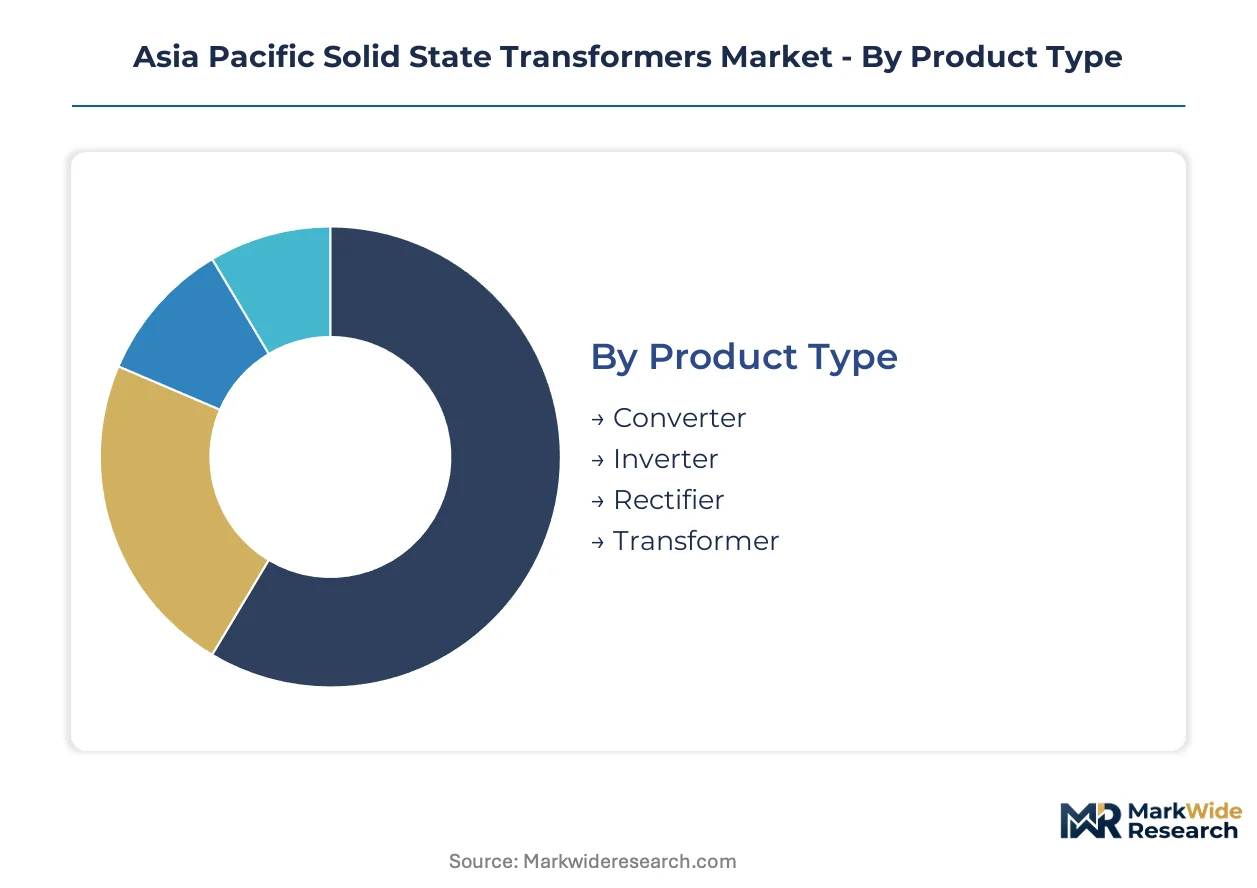
Solid state transformer procurement specifications diverge sharply across Asia Pacific jurisdictions, with national regulators enforcing incompatible technical standards that reshape segment prioritization. Manufacturers must architect product portfolios around certification requirements rather than pure performance optimization.
Product Type:
China's MIIT and Japan's METI enforce divergent voltage regulation tolerances that favor distinct converter architectures in procurement tenders.
- Converter:AC-DC-AC power conditioning architectures dominate utility-scale installations. Demand concentrates in China's state-owned power enterprises procuring for offshore wind interconnection, where bidirectional power flow capabilities satisfy dual carbon procurement mandates.
- Inverter:DC-AC conversion modules enable real-time grid synchronization for distributed renewable assets. Japan's Tokyo and Osaka metropolitan networks drive pilot-to-deployment transitions as METI's earthquake-resilient infrastructure requirements accelerate semiconductor-based replacements of electromagnetic units.
- Rectifier:AC-DC conversion stages condition power for industrial DC bus applications in Australia's mining corridors.
- Transformer:Isolation stages complete voltage transformation functions in hybrid framework designs.
Established volume favors Converter; emerging adoption favors Inverter.
End User:
Utility procurement timelines compress as grid modernization mandates displace conventional equipment replacement cycles.
- Utilities:State-owned power enterprises in China anchor procurement volume for grid-connected installations. Japan's METI smart grid roadmaps force accelerated SST deployment across Tokyo and Osaka distribution networks.
- Renewable Energy:Offshore wind developers in Japan and South Korea adopt gallium nitride devices for subsea interconnection projects, climbing the fastest as a margin pool.
- Industrial Sector:Australia's mining operators demand islanding guarantees for remote site converter-inverter systems.
- Commercial Sector:Building-scale microgrid installations in Southeast Asian urban centers seek modular platforms.
Procurement scale concentrates with Utilities; technical complexity concentrates with Renewable Energy.
Technology:
Foundry access constraints in Japan and South Korea determine which semiconductor architectures reach commercial deployment.
- Integrated Circuit:Silicon carbide and gallium nitride fabrication expertise enables high-voltage converter prototyping. Hitachi ABB leverages this heritage to dominate prototyping for Japanese and Australian utility clients.
- Modular Design:Standardized subsystems reduce commissioning complexity for field deployment. Siemens AG anchors market position through platforms that address utility capability gaps.
- Hybrid Framework:Dual-mode converter-inverter systems provide islanding capability for industrial buyers in Australia's mining corridors.
- Grid-Connected:Utility-scale frameworks mature fastest in procurement specifications issued by China's state-owned power enterprises.
Commercial maturity favors Grid-Connected; capability scarcity constrains Integrated Circuit.
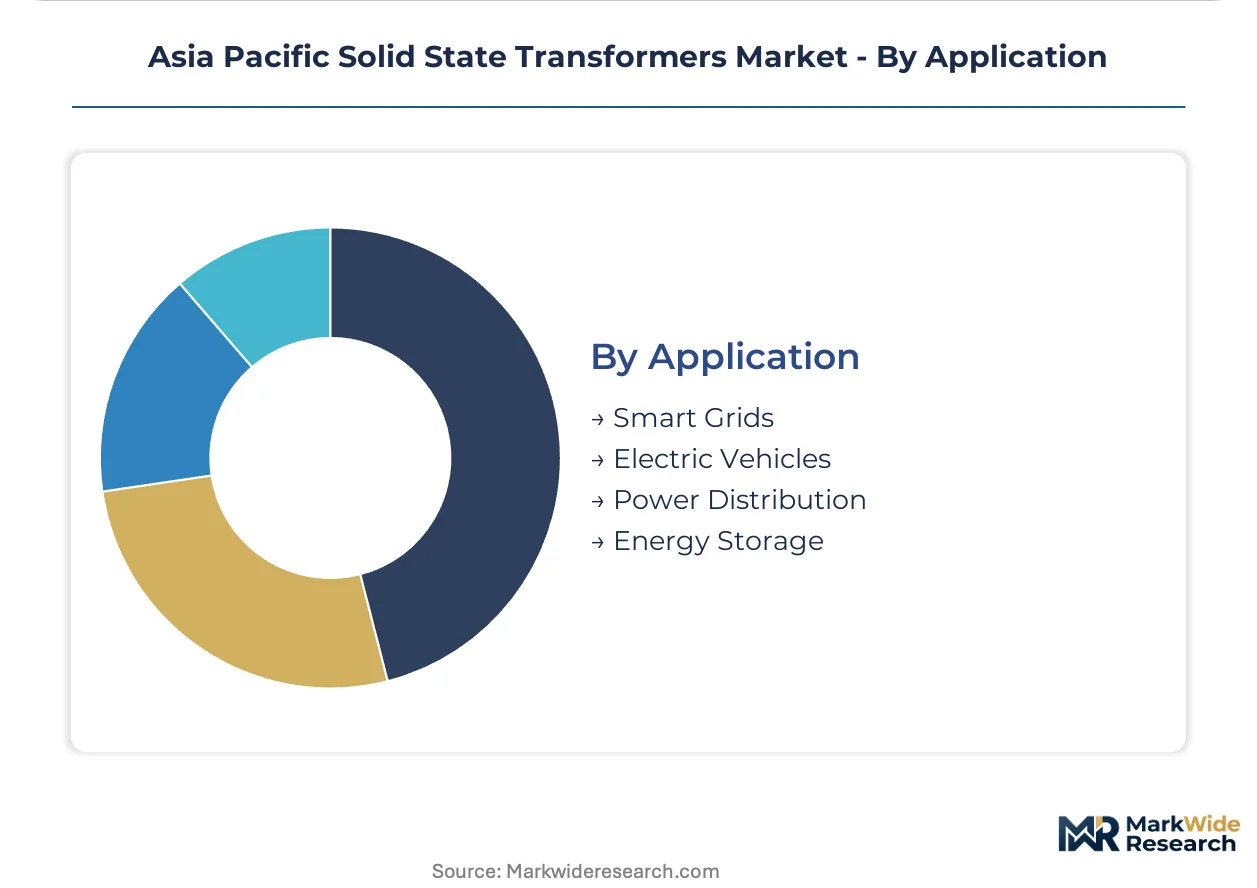
Application:
Smart grid mandates in Japan and renewable integration requirements in China bifurcate demand across metropolitan and interconnection use cases.
- Smart Grids:Real-time voltage regulation capabilities satisfy METI monitoring mandates that conventional transformers cannot fulfill. Tokyo and Osaka metropolitan networks drive segment concentration.
- Electric Vehicles:Charging infrastructure bidirectional power flow enables vehicle-to-grid services in South Korean pilot zones.
- Power Distribution:Medium-voltage SST deployment accelerates across China's national smart grid demonstration zones.
- Energy Storage:Battery interconnection projects in Australia's renewable zones demand hybrid converter architectures.
Regulatory enforcement favors Smart Grids; infrastructure buildout favors Power Distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT coordinates GB standards development through China's national smart grid demonstration zones, compressing procurement timelines for state-owned power enterprises replacing conventional electromagnetic units with semiconductor-based architectures.
China
Dual carbon goals accelerate utility-scale SST deployment across offshore wind interconnection projects. MIIT's GB standards mandate bidirectional power flow capabilities in procurement specifications. Yangtze River Delta demonstration zones concentrate pilot-to-deployment transitions for grid modernization.
Japan
METI's earthquake-resilient infrastructure requirements drive semiconductor-based replacements of electromagnetic units in metropolitan networks. JIS standards enforcement for grid-interactive power converters accelerates procurement. Tokyo and Osaka distribution networks lead pilot program expansion beyond original timelines.
South Korea
Gallium nitride device adoption for subsea interconnection projects climbs fastest among renewable energy developers. MFDS-aligned technical specifications shape procurement for offshore wind infrastructure. Busan-Ulsan industrial corridors anchor converter-inverter integration for marine renewable projects.
Australia
Mining operators in Western Australia demand islanding guarantees for remote site converter-inverter systems. CEA imposes frequency and harmonic distortion thresholds that fragment certification requirements. Queensland renewable zones drive battery interconnection demand for hybrid converter architectures.
India
CEA regulatory divergence from Australian thresholds complicates cross-border equipment deployment for multinational suppliers. State-owned power enterprises pilot medium-voltage SST interoperability in national smart grid demonstration zones. Gujarat and Maharashtra industrial corridors concentrate early procurement for power distribution modernization.
Asia Pacific Solid State Transformers Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Asia Pacific Solid State Transformers Market. The upper tier commands high-voltage converter prototyping and modular design platform development, while specialists focus on distribution channel control and field commissioning services. Three archetypes dominate: integrated circuit heritage players leveraging semiconductor fabrication access, modular platform architects reducing utility deployment complexity, and distribution channel controllers penetrating Southeast Asian smart grid rollouts. Competitive intensity concentrates on strategic partnerships with state-owned utilities and technology licensing for silicon carbide fabrication capabilities.
Within the integrated circuit heritage tier, Hitachi ABB and Mitsubishi Electric occupy positions shaped by Japanese semiconductor fabrication ecosystems. Siemens AG anchors the modular platform archetype through standardized subsystem offerings. Schneider Electric exemplifies distribution channel control across Thailand, Vietnam, and Indonesia smart grid procurement. These three companies represent the competitive vectors—fabrication access, deployment simplification, and geographic penetration—that define strategic positioning in regional SST markets.
| Leading Market Players |
|---|
| Hitachi ABB |
| Schneider Electric |
| General Electric |
| Mitsubishi Electric |
| Siemens AG |
| Delta Electronics |
| Alstom |
| Eaton Corporation |
| Synergy Transformers |
| Others |
Value Chain & Pricing Dynamics
Japan's JIS certification regime for grid-interactive power converters gates both supplier qualification and price tiering simultaneously, forcing equipment vendors to absorb compliance costs upfront while utilities segment procurement across premium-certified and standard-grade converter architectures.
Pricing Analysis
Price spreads between Japanese and Chinese procurement specifications exceed those within either domestic market, with Tokyo metropolitan utilities paying certification premiums for earthquake-resilient converter designs while Yangtze River Delta demonstration zones optimize for volume scale. Three-tier pricing structure across premium-certified, standard-grade, and economy-tier converter modules reflects divergent GB and JIS compliance burdens. Cost compression in standard-grade silicon carbide converters is intensifying because South Korean foundry expansion relaxes wafer supply constraints. State-owned power enterprises in China exhibit lowest price sensitivity; Australia's remote mining operators show highest.
Supply Chain Analysis
Strategic stockpiling of gallium nitride wafers dominates procurement behavior among Japanese converter manufacturers, while Chinese state-owned enterprises favor just-in-time silicon carbide sourcing from domestic foundries. Semiconductor fabrication concentrates in Japan, South Korea, and Taiwan; magnetic core materials draw from China and Vietnam. Supply chain risk centers on single-source vulnerability for 1.2 kV to 13.8 kV-rated silicon carbide substrates. Distribution runs through utility procurement consortia in metropolitan networks and EPC contractor channels for remote industrial sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among China's state-owned power enterprises as procurement consolidation across provincial grid operators compresses vendor margins and forces qualification standardization.
For Market Incumbents: Compound fabrication access advantages by deepening captive silicon carbide foundry relationships in Japan and South Korea before Chinese MIIT domestic-content requirements harden. Defend against modular platform competitors by embedding proprietary converter control algorithms into utility commissioning protocols. Prioritize certification pre-approval with Australia's CEA to preempt harmonization with Indian CEA standards.
For New Entrants and Emerging Players: Lead with hybrid framework designs targeting Australia's Western Australian mining corridors, where islanding capability commands price premiums and incumbent footprint remains shallow. Southeast Asian smart grid rollouts in Thailand and Vietnam offer the most penetrable geography for modular converter-inverter systems lacking legacy grid integration baggage. Go-to-market through EPC contractor partnerships rather than direct utility sales.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed semiconductor fabrication specialists holding stranded silicon carbide capacity outside utility certification pathways. Long-term viability hinges on regulatory harmonization across the analysis window; five-to-ten year returns depend on which national regulator unifies medium-voltage SST interoperability standards first. Target acquisition archetype: integrated circuit heritage players with dormant JIS certification assets. Watch for METI accelerating GB-JIS mutual recognition talks as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Backward Integration | Captive wafer supply secures converter prototyping capacity against MIIT domestic-content mandates. |
| Hybrid Framework Certification | Dual-mode converter-inverter systems unlock Australia's mining corridor islanding premiums. |
| JIS-GB Standards Harmonization Lobbying | Preemptive regulatory alignment reduces cross-border equipment recertification costs. |
| Modular Platform Channel Partnerships | Distribution control across Thailand and Vietnam smart grid rollouts accelerates deployment velocity. |
| Gallium Nitride Subsea Interconnection Development | Offshore wind developers in Japan and South Korea adopt higher-frequency switching for marine projects. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, power electronics procurement leads at state-owned enterprises, EPC contractor project managers, and semiconductor fabrication specialists; alongside secondary validation through MIIT GB standards documentation, METI smart grid roadmap publications, CEA regulatory filings, and customs trade data for silicon carbide substrate imports. Bottom-up installation forecasts triangulated against top-down grid modernization budget allocations.
Across the projection horizon, the analytical framework modeled segmentation across converter-inverter-rectifier product types, utility-renewable-industrial end users, and grid-connected-hybrid technology frameworks, with regional regulatory cluster as an additional dimension. CAGRs derived from utility procurement pipeline analysis and semiconductor foundry capacity expansion announcements. Forecast inputs included offshore wind interconnection project timelines and earthquake-resilient infrastructure replacement schedules.
Forecasts assume regulatory continuity in Japan's METI JIS enforcement and China's MIIT GB standards development; material policy shifts toward divergent interoperability requirements would require re-modeling. Revision becomes warranted when cross-border equipment certification reciprocity agreements cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
PV Micro Inverters Market
Power Systems
Three Phase Micro Inverters Market
Power Systems
Medium Voltage Drives Market
Power Systems
Traction Inverter Market
Power Systems
Power Electronics Equipment Cooling System Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Space DC-DC Converters Market
Power Systems
Battery Charge Controller Market
Power Systems
Global Chip Power Inductor Market
Power Systems
Switch Mode Power Supply (SMPS) Market
Power Systems
South America DC Distribution Network Market
Power Systems
Shunt Capacitor Market
Power Systems
Digital Inverter Market
Power Systems
Power Supply and Charger Market
Power Systems
Global Frequency Converter Market
Power Systems
DC Stabilized Power Supply Market