
 Global Plasma Generators Market | 2026-2036
Global Plasma Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plasma Generators Market Outlook
South Korea is tilting toward expanded domestic plasma generator capacity as display and semiconductor fabs deepen local sourcing requirements. MKS Instruments leverages its Boston-based R&D footprint to sustain technology leadership in RF power delivery architectures. Advanced Energy Industries anchors North American supply through vertically integrated manufacturing of precision power conversion systems. Comet AG competes from its Swiss base with specialized ceramic components that differentiate performance in high-frequency applications.
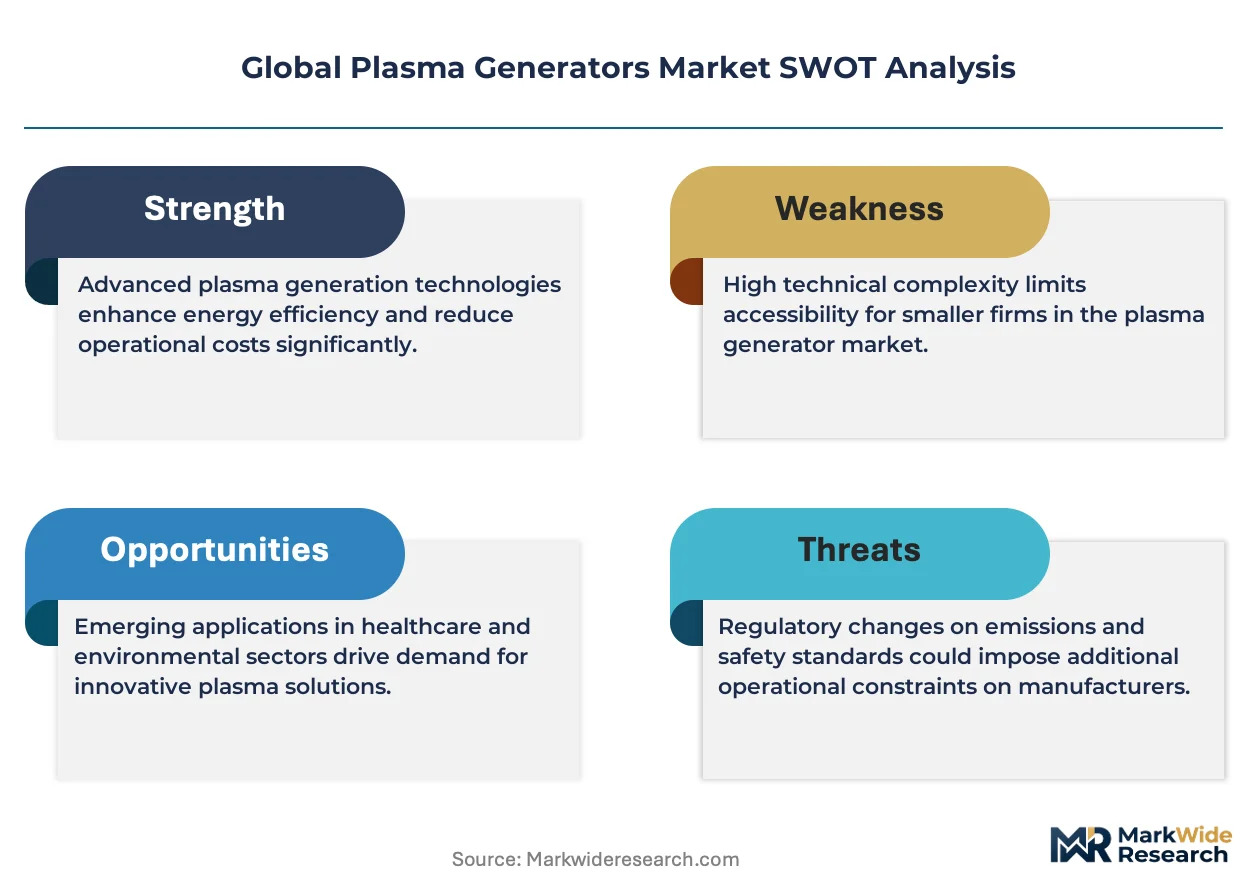
Plasma generators are electrical systems that ionize gas to produce controlled plasma for industrial processing, typically operating at power levels from kilowatts to megawatts and frequencies spanning DC through microwave bands. They serve primarily to modify material surfaces, deposit thin films, or etch substrates with precision unattainable through chemical or mechanical methods. RF plasma generators command the largest installed base across semiconductor fabrication, while microwave plasma generators represent the fastest-expanding category as photovoltaic and diamond synthesis applications multiply. Surface treatment applications generate the deepest margin pools due to stringent performance requirements in aerospace component preparation.
FDA oversight of plasma sterilization equipment in medical end-use segments shapes product validation timelines and clinical trial burdens for manufacturers targeting healthcare applications. EPA regulations on volatile organic compound emissions from traditional solvent cleaning are accelerating displacement toward plasma-based alternatives in automotive and electronics manufacturing. The EU Green Deal's industrial decarbonization mandates are tightening energy efficiency standards for plasma processing equipment sold across European member states. Stakeholders must monitor how evolving semiconductor export controls in Washington, Beijing, and Brussels reshape equipment qualification pathways and customer access across major manufacturing geographies.
Market Dynamics
RF plasma generator architecture is virtualizing across semiconductor fabs as legacy analog power delivery systems compress into software-defined platforms, forcing incumbent hardware suppliers to defend installed bases against modular competitors.
Growth Catalysts
- EPA volatile organic compound restrictions:Solvent-based cleaning faces displacement across automotive and electronics manufacturing, accelerating plasma surface treatment adoption in US industrial corridors.
- East Asian semiconductor capacity expansion:Fabrication facilities in South Korea and Taiwan are scaling RF plasma generator orders to support advanced node production.
- Diamond synthesis:Microwave plasma generators enable chemical vapor deposition for synthetic gem and industrial diamond production, opening specialized equipment demand.
Market Restraints
- High-purity ceramic component supply:Specialized alumina and aluminum nitride substrates concentrate among Swiss and Japanese suppliers, creating input bottlenecks.
- Technical limitation in power modulation:RF generators above 13.56 MHz struggle with impedance matching stability in large-area processing chambers.
- Capital intensity barrier:Precision power conversion systems require multi-million-dollar cleanroom manufacturing infrastructure, limiting new entrant scale.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and display fabrication create virgin territory for plasma equipment vendors.
- EU Green Deal industrial decarbonization:Energy efficiency mandates for processing equipment favor next-generation plasma systems with regenerative power architectures.
- Medical sterilization convergence:Low-temperature hydrogen peroxide plasma sterilizers are penetrating hospital central supply departments as FDA-validated alternatives to ethylene oxide.
Industry Challenges
- RF engineering talent scarcity:Specialized expertise in high-frequency power electronics and plasma physics concentrates among aging workforce cohorts in Germany and Japan.
- Multi-regulatory certification burden:Equipment qualifying for semiconductor fabs must simultaneously satisfy SEMI standards, CE marking, and country-specific electrical safety codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plasma Generators Market |
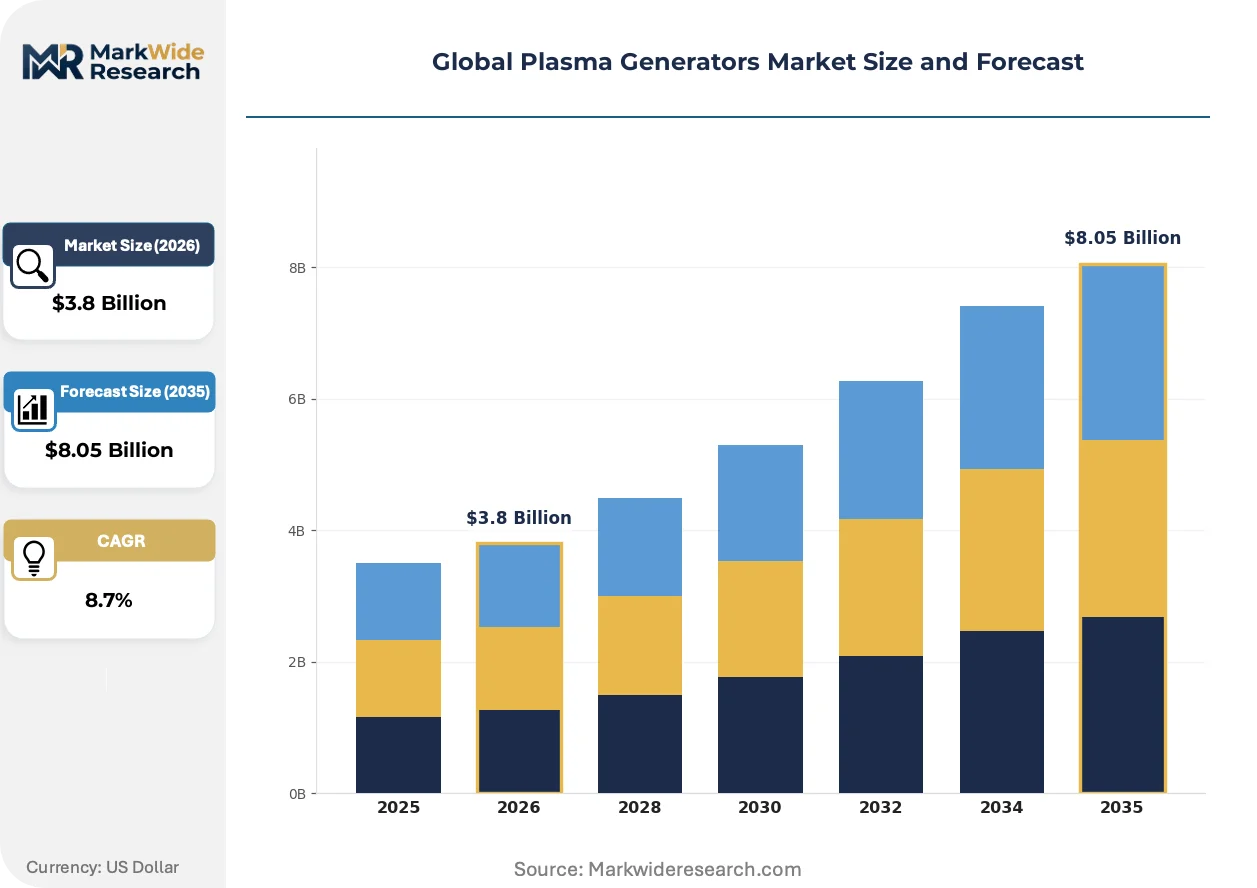
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DC Plasma Generators, RF Plasma Generators, Microwave Plasma Generators, Laser Plasma Generators End User: Aerospace, Electronics, Automotive, Medical Application: Surface Treatment, Material Processing, Plasma Coating, Cleaning Operation Mode: Continuous Wave, Pulsed Wave, Hybrid, Fixed Frequency |
| Companies Covered | Advanced Energy Industries, MKS Instruments, Seren IPS, ADTEC Plasma Technology, DAIHEN Corporation, Comet AG, Kyosan Electric Manufacturing, New Power Plasma, Thierry Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plasma Generators Market Strategic Shifts
Plasma generator technology is fragmenting across three vectors: digital control architectures replacing analog systems, regulatory emissions mandates rewriting process chemistry, and buyer consolidation reshaping vendor-customer power dynamics.
Solid-state RF power amplifiers are virtualizing generator control planes by replacing vacuum tube oscillators with gallium nitride transistor arrays. Semiconductor fabs in South Korea's Pyeongtaek cluster are adopting these platforms for real-time impedance tuning. This compression of hardware into firmware is virtualizing service revenue models toward software subscriptions.
REACH restrictions on perfluorinated compounds are forcing etch process chemistry redesign across European semiconductor fabs. The F-Gas Regulation's phasedown of sulfur hexafluoride is accelerating alternative plasma feedstock validation. German equipment suppliers are responding with modular gas handling architectures that accommodate fluorine-free chemistries.
Display panel manufacturers are consolidating procurement authority from individual fabs to corporate headquarters, compressing vendor negotiation cycles. Samsung Display and LG Display now centralize plasma generator specification decisions in Seoul, displacing site-level engineering autonomy. This concentration is visible across South Korea's Gyeonggi-do manufacturing belt.
Global Plasma Generators Market Segmentation
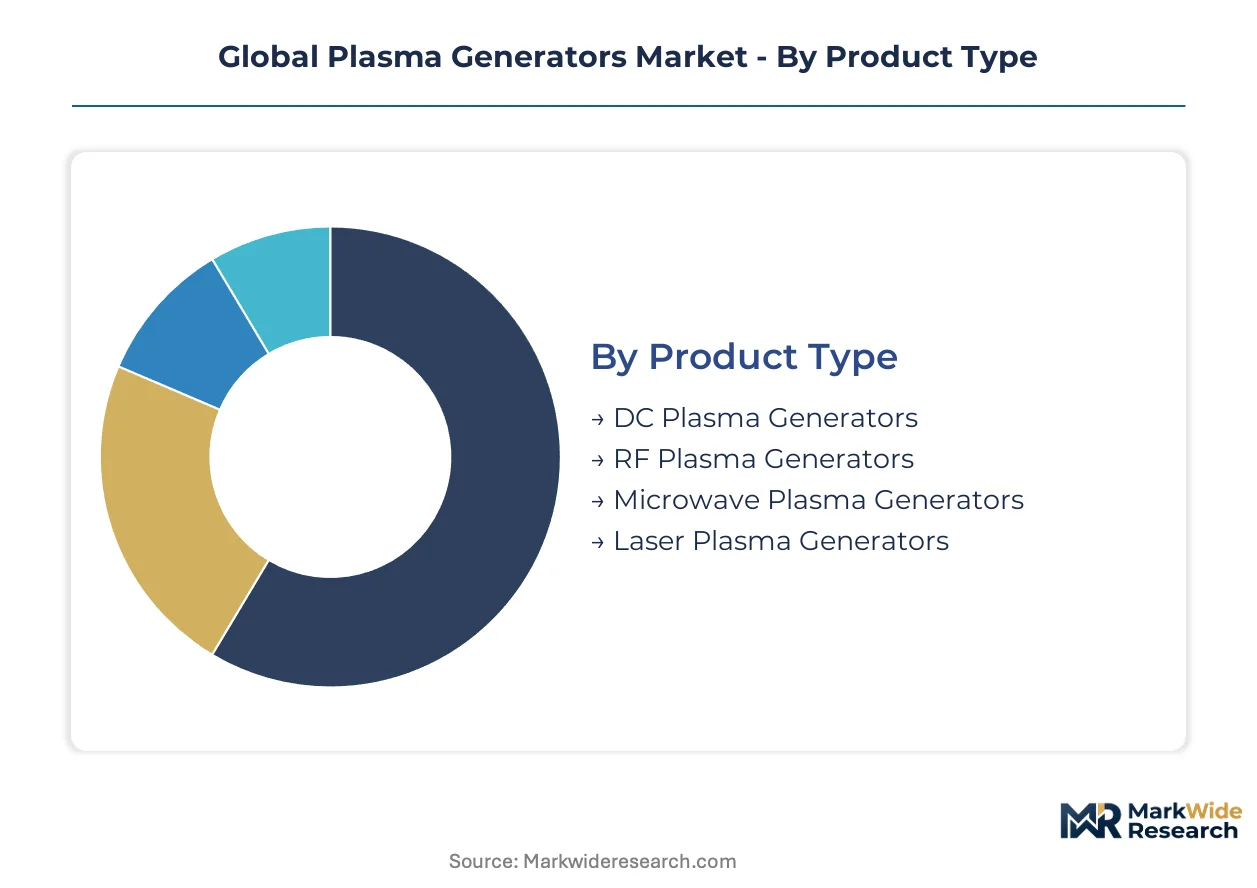
Plasma generator architectures diverge sharply across power delivery methods, end-use cleanliness requirements, and operational duty cycles. Each segmentation axis carries distinct service attach rates, spare parts lifecycles, and technical support intensity that reshape vendor profitability.
Product Type:
RF and microwave platforms demand intensive field calibration and impedance matching expertise, driving after-sales service contracts to 15-20% of original equipment value annually.
- RF Plasma Generators:These systems operate at 13.56 MHz and harmonic frequencies, delivering precise power control through matching networks for semiconductor etch and deposition chambers. South Korean memory fabs in Pyeongtaek and Icheon concentrate procurement as advanced node production scales, with EPA volatile organic compound restrictions accelerating displacement of solvent-based alternatives.
- Microwave Plasma Generators:Operating at 2.45 GHz or 915 MHz, these units generate high-density plasma through electron cyclotron resonance for diamond synthesis and photovoltaic manufacturing. Synthetic gem producers in India and industrial diamond fabricators are expanding orders as chemical vapor deposition matures.
- DC Plasma Generators:Direct current arc systems power thermal spray coating and waste treatment applications with simpler electronics architectures.
- Laser Plasma Generators:Femtosecond and nanosecond pulse systems create transient plasma for materials analysis and medical device surface modification.
RF Plasma Generators hold the largest share; momentum sits with Microwave Plasma Generators.
End User:
Electronics and aerospace buyers impose divergent certification burdens, with FDA validation timelines stretching medical equipment development cycles.
- Electronics:Semiconductor and display panel manufacturers dominate volume, with Samsung Display and LG Display centralizing procurement authority in Seoul for South Korea's Gyeonggi-do manufacturing belt. Tightening EPA emissions standards for solvent cleaning are pushing printed circuit board fabricators toward plasma surface treatment.
- Aerospace:Component preparation for turbine blades and airframe structures generates premium margins due to stringent surface integrity requirements. Boeing and Airbus tier-one suppliers in Germany and France specify plasma cleaning for adhesive bonding preparation.
- Automotive:EV battery cell manufacturing and power electronics packaging are emerging applications as lightweighting demands intensify.
- Medical:Low-temperature hydrogen peroxide plasma sterilizers penetrate hospital central supply departments as FDA-validated alternatives to ethylene oxide, with clinical trial burdens shaping product validation timelines.
Electronics commands the deepest revenue concentration; aerospace generates the steepest margin expansion.
Application:
Surface treatment and cleaning applications concentrate in high-volume manufacturing corridors where regulatory emissions mandates rewrite process chemistry.
- Surface Treatment:Plasma activation modifies polymer and metal surfaces for adhesion, printing, and coating without chemical primers. Automotive manufacturers in Michigan and electronics assemblers in Mexico are displacing solvent-based preparation under EPA volatile organic compound restrictions.
- Cleaning:Plasma removes organic contamination from precision components in vacuum and atmospheric pressure configurations. EU F-Gas Regulation phasedown of sulfur hexafluoride is accelerating alternative feedstock validation for semiconductor fabs.
- Material Processing:Thermal plasma torches enable melting, spheroidization, and waste destruction at megawatt power levels.
- Plasma Coating:Physical and chemical vapor deposition systems deposit wear-resistant and functional thin films.
Surface Treatment anchors current deployment; Cleaning is climbing the fastest on regulatory tailwinds.
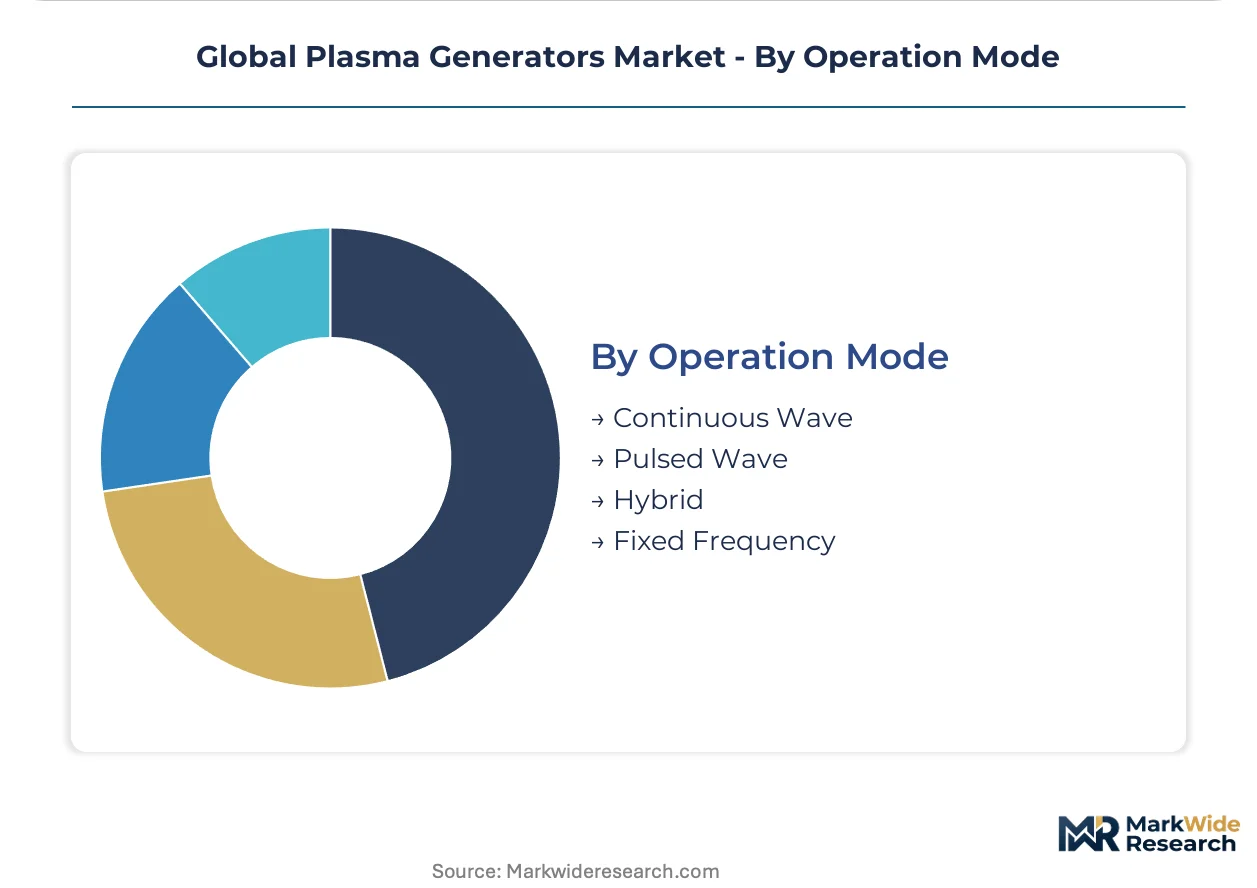
Operation Mode:
Continuous and pulsed architectures split across duty cycle requirements, with pulsed systems demanding more sophisticated power electronics and control firmware.
- Continuous Wave:Steady-state operation dominates semiconductor fabrication and industrial coating where process stability outweighs power efficiency. Taiwan's foundry cluster in Hsinchu and Tainan Science Park standardizes on continuous RF delivery for 24/7 production.
- Pulsed Wave:Modulated power delivery reduces substrate heating and enables time-resolved process control for temperature-sensitive materials. Japanese equipment suppliers in Osaka and Kyoto are advancing burst-mode architectures for advanced packaging applications.
- Hybrid:Switchable continuous-pulsed configurations accommodate multiproduct fabrication lines.
- Fixed Frequency:Crystal-controlled oscillators serve cost-sensitive applications with standardized process recipes.
Continuous Wave retains the broadest installed base; Pulsed Wave is gaining share fastest on precision processing demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions standards and semiconductor export controls from Washington reshape equipment qualification pathways across major manufacturing geographies. Washington's tightening restrictions on advanced chipmaking equipment redirect procurement patterns. Beijing's domestic substitution mandates accelerate local plasma generator development.
United States
Automotive manufacturers in Michigan displace solvent-based surface preparation under EPA volatile organic compound restrictions. The Inflation Reduction Act channels investment toward domestic semiconductor fabrication. Intel's expanding presence in Arizona and Ohio drives RF plasma generator demand for advanced node production.
South Korea
Samsung Display and LG Display centralize procurement authority in Seoul for the Gyeonggi-do manufacturing belt. MFDS oversight of medical sterilization equipment shapes product validation timelines for healthcare applications. Memory fabs in Pyeongtaek and Icheon scale RF plasma generator orders as advanced node production expands.
Germany
Boeing and Airbus tier-one suppliers specify plasma cleaning for turbine blade adhesive bonding preparation. The EU F-Gas Regulation's phasedown of sulfur hexafluoride accelerates alternative plasma feedstock validation. Equipment suppliers in Bavaria and Baden-Württemberg advance modular gas handling architectures for fluorine-free chemistries.
Japan
Osaka and Kyoto-based equipment suppliers advance burst-mode pulsed wave architectures for advanced packaging applications. METI industrial decarbonization mandates tighten energy efficiency standards for processing equipment. Japanese suppliers concentrate specialized expertise in high-frequency power electronics among aging workforce cohorts.
India
PLI scheme incentives for semiconductor and display fabrication create virgin territory for plasma equipment vendors. The country's national electronics regulator shapes equipment certification requirements. Synthetic gem producers expand orders for microwave plasma generators as chemical vapor deposition capacity matures.
Global Plasma Generators Market Competitive Environment
Capability concentration sits with specialized RF power electronics architects; scale advantage sits with diversified industrial electronics conglomerates. The vendor base organizes across three tiers: precision power conversion specialists, diversified industrial electronics manufacturers, and regional system integrators. Dominant competitive moves include geographic expansion into India's PLI-subsidized manufacturing corridors and portfolio diversification toward medical sterilization applications.
Among US-based precision power specialists, Advanced Energy Industries and MKS Instruments exemplify the capability-driven tier with Boston-area R&D footprints. Swiss-based Comet AG occupies a position within the specialized ceramic components segment. Japanese industrial electronics manufacturers including DAIHEN Corporation and Kyosan Electric Manufacturing represent the scale-advantaged conglomerate archetype with diversified power electronics portfolios.
| Leading Market Players |
|---|
| Advanced Energy Industries |
| MKS Instruments |
| Seren IPS |
| ADTEC Plasma Technology |
| DAIHEN Corporation |
| Comet AG |
| Kyosan Electric Manufacturing |
| New Power Plasma |
| Thierry Corporation |
| Others |
Value Chain & Pricing Dynamics
Pyeongtaek's memory fab cluster concentrates RF plasma generator procurement authority, compressing vendor margins through consolidated volume negotiations while Swiss ceramic substrate suppliers retain pricing power on high-frequency components. EPA volatile organic compound restrictions are accelerating plasma surface treatment adoption, yet specialized alumina and aluminum nitride substrate bottlenecks limit downstream price competition.
Pricing Analysis
East Asian price spreads exceed North American benchmarks by substantial margins, reflecting consolidated buyer power in South Korea's Gyeonggi-do corridor against fragmented automotive demand in Michigan. Three-tier pricing structure across premium, standard, and economy levels segments by SEMI certification grade and after-sales service bundling. Cost compression in standard-tier RF generators is intensifying because solid-state gallium nitride architectures displace legacy vacuum tube systems. Display panel manufacturers exhibit highest price sensitivity due to centralized Seoul procurement, while aerospace turbine blade suppliers accept premium positioning for FAA-validated surface preparation systems.
Supply Chain Analysis
Contract manufacturing concentrates with DAIHEN Corporation and Kyosan Electric Manufacturing in Osaka and Kyoto, alongside MKS Instruments' vertically integrated Boston-area facilities. Geographic supply concentration centers on Japan, Switzerland, and the United States for precision power conversion systems. Raw material dependencies rest on high-purity alumina substrates, aluminum nitride ceramics, and gallium nitride wafers. Single-source vulnerability from Swiss and Japanese ceramic component suppliers creates input bottlenecks for RF matching networks. Distribution runs through direct OEM relationships for semiconductor fabs and regional system integrators for industrial surface treatment applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma generator vendors are pivoting toward software-defined service architectures, with firmware subscriptions and real-time impedance tuning contracts expanding faster than hardware shipments. This recurring-revenue layer commands 15-20% of original equipment value annually in RF and microwave platforms.
For Market Incumbents: Harden defensive positions by deepening backward integration into high-purity ceramic substrate production, neutralizing Swiss and Japanese supply bottlenecks. Accelerate SEMI S2/S8 certification investments to lock out modular competitors attacking legacy analog installed bases. Prioritize field engineering talent retention in Germany and Japan where RF physics expertise concentrates among aging workforce cohorts. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized semiconductor and display fabrication corridors before incumbent channel relationships solidify. Target medical sterilization applications where FDA validation timelines create barrier-to-entry protection against price competition. Pursue hydrogen peroxide plasma sterilizer partnerships with hospital central supply departments as ethylene oxide displacement accelerates. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision power conversion specialists with software-defined control plane capabilities over legacy hardware manufacturers. Long-term viability rests on regenerative power architecture development for EU Green Deal compliance. Acquisition target archetype: mid-cap RF power electronics firms with captive gallium nitride transistor sourcing. Watch solid-state RF amplifier adoption rates in South Korean memory fabs as inflection indicator for analog-to-digital transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Control Platform Development | MKS Instruments' Boston R&D footprint enables real-time impedance tuning subscriptions displacing legacy hardware service models. |
| High-Purity Ceramic Component Backward Integration | Captive alumina and aluminum nitride substrate production neutralizes Swiss and Japanese supply bottlenecks for RF matching networks. |
| India PLI Corridor Market Entry | First-mover positioning in semiconductor and display fabrication incentives before Samsung Display and LG Display consolidate procurement. |
| Medical Sterilization FDA Validation Investment | Low-temperature hydrogen peroxide plasma sterilizer approvals create protected revenue streams in hospital central supply departments. |
| Regenerative Power Architecture Development | EU Green Deal energy efficiency mandates favor next-generation plasma systems with energy recovery capabilities in Bavarian and Baden-Württemberg supplier bases. |
Study Parameters
Initial hypotheses were tested against primary input from RF power electronics engineers, semiconductor fab procurement directors, aerospace surface treatment specialists, and medical device regulatory affairs managers and refined through secondary validation. Primary fieldwork combined structured interviews with MKS Instruments and Advanced Energy Industries product managers, DAIHEN Corporation technical sales leads, and Samsung Display central procurement officers. Secondary sources encompassed SEMI standards documentation, EPA volatile organic compound regulatory filings, EU F-Gas Regulation impact assessments, and SEC 10-K equipment supplier disclosures. Bottom-up unit shipment estimates from individual fab expansion projects were triangulated against top-down market sizing from power electronics revenue aggregation.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling RF plasma generator deployment against semiconductor wafer start capacity additions in Pyeongtaek, Hsinchu, and Arizona. Segmentation dimensions included product type, end-use industry, application method, and operational duty cycle alongside geographic regulatory cluster differentiation. CAGRs were derived from regression analysis of historical equipment procurement patterns against fab capital expenditure cycles. Industry-specific forecast inputs incorporated REACH perfluorinated compound restriction timelines and METI industrial decarbonization mandate implementation schedules.
Stress conditions across semiconductor export control escalation, gallium nitride wafer supply disruption, and EPA emissions standard acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding solid-state RF amplifier substitution velocity and display panel procurement centralization trajectories. Quarterly review of South Korean memory fab equipment qualification pathways and EU alternative feedstock validation progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Surface Mounted Medium Voltage Distribution Panel Market
Power Systems
Digital Inverter Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Vehicle Inverter Market
Power Systems
Power Amplifier Modules Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Power Electronics Market
Power Systems
Wireless Battery Monitoring System Market
Power Systems
DC Stabilized Power Supply Market
Power Systems
Smart Power Strips Market
Power Systems
Global Gan Power Device Market
Power Systems
DC-DC Converter Market
Power Systems
Voltage Regulators Market
Power Systems
Southeast Asia Uninterruptible Power Supply (UPS) Market
Power Systems
Global Excitation Systems Market
Power Systems
Thermal Management Systems Market