
 D-Dimer Testing Market | 2026-2036
D-Dimer Testing Market Size, Share, and Industry Trends Forecast 2026-2036
D-Dimer Testing Market Intelligence
Hospital emergency departments is realigning demand toward rapid-result D-dimer protocols that rule out venous thromboembolism within sixty minutes. Siemens Healthineers AG leverages its installed base of coagulation analyzers to sustain high-throughput laboratory contracts across integrated delivery networks. Abbott competes through handheld point-of-care platforms that occupy ambulatory settings where laboratory infrastructure remains limited. Werfen differentiates via specialized hemostasis systems that dominate reference laboratory workflows in Europe and Latin America.
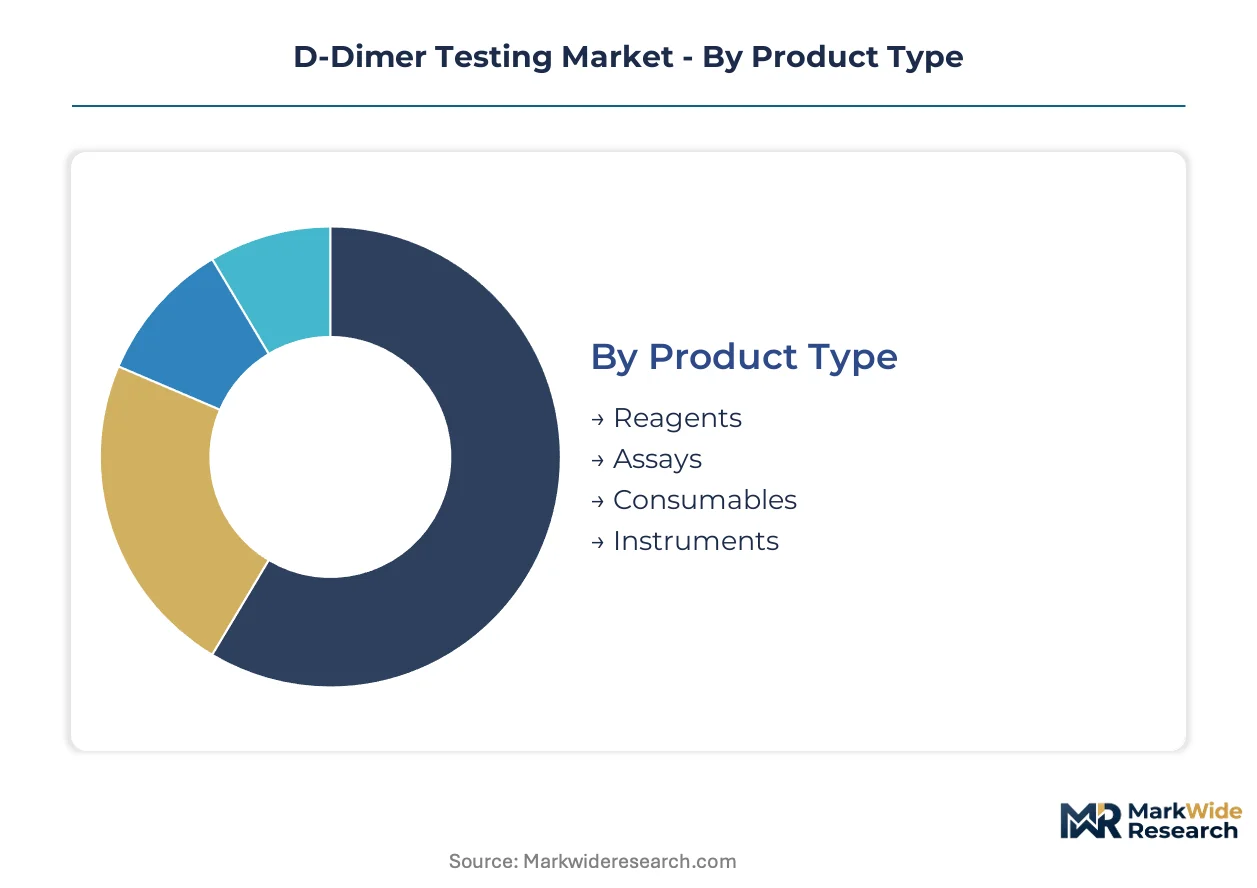
D-dimer testing measures fibrin degradation products in human blood plasma through monoclonal antibody detection methods, with clinical thresholds typically set below 500 ng/mL for excluding thrombotic events in low-to-moderate risk patients. Reagents and assays command the largest revenue share within product type categories due to recurring consumable demand tied to analyzer installed bases. Immunoassay technology leads the technology dimension while rapid test kits represent the fastest-expanding segment, driven by emergency department decentralization and clinic-based anticoagulation monitoring programs.
The FDA oversees premarket notification pathways for D-dimer assays under 510(k) clearance requirements, while the EU In Vitro Diagnostic Regulation mandates notified body conformity assessments that extend approval timelines for new entrants. ISO 15189 accreditation frameworks shape laboratory quality management systems that determine vendor eligibility in competitive tenders. Stakeholders must monitor evolving payer coverage decisions for point-of-care coagulation testing as these determine whether rapid D-dimer platforms achieve sustainable reimbursement outside centralized laboratory settings.
Market Dynamics
Emergency medicine protocols are compressing diagnostic turnaround windows, forcing laboratory infrastructure to migrate toward point-of-care architectures that bypass centralized workflows entirely.
Growth Catalysts
- CLIA-waived assay expansion:The FDA's Clinical Laboratory Improvement Amendments framework permits non-laboratory personnel to operate rapid D-dimer platforms, extending test access to urgent care clinics and physician offices.
- Venous thromboembolism protocol standardization:Hospital emergency departments across the United States are adopting sixty-minute rule-out pathways that embed D-dimer testing into triage workflows.
- Immunoassay sensitivity advances:Monoclonal antibody detection methods now achieve quantitative precision previously restricted to laboratory analyzers, enabling handheld device deployment.
Market Restraints
- Reagent supply concentration:European Union manufacturers control critical monoclonal antibody production, creating vulnerability to REACH chemical registration disruptions.
- Reimbursement fragmentation:United States Medicare coverage determinations for point-of-care coagulation testing vary by contractor jurisdiction, limiting predictable revenue streams.
- Laboratory consolidation inertia:Integrated health networks in Germany and France resist decentralizing testing authority from centralized hematology departments.
Strategic Opportunities
- Home anticoagulation monitoring:Direct oral anticoagulant therapy expansion in Japan creates demand for patient-operated D-dimer tracking outside clinical settings.
- EU In Vitro Diagnostic Regulation compliance services:New notified body conformity assessment requirements extend approval timelines, creating advisory service revenue for quality management consultancies.
- AI-assisted result interpretation:Machine learning algorithms that integrate D-dimer values with clinical pretest probability scores are penetrating emergency department information systems.
Industry Challenges
- ISO 15189 accreditation complexity:Point-of-care testing sites struggle to implement laboratory quality management systems without dedicated quality officers.
- Analyzer-reagent lock-in:Closed system architectures prevent third-party reagent competition, raising operational costs for high-volume hospital laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | D-Dimer Testing Market |
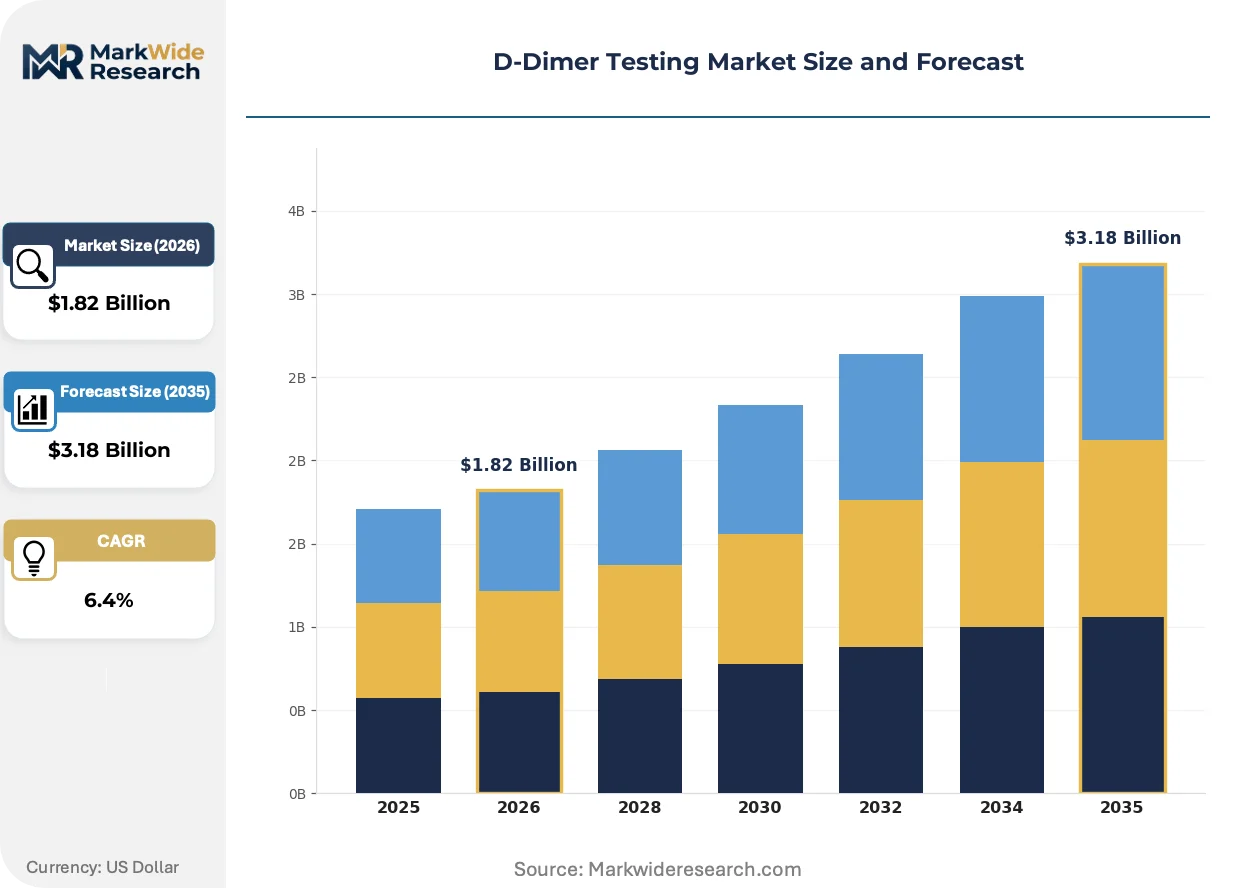
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Assays, Consumables, Instruments Application: Cardiovascular Disorders, Thrombosis, Pulmonary Embolism, Oncology End User: Hospitals, Diagnostic Laboratories, Research Institutions, Clinics Technology: Immunoassay, ELISA, Polymerase Chain Reaction, Rapid Test Kits |
| Companies Covered | F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Abbott, Thermo Fisher Scientific Inc., biomérieux, QuidelOrtho Corporation, Danaher Corporation, Werfen, Sysmex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
D-Dimer Testing Market Strategic Shifts & Innovations
Diagnostic workflows are fragmenting across care settings, with technology vendors racing to match laboratory-grade precision to portable form factors and ambient operating conditions.
Fluorescence immunoassay cartridge systems are decentralizing thrombotic risk assessment from hospital core laboratories to satellite emergency departments and ambulatory surgical centers. Rural hospital networks in the United States are deploying these platforms to avoid specimen transport delays. The technology is decentralizing diagnostic authority toward frontline clinical staff without hematology specialization.
The EU In Vitro Diagnostic Regulation's 2022 implementation is extending conformity assessment timelines for novel D-dimer assays, forcing manufacturers to maintain parallel technical documentation for CE-marked and FDA-cleared versions. European reference laboratories are delaying procurement decisions pending notified body certification clarity. Smaller assay developers are exiting the European market rather than absorbing compliance costs.
Emergency department purchasing committees are consolidating vendor relationships around integrated coagulation testing menus rather than standalone D-dimer contracts. Hospital systems in Texas and California are awarding sole-source agreements to suppliers offering thrombosis-hemostasis assay breadth. This concentration is visible most acutely in United States metropolitan markets where health network mergers have reduced independent laboratory decision-making.
D-Dimer Testing Market Segmentation
Product architecture and testing workflows diverge sharply across care settings, with procurement committees weighting throughput, portability, and reagent economics differently. Technology choices determine whether D-dimer testing remains captive to core laboratories or migrates toward decentralized triage environments.
Product Type:
Buyers differentiate primarily by recurring spend versus capital commitment, with consumable-heavy models dominating high-volume hospital contracts.
- Reagents:Monoclonal antibody formulations and calibrator solutions constitute the recurring revenue backbone for analyzer manufacturers. United States integrated delivery networks negotiate multi-year reagent supply agreements that lock in per-test pricing and service response guarantees.
- Assays:Quantitative and qualitative test kits with FDA 510(k) clearance or CE marking under EU IVDR requirements enable clinical utility claims for venous thromboembolism exclusion. German reference laboratories prioritize assay traceability to international standards when qualifying vendors for competitive tenders.
- Consumables:Reaction cuvettes, sample cups, and control materials support continuous analyzer operation without instrument replacement.
- Instruments:Benchtop and floor-standing coagulation analyzers represent capital-intensive procurement decisions with extended depreciation schedules.
Reagents lead volumes today; rapid test consumables are gaining share fastest.
Application:
Clinical urgency and diagnostic certainty requirements shape whether D-dimer testing integrates into standardized protocols or remains discretionary.
- Cardiovascular Disorders:Atrial fibrillation patients on direct oral anticoagulants require periodic D-dimer monitoring to assess thrombotic risk alongside bleeding profiles. Japanese cardiology clinics are embedding these tests into chronic disease management pathways.
- Thrombosis:Deep vein thrombosis rule-out algorithms in emergency medicine represent the highest-frequency application, with sixty-minute turnaround mandates driving platform selection. United States hospital emergency departments specify CLIA-waived status for point-of-care deployment.
- Pulmonary Embolism:Computed tomography angiography gatekeeping relies on D-dimer thresholds to reduce radiation exposure in low-risk patients.
- Oncology:Cancer-associated thrombosis surveillance uses D-dimer trends alongside imaging to guide prophylactic anticoagulation decisions.
Thrombosis applications anchor current demand; oncology monitoring is climbing the fastest.
End User:
Capital availability and regulatory sophistication determine whether sites qualify for integrated analyzer contracts or rely on referral networks.
- Hospitals:Emergency departments and hematology laboratories command the highest test volumes, with purchasing committees favoring vendors offering thrombosis-hemostasis assay breadth. Texas and California health systems are consolidating around sole-source agreements.
- Diagnostic Laboratories:Commercial reference laboratories in France and Germany maintain centralized testing authority, resisting decentralization pressures from hospital networks.
- Research Institutions:Academic medical centers utilize D-dimer assays for translational studies on fibrinolysis biomarkers and anticoagulant therapy monitoring.
- Clinics:Urgent care and anticoagulation clinics in the United States are adopting CLIA-waived rapid platforms where laboratory infrastructure is absent.
Hospitals dominate current procurement; clinics are expanding most quickly.
Technology:
Detection sensitivity and time-to-result tradeoffs determine platform suitability for emergency versus routine settings.
- Immunoassay:Chemiluminescence and immunoturbidimetric methods deliver quantitative precision required for guideline-concordant VTE exclusion. Siemens Healthineers leverages installed bases of coagulation analyzers to sustain high-throughput laboratory contracts.
- ELISA:Enzyme-linked immunosorbent assays provide batch-processing efficiency for reference laboratories with lower urgency requirements.
- Polymerase Chain Reaction:PCR-based methods remain investigational for D-dimer quantification, with limited clinical validation.
- Rapid Test Kits:Fluorescence immunoassay cartridge systems enable whole-blood testing at point-of-care without specimen processing. Rural United States hospital networks deploy these to bypass transport delays.
Immunoassay platforms anchor laboratory volumes; rapid test kits are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated health networks in the United States drive centralized laboratory consolidation while emergency departments accelerate point-of-care adoption. Hospital procurement committees in Texas and California consolidate vendor relationships around thrombosis-hemostasis assay breadth. Regulatory frameworks across major economies shape approval timelines and reimbursement pathways for D-dimer platforms.
United States
Emergency medicine protocols mandate sixty-minute venous thromboembolism rule-out pathways that compress diagnostic turnaround windows. The FDA's Clinical Laboratory Improvement Amendments framework permits CLIA-waived rapid D-dimer platforms in urgent care clinics and physician offices. Rural hospital networks in the Mountain West deploy fluorescence immunoassay cartridge systems to bypass specimen transport delays entirely.
Germany
Reference laboratories in Baden-Württemberg and Bavaria maintain centralized testing authority, resisting decentralization pressures from hospital networks. The EU In Vitro Diagnostic Regulation mandates notified body conformity assessments that extend approval timelines for new market entrants. Industrial clusters around Munich and Heidelberg anchor hemostasis system manufacturing for European and Latin American distribution.
Japan
Cardiology clinics in the Kanto region embed D-dimer monitoring into chronic disease management pathways for atrial fibrillation patients on direct oral anticoagulants. The Pharmaceuticals and Medical Devices Agency oversees premarket approval pathways for quantitative assay platforms. Tokyo-based academic medical centers utilize D-dimer assays for translational studies on fibrinolysis biomarkers and anticoagulant therapy monitoring.
France
Commercial reference laboratories in Île-de-France preserve centralized hematology testing authority despite hospital network consolidation. ANSM regulatory oversight shapes quality benchmarks for point-of-care deployment in emergency departments. Parisian health systems delay procurement decisions pending notified body certification clarity under EU IVDR implementation timelines.
United Kingdom
NHS England integrated care systems in London and the Southeast consolidate laboratory contracts around high-throughput analyzer platforms. The Medicines and Healthcare products Regulatory Agency aligns with EU IVDR transitional provisions for CE-marked device recognition. Cambridge and Oxford academic clusters drive AI-assisted result interpretation research that integrates D-dimer values with clinical pretest probability scores.
D-Dimer Testing Market Key Industry Players
Strategic partnerships dominate the current landscape as vendors seek to expand thrombosis-hemostasis assay menus without internal R&D absorption. The vendor base organizes around three tiers: diversified diagnostics conglomerates with installed analyzer bases, specialized hemostasis system developers, and point-of-care platform innovators. Two archetypes anchor competitive positioning: high-throughput laboratory contract holders and rapid-test ambulatory specialists. Geographic expansion into Asia-Pacific markets and technology licensing for AI-assisted interpretation represent the dominant competitive moves.
Among Swiss-based pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd exemplifies the diversified diagnostics archetype with broad immunoassay portfolio coverage. Siemens Healthineers AG anchors the German industrial contingent, occupying a position within high-throughput laboratory contract channels across integrated delivery networks. Abbott represents the point-of-care platform specialist tier, with handheld systems positioned in ambulatory settings where laboratory infrastructure remains limited. These three entities collectively illustrate the competitive structure: scale-driven conglomerates, regional industrial champions, and portable technology innovators each defend distinct channel positions.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers AG |
| Abbott |
| Thermo Fisher Scientific Inc. |
| biomérieux |
| QuidelOrtho Corporation |
| Danaher Corporation |
| Werfen |
| Sysmex Corporation |
| Others |
Cost & Logistics Intelligence
Fluorescence immunoassay miniaturization is compressing production economics while concentrating monoclonal antibody supply among European Union manufacturers. This technology shift simultaneously reduces per-test manufacturing costs for cartridge-based platforms and amplifies pricing power for reagent suppliers controlling critical antibody production.
Pricing Analysis
Monoclonal antibody formulation costs pass through directly to reagent pricing, with three-tier pricing structure across premium, standard, and economy levels tied to FDA clearance tier and ISO 15189 accreditation status. Price differentiation centers on CLIA-waiver certification and analyzer-reagent bundling depth. Pricing pressure stems from integrated delivery network volume consolidation in Texas and California. Hospital laboratories exhibit lowest price sensitivity due to sole-source contract lock-in; urgent care clinics face highest sensitivity where rapid test consumables compete on per-test economics.
Supply Chain Analysis
Reverse-logistics flows for analyzer refurbishment and recalibration services anchor aftermarket revenue streams for installed base holders. Monoclonal antibody production concentrates in Germany, Ireland, and the Netherlands under REACH chemical registration frameworks. Critical inputs include recombinant antibody cell lines, fluorescence reporter molecules, and precision-molded cartridge plastics. Single-source vulnerability runs through EU-based notified body certification bottlenecks under IVDR implementation. Distribution runs through integrated health network procurement committees and GPO contracts managers in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between United States reimbursement generosity for CLIA-waived platforms and European regulatory cost absorption for IVDR compliance.
For Market Incumbents: Cement installed base loyalty through multi-year reagent supply agreements with service response guarantees that raise switching costs for integrated delivery networks. Threaten emerging point-of-care specialists by embedding D-dimer into thrombosis-hemostasis assay breadth contracts. Prioritize backward integration into monoclonal antibody production to secure supply against REACH disruption.
For New Entrants and Emerging Players: Enter via AI-assisted result interpretation software that integrates D-dimer values with clinical pretest probability scores, bypassing capital-intensive analyzer manufacturing. Target urgent care clinics in United States Mountain West states where laboratory infrastructure gaps persist. Pursue white-label rapid test kit partnerships with established point-of-care distributors.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized hemostasis system developers facing IVDR compliance cost absorption without diversified revenue streams. Long-term viability favors platforms with sustainable reimbursement pathways outside centralized laboratory settings. Monitor Medicare contractor coverage determinations for point-of-care coagulation testing as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Platform Expansion | Extends test access to urgent care clinics under FDA Clinical Laboratory Improvement Amendments framework. |
| EU IVDR Compliance Service Development | Creates advisory revenue streams as notified body assessments extend approval timelines for assay developers. |
| AI-Assisted Interpretation Integration | Penetrates emergency department information systems through machine learning algorithm partnerships. |
| Multi-Year Reagent Supply Lock-In | Secures per-test pricing guarantees with United States integrated delivery networks. |
| Home Anticoagulation Monitoring Pathway | Captures direct oral anticoagulant therapy expansion in Japanese cardiology clinics. |
Research Approach
Multiple input streams — hospital procurement committee interviews, regulatory affairs consultations, and GPO contracts analysis — were reconciled against secondary validation from FDA 510(k) filings, EU IVDR notified body documentation, and CMS Medicare coverage determinations. Primary discussions with emergency medicine physicians, biomedical engineers, hematology laboratory directors, and point-of-care platform specialists informed operational workflow assessments. Bottom-up test volume modeling and top-down market sizing triangulated across the analysis window.
Cross-referencing historical procurement patterns against expert panel input shaped the analytical framework across product type, application, end user, and technology segmentation dimensions. CAGRs were derived from test volume elasticity modeling and pricing trajectory assumptions. Industry-specific forecast inputs included emergency department protocol standardization timelines and direct oral anticoagulant therapy penetration curves.
Inputs from FDA premarket notification databases and EU notified body certification registries were available through the study window; gaps in real-time Medicare contractor coverage determination updates introduce uncertainty bands around point-of-care platform revenue projections. Forecasts reflect documented assumptions regarding CLIA-waiver expansion velocity and IVDR implementation adherence. Practitioners should monitor Medicare Administrative Contractor local coverage determinations and REACH chemical registration enforcement actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Specific Protein Testing Market
Testing Services
Antibiotic Susceptibility Testing Market
Testing Services
Pyrogen Testing Market
Testing Services
Global Direct-To-Consumer (DTC)Testing Market
Testing Services
Global Virology Testing Market
Testing Services
Global Immunoprecipitation Testing Market
Testing Services
Service Laboratory Market
Testing Services
United States Hospital Acquired Disease Testing Market
Testing Services
STD Testing Devices Market
Testing Services
Hemotransmissive Infections Testing Market
Testing Services
Drug Tester Market
Testing Services
Infusion Toxicology Services Market
Testing Services
Diagnostic Shipper Market
Testing Services
Global Metabolic Testing Market
Testing Services
Fecal Calprotectin Test Market
Testing Services
Germany Testing, Inspection and Certification Market