
 Service Laboratory Market | 2026-2036
Service Laboratory Market Size, Share, and Industry Trends Forecast 2026-2036
Service Laboratory Market Analytics
Buyer concentration among pharmaceutical and medical device manufacturers is restructuring procurement patterns across the service laboratory sector. Large contract manufacturers now bundle testing volumes with fewer preferred laboratory partners. SGS SA leverages its global accreditation network to anchor multi-site outsourcing agreements with multinational health science clients. Bureau Veritas competes through specialized pharmaceutical and biologics testing capabilities in regulated markets. Advantest Corporation differentiates by integrating semiconductor test equipment expertise with calibration and verification services for advanced electronics manufacturers.
A service laboratory provides accredited analytical testing, calibration, measurement traceability, and conformity assessment against defined technical standards or regulatory specifications, typically operating under ISO/IEC 17025 quality systems with documented measurement uncertainty budgets and proficiency testing participation. Its primary purpose is to verify that materials, components, products, or environmental conditions meet safety, performance, or legal requirements before market release or operational deployment. Testing services generate the largest revenue share due to recurring demand for batch release and stability studies in pharmaceutical quality assurance, while calibration services command premium pricing where NIST-traceable or national metrology institute standards are mandatory for regulated industries. Certification services represent the fastest-expanding margin pool as manufacturers seek streamlined market access across multiple jurisdictions.
FDA 21 CFR Part 11 and EU GMP Annex 1 enforcement are elevating data integrity and environmental monitoring requirements, directly increasing validation workloads for contract laboratories serving US and European pharmaceutical markets. ISO/IEC 17025 accreditation serves as the baseline market access credential, with national regulators such as Germany's DAkkS and the UK's UKAS layering additional sector-specific requirements that filter laboratory eligibility for public sector contracts. Stakeholders must monitor evolving mutual recognition agreements between accreditation bodies and anticipate where regulatory divergence between FDA, EMA, and emerging market agencies will create compliance complexity or competitive shelter for locally accredited laboratories.
Market Dynamics
Pharmaceutical manufacturers are consolidating testing volumes with fewer accredited partners, restructuring procurement around multi-site outsourcing agreements that bundle analytical, calibration, and certification services under unified quality frameworks.
Growth Catalysts
- FDA 21 CFR Part 11:Data integrity enforcement is expanding validation workloads for contract laboratories serving US pharmaceutical markets, creating recurring revenue streams for ISO/IEC 17025-accredited facilities.
- Biologics manufacturing:Cell and gene therapy production requires specialized environmental monitoring and sterility testing that exceeds in-house capabilities at most drug developers.
- Rhine-Main cluster:Germany's concentration of chemical and medical device manufacturers generates sustained demand for TÜV-affiliated and independent testing facilities with DAkkS accreditation.
Market Restraints
- Reference material costs:NIST-traceable standards and certified reference materials face price volatility and extended lead times from national metrology institutes.
- Accreditation concentration:DAkkS, UKAS, and France's COFRAC dominate European laboratory recognition, creating bottlenecks for facilities seeking multi-jurisdiction credentials.
- Equipment qualification:Analytical instrumentation requires extensive IQ/OQ/PQ documentation under EU GMP Annex 15, extending facility commissioning timelines.
Strategic Opportunities
- India's CDSCO expansion:Domestic pharmaceutical production under the PLI scheme is generating demand for local bioanalytical and stability testing capacity.
- Digital laboratory platforms:LIMS integration with blockchain-based data integrity verification is opening premium service tiers for audit-ready documentation.
- EU MDR transition:Medical device reclassification is forcing manufacturers to rebuild technical documentation, expanding notified body and testing laboratory outsourcing.
Industry Challenges
- Analytical chemist shortage:Specialized expertise in mass spectrometry and chromatography method development is concentrated among experienced practitioners nearing retirement.
- Multi-standard harmonization:Divergent FDA, EMA, and ICH Q2(R1) validation requirements force laboratories to maintain parallel standard operating procedures for identical tests.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Service Laboratory Market |
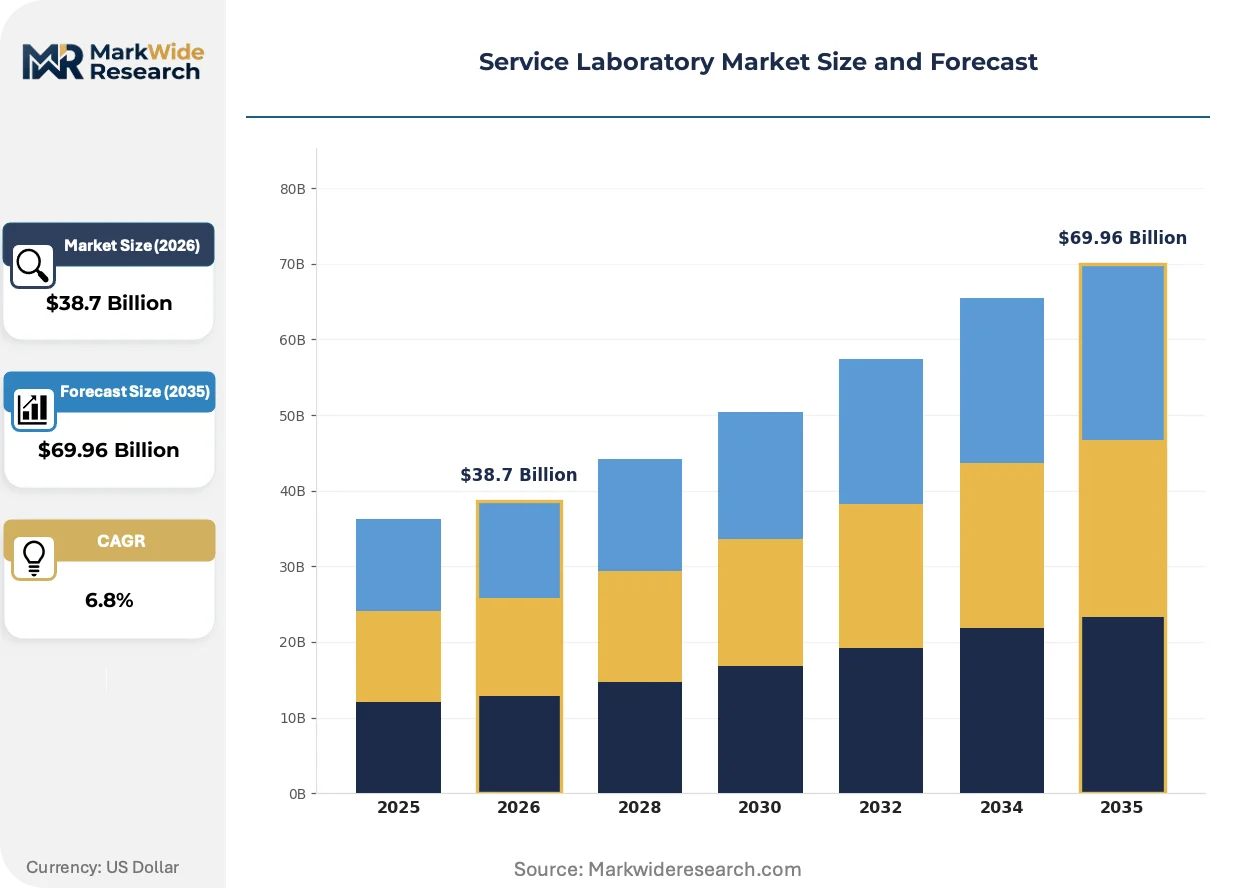
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Testing Services, Calibration Services, Inspection Services, Certification Services Industry Vertical: Pharmaceuticals, Biotechnology, Environmental, Food & Beverage End User: Manufacturers, Research Institutions, Government Agencies, Healthcare Providers Application: Quality Assurance, Compliance Testing, Research Development, Product Verification |
| Companies Covered | Keysight Technologies, Anritsu Corporation, Spirent Communications, Tektronix (Fortive), Advantest Corporation, Bureau Veritas, SGS SA, TÜV Rheinland, Intertek Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Service Laboratory Market Evolving Landscape
Automation and digital traceability are compressing turnaround times while elevating data defensibility requirements, reshaping how laboratories structure workflows and client interfaces.
Robotic sample handling systems coupled with AI-driven analytical method optimization are electrifying high-throughput screening operations. Pharmaceutical quality control departments are deploying these platforms for batch release testing, reducing analyst touchpoints while tightening measurement uncertainty budgets. The technology is compressing the traditional 5-day stability study turnaround into 48-hour windows, forcing smaller laboratories to specialize or exit routine pharmaceutical work.
EU GMP Annex 1 revisions mandating continuous environmental monitoring are restructuring cleanroom validation protocols. Manufacturers must now demonstrate real-time viable and non-viable particle detection, quadrupling sensor calibration and data review burdens. Sterile drug facilities in Ireland, Belgium, and the Netherlands are accelerating outsourcing to accredited microbiology laboratories with automated colony counting and rapid microbial detection capabilities.
Preferred provider agreements are displacing transactional testing relationships across medical device and pharmaceutical supply chains. Large contract manufacturers now consolidate annual testing spend with two to three laboratory partners offering geographic coverage and unified data formats. This concentration is most visible in Germany and Switzerland, where SGS SA and Bureau Veritas have anchored multi-year frameworks covering release testing, stability storage, and regulatory submission support.
Service Laboratory Market Segmentation
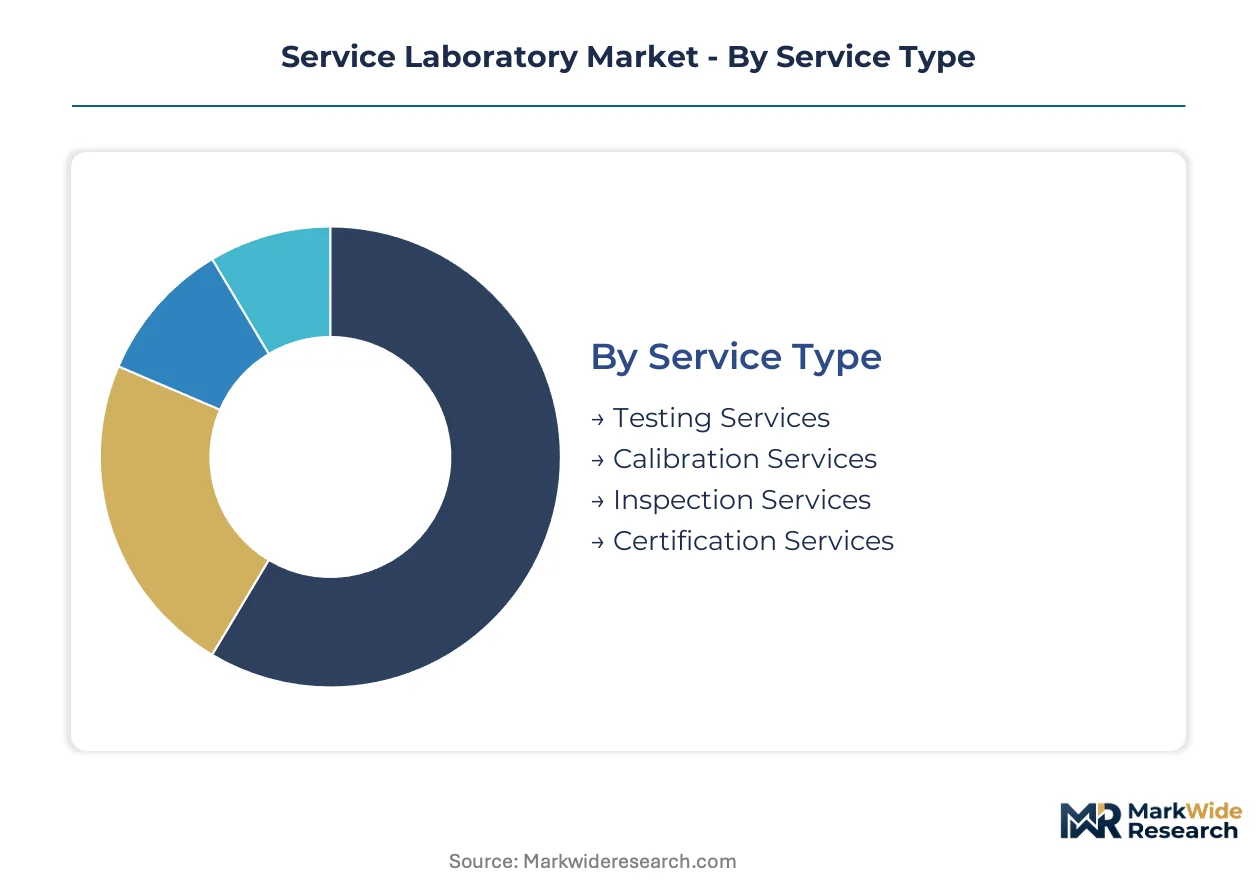
Laboratory service providers structure operations around distinct capability clusters, each demanding specialized accreditation, equipment profiles, and technical staffing. Procurement decisions hinge on matching segment-specific expertise to regulatory requirements, creating clear differentiation between commodity testing and premium analytical services.
Service Type:
Capital intensity varies sharply across service categories, with analytical instrumentation and reference material libraries representing the largest upfront investments.
- Testing Services:Chromatography, mass spectrometry, and microbiological assay platforms require seven-figure capital commitments for pharmaceutical-grade installations. Batch release and stability studies for FDA-regulated drug manufacturers concentrate demand in ISO/IEC 17025-accredited facilities with documented measurement uncertainty budgets.
- Calibration Services:NIST-traceable standards and primary measurement capabilities command premium positioning where national metrology institute linkage is mandatory. Automated sensor networks for EU GMP Annex 1 environmental monitoring are expanding recurring calibration contracts in Belgium and Ireland.
- Inspection Services:Visual and dimensional verification for manufacturing quality gates.
- Certification Services:Third-party conformity assessment for market access across multiple jurisdictions.
Testing services absorb the bulk of installed capacity; certification services are expanding most quickly.
Industry Vertical:
Application complexity and regulatory burden determine margin structures across vertical markets.
- Pharmaceuticals:FDA 21 CFR Part 11 and EMA GMP requirements drive validation-intensive analytical workflows. Sterile drug manufacturers in Germany's Rhine-Main cluster outsource environmental monitoring and sterility testing to DAkkS-accredited laboratories with automated colony counting capabilities.
- Biotechnology:Cell and gene therapy production demands specialized biosafety level containment and molecular characterization expertise that exceeds in-house capabilities at emerging drug developers.
- Environmental:Soil, water, and air quality monitoring for industrial compliance.
- Food & Beverage:Contaminant screening and nutritional labeling verification.
Pharmaceuticals commands the deepest analytical specialization; biotechnology is climbing the fastest as advanced therapy manufacturing scales.
End User:
Procurement scale and technical sophistication create distinct service tier requirements across customer categories.
- Manufacturers:Large contract manufacturers consolidate annual testing spend with preferred laboratory partners offering unified data formats and geographic coverage. Multi-site outsourcing agreements now bundle analytical, calibration, and certification services under single quality frameworks.
- Research Institutions:Academic and government research programs generate project-based demand for specialized method development and non-routine analytical support.
- Government Agencies:Public sector contracts requiring national accreditation body recognition.
- Healthcare Providers:Clinical laboratory referral and point-of-care device validation services.
Manufacturers dominate contract value; research institutions are gaining share fastest as public funding for advanced materials characterization expands.
Application:
Regulatory urgency and commercial timeline pressure differentiate application-specific service requirements.
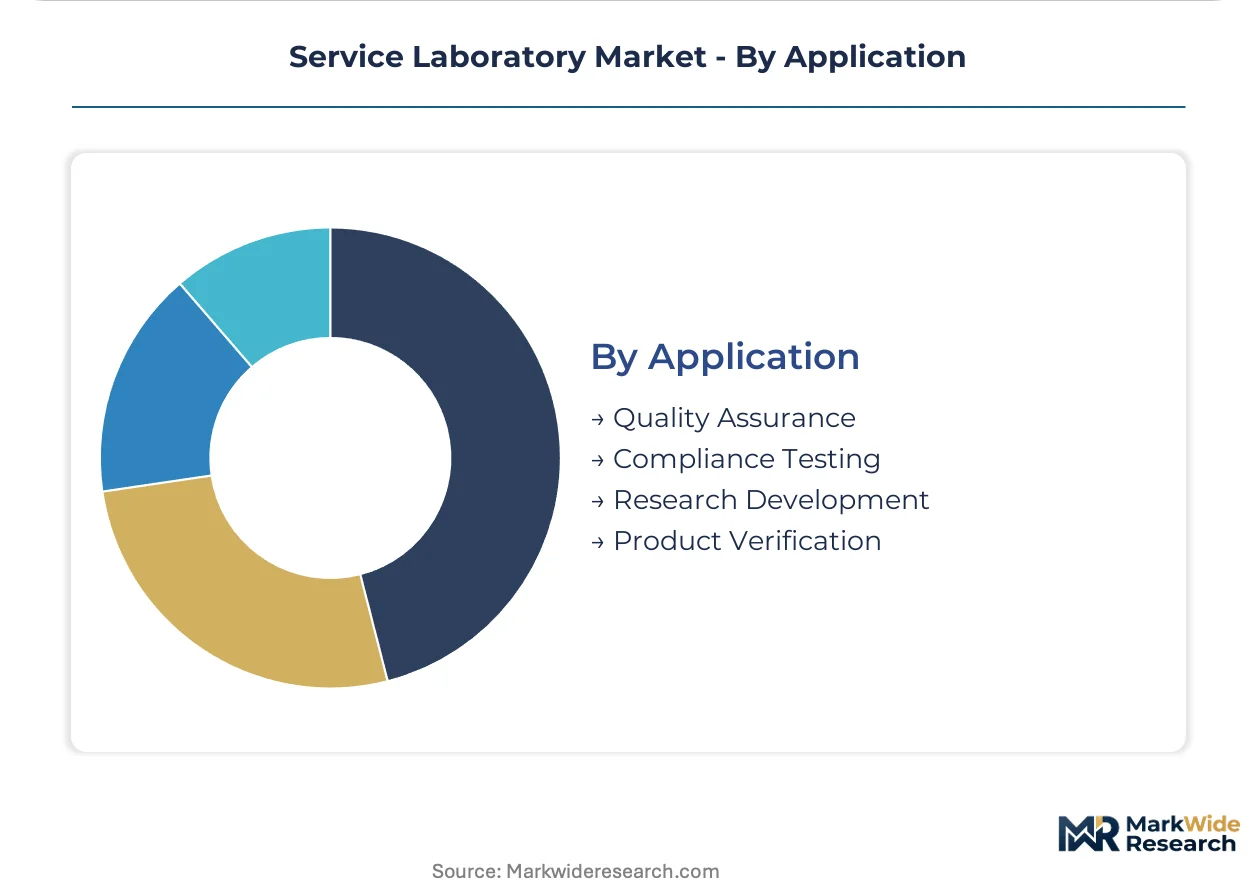
- Quality Assurance:Real-time batch release testing and in-process control monitoring for pharmaceutical production. Robotic sample handling systems coupled with AI-driven method optimization are compressing traditional stability study turnarounds from five days to forty-eight hours.
- Compliance Testing:Mandatory verification against FDA, EMA, and national standards for market authorization. EU MDR transition is forcing medical device manufacturers to rebuild technical documentation, expanding notified body and testing laboratory outsourcing.
- Research Development:Early-phase analytical support for formulation and process development.
- Product Verification:Pre-shipment and incoming inspection for supply chain quality gates.
Quality assurance anchors laboratory revenue; compliance testing is expanding most rapidly as regulatory divergence between FDA and EMA multiplies validation workloads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical and medical device manufacturers concentrate testing procurement in Germany, the United States, Switzerland, India, and Japan, where regulatory stringency and industrial density sustain premium laboratory demand.
Germany
The Rhine-Main cluster hosts DAkkS-accredited facilities serving chemical and sterile drug manufacturers. EU GMP Annex 1 revisions mandate continuous environmental monitoring, quadrupling calibration contracts for TÜV-affiliated laboratories. Frankfurt and Darmstadt anchor multi-site outsourcing frameworks bundling analytical, stability, and certification services.
United States
FDA 21 CFR Part 11 enforcement expands validation workloads for contract laboratories supporting pharmaceutical batch release. Boston-Cambridge biotech density and New Jersey's generic drug manufacturing sustain demand for ISO/IEC 17025-accredited facilities with documented measurement uncertainty. Large contract manufacturers consolidate annual testing spend with preferred partners offering unified data formats.
Switzerland
Swissmedic requirements for biologics and cell therapy production exceed in-house capabilities at emerging drug developers. Basel's pharmaceutical concentration and Zurich's medical device manufacturing generate specialized outsourcing for sterility testing and environmental monitoring. Preferred provider agreements now displace transactional relationships across sterile drug supply chains.
India
CDSCO expansion under the PLI scheme generates demand for local bioanalytical and stability testing capacity. Maharashtra and Gujarat pharmaceutical manufacturing clusters require DAkkS- and UKAS-recognized laboratory partners for export documentation. Domestic contract research organizations are building ISO/IEC 17025-accredited facilities to capture outsourced analytical work.
Japan
PMDA's alignment with ICH Q2(R1) validation requirements sustains demand for specialized chromatography and mass spectrometry expertise. Tokyo-Osaka pharmaceutical manufacturing corridors outsource environmental monitoring and reference standard calibration to JIS-accredited facilities. METI funding for advanced materials characterization expands research institution laboratory contracts.
Service Laboratory Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital laboratory platforms and blockchain-based data integrity verification. The market structures around three tiers: global accreditation networks anchoring multi-site frameworks, specialized pharmaceutical and biologics testing boutiques, and regional calibration services with national metrology institute linkages. Consolidation accelerates through preferred provider agreements displacing transactional relationships, while technology licensing partnerships embed automation into high-throughput screening operations.
Among testing and certification specialists, SGS SA, Bureau Veritas, and Advantest Corporation occupy distinct positioning vectors. SGS SA represents the global network archetype with multi-jurisdiction accreditation coverage. Bureau Veritas exemplifies specialized pharmaceutical and biologics testing capabilities in regulated markets. Advantest Corporation anchors semiconductor test equipment integration with calibration services for advanced electronics manufacturers.
| Leading Market Players |
|---|
| Keysight Technologies |
| Anritsu Corporation |
| Spirent Communications |
| Tektronix (Fortive) |
| Advantest Corporation |
| Bureau Veritas |
| SGS SA |
| TÜV Rheinland |
| Intertek Group |
| Others |
Value Network & Pricing Analysis
Accreditation-grade divergence between DAkkS-recognized premium laboratories and commodity testing facilities manifests in both pricing power and supply chain configurations. Pharmaceutical manufacturers pay 40-60% premiums for multi-jurisdiction accredited partners while consolidating procurement with fewer vendors.
Pricing Analysis
High-volume batch release testing operates on thin margins while specialized biologics characterization commands substantial premiums. Price differentiation hinges on ISO/IEC 17025 accreditation tier and NIST-traceable calibration capability. Cost compression in routine pharmaceutical testing is intensifying because robotic automation reduces analyst touchpoints. Generic drug manufacturers exhibit highest price sensitivity; cell therapy developers show lowest sensitivity due to regulatory submission risks.
Supply Chain Analysis
Reverse-logistics for expired reference materials and recalibrated instrumentation flows through Germany, the United States, and Switzerland. Analytical equipment supply draws from Japan, Germany, and the United States. Single-source vulnerability concentrates in NIST-traceable standard production. Distribution runs through preferred provider agreements rather than spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laboratory automation and AI-driven method optimization are displacing legacy manual workflows. Digital LIMS platforms with blockchain verification replace paper-based data integrity systems.
For Market Incumbents: Deepen vertical integration into reference material production to escape NIST supply bottlenecks. Expand DAkkS-accredited capacity in Germany's Rhine-Main cluster before EU GMP Annex 1 enforcement peaks. Automation specialists threaten commoditized testing margins.
For New Entrants and Emerging Players: The mid-tier pricing gap between SGS-scale global networks and regional calibration shops offers entry room. Target India's CDSCO-recognized bioanalytical segment under PLI scheme expansion. Pursue digital-first positioning with automated colony counting and rapid microbial detection.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to accreditation network consolidators. Long-term viability favors laboratories with multi-jurisdiction recognition and biologics specialization. Watch FDA-EU mutual recognition agreement negotiations as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Network Expansion | DAkkS and UKAS multi-site recognition unlocks pharmaceutical preferred provider status. |
| Digital LIMS Integration | Blockchain-based data integrity verification commands premium pricing from FDA-regulated clients. |
| Biologics Testing Capacity Buildout | Cell therapy environmental monitoring exceeds in-house capabilities at emerging drug developers. |
| Reference Material Backward Integration | Captive NIST-traceable standard production insulates against national metrology institute lead times. |
| India CDSCO Facility Establishment | Domestic PLI scheme manufacturing requires local ISO/IEC 17025-accredited partners for export documentation. |
Research Methodology
Multi-period observation of accreditation expansion, automation deployment rates, and preferred provider agreement structures anchored the trend analysis, supplemented by interviews with laboratory quality directors, pharmaceutical regulatory affairs managers, DAkkS assessment officers, and metrology institute procurement leads. Secondary validation drew from FDA warning letter databases, EMA GMP inspection findings, ISO/IEC 17025 directory records, and national accreditation body annual reports. Bottom-up facility capacity modeling triangulated against top-down pharmaceutical outsourcing spend estimates.
Segment-weighting applied service type, industry vertical, and geographic regulatory cluster dimensions across the projection horizon. CAGRs derived from regression analysis of historical accreditation growth rates and pharmaceutical manufacturing expansion patterns. Forecast inputs incorporated EU MDR transition timelines and CDSCO PLI scheme capacity buildout schedules.
Inputs from primary stakeholder interviews were available through the study window; gaps in private laboratory financial disclosures introduce uncertainty bands around market sizing. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and automation adoption curves. Practitioners should monitor FDA 21 CFR Part 11 audit frequency and EU-UKAS mutual recognition developments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Biomarker Testing Services Market
Testing Services
Biological Indicator Incubators Market
Testing Services
Home DNA Testing Market
Testing Services
Europe Newborn Screening Market
Testing Services
Gastrointestinal Testing Panels Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
Home Blood Testing Devices Market
Testing Services
US & Europe Extractable and Leachable Testing Services Market
Testing Services
Helicobacter Pylori Testing Market
Testing Services
Self-Testing Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
Specific Protein Testing Market
Testing Services
CRO Mass Spectroscopy Services Market
Testing Services
Adenovirus Testing Market
Testing Services
Asia-Pacific Viral Clearance Market
Testing Services
Genetic Toxicology Testing Market