
 Specific Protein Testing Market | 2026-2036
Specific Protein Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Specific Protein Testing Market Analytics
Hospital reference laboratory procurement is reshaping vendor relationships across the Specific Protein Testing landscape. Thermo Fisher Scientific leverages its reagent-instrument bundling strength to secure multi-year service contracts with large health systems. Bio-Rad Laboratories anchors its position through specialized autoimmune and infectious disease protein panels that differentiate against broader-menu competitors. Siemens Healthineers competes on integrated workflow automation, extending its Atellica platform into mid-volume laboratories seeking throughput gains without footprint expansion.
Specific protein testing encompasses quantitative and qualitative analytical methods that detect individual protein biomarkers in biological specimens using antibody-antigen binding, mass spectrometric detection, or electrophoretic separation with functional sensitivity thresholds typically reaching picogram-per-milliliter concentrations. These assays serve clinical diagnostic decision-making for disease staging, therapeutic monitoring, and risk stratification across oncology, immunology, and cardiovascular specialties. Immunoassay technology dominates installed base economics due to regulatory familiarity and reimbursement codification, while mass spectrometry segments capture fastest growth from multiplex protein profiling demands in precision medicine workflows. Research applications sustain premium pricing through grant-funded instrument acquisitions, though clinical diagnostics concentrates the largest revenue pool from recurring reagent consumption at hospital laboratories.
FDA oversight of in vitro diagnostic devices and the European Union's In Vitro Diagnostic Regulation impose escalating clinical evidence requirements that filter market access toward well-capitalized manufacturers with dedicated regulatory affairs infrastructure. The Centers for Medicare & Medicaid Services' laboratory fee schedule adjustments directly influence test menu profitability and drive consolidation among independent reference laboratories. Stakeholders must monitor evolving companion diagnostic co-development partnerships between assay manufacturers and pharmaceutical sponsors, as these alliances increasingly determine platform standardization decisions across major oncology trials.
Market Dynamics
Automated immunoassay platforms are compressing turnaround times for high-volume specific protein testing, forcing mid-tier laboratories to consolidate workflows or exit the market entirely. This technology-driven consolidation redistributes volume toward integrated health systems with capital for platform standardization.
Growth Catalysts
- FDA IVDR Alignment:Companion diagnostic validation requirements are tightening quality benchmarks, filtering out low-complexity assay providers and concentrating revenue among manufacturers with dedicated regulatory infrastructure.
- Oncology Precision Medicine:Multiplex protein profiling demand from pharmaceutical co-development partnerships is accelerating platform standardization decisions across major clinical trials.
- Hospital System Consolidation:United States academic medical centers are driving premium instrument placements through multi-year reagent-instrument bundling contracts.
Market Restraints
- Antibody Supply Concentration:Specialized monoclonal antibody production concentrates among a limited supplier base, creating input cost volatility for assay manufacturers.
- CMS Fee Schedule Compression:Laboratory reimbursement adjustments directly erode test menu profitability for independent reference laboratories.
- Mass Spectrometry Capital Intensity:Seven-figure instrument costs and specialized facility requirements limit adoption to grant-funded research institutions and tier-one health systems.
Strategic Opportunities
- Mid-Volume Laboratory Automation:Workflow-integrated platforms without footprint expansion are capturing underserved laboratories seeking throughput gains.
- Autoimmune Disease Panels:Specialized protein biomarker combinations differentiate against broader-menu competitors in rheumatology and immunology specialties.
- Research Grant Funding Channels:National Institutes of Health instrumentation awards sustain premium pricing for high-sensitivity detection systems outside clinical reimbursement constraints.
Industry Challenges
- Mass Spectrometry Specialist Shortage:Clinical laboratories face acute recruitment gaps for PhD-level mass spectrometrists capable of validating multiplex protein assays.
- Legacy Immunoassay Integration:Health systems with decade-old installed bases encounter workflow friction when bridging manual and automated platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specific Protein Testing Market |
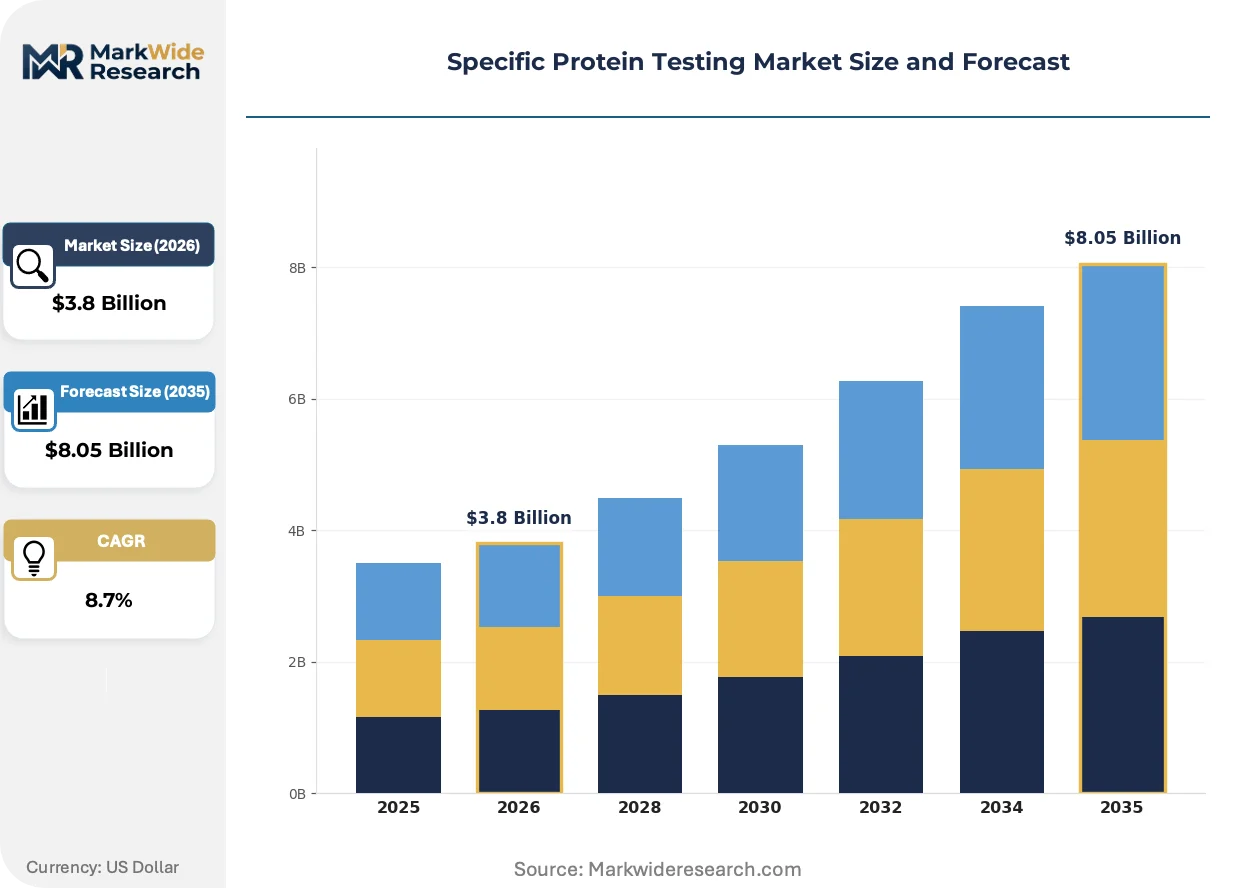
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA Kits, Immunoassays, Western Blotting, Mass Spectrometry Technology: Enzyme-Linked, Fluorescence, Radioimmunoassay, Luminex Application: Clinical Diagnostics, Research, Drug Discovery, Quality Control End User: Hospitals, Laboratories, Research Institutes, Pharmaceutical Companies |
| Companies Covered | Thermo Fisher Scientific Inc., Bio-Rad Laboratories, Inc., Siemens Healthineers AG, Abbott Laboratories, Danaher Corporation, Roche Diagnostics, PerkinElmer, Inc., Agilent Technologies, Inc., Sartorius AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specific Protein Testing Market Evolving Landscape
Multiplex detection architectures and regulatory harmonization initiatives are compressing the traditional separation between research-grade and clinical-grade protein quantification. These forces are redrawing competitive boundaries across instrument, reagent, and service segments.
High-resolution mass spectrometry is collapsing the cost-per-analyte economics of protein biomarker panels. Academic medical centers in the United States are adopting these platforms for precision oncology workflows. The technology is collapsing the historical distinction between discovery-phase and clinical-phase assay development, enabling same-platform translation from bench to bedside.
The European Union's In Vitro Diagnostic Regulation is extending clinical evidence requirements to Class B and C protein assays previously cleared through self-certification. Manufacturers must now submit prospective performance studies for novel biomarker claims. Mid-sized assay developers without dedicated regulatory affairs infrastructure are withdrawing from the EU market or partnering with larger manufacturers for distribution.
Health system procurement teams are unbundling instrument service contracts from reagent supply agreements, forcing vendors to compete on discrete value propositions. Large integrated delivery networks in the United States are negotiating separate pricing for preventive maintenance, emergency repair, and remote monitoring services. This unbundling is most visible in multi-hospital systems with centralized laboratory oversight committees.
Specific Protein Testing Market Segmentation
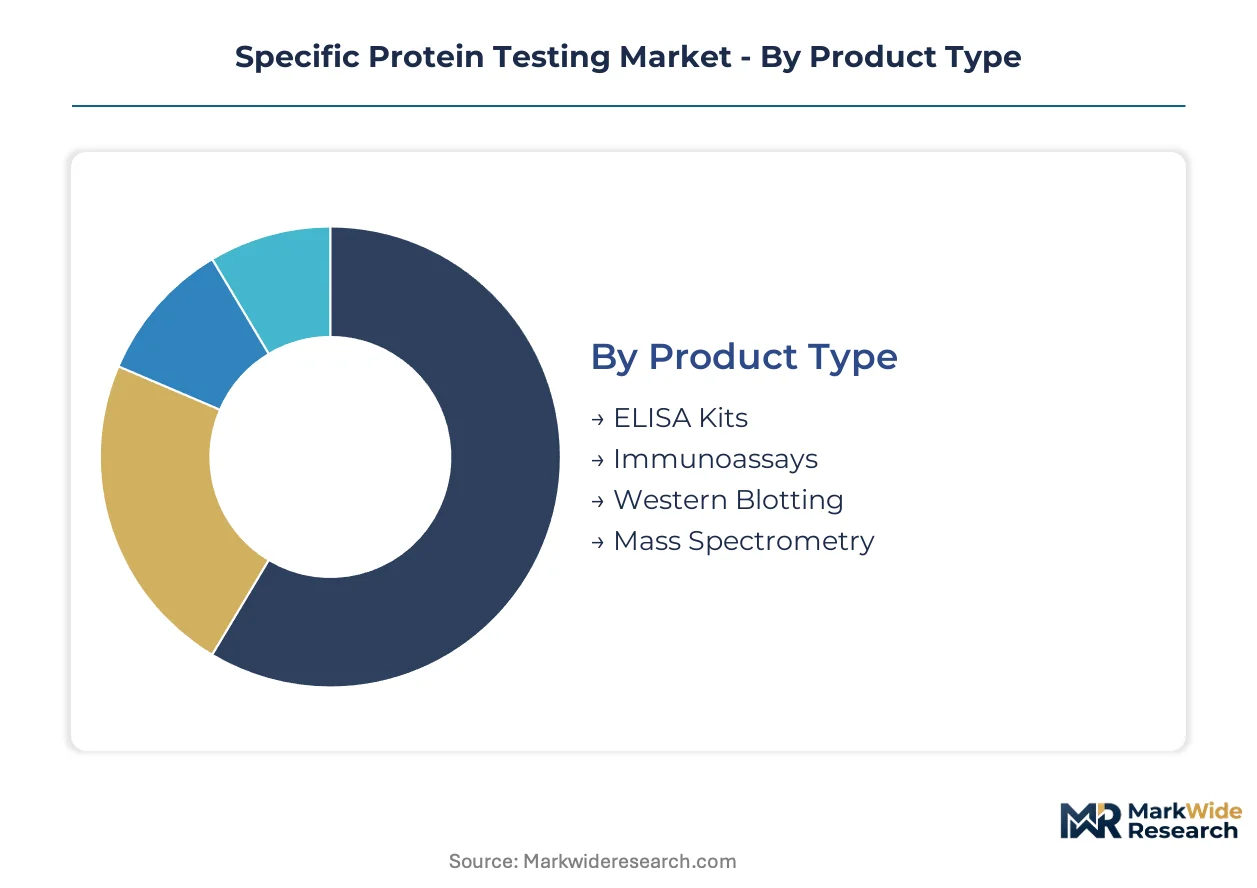
Segmentation in specific protein testing reveals divergent equipment lifecycles and reagent consumption patterns. Clinical diagnostics laboratories rotate immunoassay platforms on five-to-seven-year replacement cycles, while mass spectrometry installations persist for twelve to fifteen years with incremental detector upgrades.
Product Type:
Immunoassay platforms turn over fastest in high-throughput hospital laboratories, while mass spectrometry systems remain anchored for decade-plus service lives with modular component refreshes.
- Immunoassays:Automated analyzers process thousands of protein determinations daily using chemiluminescent or electrochemiluminescent detection with picogram-per-milliliter sensitivity. United States academic medical centers drive replacement demand as health systems consolidate onto standardized platforms to reduce reagent complexity and service contract fragmentation.
- Mass Spectrometry:High-resolution systems enable multiplex protein profiling across hundreds of analytes simultaneously using liquid chromatography-tandem mass spectrometry workflows. Research institutes and tier-one health systems in the United States absorb capital intensity through NIH instrumentation grants, though clinical translation requires FDA 510(k) clearance for diagnostic claims.
- ELISA Kits:Microplate-based enzyme-linked immunosorbent assays serve lower-throughput laboratories with manual or semi-automated processing. Research institutes sustain volume through grant-funded consumable purchasing outside clinical reimbursement constraints.
- Western Blotting:Gel electrophoresis combined with antibody detection remains essential for protein molecular weight verification and post-translational modification analysis. Academic research laboratories maintain installed bases despite longer turnaround times compared to automated alternatives.
Immunoassays dominate installed base economics through recurring reagent consumption. Mass spectrometry is where expansion concentrates for precision oncology multiplex profiling.
Technology:
Detection chemistry selection hinges on sensitivity requirements, throughput demands, and regulatory pathway complexity for diagnostic claims.
- Enzyme-Linked:Horseradish peroxidase and alkaline phosphatase conjugates generate colorimetric or chemiluminescent signals with established FDA predicate device pathways. Hospital laboratories favor these systems for routine protein quantification where regulatory familiarity accelerates validation timelines.
- Fluorescence:Fluorophore-labeled antibodies enable multiplex detection with spectral resolution across multiple analytes. Drug discovery operations prioritize these platforms for high-content screening applications requiring simultaneous protein panel measurement.
- Radioimmunoassay:Iodine-125 labeled tracers deliver femtomolar detection limits for specialized endocrine protein measurements. Clinical laboratories with nuclear medicine licensing maintain limited capacity for reference-range confirmation of challenging analytes.
- Luminex:Bead-based flow cytometric detection supports simultaneous quantification of up to 500 protein targets per sample. Cytokine profiling and autoimmune panel applications drive adoption among research institutes and specialized reference laboratories.
Enzyme-linked detection anchors routine clinical throughput. Fluorescence and Luminex platforms are climbing fastest for multiplex research applications.
Application:
End-use economics separate recurring clinical revenue from episodic research instrumentation cycles and milestone-dependent pharmaceutical funding.
- Clinical Diagnostics:Disease staging, therapeutic monitoring, and risk stratification applications generate recurring reagent revenue through Medicare and commercial insurance reimbursement. United States hospital laboratories concentrate volume as integrated delivery networks negotiate multi-year supply agreements.
- Research:Grant-funded basic science and translational investigations sustain premium pricing for high-sensitivity detection systems outside clinical regulatory constraints. NIH and NSF instrumentation awards drive cyclical purchasing aligned with federal budget appropriations.
- Drug Discovery:Pharmaceutical sponsors utilize protein biomarker data for patient stratification, pharmacodynamic response measurement, and companion diagnostic co-development. Contract research organizations manage specialized bioanalytical capacity on behalf of sponsor companies.
- Quality Control:Biopharmaceutical manufacturing operations validate batch consistency and detect process-related impurities using validated protein quantification methods. FDA process analytical technology initiatives encourage real-time monitoring integration.
Clinical diagnostics commands the largest revenue pool through consumable replenishment. Drug discovery represents the steepest expansion trajectory from companion diagnostic partnership structures.
End User:
Procurement authority and capital access differentiate institutional purchasing behavior across the customer base.
- Hospitals:Integrated health systems leverage multi-hospital volume for reagent-instrument bundling negotiations with manufacturers. Centralized laboratory oversight committees standardize platforms to reduce training complexity and service contract proliferation.
- Laboratories:Independent reference laboratories and hospital-affiliated operations face CMS fee schedule compression that erodes test menu profitability. Consolidation toward larger entities accelerates as smaller operators exit protein testing services.
- Research Institutes:University and government laboratory facilities acquire instrumentation through competitive grant mechanisms with equipment-dedicated funding lines. Maintenance and reagent costs compete with personnel budgets for operational allocation.
- Pharmaceutical Companies:Sponsor organizations internalize biomarker testing capacity or outsource to contract research organizations based on pipeline stage and strategic priority. Companion diagnostic co-development partnerships increasingly determine platform standardization.
Hospitals anchor installed base concentration through system-wide standardization mandates. Pharmaceutical company partnerships are gaining share fastest as precision medicine trials expand protein biomarker requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States academic medical centers while European laboratories absorb IVDR compliance costs without commensurate reimbursement gains. German and French reference laboratories face margin compression from regulatory overhead that American counterparts avoid.
United States
Academic medical centers in Boston and Houston drive premium instrument placements through NIH-funded precision oncology initiatives. FDA companion diagnostic guidelines tighten validation requirements for multiplex protein assays. The Research Triangle Park cluster anchors pharmaceutical co-development partnerships between assay manufacturers and oncology trial sponsors.
Germany
Baden-Württemberg industrial laboratories absorb EMA IVDR implementation costs while maintaining ISO 15189 accreditation for clinical protein testing. The country's national pharmaceutical regulator requires prospective performance studies for novel biomarker claims that previously self-certified. Munich and Heidelberg research institutes sustain mass spectrometry capacity through federal excellence cluster funding.
China
NMPA regulatory harmonization with international standards accelerates local assay manufacturer consolidation. The Yangtze River Delta biotech corridor concentrates domestic immunoassay production in Shanghai and Suzhou industrial parks. Beijing-Tianjin-Hebei health system procurement centralization favors vendors with integrated workflow automation platforms.
Japan
PMDA quality management system inspections filter market access toward manufacturers with dedicated Japanese regulatory affairs infrastructure. Tokyo and Osaka metropolitan hospitals standardize platforms to reduce reagent complexity across consolidated delivery networks. METI industrial competitiveness grants sustain domestic mass spectrometry component manufacturing in Nagoya precision instrument clusters.
United Kingdom
NHS England procurement frameworks unbundle instrument service contracts from reagent supply agreements, forcing discrete vendor competition. The country's national pharmaceutical regulator enforces post-market surveillance for protein assays previously exempt from active monitoring. Cambridge and Oxford academic laboratories anchor companion diagnostic co-development with European pharmaceutical sponsors.
Specific Protein Testing Market Competitive Landscape
Integrated conglomerates and specialized diagnostics firms split the market along capital intensity and menu breadth vectors. The installed base concentrates among five manufacturers with dedicated regulatory affairs infrastructure spanning FDA, EMA, and NMPA jurisdictions. Two strategic archetypes dominate: reagent-instrument bundlers leveraging service contract lock-in, and autoimmune panel specialists differentiating through biomarker combinations. Competitive moves center on mid-volume laboratory automation partnerships and pharmaceutical companion diagnostic co-development alliances.
Within the bundling archetype, Thermo Fisher Scientific Inc. and Siemens Healthineers AG exemplify platform standardization strategies that capture multi-year health system contracts. Bio-Rad Laboratories, Inc. occupies a specialist position differentiated by focused protein panel development. These three entities represent the regulatory scale and portfolio breadth required for IVDR-era market access.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories, Inc. |
| Siemens Healthineers AG |
| Abbott Laboratories |
| Danaher Corporation |
| Roche Diagnostics |
| PerkinElmer, Inc. |
| Agilent Technologies, Inc. |
| Sartorius AG |
| Others |
Value Network & Pricing Analysis
Specialized monoclonal antibody production concentrates among United States and European bioreactor facilities, anchoring input cost volatility that cascades into assay manufacturer margin structures and reagent pricing tiers. This upstream biologics concentration leaves downstream clinical diagnostics laboratories exposed to supply allocation decisions that prioritize pharmaceutical customers over IVD reagent producers.
Pricing Analysis
Configured-to-order immunoassay panel pricing commands 40-60% premiums over standard protein quantification menus, reflecting customization complexity and validation burden. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared companion diagnostic assays from research-use-only kits and unregulated ELISA consumables. Cost compression in mid-volume laboratory segments is intensifying because health system procurement committees unbundle service contracts from reagent supply agreements. Independent reference laboratories exhibit highest price sensitivity due to CMS fee schedule compression, while academic medical centers absorb premium instrument placements through NIH grant funding channels.
Supply Chain Analysis
Export control regimes restricting high-resolution mass spectrometry components limit instrument flows from United States and German precision manufacturing clusters to Chinese and Russian end users. Assay manufacturing draws from monoclonal antibody production in United States bioreactor facilities, detector electronics from Japanese component suppliers, and plastic consumables molded in Mexican maquiladora operations. Single-source vulnerability concentrates in specialized affinity reagent production, where sole-supplier relationships for rare protein targets create allocation risk during demand surges. Distribution runs through manufacturer-direct field service organizations for capital equipment, with reagent consumables flowing through group purchasing organizations and specialized diagnostics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specific protein testing sits in early-cycle expansion as precision oncology trials accelerate multiplex protein biomarker adoption beyond traditional immunoassay menus. Pharmaceutical co-development partnerships are pulling clinical-grade assay validation forward into research workflows.
For Market Incumbents: Harden regulatory affairs infrastructure against escalating FDA IVDR alignment requirements for companion diagnostic claims. Expand dedicated quality systems teams to manage prospective performance study submissions that filter out undercapitalized competitors. Deepen backward integration into monoclonal antibody production to secure reagent supply against bioreactor allocation competition from pharmaceutical customers.
For New Entrants and Emerging Players: Build out autoimmune disease panel specialization as a white-space entry vector, where biomarker combination expertise differentiates against broader-menu competitors. Target mid-volume hospital laboratories seeking workflow automation without footprint expansion, a segment underserved by capital-intensive mass spectrometry vendors. Pursue research grant funding channels as initial revenue anchor, leveraging NIH instrumentation awards to bypass clinical reimbursement constraints during platform development.
For Investors and Strategic Acquirers: Capital is best deployed toward autoimmune panel specialists with proprietary biomarker combinations and established rheumatology reference laboratory relationships, positioned for IVDR-era consolidation. Long-term viability hinges on regulatory scale spanning FDA, EMA, and NMPA jurisdictions as market access barriers concentrate revenue among compliant manufacturers. Watch pharmaceutical companion diagnostic partnership announcements as inflection indicators, since these alliances increasingly determine platform standardization across major oncology trials.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | Pharmaceutical co-development alliances determine platform standardization in precision oncology trials. |
| Regulatory Scale Investment | Dedicated FDA, EMA, and NMPA infrastructure filters market access toward well-capitalized assay manufacturers. |
| Mid-Volume Automation Launch | Workflow-integrated platforms without footprint expansion capture underserved hospital laboratory segments. |
| Reagent-Instrument Bundling | Multi-year service contracts with integrated health systems lock in recurring consumable revenue streams. |
| Autoimmune Panel Specialization | Biomarker combination expertise differentiates against broader-menu competitors in rheumatology specialties. |
Research Methodology
Cross-validation between primary interviews with clinical laboratory directors, regulatory affairs specialists at assay manufacturers, hospital procurement committee members, and pharmaceutical biomarker strategists anchors the qualitative findings. Secondary validation draws from FDA 510(k) clearance databases, EMA IVDR implementation guidance documents, CMS laboratory fee schedule publications, and NIH instrumentation grant award records. Bottom-up and top-down triangulation reconciles instrument installation counts with reagent consumption estimates across hospital, reference laboratory, and research institute end-use segments.
Calibration against historical replacement cycles and grant funding appropriation patterns shapes the analytical framework across the analysis window. Segmentation dimensions modeled include product type, detection technology, clinical versus research application, and end-user procurement authority tier. CAGRs derive from instrument placement velocity projections and per-test reagent consumption curves, with precision oncology trial expansion and IVDR compliance cost absorption as key forecast inputs.
Sensitivities concentrate around pharmaceutical pipeline progression, monoclonal antibody supply allocation shifts, and CMS reimbursement adjustments. Forecasts reflect documented assumptions regarding health system consolidation trajectories and regulatory harmonization timelines. Material shifts in companion diagnostic partnership structures or export control regime expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Bioburden Testing Market
Testing Services
Medical Device Analytical Testing Outsourcing Market
Testing Services
Diagnostic Shipper Market
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
Global Cannabis Testing Market
Testing Services
STD Testing Devices Market
Testing Services
North America Newborn Screening Market
Testing Services
US at-Home Testing Kits Market
Testing Services
Alcohol Breathalyzer and Drug Testing Equipment Market
Testing Services
US Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Hemotransmissive Infections Testing Market
Testing Services
Friability Tester Market
Testing Services
Calprotectin Testing Market
Testing Services
Bimetallic Thermometer Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market