
 Cardiac Marker Analyzer Market | 2026-2036
Cardiac Marker Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Marker Analyzer Market Analysis
A shortage of trained clinical laboratory scientists is reorganizing how healthcare systems deploy cardiac marker analyzers, forcing automation upgrades and remote monitoring capabilities. Abbott Laboratories leverages its broad immunoassay portfolio to sustain installed-base loyalty across hospital networks. Siemens Healthineers AG anchors its position through integrated laboratory informatics that streamline troponin workflow management. Danaher competes via operational excellence in its diagnostics platform, controlling costs that pressure mid-tier rivals.
A cardiac marker analyzer is an in vitro diagnostic instrument that quantifies protein biomarkers—principally troponin I, troponin T, BNP, and NT-proBNP—in blood samples using chemiluminescence or electrochemical detection methods, enabling rapid assessment of myocardial injury or cardiac stress. Point-of-care devices command premium placement in emergency departments where turnaround time under fifteen minutes directly influences admission decisions, while benchtop analyzers retain volume dominance in centralized hospital laboratories processing high-throughput troponin panels. Immunoassay technology leads absolute revenue but biosensor platforms are capturing fastest growth as solid-state electrodes reduce reagent consumption and calibration frequency.
The FDA's Clinical Laboratory Improvement Amendments and the EU's In Vitro Diagnostic Regulation impose divergent conformity pathways that fragment product development roadmaps for multinational suppliers. ISO 15189 accreditation standards for medical laboratories shape analyzer specifications around traceability and quality control documentation. Stakeholders must weigh the capital efficiency of portable analyzer expansion against the analytical precision of laboratory platforms as health systems recalibrate site-of-care strategies.
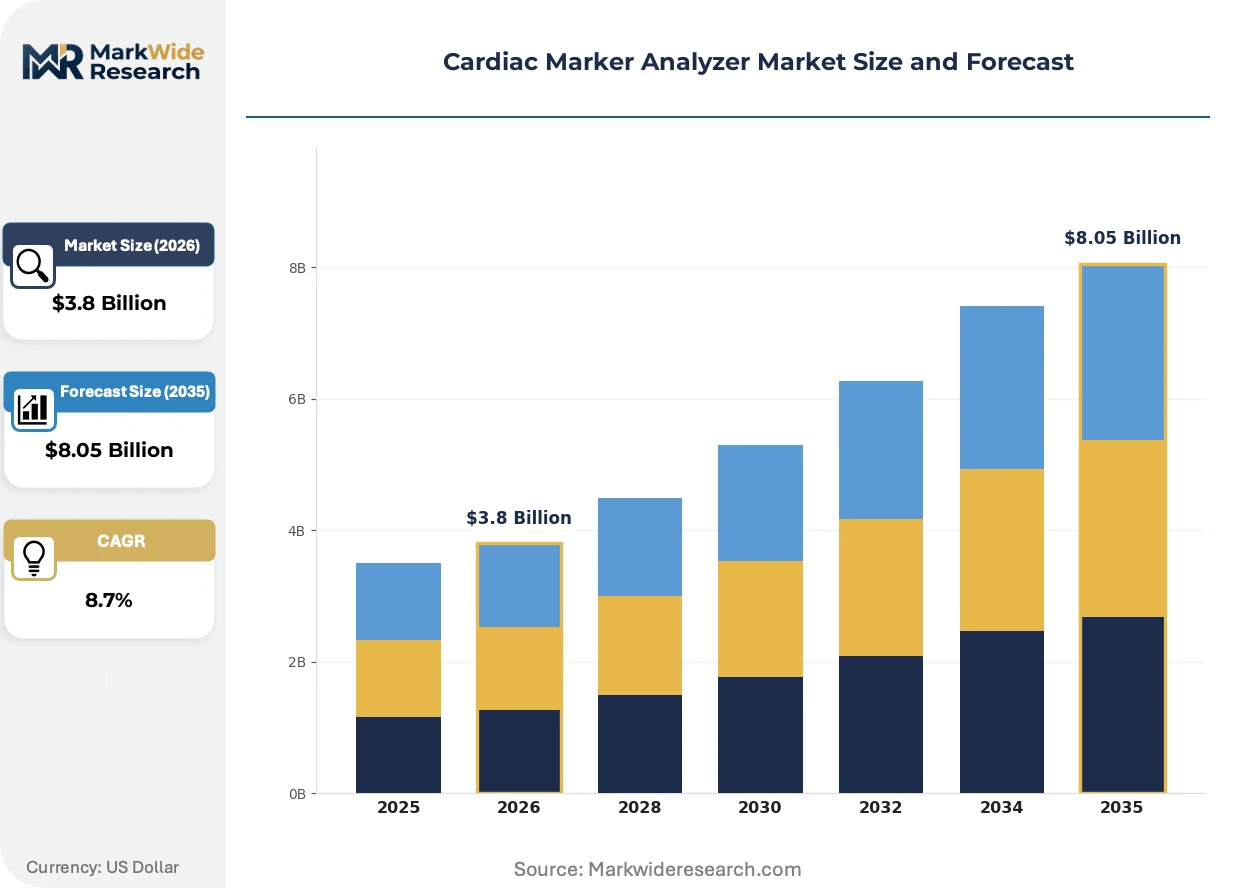
Market Dynamics
The shortage of trained clinical laboratory scientists is forcing health systems to automate cardiac marker workflows and deploy remote monitoring capabilities, compressing the traditional site-of-care hierarchy between emergency departments and centralized labs.
Growth Catalysts
- Emergency department triage protocols:Hospital networks in the United States are mandating sub-fifteen-minute troponin turnaround times, accelerating point-of-care analyzer placement at the expense of send-out testing.
- FDA analytical sensitivity guidance:Evolving in vitro diagnostic standards for high-sensitivity troponin assays are pushing manufacturers to upgrade detection platforms, creating replacement demand across installed bases.
- Chemiluminescence miniaturization:Solid-state electrode advances are reducing reagent consumption and calibration frequency, lowering total cost of ownership for mid-sized hospital laboratories.
Market Restraints
- Reagent supply concentration:Critical antibody and enzyme inputs for troponin immunoassays depend on a narrow supplier base concentrated in Germany and Switzerland, exposing procurement to single-source risk.
- EU MDR conformity costs:The European Union's In Vitro Diagnostic Regulation imposes extended clinical evidence requirements and notified body bottlenecks, delaying product launches by 18-36 months.
- Optical biosensor substitution:Surface plasmon resonance platforms are capturing research-laboratory volume for cardiac biomarker discovery, threatening to migrate downstream into clinical diagnostics.
Strategic Opportunities
- Ambulatory surgical center expansion:United States outpatient facilities are adding pre-operative cardiac risk stratification, creating demand for compact benchtop analyzers with moderate throughput.
- Integrated delivery network consolidation:IDN laboratory procurement centralization favors vendors offering standardized troponin protocols across distributed hospital campuses, rewarding platform breadth.
- Remote connectivity mandates:ISO 15189 accreditation requirements for quality control documentation are opening aftermarket revenue streams in cloud-based analyzer monitoring and predictive maintenance.
Industry Challenges
- Clinical laboratory scientist scarcity:The United States faces a 25,000-person shortfall in credentialed personnel, forcing automation investments that strain capital budgets at community hospitals.
- Legacy LIS integration complexity:Hospital information system heterogeneity requires custom middleware development for each cardiac analyzer deployment, extending implementation timelines and inflating professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Marker Analyzer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Analyzers, Portable Analyzers, Point-of-Care Devices, Laboratory Analyzers Application: Cardiac Events, Chronic Heart Failure, Acute Coronary Syndrome, Myocardial Infarction End User: Hospitals, Diagnostic Laboratories, Clinics, Homecare Settings Technology: Immunoassay, Molecular Diagnostics, Biosensors, Microfluidics |
| Companies Covered | F. Hoffmann-La Roche Ltd, Abbott Laboratories, Quidel Corporation, Siemens Healthineers AG, Danaher, LSI Medience Corporation, CardioGenics Holdings Inc, Trinity Biotech, Beckman Coulter, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Marker Analyzer Market Emerging Trajectories
Detection platform diversification is fragmenting the historical chemiluminescence monopoly, while regulatory divergence between the United States and European Union forces parallel product development tracks.
Biosensor architectures built on solid-state electrochemical electrodes are fragmenting the cardiac marker analyzer technology landscape. These platforms eliminate photomultiplier tubes and reduce optical alignment complexity. Community hospital laboratories in the United States are adopting them at twice the rate of academic medical centers. The structural consequence is compressing price premiums for traditional chemiluminescence systems outside the highest-sensitivity troponin segment.
The European Union's In Vitro Diagnostic Regulation is recasting conformity assessment pathways for cardiac marker analyzers. Clinical evidence requirements now demand larger patient cohorts for troponin assay validation. Manufacturers serving the EU market are responding by prioritizing high-volume troponin platforms over niche cardiac biomarker panels, consolidating R&D roadmaps around proven analytes.
Integrated delivery networks are unbundling analyzer procurement from reagent supply contracts. Hospital systems in the United States are negotiating separate agreements for capital equipment and consumables, displacing the traditional bundled lease model. This pattern is most visible in the Southeast and Midwest IDNs, where procurement committees now benchmark total cost per reportable result across multi-vendor scenarios.
Cardiac Marker Analyzer Market Segmentation
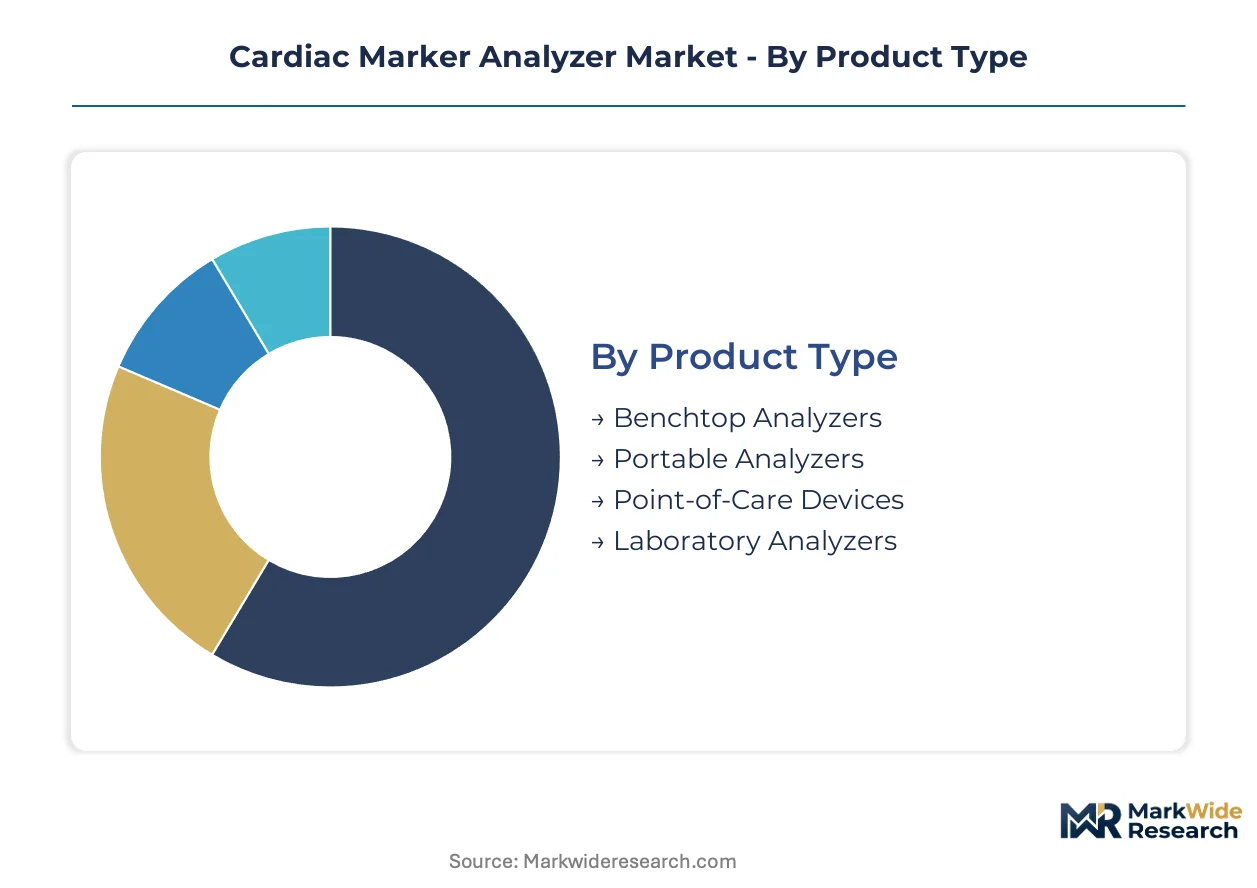
Cardiac marker analyzer segmentation reflects divergent site-of-care economics. Product configuration, clinical application, and technology platform each reshape procurement priorities across hospital networks and outpatient settings.
Product Type:
Domestic demand concentrates in benchtop systems for centralized laboratories, while portable and point-of-care formats drive export-led growth into emerging health systems seeking decentralized diagnostics.
- Benchtop Analyzers:These high-throughput systems process 200-400 samples hourly using chemiluminescence detection with automated sample handling. United States academic medical centers anchor demand as integrated delivery networks standardize troponin protocols across multiple campuses.
- Portable Analyzers:Compact units weighing under 15 kilograms deliver troponin results in 10-15 minutes using solid-state electrochemical sensors. Community hospitals in the United States Southeast and Midwest adopt these at twice the rate of academic centers to address clinical laboratory scientist shortages.
- Point-of-Care Devices:Handheld units for emergency department triage with sub-15-minute turnaround.
- Laboratory Analyzers:Floor-standing systems for reference laboratories processing 1,000+ daily samples.
Benchtop analyzers command the established base. The steepest expansion runs through point-of-care devices.
Application:
Volume tiers separate routine chronic monitoring from acute event triage, with cost-per-test economics driving divergent platform selection.
- Cardiac Events:Emergency department protocols for chest pain evaluation require high-sensitivity troponin detection at femtomolar concentrations. United States hospital networks mandate sub-15-minute turnaround times, accelerating point-of-care placement.
- Acute Coronary Syndrome:Serial troponin testing at 0, 3, and 6-hour intervals demands analyzer reliability above 99% uptime. Diagnostic laboratories in Germany and Switzerland anchor procurement for these workflows.
- Chronic Heart Failure:BNP and NT-proBNP monitoring for outpatient volume status management.
- Myocardial Infarction:Definitive troponin elevation confirmation for admission decisions.
Acute coronary syndrome applications command the established base. The steepest expansion runs through chronic heart failure monitoring.
End User:
Customer concentration patterns split between capital-rich hospital systems and cost-constrained outpatient settings.
- Hospitals:Emergency departments and central laboratories deploy mixed analyzer fleets balancing point-of-care speed with laboratory precision. United States integrated delivery networks now unbundle equipment procurement from reagent contracts.
- Diagnostic Laboratories:Independent reference labs and hospital outreach programs process send-out troponin panels. These facilities in Germany and Switzerland concentrate procurement for high-volume immunoassay platforms.
- Clinics:Cardiology and internal medicine practices adding pre-operative risk stratification.
- Homecare Settings:Remote patient monitoring programs for post-discharge heart failure management.
Hospital end users command the established base. The steepest expansion runs through diagnostic laboratories.
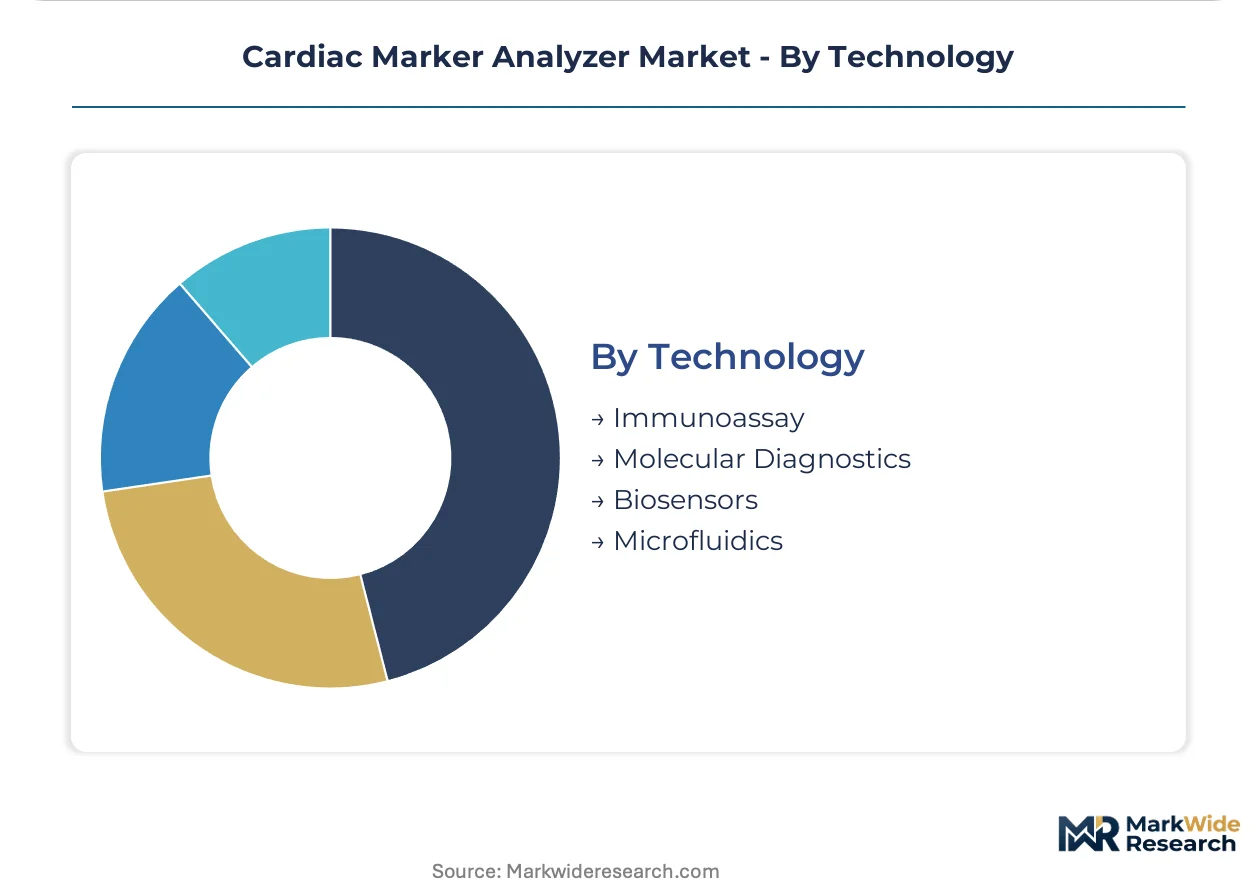
Technology:
Platform maturity separates proven chemiluminescence dominance from emerging biosensor disruption.
- Immunoassay:Chemiluminescence microparticle immunoassay technology delivers femtomolar sensitivity for high-sensitivity troponin I and T. FDA guidance on analytical sensitivity standards drives replacement demand across installed bases in the United States.
- Biosensors:Solid-state electrochemical electrodes eliminate photomultiplier tubes and reduce calibration frequency. Community hospitals adopt these platforms to lower total cost of ownership.
- Molecular Diagnostics:PCR and nucleic acid amplification for genetic cardiac risk markers.
- Microfluidics:Lab-on-chip architectures integrating sample preparation with detection.
Immunoassay technology commands the established base. Biosensor platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on high-sensitivity troponin assays anchors the United States as the dominant geography, while EU MDR conformity costs and laboratory scientist shortages reshape procurement patterns across Germany, Japan, China, and India.
United States
Emergency department triage protocols and integrated delivery network consolidation drive analyzer deployment. FDA evolving standards for analytical sensitivity push manufacturers toward platform upgrades. Hospital networks in the Southeast and Midwest unbundle equipment procurement from reagent contracts.
Germany
Diagnostic laboratories anchor European demand for high-throughput immunoassay platforms. EU MDR extended clinical evidence requirements delay product launches by 18-36 months. The Rhine-Ruhr metropolitan region concentrates reference laboratory procurement for serial troponin testing workflows.
Japan
PMDA regulatory frameworks emphasize traceability standards for medical laboratory accreditation. METI industrial policy supports domestic diagnostics manufacturing. The Kanto region surrounding Tokyo hosts concentrated demand from academic medical centers standardizing cardiac biomarker protocols.
China
NMPA approval pathways for in vitro diagnostic devices accelerate for domestic manufacturers. Hospital laboratory automation investments address personnel constraints in tier-two cities. The Yangtze River Delta cluster drives point-of-care analyzer adoption in provincial emergency departments.
India
CDSCO regulatory harmonization with international standards shapes import-dependent procurement. Private hospital chains expand cardiac care networks into tier-three cities. Maharashtra and Karnataka states concentrate demand for portable analyzers addressing clinical laboratory scientist scarcity.
Cardiac Marker Analyzer Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding installed-base loyalty through broad immunoassay portfolios and laboratory informatics integration. Mid-tier competitors face cost pressures from operational excellence programs. Three archetypes dominate: diversified diagnostics conglomerates with full-platform coverage, point-of-care specialists with emergency department placement expertise, and regional manufacturers serving price-sensitive procurement committees. Competitive moves concentrate on strategic partnerships for remote monitoring capabilities and portfolio diversification into biosensor platforms.
Among diversified diagnostics conglomerates, F. Hoffmann-La Roche Ltd and Abbott Laboratories exemplify the integrated-leader archetype through their positions across chemiluminescence and point-of-care formats. Siemens Healthineers AG occupies a distinct position anchoring laboratory informatics integration. Danaher represents the operational-excellence vector through diagnostics platform consolidation. Quidel Corporation sits within the point-of-care specialist tier. These five entities collectively illustrate the competitive structure: scale-driven platform breadth versus targeted site-of-care specialization.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Quidel Corporation |
| Siemens Healthineers AG |
| Danaher |
| LSI Medience Corporation |
| CardioGenics Holdings Inc |
| Trinity Biotech |
| Beckman Coulter, Inc |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German and Swiss antibody production facilities anchors cost structures for troponin immunoassay reagents, compressing margins for mid-tier manufacturers unable to secure long-term supply commitments. This scale concentration creates asymmetric pricing power where integrated diagnostics conglomerates capture volume discounts unavailable to standalone analyzer vendors, while community hospitals absorb premium markups on consumables.
Pricing Analysis
United States emergency departments pay 40-60% above German reference laboratory rates for equivalent high-sensitivity troponin testing capacity. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared high-sensitivity assays from CE-marked moderate-sensitivity platforms and research-use-only systems. Pricing pressure stems from IDN procurement centralization unbundling equipment from reagent contracts. Community hospitals in the Southeast and Midwest exhibit highest price sensitivity due to capital budget constraints, while academic medical centers prioritize analytical sensitivity over unit economics.
Supply Chain Analysis
Monoclonal antibody production concentrates in Germany, Switzerland, and the Netherlands, creating single-source vulnerability for troponin assay reagents. Critical inputs include recombinant antibodies, streptavidin-coated microparticles, and acridinium ester chemiluminescence substrates. Tariff exposure runs through EU-sourced reagents imported into United States manufacturing facilities. Distribution runs through GPO-negotiated contracts with regional warehousing in Dallas, Chicago, and Atlanta serving hospital network consolidation zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
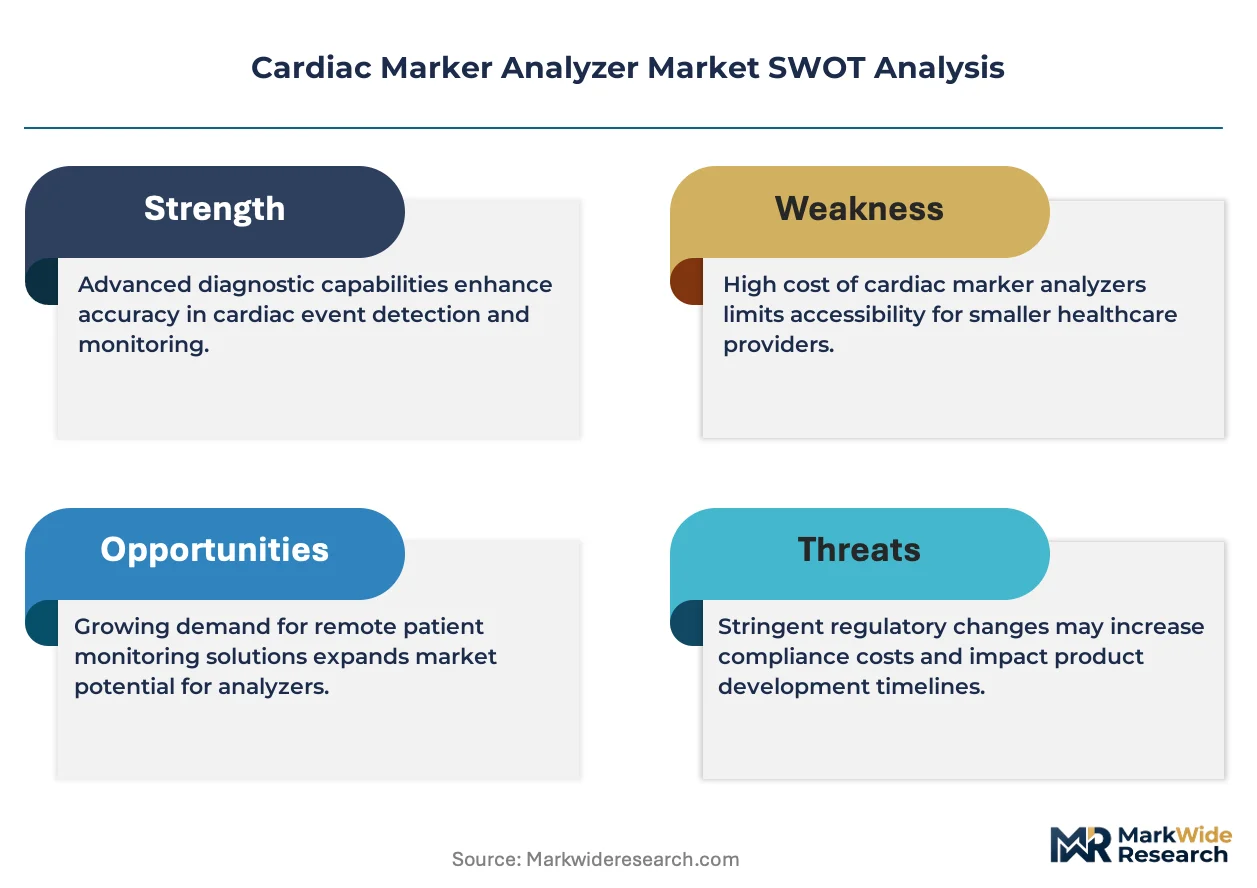
Platform economics in cardiac marker analyzers are pivoting toward interoperability ecosystems where cloud-based quality control documentation and remote predictive maintenance create switching costs exceeding hardware differentiation. FDA's evolving analytical sensitivity guidance and ISO 15189 connectivity mandates are accelerating this shift from standalone instruments to integrated diagnostic networks.
For Market Incumbents: Consolidate installed-base loyalty through backward integration into high-sensitivity antibody production and captive cloud-monitoring services. Lock in IDN procurement committees with standardized troponin protocols across distributed campuses. Defend against biosensor substitution by embedding solid-state electrochemical platforms within existing chemiluminescence portfolios. For New Entrants and Emerging Players: Lead with portable analyzer deployments in United States ambulatory surgical centers and India tier-three private hospital chains where clinical laboratory scientist scarcity creates urgent automation demand. Target pre-operative cardiac risk stratification workflows with compact benchtop systems offering moderate throughput at sub-premium price positioning. Pursue CDSCO fast-track approvals for import-dependent Indian procurement committees. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with unbundled reagent supply contracts and cloud-based analyzer monitoring subscriptions. Long-term viability favors platforms with demonstrated EU MDR conformity pathway completion and established GPO contract penetration. Monitor FDA high-sensitivity troponin assay guidance finalization as inflection indicator for replacement demand acceleration across installed bases.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | High-sensitivity troponin assay clearance anchors United States hospital network procurement decisions. |
| CE Marking Pathway | EU MDR conformity completion unlocks diagnostic laboratory demand in Germany and Switzerland. |
| Hospital System Partnership | Integrated delivery network standardization agreements displace fragmented point-of-care purchasing. |
| Software Companion Development | Cloud-based quality control documentation satisfies ISO 15189 remote connectivity mandates. |
| Reimbursement Strategy | CMS coverage alignment for emergency department troponin protocols accelerates point-of-care placement. |
Methodological Framework
A spread of perspectives from hospital laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists at IVD manufacturers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare laboratory fee schedule data. Bottom-up instrument placement estimates triangulated against top-down diagnostics market sizing across the analysis window.
Segmentation dimensions modeled include product configuration, clinical application, technology platform, and end-user site-of-care economics. Volume and value outputs reflect cross-referencing of manufacturer shipment data with hospital capital expenditure disclosures and IDN standardization announcements. CAGRs were derived from slope analysis of replacement demand curves and point-of-care expansion trajectories. Forecast inputs incorporated clinical laboratory scientist vacancy rates and EU MDR approval timeline bottlenecks.
Underlying assumptions cover stable FDA analytical sensitivity guidance implementation and sustained IDN procurement centralization, with deviation risk concentrated in reagent supply disruptions and EU notified body capacity constraints. Practitioners should keep alternative scenarios live as high-sensitivity troponin assay validation requirements and cloud-connectivity mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Cardiac Catheterization Market
Cardiology Equipment
Europe ECG Electrodes Market
Cardiology Equipment
Europe Cardiac Arrhythmia Monitoring Devices Market
Cardiology Equipment
Medical Smart Stethoscopes Market
Cardiology Equipment
Europe Electrophysiology Market
Cardiology Equipment
Global Cardiology Electrodes Market
Cardiology Equipment
Global Stethoscope Market
Cardiology Equipment
Global Coronary Artery Bypass Grafting Market
Cardiology Equipment
Heart Lung Machine Market
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Global Extra Corporeal Membrane Oxygenation (ECMO) System Market
Cardiology Equipment
Intracardiac Echocardiography (ICE) Market
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Cardiac Rhythm Management Market
Cardiology Equipment
Intracardiac Imaging Market