
 Infusion Toxicology Services Market | 2026-2036
Infusion Toxicology Services Market Size, Share, and Industry Trends Forecast 2026-2036
Infusion Toxicology Services Market Analytics
Buyer consolidation among mid-sized biotechnology firms is repositioning contract demand toward full-service toxicology providers. Charles River Laboratories leverages integrated discovery-to-safety workflows to capture multi-year client commitments. WuXi AppTec anchors Asia-Pacific study execution through its Shanghai and Suzhou facilities. Eurofins Scientific differentiates via specialized large-molecule infusion capabilities across European and North American sites.
Infusion toxicology services encompass repeated-dose safety evaluation of compounds administered through intravenous, subcutaneous, or intrathecal delivery routes, typically spanning 14-day to 26-week study durations with hematology, clinical chemistry, and histopathology endpoints. These services determine maximum tolerated doses, identify target organ toxicity, and generate pharmacokinetic profiles required for investigational new drug submissions. In-vivo testing commands the largest revenue share due to regulatory mandates for whole-organism safety data, while toxicokinetics represents the fastest-expanding segment as sponsors integrate real-time exposure-response modeling into early-phase decisions. Chromatography-based test methodology retains mature, high-volume status, whereas mass spectrometry applications are displacing older detection platforms for biologic drug metabolism studies.
FDA guidelines on immunogenicity risk assessment and EMA REACH-aligned chemical safety protocols shape study design requirements and facility qualification standards across jurisdictions. The EPA's Good Laboratory Practice enforcement and OECD Test Guideline harmonization further constrain market entry for non-accredited laboratories. Stakeholders must monitor evolving large-molecule guidance documents from multiple regulators to anticipate protocol changes that will alter service pricing and capacity allocation.
Market Dynamics
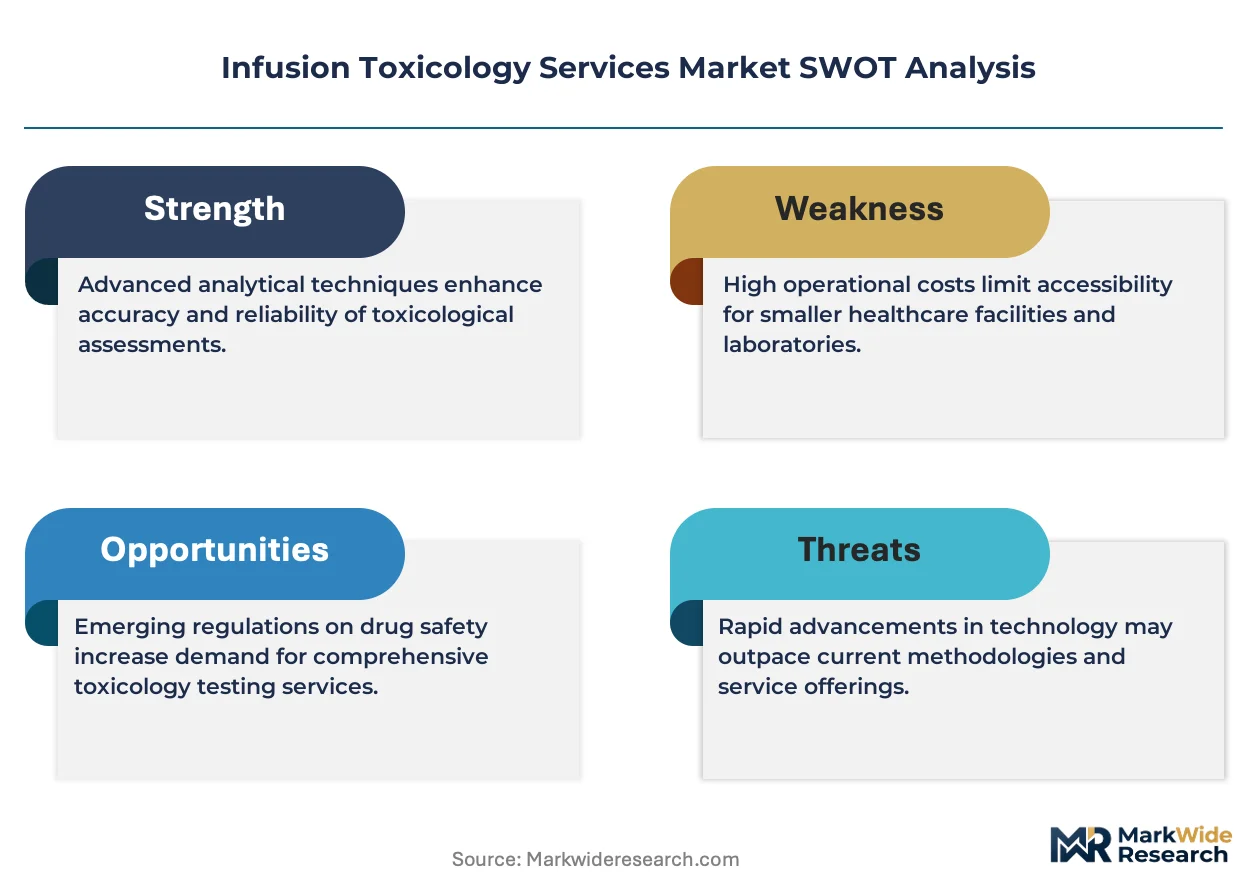
Pharmaceutical outsourcing concentration is compressing contract timelines and forcing toxicology providers to absorb protocol complexity without proportional pricing power. FDA large-molecule guidance updates and EMA REACH-aligned chemical safety mandates are layering compliance costs onto fixed-fee study structures.
Growth Catalysts
- EMA revised non-clinical testing requirements:European biotech sponsors must commission extended-duration infusion studies, expanding addressable study volume for contract research organizations with GLP-certified rodent and non-rodent facilities.
- Biologics pipeline expansion:Monoclonal antibody and cell therapy developers require species-specific immunogenicity assessment, creating dedicated demand for large-molecule toxicokinetic capabilities.
- Boston-San Diego corridor concentration:Geographic clustering of venture-backed biotechnology firms generates localized demand density that supports specialized toxicology infrastructure investment.
Market Restraints
- Primates supply concentration:NHP import restrictions and breeding facility scarcity in Southeast Asia create study-start delays and cost volatility for 26-week carcinogenicity assessments.
- FDA GLP enforcement escalation:Enhanced facility inspection frequency and data integrity scrutiny extend qualification timelines for new laboratory entrants.
- In silico toxicology substitution:Computational exposure-response modeling and organ-on-chip platforms capture early-phase screening volume that previously flowed to in vivo contract studies.
Strategic Opportunities
- China NMPA convergence:Domestic biopharmaceutical registration requirements are aligning with ICH safety standards, opening demand for Western toxicology providers with bilingual protocol capabilities and local affiliate partnerships.
- Real-time bioanalytical integration:Mass spectrometry and chromatography convergence enables continuous pharmacokinetic monitoring during infusion, differentiating full-service providers from discrete testing laboratories.
- Japan PMDA consultation pathways:Pre-IND scientific advice mechanisms reward toxicology sponsors with documented regulatory dialogue, creating premium positioning for CROs with Tokyo-based liaison capabilities.
Industry Challenges
- Pathologist specialization scarcity:Board-certified veterinary pathologists capable of large-molecule histopathology interpretation command compensation premiums that compress study margins.
- Multi-site data harmonization:Sponsors demand seamless cross-facility protocol execution, requiring toxicology providers to standardize operating procedures across geographically dispersed GLP laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infusion Toxicology Services Market |
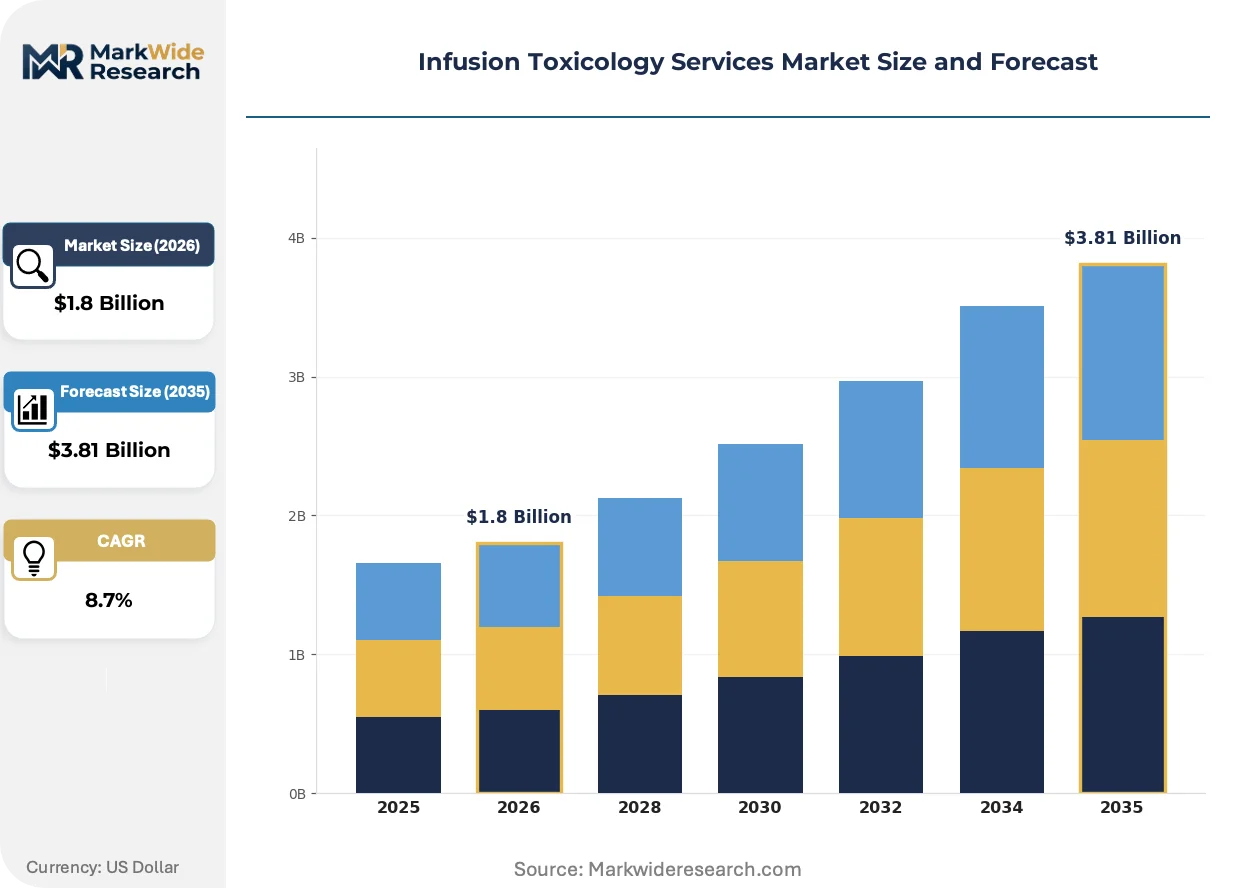
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: In-Vitro Testing, In-Vivo Testing, Toxicokinetics, Risk Assessment End User: Pharmaceutical Companies, Research Institutions, Contract Research Organizations, Biotechnology Firms Test Methodology: Chromatography, Mass Spectrometry, Immunoassays, Histopathology Application Area: Drug Development, Chemical Safety, Environmental Testing, Clinical Trials |
| Companies Covered | Eurofins Scientific, SGS, Charles River Laboratories, Evotec, Merck, Labcorp, WuXi AppTec, Abbott Toxicology, Envigo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infusion Toxicology Services Market Evolving Landscape
Digital biomarker capture and automated histopathology are compressing study turnaround timelines while elevating data granularity expectations. Regulatory agencies are incorporating these capabilities into guidance documents, reshaping facility capital allocation priorities.
Mass spectrometry-based toxicokinetic analysis is integrating real-time exposure-response modeling into early-phase safety decisions. Biologics developers are adopting these platforms to refine dose-escalation protocols before committing to extended-duration studies. The technology is integrating pharmacokinetic and immunogenicity endpoints into unified analytical workflows, reducing discrete bioanalytical handoffs.
EMA REACH-aligned chemical safety protocols are mandating extended analytical detection limits for extractables and leachables in infusion device materials. Medical device and combination product sponsors must commission specialized compatibility studies alongside traditional toxicology assessments. European CROs with polymer chemistry expertise are capturing this adjacent service volume.
Biotechnology sponsors are consolidating vendor relationships around full-service toxicology providers capable of seamless discovery-to-safety handoffs. Discrete testing laboratories without integrated in vivo and bioanalytical capabilities are losing multi-year framework agreements. This concentration is most visible in the United States, where mid-sized biotech firms prioritize single-accountability vendor structures over fragmented specialist procurement.
Infusion Toxicology Services Market Segmentation
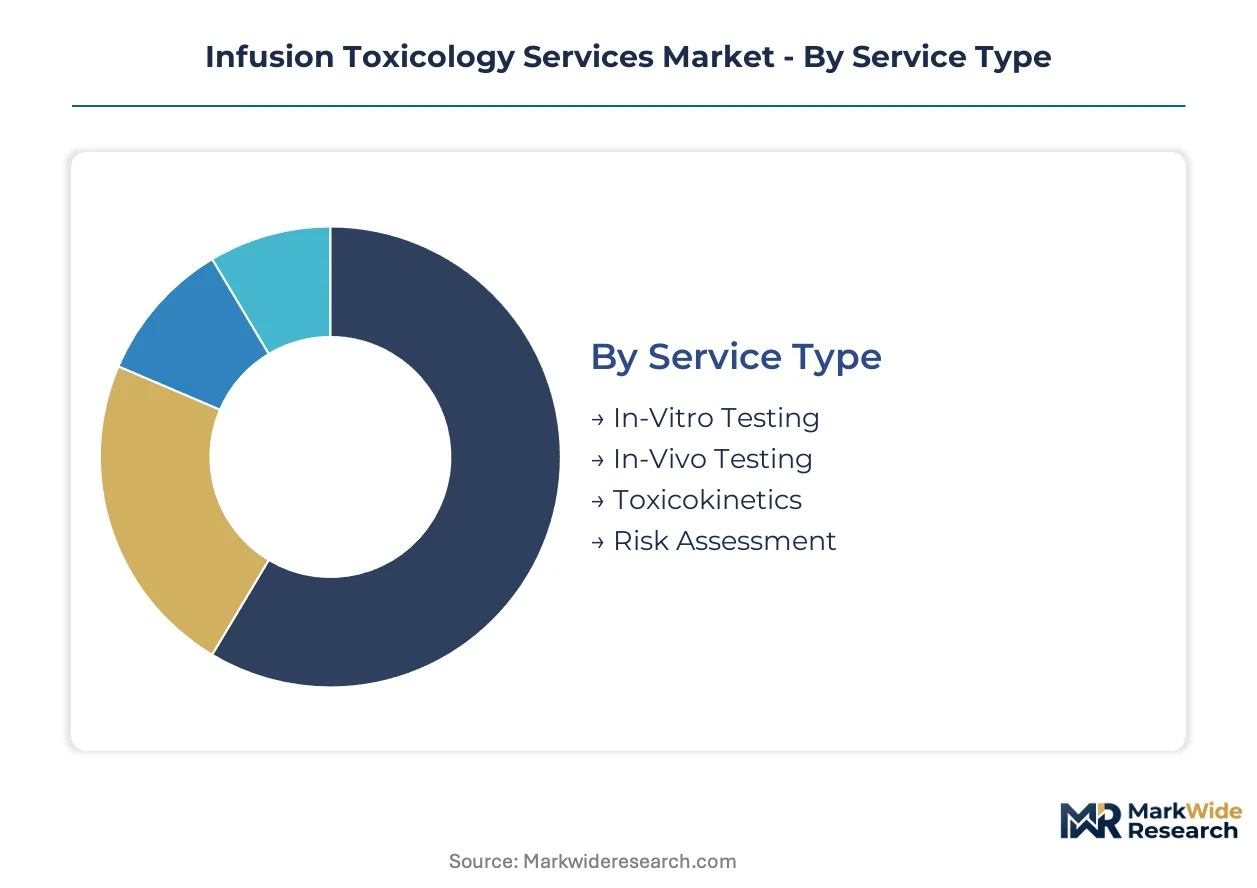
Infusion toxicology services fragment across service delivery modes, sponsor types, analytical platforms, and regulatory applications. Each segmentation axis reveals distinct capacity requirements and margin structures that shape provider specialization strategies.
Service Type:
Replacement cycles accelerate as sponsors retire legacy study designs in favor of integrated safety packages that compress IND timelines.
- In-Vivo Testing:Whole-organism studies in rodent and non-rodent species generate the regulatory-mandated safety data required for FDA investigational new drug submissions. Pharmaceutical sponsors in the United States concentrate procurement here, driven by agency insistence on histopathological and clinical chemistry endpoints from intact biological systems.
- Toxicokinetics:Real-time exposure-response modeling integrates pharmacokinetic profiling into early-phase safety decisions, enabling dose-escalation refinement before extended-duration study commitment. Biotechnology firms in Boston and San Diego clusters are displacing discrete bioanalytical handoffs with continuous monitoring platforms.
- In-Vitro Testing:Cell-based assays and organ-on-chip platforms capture screening-phase volume for cytotoxicity and genotoxicity assessment.
- Risk Assessment:Regulatory documentation packages synthesize study data into agency-ready submission formats.
Volume placements concentrate in In-Vivo Testing; the faster expansion belongs to Toxicokinetics.
End User:
Cost-tier stratification separates large pharmaceutical sponsors with captive toxicology infrastructure from outsourcing-dependent mid-market players.
- Pharmaceutical Companies:Multinational drug developers maintain hybrid models combining internal GLP facilities with contracted overflow capacity for specialized large-molecule studies. Their procurement concentrates on full-service providers capable of seamless discovery-to-safety handoffs.
- Biotechnology Firms:Venture-backed developers lack internal toxicology infrastructure and depend entirely on contract research organizations for IND-enabling safety packages. Geographic clustering in Massachusetts and California generates localized demand density that supports specialized facility investment.
- Contract Research Organizations:Toxicology providers themselves subcontract discrete analytical services to specialized bioanalytical laboratories.
- Research Institutions:Academic centers commission exploratory toxicology studies with reduced regulatory documentation requirements.
Revenue concentration sits with Pharmaceutical Companies; Biotechnology Firms are climbing the fastest as pipeline expansion outpaces internal capacity builds.
Test Methodology:
Technology maturity curves displace older detection platforms as biologic drug metabolism studies demand higher analytical resolution.
- Chromatography:High-performance liquid chromatography and gas chromatography retain mature, high-volume status for routine small-molecule quantification and metabolite identification. Established protocols and validated equipment sustain cost-efficient throughput for standard safety assessments.
- Mass Spectrometry:LC-MS/MS and high-resolution mass spectrometry platforms capture biologic drug metabolism studies requiring femtomolar detection limits and complex biotransformation characterization. Large-molecule developers in the United States and Europe are accelerating displacement of older detection platforms.
- Immunoassays:ELISA and electrochemiluminescence methods support immunogenicity screening for antibody therapeutics.
- Histopathology:Tissue section analysis and digital pathology deliver target organ toxicity identification required by FDA guidance.
Chromatography commands the largest installed base; Mass Spectrometry is gaining share fastest as biologics pipelines expand.
Application Area:
Margin structures diverge between commoditized environmental screening and premium-priced drug development services with regulatory documentation requirements.
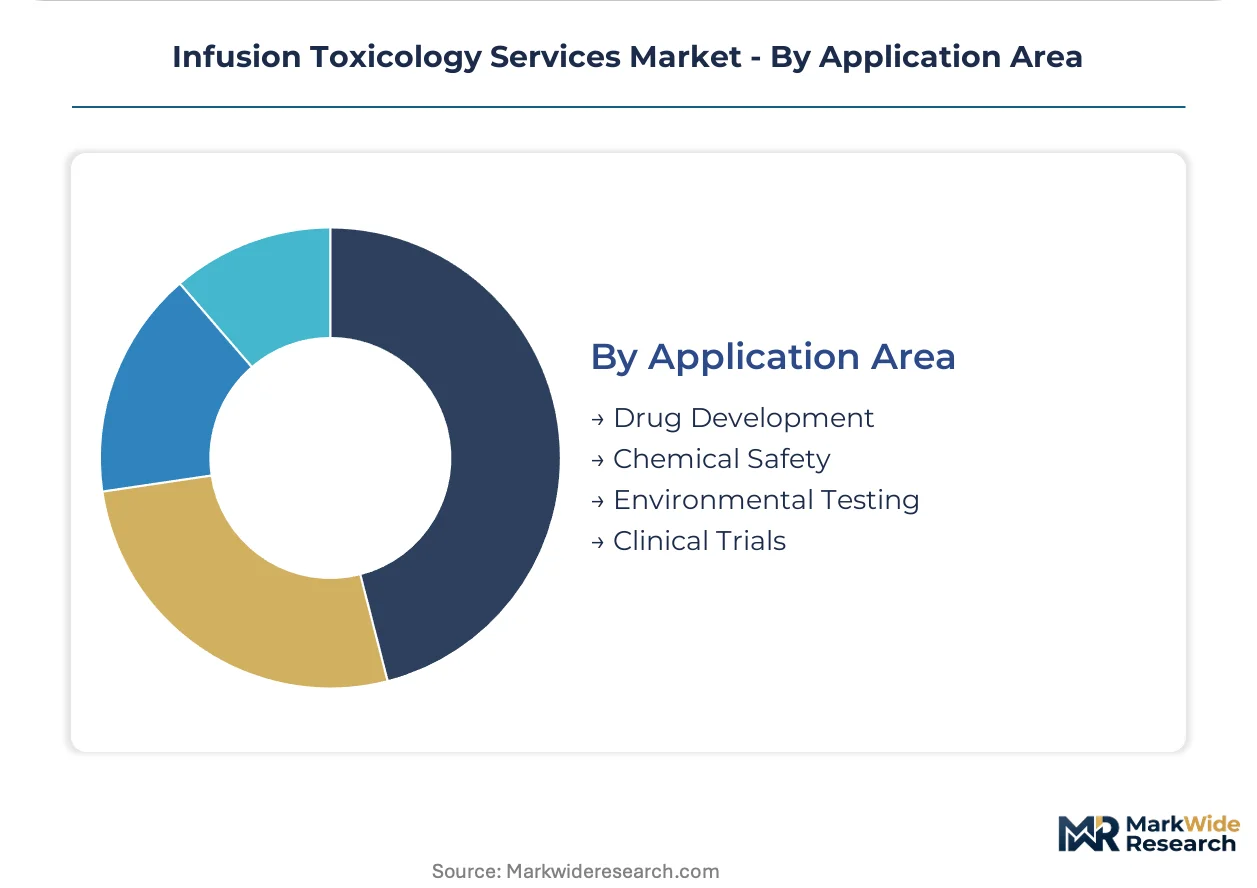
- Drug Development:IND-enabling and NDA-supporting toxicology studies command premium pricing due to GLP compliance burdens and submission-critical data integrity requirements. Sponsors in the United States allocate the largest procurement budgets here, driven by FDA's enhanced guidance on large-molecule safety assessment.
- Chemical Safety:REACH-aligned hazard characterization and industrial chemical registration studies generate steady European demand. ECHA mandates for extended analytical detection limits are expanding service scope into extractables and leachables assessment.
- Clinical Trials:Phase-appropriate safety monitoring supports adaptive trial designs with real-time dose modifications.
- Environmental Testing:Ecotoxicology and environmental fate studies serve agrochemical and industrial chemical registrants.
Drug Development absorbs the dominant share of contract value; Chemical Safety is expanding most quickly as European regulatory mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical outsourcing concentrates study demand in jurisdictions with mature GLP infrastructure and dense biotechnology clusters. Regulatory convergence around ICH safety standards is expanding addressable contract volume beyond traditional Western markets.
United States
Boston and San Diego biotech corridors generate localized demand density for extended-duration infusion studies. FDA enhanced guidance on large-molecule safety assessment tightens compliance standards for IND-enabling packages. Massachusetts and California venture-backed firms drive procurement toward full-service toxicology providers with integrated discovery-to-safety workflows.
Germany
REACH-aligned chemical safety mandates expand service scope into extractables and leachables assessment for medical device sponsors. ECHA requirements for extended analytical detection limits shape facility qualification standards. The Rhine-Main and Munich metropolitan areas concentrate polymer chemistry expertise for adjacent compatibility studies.
China
NMPA convergence with ICH safety standards opens demand for bilingual protocol capabilities among domestic biopharmaceutical registrants. Shanghai and Suzhou facilities anchor Asia-Pacific study execution for multinational sponsors. Yangtze River Delta biopharmaceutical manufacturing clusters drive investment in GLP-certified rodent and non-rodent capacity.
United Kingdom
EMA revised non-clinical testing requirements position British CROs to capture extended-duration study volume from European biotechnology sponsors. MHRA alignment with post-Brexit regulatory frameworks maintains access to EU submission pathways. The Golden Triangle research corridor sustains specialized toxicology infrastructure investment.
Japan
PMDA consultation pathways reward toxicology sponsors with documented regulatory dialogue prior to IND submission. Tokyo-based liaison capabilities differentiate premium-positioned CROs in the Asia-Pacific procurement landscape. Osaka and Kansai pharmaceutical manufacturing clusters generate steady demand for toxicokinetic integration services.
Infusion Toxicology Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized large-molecule capabilities and real-time bioanalytical integration. The vendor base stratifies across full-service integrated providers, regional specialists with geographic density, and discrete testing laboratories facing consolidation pressure. Three archetypes dominate: multinational CROs with discovery-to-safety workflows, Asia-Pacific execution specialists with bilingual protocol capabilities, and European polymer chemistry experts capturing adjacent medical device testing. Competitive moves center on multi-year client commitment capture through integrated service packaging and GLP facility capacity expansion in high-demand corridors.
Within the full-service tier, Charles River Laboratories exemplifies integrated discovery-to-safety positioning, while WuXi AppTec anchors Asia-Pacific execution capabilities through Shanghai and Suzhou infrastructure. Eurofins Scientific occupies a specialization-focused position across European and North American sites with large-molecule infusion capabilities. These three entities represent distinct strategic archetypes rather than direct substitutes, with procurement patterns reflecting sponsor preferences for single-accountability vendor structures versus geographically distributed execution.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS |
| Charles River Laboratories |
| Evotec |
| Merck |
| Labcorp |
| WuXi AppTec |
| Abbott Toxicology |
| Envigo |
| Others |
Value Network & Pricing Analysis
GLP certification tier divergence separates premium-positioned toxicology providers from commodity testing laboratories, with FDA-compliant facilities commanding pricing power that reflects both compliance investment recovery and captive NHP supply arrangements. This bifurcation manifests in supply chain configurations where accredited laboratories integrate backward into primate breeding partnerships while non-certified competitors remain dependent on spot-market animal procurement.
Pricing Analysis
Volume placements concentrate in mid-tier contract structures while margins accrue to providers with integrated toxicokinetic capabilities. Project-based pricing dominates IND-enabling studies, with differentiation driven by FDA audit history and large-molecule specialization. Pricing pressure stems from sponsor consolidation around full-service providers, compressing margins for discrete testing laboratories. Biotechnology firms exhibit highest price sensitivity due to venture-capital funding constraints, whereas multinational pharmaceutical sponsors prioritize data integrity over cost minimization.
Supply Chain Analysis
Direct-to-sponsor channels handle multinational pharmaceutical procurement, while regional distributors serve mid-sized biotechnology clusters. Supply concentration rests on United States, China, and Germany for GLP-certified facility infrastructure. Critical inputs span purpose-bred non-human primates, specialized mass spectrometry platforms, and board-certified veterinary pathologists. Single-source vulnerability concentrates in Southeast Asian NHP breeding facilities, with import restrictions creating study-start delays. Distribution runs through multi-year framework agreements rather than transactional spot contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA GLP enforcement escalation has erected a compliance moat that rewards incumbent investment in facility qualification while raising barriers for new laboratory entrants. This cost-of-compliance dynamic concentrates market power among providers with documented regulatory dialogue histories.
For Market Incumbents: Deploy real-time bioanalytical integration as the priority capability investment. Consolidate position by acquiring specialized toxicokinetic laboratories in Boston and San Diego corridors to capture biotechnology sponsor consolidation. Capture multi-year client commitments through discovery-to-safety workflow packaging that eliminates discrete vendor handoffs.
For New Entrants and Emerging Players: Digital pathology partnerships offer the lowest-friction entry vector for mid-market positioning. Target European chemical safety services as the most penetrable segment given ECHA REACH-aligned mandate expansion. Pursue polymer chemistry expertise acquisition to capture adjacent medical device compatibility study volume.
For Investors and Strategic Acquirers: Re-rating potential sits with Asia-Pacific execution specialists given NMPA-ICH convergence catalyst. Long-term viability favors providers with bilingual protocol capabilities and Shanghai-based GLP infrastructure. Monitor Japan PMDA consultation pathway documentation as the signal indicating premium regulatory positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| GLP Facility Capacity Expansion | Additional rodent and non-rodent capacity in Massachusetts and California captures biotechnology cluster demand. |
| Real-Time Bioanalytical Integration | Mass spectrometry convergence during infusion studies differentiates full-service providers from discrete laboratories. |
| NHP Breeding Partnership | Captive primate supply agreements mitigate Southeast Asian import restriction risks for extended-duration studies. |
| Regulatory Liaison Investment | Tokyo-based PMDA consultation capabilities unlock premium positioning in Asia-Pacific procurement decisions. |
| Polymer Chemistry Acquisition | REACH-aligned extractables and leachables expertise captures adjacent medical device testing volume. |
Research Methodology
FDA guidance documents, EMA submission databases, and OECD Test Guidelines formed the secondary backbone for protocol requirement mapping. Primary interviews with drug development executives, regulatory affairs leads, toxicology study directors, and CRO procurement managers validated service demand patterns. Bottom-up and top-down triangulation reconciled facility capacity data with sponsor outsourcing survey responses.
Bottom-up modeling aggregated individual study-type pricing across service delivery modes, while top-down analysis cross-checked against pharmaceutical R&D expenditure trends. Segmentation dimensions encompassed service type, end-user category, analytical platform, and regional regulatory cluster. CAGRs derived from sponsor pipeline forecasts and GLP facility expansion announcements. Forecast inputs incorporated biologics pipeline expansion rates and NHP supply constraint indicators.
The model holds under sustained FDA large-molecule guidance enforcement; deviation in primate import policy or in silico substitution acceleration would shift capacity utilization assumptions. Forecasts reflect base-case regulatory convergence and sponsor outsourcing propensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
India GMP Testing Service Market
Testing Services
United States Esoteric Testing Market
Testing Services
Pharmaceutical Dosage Form Testing Systems Market
Testing Services
Global Vitamin D Testing Market
Testing Services
Adiponectin Testing Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
Europe Endotoxin and Pyrogen Testing Market
Testing Services
Toxicology Testing Services Market
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
Breath Biopsy Testing Market
Testing Services
Viral Vector Integrity and Potency Analytics Test Instruments Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
Drug Screening Laboratory Service Market
Testing Services
Allergy Skin Test Market
Testing Services
Global Urinalysis Test Market
Testing Services
Human Papilloma Virus Testing Market