
 Germany Testing, Inspection and Certification Market | 2026-2036
Germany Testing, Inspection and Certification Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Testing, Inspection and Certification Market Insights
Multi-source outsourcing of conformity assessment is broadening as German manufacturers diversify beyond captive laboratories. TÜV SÜD AG leverages its Munich headquarters to dominate automotive homologation workflows. DEKRA SE anchors commercial vehicle inspection through dense station networks across Bavaria and North Rhine-Westphalia. Bureau Veritas SA competes in industrial asset integrity, positioning its Düsseldorf hub near chemical plant clusters.
Testing, Inspection and Certification encompasses technical verification of product compliance against harmonized standards through sampling, measurement, and audit protocols; laboratories employ spectrometry, tensile testing, and electromagnetic compatibility chambers to generate traceable evidence for regulatory acceptance. Quality Control services command sustained premiums where automotive supply chains require zero-defect documentation for IATF 16949 adherence. Safety Testing experiences fastest expansion as EU Machinery Regulation updates force recertification of legacy industrial equipment. Non-Destructive Testing occupies critical margin pools in aerospace component lifing programs where radiographic and ultrasonic methods replace destructive sampling.
KBA enforces UN ECE type-approval for vehicle systems entering German registration, while REACH compliance obligations administered by ECHA mandate chemical substance testing for imported components. The EU AI Act introduces conformity requirements for machine-learning-enabled inspection equipment, redirecting provider R&D toward algorithmic audit capabilities. Stakeholders must monitor how CSRD sustainability reporting obligations extend verification demands from products to entire supply chain footprints.
Market Dynamics
KBA's stricter type-approval enforcement for electric powertrains is forcing automotive OEMs to outsource conformity assessment, restructuring how testing capacity is procured across Baden-Württemberg's supplier corridor.
Growth Catalysts
- EU AI Act compliance:Machine-learning-enabled inspection equipment now requires algorithmic audit capabilities, redirecting provider R&D budgets toward automated conformity assessment tools.
- REACH substance testing:ECHA mandates chemical verification for imported components, expanding laboratory throughput for automotive and industrial supply chains.
- Baden-Württemberg cluster effects:Dense supplier concentration in Stuttgart-Karlsruhe corridor creates localized demand spikes for on-site testing services.
Market Restraints
- Accreditation bottlenecks:DAkkS laboratory recognition timelines stretch 18-24 months, constraining new entrant capacity expansion.
- Skilled technician scarcity:Radiographic and ultrasonic NDT certification requires 3,000+ supervised hours, limiting workforce scalability.
- Equipment capex intensity:Electromagnetic compatibility chambers and spectrometry suites demand EUR 2-5 million per installation, raising barrier to entry.
Strategic Opportunities
- CSRD supply chain verification:Corporate Sustainability Reporting Directive extends audit mandates from products to entire value chain footprints, opening adjacent service lines.
- Bavaria commercial vehicle inspection:Underpenetrated heavy-truck testing corridors between Munich and Nuremberg offer station network expansion potential.
- Digital twin convergence:Physics-based simulation paired with physical testing compresses homologation cycles for powertrain developers.
Industry Challenges
- IATF 16949 documentation burdens:Automotive suppliers face audit fatigue from zero-defect traceability requirements across multi-tier supply chains.
- Legacy equipment recertification:EU Machinery Regulation updates force retesting of installed industrial assets, straining laboratory scheduling capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Testing, Inspection and Certification Market |
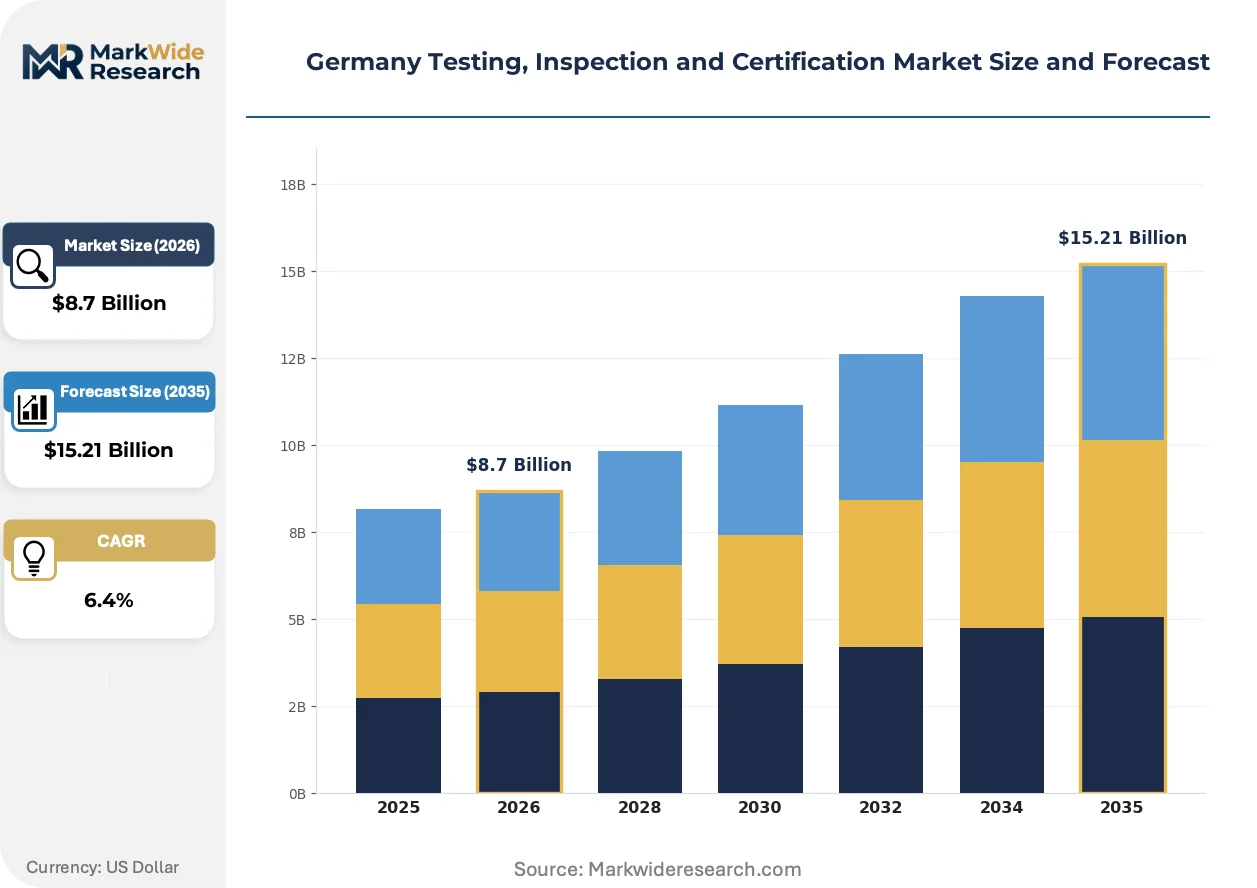
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Quality Control, Product Certification, Safety Testing, Environmental Testing Industry Vertical: Manufacturing, Automotive, Aerospace, Electronics Technology: Non-Destructive Testing, Radiographic Testing, Optical Testing, Chemical Analysis End User: OEMs, Service Providers, Research Institutions, Government Agencies |
| Companies Covered | TÜV SÜD AG, TÜV Rheinland AG, DEKRA SE, TÜV Nord Group, SGS Germany GmbH, Bureau Veritas SA, Intertek Group plc, Eurofins Scientific SE, DNV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Testing, Inspection and Certification Market Trends and Innovations
Digitalization of conformity assessment workflows is compressing homologation timelines while regulatory scope expansion forces providers to build algorithmic audit competencies alongside physical testing infrastructure.
Automated optical inspection systems equipped with machine vision and deep learning classification are rewriting quality control economics in automotive stamping and electronics assembly. Tier-1 suppliers in Stuttgart and Wolfsburg are deploying these systems at 40% of new lines. The technology is compressing defect detection cycles from hours to seconds, reducing destructive sampling volumes.
REACH authorization lists now cover 59 substance categories, forcing chemical testing laboratories to expand chromatography and mass spectrometry capacity for SVHC screening. Industrial coating and polymer compound suppliers face the steepest compliance cost escalations. German importers are shifting sourcing verification upstream to Asian material producers to avoid border detention.
Certification-driven procurement now dominates capital equipment purchasing in Saxony's semiconductor fabrication expansion. Buyers require pre-integrated CE marking documentation and ISO 17025 traceability from equipment vendors before contract signature. This behavior is most pronounced in Dresden's wafer processing cluster, where tool qualification timelines directly determine fab ramp schedules.
Germany Testing, Inspection and Certification Market Segmentation
German TIC providers structure service portfolios around distinct regulatory approval pathways. Each segment carries unique accreditation requirements from DAkkS, KBA, or ECHA that determine pricing power and customer stickiness across Baden-Württemberg's industrial corridor.
Service Type:
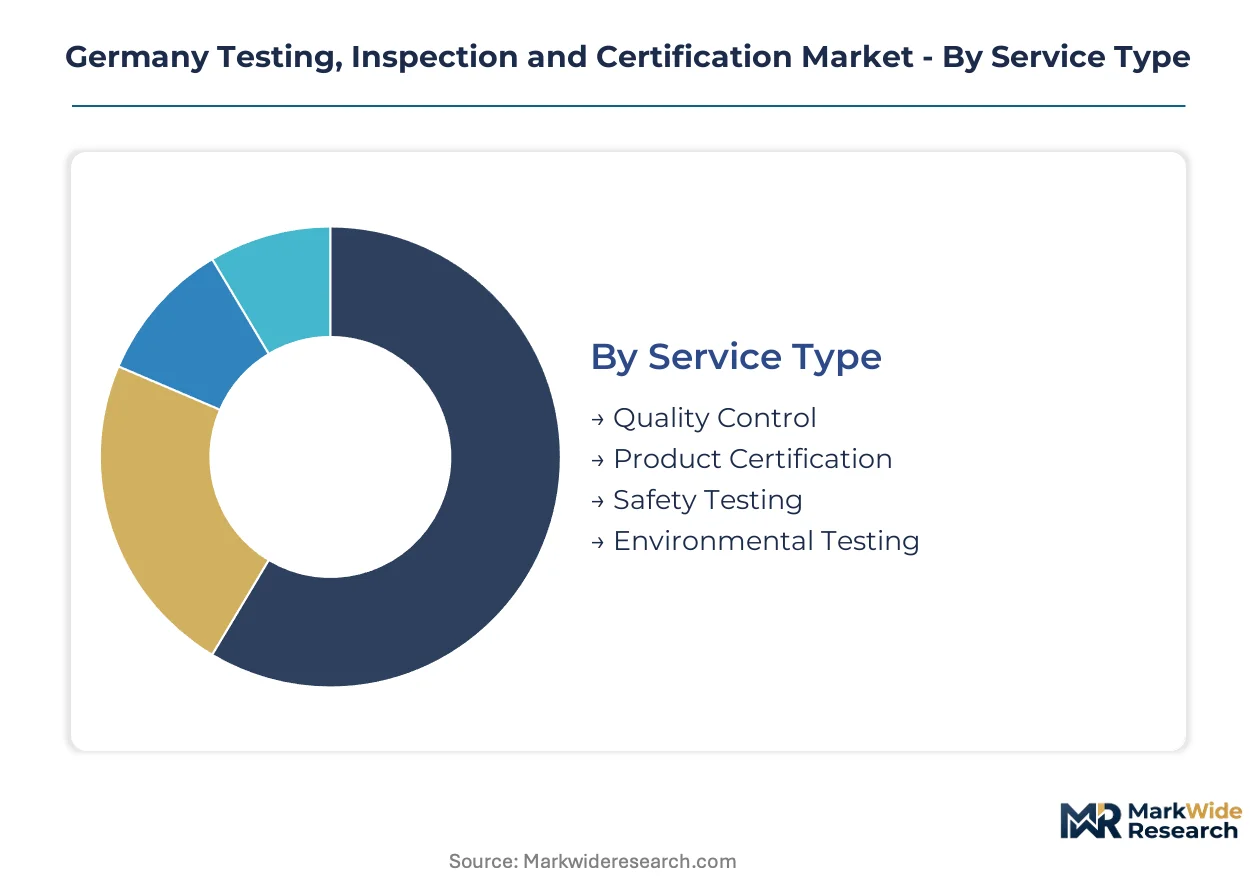
Quality Control commands KBA documentation for automotive homologation, while Safety Testing requires EU Machinery Regulation recertification for legacy industrial assets.
- Quality Control:Zero-defect traceability protocols for IATF 16949 adherence dominate Stuttgart supplier networks. Tier-1 automotive manufacturers in Wolfsburg and Munich require batch-level documentation for every component shipment.
- Safety Testing:Electromagnetic compatibility chambers and mechanical stress rigs verify machinery compliance under updated EU directives. Laboratory scheduling bottlenecks are intensifying as installed base recertification deadlines approach.
- Product Certification:CE marking documentation bundles accelerate capital equipment procurement in Saxony's semiconductor fabrication expansion.
- Environmental Testing:REACH SVHC screening and emissions verification support chemical plant clusters near Düsseldorf and Ludwigshafen.
Quality Control sits at the top of the volume ranking, with Safety Testing climbing the fastest.
Industry Vertical:
Cost tier differentiation separates high-volume automotive workflows from premium-margin aerospace programs requiring radiographic technician certification.
- Automotive:Electric powertrain homologation under UN ECE type-approval protocols consumes the largest share of outsourced testing capacity. KBA enforcement is restructuring procurement relationships across Stuttgart-Karlsruhe supplier corridors.
- Manufacturing:Industrial machinery recertification drives sustained demand for mechanical safety and electromagnetic compatibility verification. Legacy equipment updates under EU Machinery Regulation strain available laboratory slots.
- Aerospace:Component lifing programs in Bavaria require ultrasonic and radiographic NDT methods that replace destructive sampling.
- Electronics:Automated optical inspection with machine vision compresses defect detection cycles in Dresden wafer processing clusters.
Automotive dominates revenue concentration, though Aerospace delivers the steepest margin premiums.
Technology:
Equipment capex intensity separates established laboratories from new entrants, with electromagnetic compatibility chambers demanding EUR 2-5 million per installation.
- Non-Destructive Testing:Ultrasonic and radiographic methods support aerospace component lifing without destructive sampling. Technician certification requires 3,000-plus supervised hours, constraining workforce scalability.
- Chemical Analysis:Chromatography and mass spectrometry capacity expands for REACH SVHC screening across 59 substance categories. Industrial coating suppliers face the steepest compliance cost escalations.
- Radiographic Testing:X-ray and gamma-ray inspection protocols verify weld integrity in pressure equipment and pipeline infrastructure.
- Optical Testing:Machine vision systems with deep learning classification rewrite quality control economics in automotive stamping operations.
Non-Destructive Testing anchors the highest equipment investment requirements, while Optical Testing is gaining share fastest through automation.
End User:
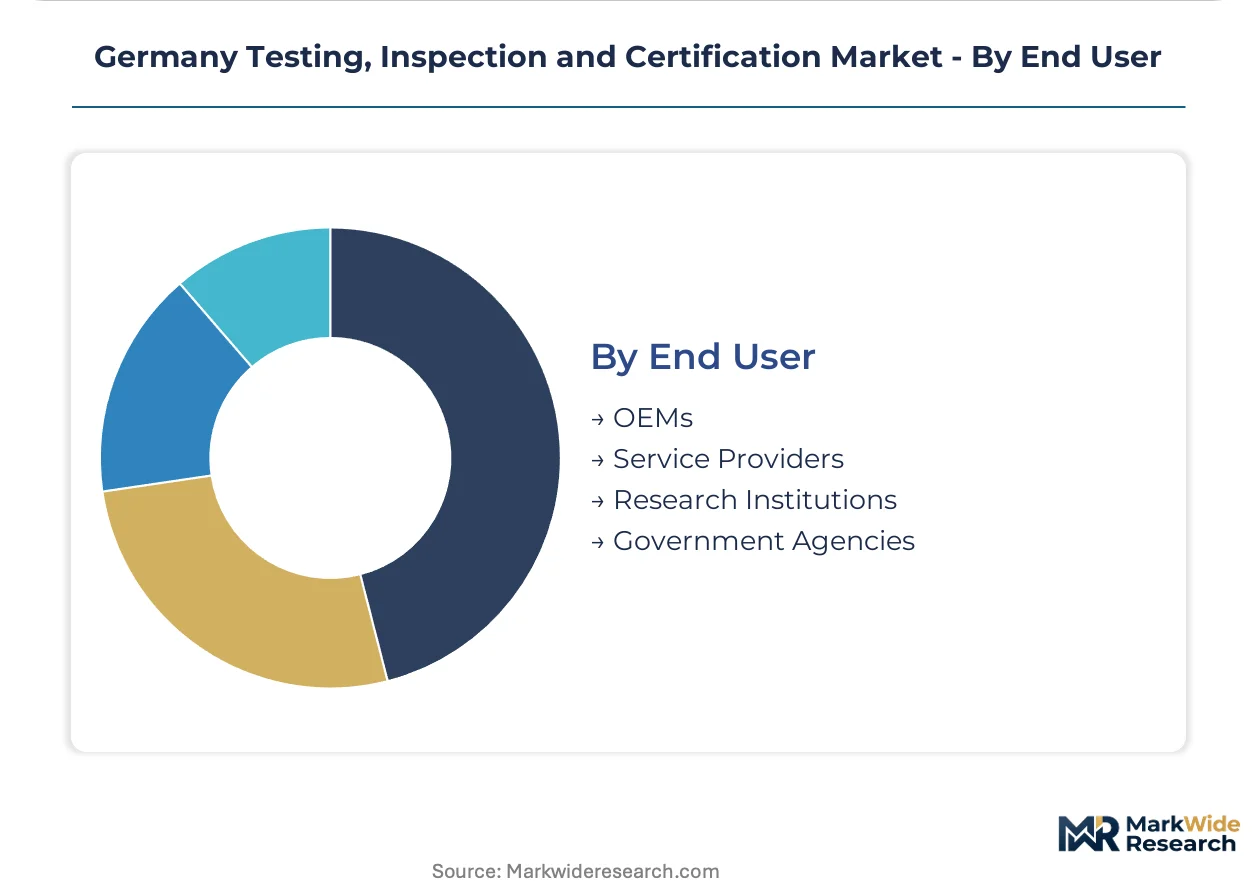
Procurement authority concentration varies sharply, with OEMs bundling multi-year testing contracts while government agencies enforce mandatory inspection regimes.
- OEMs:German automotive manufacturers outsource electric powertrain certification as KBA tightens type-approval protocols. Multi-tier supply chain documentation requirements extend audit mandates to second and third-tier suppliers.
- Government Agencies:KBA vehicle registration enforcement and ECHA chemical compliance administration create non-discretionary demand for accredited laboratory services.
- Service Providers:Commercial vehicle inspection station networks across Bavaria and North Rhine-Westphalia require recurring equipment calibration and auditor certification.
- Research Institutions:Fraunhofer and Max Planck facilities drive pre-competitive testing for emerging materials and manufacturing processes.
OEMs command the largest contract values, with Government Agencies providing the most predictable recurring revenue base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's industrial corridor generates the densest concentration of testing demand, with Stuttgart-Karlsruhe supplier networks driving localized procurement patterns for automotive and machinery certification.
Bavaria
Commercial vehicle inspection networks anchor revenue stability across Munich-Nuremberg transport corridors. KBA enforces mandatory periodic technical inspections for heavy trucks, sustaining recurring revenue for station operators. Munich-headquartered providers dominate homologation workflows for electric powertrain developers.
North Rhine-Westphalia
Chemical plant clusters near Düsseldorf and Ludwigshafen generate sustained demand for REACH compliance verification and emissions testing. ECHA substance screening mandates expand laboratory throughput for industrial coating suppliers. Dense manufacturing infrastructure supports multi-site audit contracts.
Lower Saxony
Volkswagen's Wolfsburg operations drive zero-defect traceability requirements across tiered automotive supply chains. IATF 16949 documentation burdens concentrate inspection demand at component shipment points. Supplier quality engineers maintain permanent on-site testing presence.
Hesse
Frankfurt's financial and logistics hub sustains certification demand for pharmaceutical cold chain validation and medical device conformity. EMA regulatory convergence with FDA standards drives dual-approval testing protocols. Regional laboratories specialize in biologics stability studies.
Saxony
Dresden's semiconductor fabrication expansion forces certification-driven procurement for capital equipment. CE marking documentation and ISO 17025 traceability become contract prerequisites before tool installation. Wafer processing clusters compress qualification timelines through pre-integrated testing bundles.
Germany Testing, Inspection and Certification Market Competitive Landscape
Global majors compete with regional champions across accreditation depth and geographic proximity to industrial clusters. TÜV-affiliated entities capture automotive homologation through KBA-recognized type-approval authority, while diversified international groups compete on multi-sector portfolio breadth. Three archetypes dominate: captive automotive specialists, diversified industrial generalists, and niche laboratory operators. Consolidation pressures intensify through DAkkS accreditation bottlenecks and equipment capex barriers.
Within the automotive-specialist tier, TÜV SÜD AG and DEKRA SE exemplify divergent scale strategies. TÜV SÜD occupies a position anchored in Munich's industrial policy ecosystem, representing the integrated technical services model. DEKRA SE sits within the dense station-network archetype, with geographic footprint density across Bavaria and North Rhine-Westphalia determining competitive position. Bureau Veritas SA exemplifies the diversified international group model, with Düsseldorf proximity to chemical industry clusters supporting industrial asset integrity positioning.
| Leading Market Players |
|---|
| TÜV SÜD AG |
| TÜV Rheinland AG |
| DEKRA SE |
| TÜV Nord Group |
| SGS Germany GmbH |
| Bureau Veritas SA |
| Intertek Group plc |
| Eurofins Scientific SE |
| DNV |
| Others |
Pricing and Supply Chain Analysis
German automotive OEMs and tier-1 suppliers concentrate procurement authority through multi-year framework agreements, anchoring contract-based pricing models that bundle testing volume with accreditation depth.
Pricing Analysis
Equipment depreciation and technician certification costs pass through to client rates, with electromagnetic compatibility chambers and radiographic NDT suites commanding premium tariffs. Pricing stratifies across DAkkS-accredited laboratories, KBA-recognized type-approval authorities, and non-accredited quality control providers. Cost compression in standard environmental testing reflects automation of optical inspection workflows. Small-batch automotive suppliers exhibit highest price sensitivity, while aerospace OEMs prioritize technician credential depth over unit cost.
Supply Chain Analysis
Calibration equipment refurbishment and recertification flows sustain secondary market activity for spectrometry and tensile testing assets. Equipment manufacturing concentrates in Germany, Switzerland, and the United States. Supply chains draw from specialized sensor producers in Japan, vacuum chamber fabricators in Italy, and software-defined instrumentation developers in the United States. Single-source vulnerability persists for gamma-ray source suppliers. Distribution runs through direct manufacturer relationships with laboratory networks, bypassing distributor markups for capital-intensive installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German TIC functions as a stable compounder where regulatory scope expansion under EU directives generates recurring revenue visibility.
For Market Incumbents: Deploy algorithmic audit capability investments to capture EU AI Act compliance workflows before specialized software entrants fragment the segment. Consolidate regional laboratory networks in Bavaria and North Rhine-Westphalia to defend against price pressure from international diversified groups. Deepen captive relationships with Stuttgart-Karlsruhe automotive clusters through embedded on-site testing personnel. For New Entrants and Emerging Players: The gap between premium DAkkS-accredited services and economy-tier quality control creates white-space opportunity in mid-market manufacturing machinery recertification. Target underpenetrated commercial vehicle inspection corridors between Munich and Nuremberg with mobile testing units. Pursue partnership-based entry with Fraunhofer institutes for pre-competitive research validation credentials. For Investors and Strategic Acquirers: Industrial asset integrity specialists are the most active acquirer in this space, consolidating niche laboratory operators near chemical plant clusters. Five-to-ten-year viability rests on CSRD supply chain verification service expansion beyond product-level testing. Monitor DAkkS accreditation queue lengths as inflection signal for capacity-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Capacity Expansion | DAkkS recognition timelines stretch 18-24 months, constraining competitor entry. |
| Algorithmic Audit Capability Investment | EU AI Act mandates machine-learning inspection equipment conformity assessment. |
| Embedded On-Site Testing Deployment | Baden-Württemberg supplier density rewards proximity-based service models. |
| CSRD Supply Chain Verification Service Launch | Corporate Sustainability Reporting Directive extends audit mandates to value chains. |
| Mobile Commercial Vehicle Inspection Units | Bavaria heavy-truck corridors remain underpenetrated by stationary networks. |
Research Methodology
Bottom-up automotive and industrial manufacturing modeling reconciled against top-down laboratory capacity tracking forms the analytical core. Primary interviews with KBA regulatory officers, DAkkS accreditation managers, tier-1 supplier quality engineers, and TIC procurement directors combined with secondary validation from ECHA substance screening databases, KBA type-approval registers, EU Machinery Regulation directive texts, and industry association membership records. Triangulation across stakeholder perspectives and documentary sources ensures segment-level consistency.
Historical trendline analysis of testing volume against regulatory enforcement intensity established baseline growth patterns across the projection horizon. Segmentation modeling incorporated service type, industry vertical, technology platform, and end-user procurement authority. CAGRs derived from regression of accreditation expansion rates, equipment installation pipelines, and enforcement protocol evolution. Forecast inputs included electric powertrain homologation timelines and REACH authorization list expansion schedules.
Caveats apply where DAkkS accreditation policy shifts or EU regulatory scope revisions could materially shift the outlook. Forecasts reflect assumptions about KBA enforcement consistency and ECHA substance screening throughput. Practitioners should monitor EU AI Act implementing act publication and CSRD assurance standard finalization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Syphilis Testing Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
Faecal Calprotectin Testing Market
Testing Services
Friability Tester Market
Testing Services
South Korea GMP Testing Service Market
Testing Services
Pharmaceutical Dosage Form Testing Systems Market
Testing Services
Mono Rapid Testing Market
Testing Services
Biological Safety Testing Products and Services Market
Testing Services
US C-Reactive Protein Testing Market
Testing Services
Skin Perfusion Pressure Testing Devices Market
Testing Services
Anti-Nuclear Antibody (ANA) Testing Market
Testing Services
Hospital Acquired Disease Testing Market
Testing Services
Global Lipid Panel Testing Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Global Newborn Screening Market