
 Drug Tester Market | 2026-2036
Drug Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Tester Market Analysis
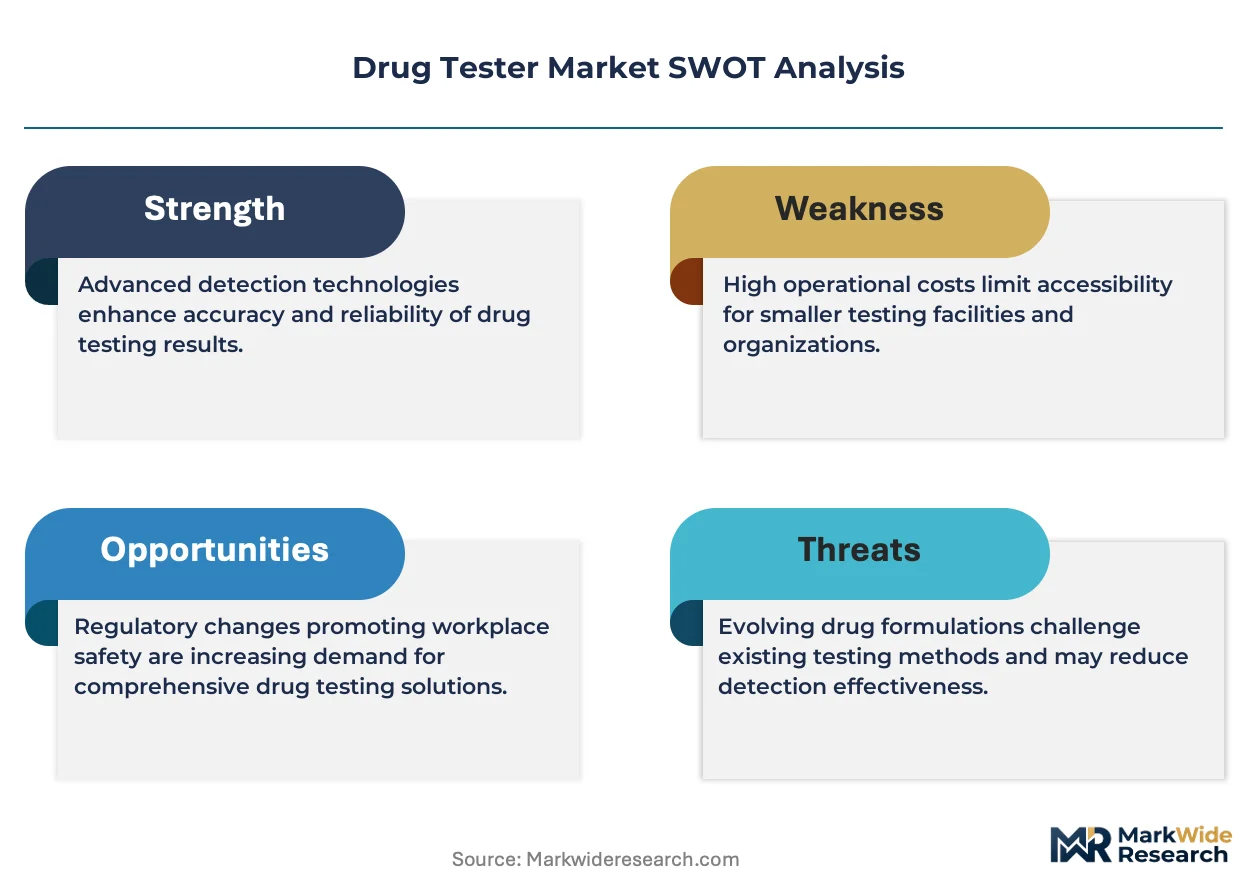
A shortage of certified forensic toxicologists is bifurcating the Drug Tester Market between high-complexity laboratory services and decentralized rapid-screening platforms. Laboratory Corporation of America Holdings leverages its national collection-site network to sustain volume leadership in employer-mandated testing programs. Quest Diagnostics anchors its position through integrated data-management systems that connect screening results directly to occupational health portals. Abbott Laboratories differentiates via handheld digital-readout devices that reduce operator training requirements in non-clinical settings.
A drug tester is an analytical instrument or consumable kit designed to detect the presence of specified drugs or their metabolites in biological specimens, typically achieving sensitivity thresholds in the nanogram-per-milliliter range through antibody-based recognition or chromatographic separation. Its primary commercial purpose is to enable legally defensible decisions in employment, athletics, criminal justice, and clinical monitoring contexts. Urine test kits retain the largest installed base due to established chain-of-custody protocols and lower per-sample cost, though saliva test kits are gaining fastest in roadside and on-site workplace applications where collection privacy concerns and adulteration risks constrain urine-based workflows. Among testing types, rapid tests command expanding shelf space in occupational health clinics, while confirmatory tests using gas chromatography-mass spectrometry capture the highest margin per analysis.
The US FDA regulates drug-testing devices as in vitro diagnostics under 21 CFR 809, requiring clinical validation for each claimed analyte, while OSHA's workplace-testing guidelines shape employer procurement standards for post-accident and reasonable-suspicion screening. In Europe, the CE marking process under the In Vitro Diagnostic Regulation mandates notified-body involvement for devices above Class A risk classification, lengthening market entry timelines for novel biomarker panels. Stakeholders must monitor evolving state-level cannabis legalization frameworks in the United States, where conflicting federal and jurisdictional standards are fragmenting testing protocols and creating compliance complexity for multi-state employers.
Market Dynamics
The Drug Tester Market is bifurcating between centralized laboratory infrastructure and decentralized rapid-screening platforms as certified forensic toxicologist shortages intensify. This structural tension is compressing margins in high-complexity confirmatory testing while accelerating investment in operator-friendly point-of-care devices.
Growth Catalysts
- OSHA workplace-testing guidelines:Post-accident and reasonable-suspicion screening mandates across US transportation and heavy manufacturing sectors sustain institutional procurement volume.
- Synthetic opioid panel expansion:Forensic toxicology laboratories are widening analyte coverage to include fentanyl analogues and novel psychoactive substances, driving reagent kit refresh cycles.
- Germany workplace safety regulations:Pre-employment and random screening mandates in logistics and automotive assembly lines concentrate European demand in this jurisdiction.
Market Restraints
- IVDR notified-body bottlenecks:CE marking timelines for Class B and above devices have lengthened substantially, delaying novel biomarker panel launches in Europe.
- Antibody raw material concentration:Monoclonal antibody supply for immunoassay manufacturing clusters among a limited set of bioreagent suppliers, creating input vulnerability.
- Gas chromatography-mass spectrometry capital intensity:Confirmatory testing infrastructure requires substantial instrumentation investment, constraining laboratory expansion in cost-sensitive markets.
Strategic Opportunities
- Saliva-based roadside screening:Privacy-advantaged collection workflows are penetrating law enforcement and on-site workplace applications where urine chain-of-custody protocols face operational friction.
- Digital-readout handheld convergence:Integration of antibody-based recognition with smartphone-connected reporting reduces training burdens in non-clinical settings.
- US state cannabis legalization divergence:Conflicting federal and jurisdictional standards create compliance complexity that favors multi-state employers outsourcing testing program management.
Industry Challenges
- Forensic toxicologist certification scarcity:The pipeline of qualified professionals capable of interpreting gas chromatography-mass spectrometry results is failing to match laboratory expansion plans.
- 21 CFR 809 clinical validation burden:FDA requirements for analyte-specific validation studies extend development timelines and escalate regulatory submission costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Tester Market |
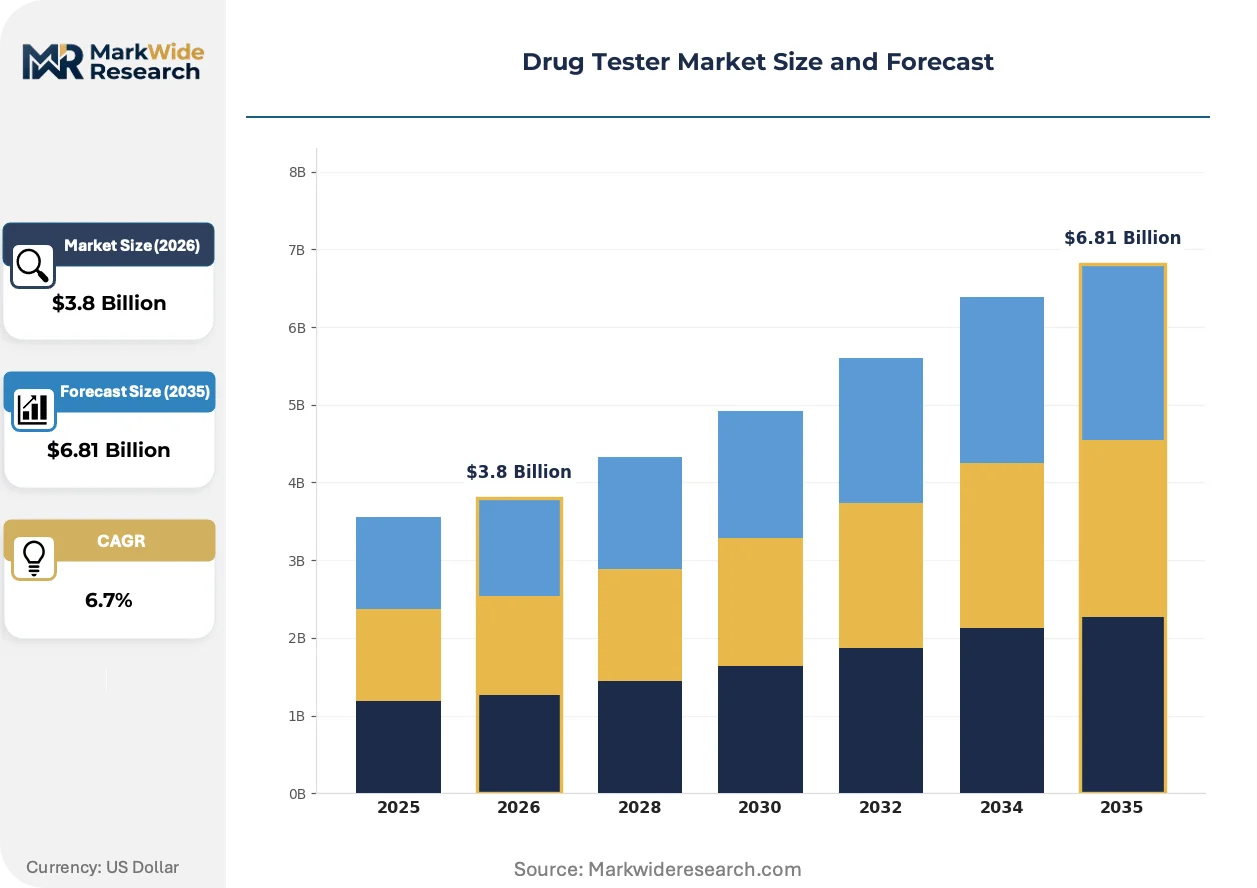
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urine Test Kits, Saliva Test Kits, Hair Test Kits, Breath Analyzers End User: Hospitals, Laboratories, Sports Organizations, Rehabilitation Centers Type of Testing: Screening Tests, Confirmatory Tests, Rapid Tests, Laboratory Tests Technology: Immunoassay, Gas Chromatography, Liquid Chromatography, ELISA |
| Companies Covered | Laboratory Corporation of America Holdings, Quest Diagnostics, Abbott Laboratories, Thermo Fisher Scientific, OraSure Technologies, Siemens Healthineers, F. Hoffmann-La Roche, Shimadzu Corporation, Drägerwerk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Tester Market Emerging Trajectories
Digital connectivity and specimen-type diversification are compressing traditional boundaries between laboratory-grade accuracy and field-deployable convenience. Three interconnected developments are reshaping competitive positioning.
Portable immunoassay readers with Bluetooth-enabled result transmission are fragmenting the historical monopoly of centralized laboratories on legally defensible testing. Occupational health clinics and third-party administrators are adopting these devices to bypass collection-site logistics. The technology is fragmenting volume concentration among national laboratory networks by enabling employer direct-access models.
The US FDA's updated point-of-care diagnostic device guidelines are accelerating 510(k) clearance pathways for rapid immunoassay platforms. This regulatory streamlining reduces time-to-market for novel analyte claims. Manufacturers are responding by front-loading clinical validation investments to capture first-mover advantage in synthetic opioid detection.
Buyers are unbundling screening program management from testing execution, contracting directly with technology vendors while retaining third-party administrators for compliance oversight. This disintermediation pressures traditional laboratory service margins. The shift is most visible among US employers with multi-state footprints navigating fragmented cannabis testing protocols.
Drug Tester Market Segmentation
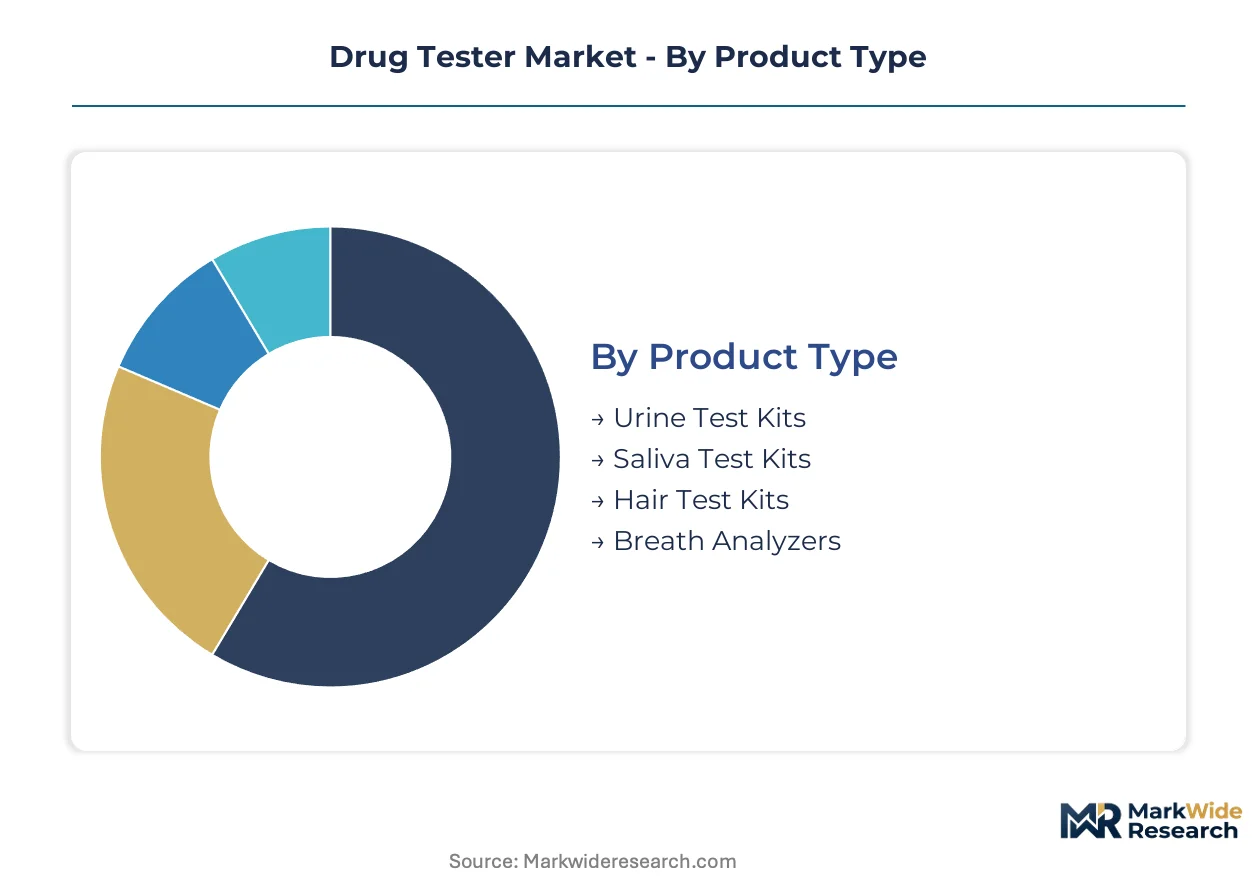
Drug tester procurement decisions hinge on chain-of-custody requirements, analyte sensitivity thresholds, and regulatory defensibility standards that vary sharply across employment, clinical, and criminal justice contexts. Segmentation reveals where centralized laboratory infrastructure retains pricing power versus where decentralized platforms are displacing traditional workflows.
Product Type:
FDA 21 CFR 809 governs in vitro diagnostic classification by specimen type and intended use setting, with urine-based systems facing distinct adulteration-detection requirements that saliva and breath-based alternatives circumvent.
- Urine Test Kits:Enzymatic and immunoassay-based detection strips process creatinine-normalized specimens with established chain-of-custody protocols. Demand concentrates in US transportation sector pre-employment screening where OSHA guidelines mandate documented collection procedures. The segment retains the largest installed base due to lower per-sample cost and defensible legal precedent.
- Saliva Test Kits:Oral fluid collection devices leverage antibody-based recognition without bathroom privacy infrastructure. Adoption is climbing the fastest among German automotive assembly lines and US roadside law enforcement where collection supervision constraints limit urine workflow feasibility. Privacy-advantaged protocols reduce operator training burdens.
- Hair Test Kits:Chromatographic analysis of keratin-incorporated metabolites extends detection windows to 90 days. Forensic toxicology laboratories in criminal justice applications favor this specimen type for historical use pattern reconstruction.
- Breath Analyzers:Fuel cell and infrared spectroscopy devices quantify ethanol in expired air for immediate impairment assessment. Law enforcement checkpoints and workplace post-accident screening drive procurement volume.
Established volume favors urine test kits; emerging adoption favors saliva test kits.
End User:
Procurement authority and reimbursement pathways diverge sharply between institutional buyers with captive laboratories versus outsourced program administrators managing multi-site compliance.
- Hospitals:Clinical toxicology departments integrate immunoassay platforms with electronic health record systems for emergency department overdose management. US hospital systems prioritize FDA-cleared devices with 510(k) documentation for medical necessity claims.
- Laboratories:Reference and forensic toxicology facilities operate gas chromatography-mass spectrometry infrastructure for legally defensible confirmatory analysis. Certified forensic toxicologist scarcity is forcing automation investments in these high-complexity settings.
- Sports Organizations:Anti-doping agencies mandate WADA-compliant chromatographic methods with chain-of-custody documentation. International federation procurement specifications drive restandardization toward mass spectrometry confirmation.
- Rehabilitation Centers:Outpatient monitoring programs combine rapid screening with scheduled laboratory confirmation. US state Medicaid reimbursement policies shape device selection in this cost-constrained segment.
Laboratories command the highest analytical margins; rehabilitation centers are expanding most quickly as court-mandated monitoring proliferates.
Type of Testing:
Margin structure inverts between high-volume screening with razor-thin unit economics and low-volume confirmatory testing capturing substantial per-analysis revenue.
- Screening Tests:Competitive immunoassay and enzyme-multiplied techniques deliver qualitative or semi-quantitative results within minutes. Occupational health clinics in US manufacturing corridors deploy these for reasonable-suspicion workflows where speed outweighs sensitivity.
- Confirmatory Tests:Gas chromatography-mass spectrometry and liquid chromatography-tandem mass spectrometry provide definitive analyte identification with quantification. Forensic toxicology laboratories in Germany and the United States maintain pricing power through certified professional interpretation requirements.
- Rapid Tests:Lateral flow and digital-readout handheld devices enable point-of-care decision-making without laboratory infrastructure. On-site workplace applications across logistics and construction sectors favor this modality.
- Laboratory Tests:Centralized processing with documented chain-of-custody supports employment termination and criminal prosecution. Multi-state US employers outsource to national networks to navigate fragmented cannabis testing protocols.
Confirmatory tests capture premium pricing; rapid tests are gaining share fastest in decentralized deployment models.
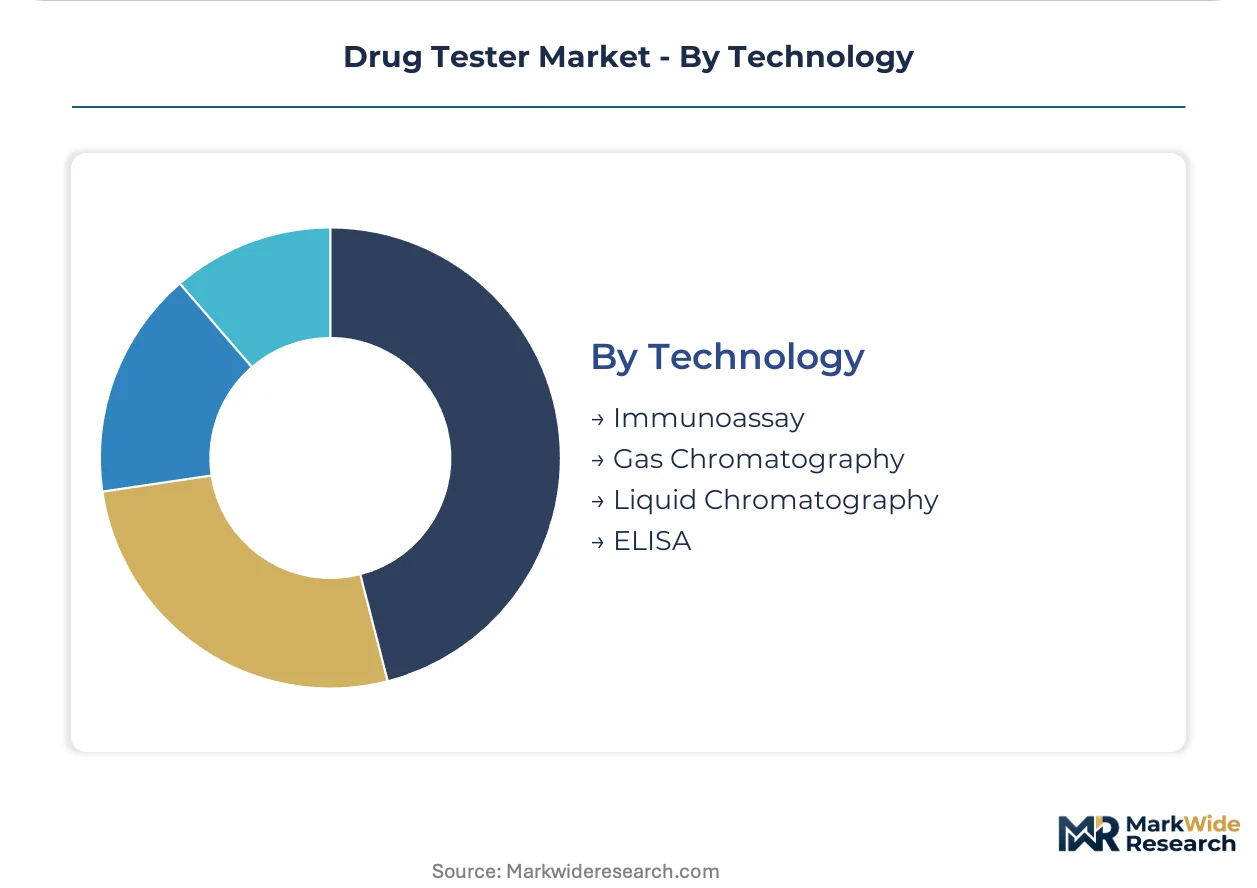
Technology:
Capital intensity and technical expertise requirements stratify the competitive landscape between antibody-based platforms and chromatographic infrastructure.
- Immunoassay:Antigen-antibody binding reactions on porous membranes or microparticle surfaces deliver rapid qualitative detection. Point-of-care occupational health settings favor this technology for minimal operator training requirements.
- Gas Chromatography:Volatile compound separation with mass spectrometric detection remains the gold standard for forensic defensibility. Forensic toxicology laboratories in the United States and Germany anchor demand despite certified analyst scarcity.
- Liquid Chromatography:High-performance and ultra-high-performance variants separate polar and thermally labile analytes without derivatization. Synthetic opioid panel expansion is accelerating reagent consumption in this segment.
- ELISA:Enzyme-linked immunosorbent assays in microplate formats enable batch processing with quantitative readout. Research and clinical reference laboratories favor this technology for high-throughput screening with moderate sensitivity requirements.
Immunoassay dominates installed base; liquid chromatography is expanding most quickly as novel psychoactive substance detection demands evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace-testing guidelines in the United States anchor institutional procurement volume, while Germany's safety mandates and Japan's clinical toxicology standards shape complementary demand centers across three continents.
United States
Transportation sector pre-employment screening and post-accident reasonable-suspicion protocols sustain institutional volume. The FDA regulates devices under 21 CFR 809, requiring analyte-specific clinical validation. Laboratory networks in North Carolina and Texas process employer-mandated programs for multi-state logistics operators.
Germany
Automotive assembly lines and logistics hubs mandate pre-employment and random screening under workplace safety regulations. CE marking under the In Vitro Diagnostic Regulation governs device classification, with notified-body involvement lengthening entry timelines. Industrial clusters in Bavaria and Baden-Württemberg concentrate occupational health clinic procurement.
Japan
Hospital emergency departments integrate immunoassay platforms for overdose management, with METI standards shaping procurement specifications. The PMDA oversees in vitro diagnostic approval pathways. Tokyo and Osaka metropolitan areas anchor clinical toxicology laboratory infrastructure.
United Kingdom
Forensic toxicology services in criminal justice applications drive confirmatory testing demand. The Medicines and Healthcare products Regulatory Agency aligns with CE marking requirements post-Brexit. London and Manchester laboratories process historical use pattern analysis via chromatographic methods.
China
Workplace safety expansion in manufacturing corridors creates emerging demand for rapid screening devices. The NMPA regulates in vitro diagnostics with GB standards compliance requirements. Yangtze River Delta industrial zones pilot employer-mandated programs in transportation and heavy machinery sectors.
Drug Tester Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with national laboratory networks leveraging collection-site density against point-of-care device manufacturers. The structure bifurcates between high-volume screening execution and premium confirmatory interpretation. Three archetypes dominate: integrated diagnostic service networks, handheld platform specialists, and analytical instrumentation manufacturers. Competitive moves center on digital-readout convergence and multi-state compliance program outsourcing.
Within the integrated diagnostic service tier, Laboratory Corporation of America Holdings and Quest Diagnostics occupy positions defined by collection-site network scale and data-management integration. Abbott Laboratories represents the handheld platform archetype, with digital-readout devices reducing operator training requirements in non-clinical deployment settings. Thermo Fisher Scientific anchors the analytical instrumentation segment, with chromatography-mass spectrometry systems serving forensic toxicology laboratories requiring legally defensible confirmation.
| Leading Market Players |
|---|
| Laboratory Corporation of America Holdings |
| Quest Diagnostics |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| OraSure Technologies |
| Siemens Healthineers |
| F. Hoffmann-La Roche |
| Shimadzu Corporation |
| Drägerwerk |
| Others |
Supply Flow & Price Mechanics
Ninety-day antibody raw material lead times compress pricing power toward bioreagent suppliers while forcing device manufacturers into strategic stockpiling commitments. This inventory burden cascades into tiered pricing structures where rapid-test producers absorb margin pressure and confirmatory laboratories pass through chromatography reagent costs.
Pricing Analysis
German occupational health clinics pay premium multiples over US employer-direct procurement for identical saliva-based screening devices. Pricing stratifies across FDA 510(k) certified, CE-IVDR marked, and uncertified economy tiers, with certification grade commanding the widest spread. Cost compression in rapid immunoassay manufacturing intensifies as monoclonal antibody suppliers consolidate. Rehabilitation centers exhibit highest price sensitivity due to Medicaid reimbursement ceilings, while forensic toxicology laboratories demonstrate lowest sensitivity given defensible confirmation requirements.
Supply Chain Analysis
Strategic stockpiling of monoclonal antibodies dominates inventory strategy over just-in-time approaches given six-month CE-IVDR certification delays. Manufacturing concentrates in the United States, Germany, and China, with antibody production drawing from bioreagent specialists in South Korea and Japan. Single-source vulnerability pervades enzyme-linked immunosorbent assay substrate supply. Distribution runs through national laboratory networks and third-party occupational health administrators rather than direct hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: FDA 21 CFR 809 and CE-IVDR certification timelines create switching costs that lock employers into validated testing programs.
For Market Incumbents: Consolidate collection-site density in multi-state logistics corridors to defend against employer direct-access models enabled by Bluetooth-connected handheld devices. Acquire certified forensic toxicologist capacity in Germany and the United States where analyst scarcity threatens service-level agreements. Channel control through third-party administrator partnerships remains the priority lever against disintermediation. For New Entrants and Emerging Players: Differentiate on saliva-based roadside screening workflows where privacy-advantaged protocols bypass established urine chain-of-custody infrastructure. Target German automotive assembly lines and US construction site applications as the most penetrable white-space segments. Pursue GPO contracts with occupational health clinic networks as the primary go-to-market angle rather than direct employer sales. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified diagnostic conglomerates with undermonetized point-of-care immunoassay divisions. Long-term viability hinges on synthetic opioid panel expansion capabilities across the analysis window. Monitor IVDR notified-body queue lengths as the critical inflection signal for European market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Opioid Panel Expansion | FDA 510(k) submissions for fentanyl analogues capture first-mover advantage in forensic toxicology refresh cycles. |
| Bluetooth-Enabled Handheld Convergence | Smartphone-connected result transmission fragments laboratory network volume concentration in occupational health settings. |
| Multi-State Compliance Program Outsourcing | Third-party administrators navigate fragmented US cannabis testing protocols for logistics employers. |
| CE-IVDR Notified-Body Pre-Submission | Early engagement with German BfArM accelerates novel biomarker panel launches against regulatory bottlenecks. |
| Forensic Toxicologist Workforce Pipeline | University partnerships in North Carolina and Texas secure certified analyst capacity for confirmatory testing expansion. |
Methodological Framework
Cross-validation between primary interviews with forensic toxicology laboratory directors, occupational health clinic procurement managers, and third-party administrator compliance officers anchors the qualitative findings against FDA 510(k) filing records, CE-IVDR notified-body databases, and OSHA workplace incident reporting systems. Bottom-up triangulation against hospital GPO contract databases and employer-mandated testing program disclosures validates top-down market sizing across specimen type, testing modality, and end-user segments.
Sensitivity analysis around monoclonal antibody supply disruptions and IVDR certification timeline scenarios shapes the analytical framework over the projection horizon. Modeled dimensions span product type, technology platform, testing type, and end-user procurement authority. CAGRs derive from segment-level volume trajectories weighted by confirmatory versus screening test mix. Synthetic opioid detection reagent consumption and saliva-based device adoption curves serve as industry-specific forecast inputs.
Material uncertainties — forensic toxicologist certification pipeline shortfalls, US state cannabis legalization divergence, and CE-IVDR notified-body capacity constraints — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and employer testing mandate continuity. Practitioners should keep alternative scenarios live as OSHA guideline revisions and European regulatory enforcement postures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Drug Abuse Testing Market
Testing Services
Redox Meter Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Global Homocysteine Testing Market
Testing Services
D-Dimer Testing Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
Thailand Point-Of-Care Testing (POCT) Market
Testing Services
Paediatric and Neonatal Testing Kits Market
Testing Services
Point of Care Testing Market
Testing Services
Syphilis Testing Market
Testing Services
Drug Testing Equipment Market
Testing Services
Active B12 Test Market
Testing Services
At-Home Testing Market
Testing Services
Self-Testing Market
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
Toxicology Drug Screening Market