
 Pyrogen Testing Market | 2026-2036
Pyrogen Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Pyrogen Testing Market Analysis
Single-source reliance on horseshoe crab-derived Limulus Amebocyte Lysate is shifting toward multi-source recombinant strategies across the industry. Lonza Group leverages its biologics manufacturing footprint to sustain integrated pyrogen testing services. Charles River Laboratories anchors its position through specialized endotoxin detection laboratories in North America. Thermo Fisher Scientific competes by extending its analytical instrument portfolio into automated chromogenic platforms.
Pyrogen testing comprises analytical methods that detect fever-inducing bacterial endotoxins and non-endotoxin contaminants in parenteral pharmaceuticals, medical devices, and biological products, with Limulus Amebocyte Lysate reagent sensitivity thresholds typically calibrated to 0.03 EU/ml for water-for-injection standards. The primary purpose centers on batch-release certification and patient safety assurance before sterile product administration. Recombinant Factor C represents the fastest-growing product category as manufacturers seek alternatives to animal-derived reagents amid supply variability concerns. The biologics application segment commands concentrated margin pools due to complex molecule formats requiring customized validation protocols. Chromogenic technology leads in throughput-intensive environments while turbidimetric methods occupy kinetic monitoring applications.
The FDA enforces endotoxin limits through its Guidance for Industry on Pyrogen and Endotoxins Testing, directly shaping validation requirements for pharmaceutical submissions. The European Pharmacopoeia's Chapter 2.6.8 and the United States Pharmacopeia Chapter 85 create divergent but converging standards that manufacturers must simultaneously satisfy for transatlantic product registration. Japan's PMDA maintains aligned but distinct bacterial endotoxin testing requirements under its pharmacopeial framework. Stakeholders must monitor regulatory acceptance trajectories for recombinant alternatives against established LAL compendial status to time capital allocation and validation investments.
Market Dynamics
The transition from horseshoe crab-derived Limulus Amebocyte Lysate to recombinant Factor C alternatives is compressing supply chains and forcing validation protocol rewrites across biologics manufacturing. This technology shift is redistributing margin pools from raw material harvesters to synthetic biology platforms while tightening endotoxin detection sensitivity thresholds.
Growth Catalysts
- European Pharmacopoeia Chapter 2.6.8:The revision toward recombinant alternatives creates regulatory cover for manufacturers to abandon animal-derived reagents. Biologics producers in Germany and Switzerland are accelerating internal validation timelines.
- Cell and gene therapy expansion:Complex viral vector manufacturing requires customized pyrogen detection protocols with lower endotoxin thresholds. CDMOs serving this segment are building captive testing laboratories.
- Water-for-injection standards:Pharmaceutical-grade water systems now mandate 0.03 EU/ml sensitivity calibration. Facility upgrades across the United States are driving chromogenic platform installations.
Market Restraints
- Atlantic horseshoe crab population volatility:Delaware Bay harvest fluctuations create raw material uncertainty for LAL producers. Conservation limits in New Jersey and Delaware constrain seasonal collection volumes.
- Recombinant Factor C validation costs:Cross-reference studies against compendial LAL methods require 18-24 month timelines. Mid-tier manufacturers lack capital reserves for parallel qualification runs.
- Pharmacopeial divergence:United States Pharmacopeia Chapter 85 maintains LAL primacy while European guidance accelerates recombinant acceptance. Dual-track compliance inflates regulatory affairs overhead.
Strategic Opportunities
- India's biologics manufacturing corridor:CDSCO inspection capacity constraints create demand for third-party pyrogen certification. Hyderabad and Bangalore clusters lack integrated testing infrastructure.
- Single-use bioreactor integration:Disposable manufacturing formats require point-of-use endotoxin detection. Automated cartridge systems eliminate sample transport delays.
- Japan PMDA harmonization pressure:Alignment with ICH Q4B bacterial endotoxins testing guidelines opens pathway for recombinant acceptance. Domestic biologics producers seek reduced import dependency.
Industry Challenges
- Reference standard calibration drift:Endotoxin unit potency variations between WHO International Standards and national reference preparations create measurement uncertainty. Analytical laboratories must maintain dual traceability chains.
- Automation integration complexity:Chromogenic platforms require LIMS connectivity with legacy batch record systems. Validation of electronic data integrity under 21 CFR Part 11 extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyrogen Testing Market |
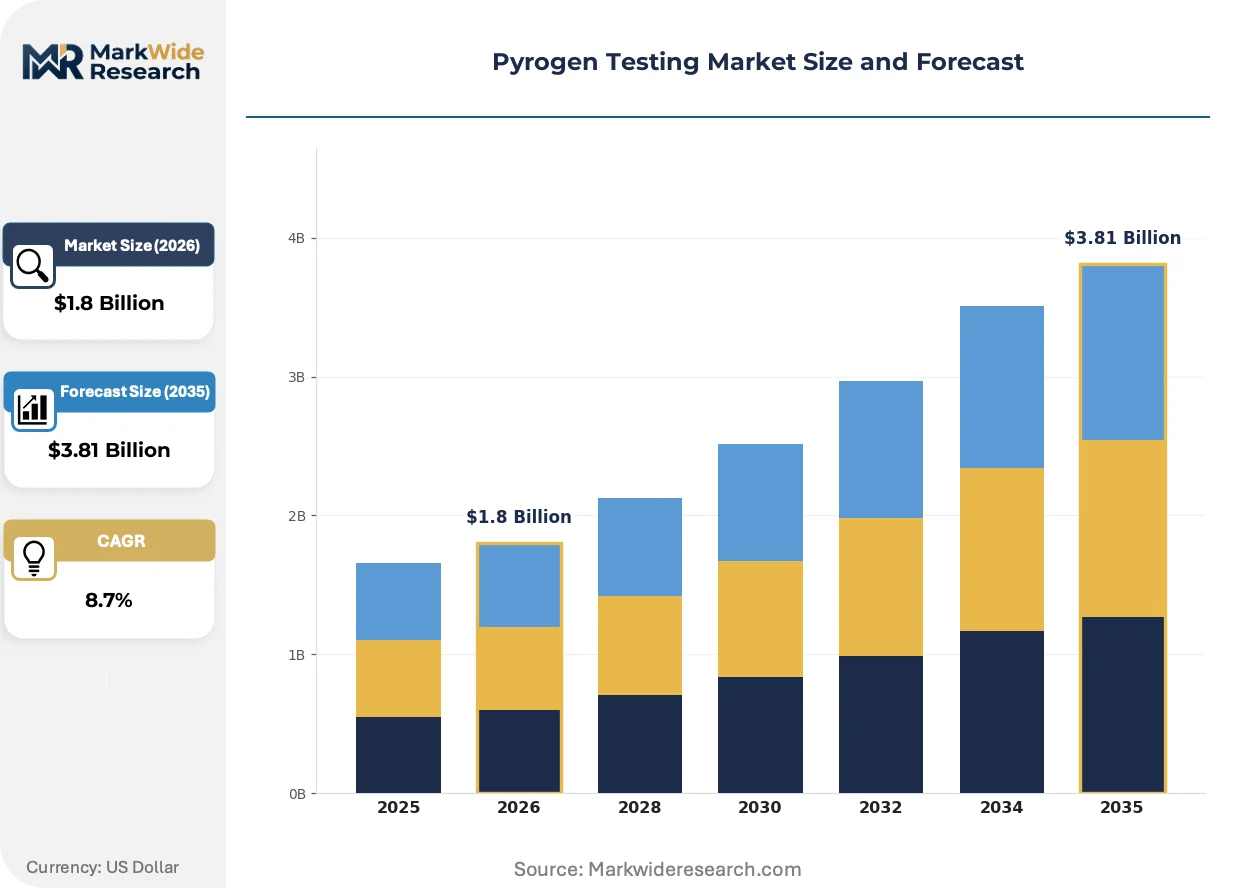
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LAL, Recombinant Factor C, Rabbit Pyrogen Test, Other Application: Pharmaceuticals, Biologics, Medical Devices, Diagnostics End User: Pharmaceutical Companies, Contract Research Organizations, Academic Institutions, Biotechnology Firms Technology: Chromogenic, Turbidimetric, Gel-Clot, Other |
| Companies Covered | bioMérieux SA, Associates of Cape Cod, Charles River Laboratories, Ellab A/S, GenScript, Lonza Group, Merck KGaA, FUJIFILM Wako Chemicals, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyrogen Testing Market Emerging Trajectories
Recombinant protein engineering and microfluidic detection architectures are converging to displace century-old biological assay methods. The competitive frontier now centers on sensitivity specificity rather than reagent supply security.
Recombinant Factor C is rewriting endotoxin detection economics by eliminating seasonal harvest dependency and lot-to-lot variability. Contract manufacturers in Massachusetts and North Carolina are completing validation transfers within 12-month windows. The technology is compressing assay development timelines from 18 months to 90 days for novel biologic formats.
EMA's phased acceptance of recombinant alternatives under the European Pharmacopoeia is forcing manufacturers to maintain dual qualification dossiers. The industrial consequence is a bifurcation of testing strategies between US-facing and EU-facing production lines. Biologics exporters in Ireland and Belgium are prioritizing recombinant methods to streamline batch release.
CDMO procurement committees are unbundling pyrogen testing from full-service manufacturing contracts. Analytical service providers in Singapore and South Korea are capturing disaggregated testing volumes through dedicated endotoxin laboratories. This pattern is most visible among mid-cap biotech sponsors lacking internal QC infrastructure.
Pyrogen Testing Market Segmentation
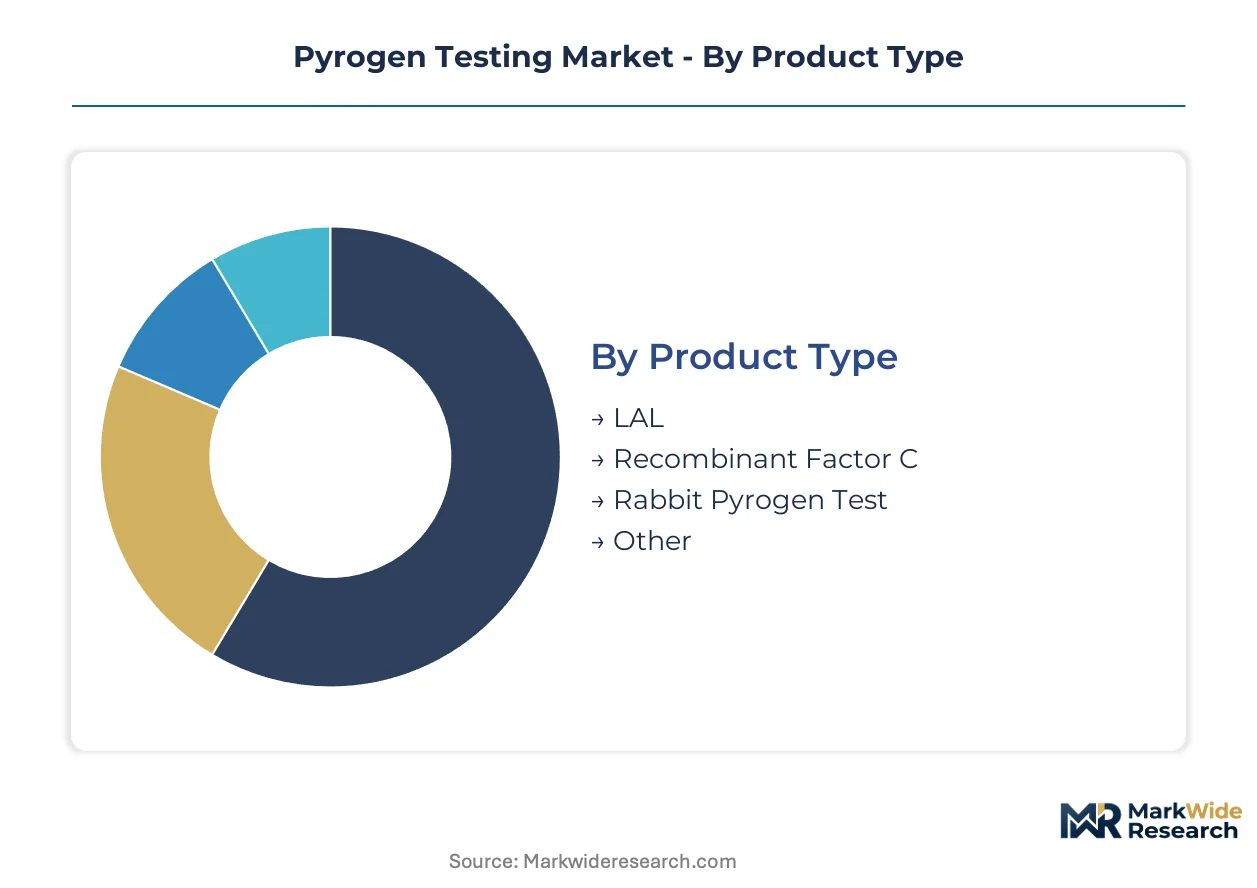
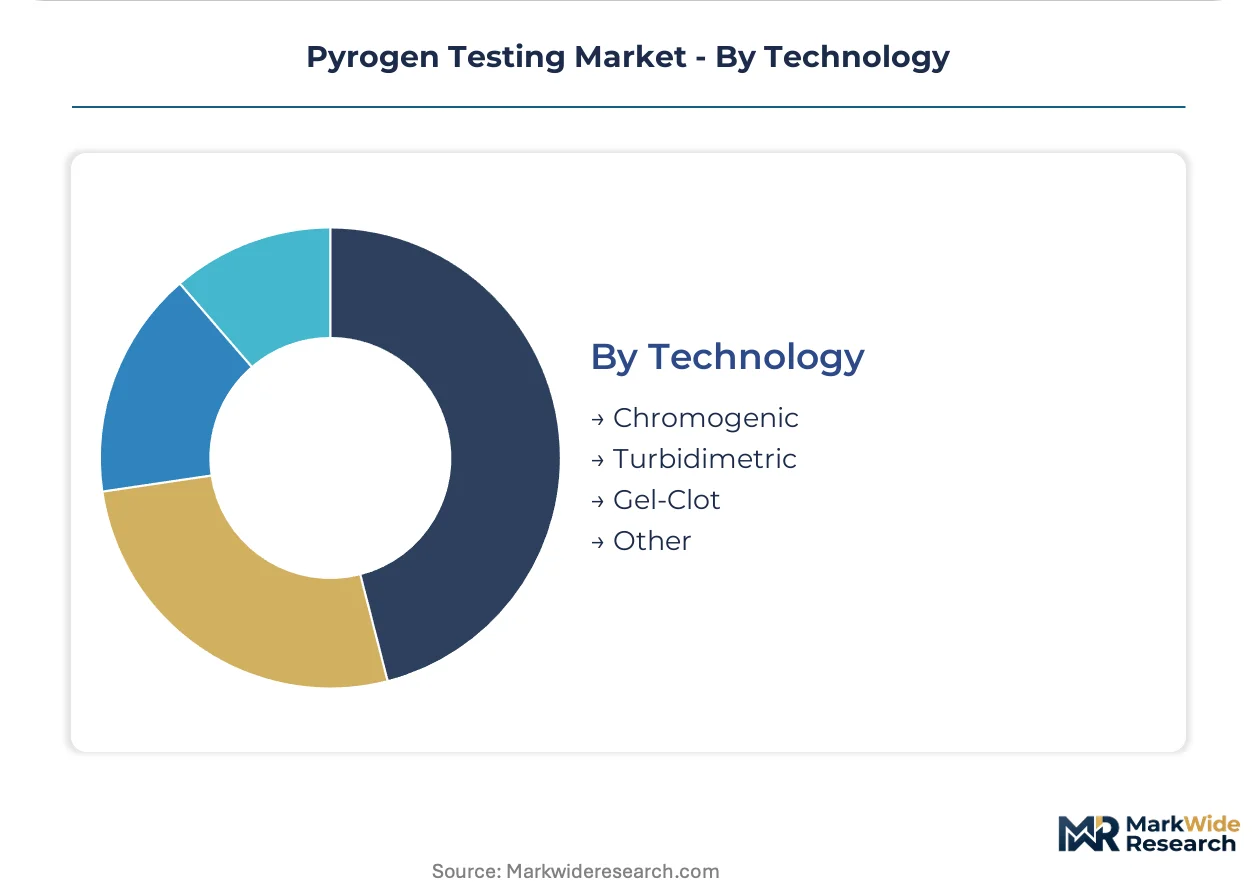
Pyrogen testing segmentation reveals divergent commercial dynamics across reagent sourcing, application complexity, and detection methodology. Each category carries distinct margin profiles and regulatory validation burdens that shape procurement strategies.
Product Type:
Standardization dominates animal-derived reagents while recombinant alternatives demand customized validation protocols for each manufacturing site.
- LAL:Horseshoe crab-derived lysate remains the compendial standard with established FDA and USP Chapter 85 recognition. Demand concentrates in legacy parenteral manufacturing facilities across the United States where regulatory inertia preserves incumbent status despite supply volatility from Delaware Bay harvest constraints.
- Recombinant Factor C:Synthetic biology-produced endotoxin detection reagent eliminates seasonal harvest dependency and lot-to-lot variability. Biologics manufacturers in Germany and Switzerland are accelerating internal validation timelines following European Pharmacopoeia Chapter 2.6.8 revisions toward recombinant acceptance.
- Rabbit Pyrogen Test:In vivo fever response assay retains niche applications for non-endotoxin pyrogen detection in complex biological matrices.
- Other:Monocyte activation test and human whole blood assays address specific non-endotoxin pyrogen requirements.
Leading the category by volume: LAL. Expanding most quickly: Recombinant Factor C.
Application:
Margin concentration tracks molecule complexity, with biologics commanding premium pricing for customized validation protocols.
- Pharmaceuticals:Small-molecule parenteral manufacturing drives standardized high-throughput testing with established endotoxin limits. Water-for-injection systems at facilities across the United States mandate 0.03 EU/ml sensitivity calibration, sustaining chromogenic platform demand.
- Biologics:Monoclonal antibodies, vaccines, and cell therapies require customized detection protocols with lower endotoxin thresholds. CDMOs serving viral vector manufacturing in Massachusetts and North Carolina are building captive testing laboratories to compress batch-release timelines.
- Medical Devices:Implantable and infusion set products face sterilization validation requirements with device-specific extraction protocols.
- Diagnostics:In vitro diagnostic reagents and calibrators require endotoxin control for assay reliability.
Biologics commands the steepest margin expansion. Pharmaceuticals retains the largest absolute testing volume.
End User:
Procurement sophistication varies from integrated biopharma quality control departments to outsourced analytical service providers.
- Pharmaceutical Companies:Integrated manufacturers maintain in-house endotoxin detection laboratories with validated LAL and recombinant methods. Batch-release certification requirements under FDA Guidance for Industry drive captive infrastructure investment.
- Contract Research Organizations:Analytical service providers capture disaggregated testing volumes through dedicated endotoxin laboratories. CDMO procurement committees in Singapore and South Korea are unbundling pyrogen testing from full-service manufacturing contracts.
- Academic Institutions:Research-scale testing supports preclinical biologic development with limited regulatory submission requirements.
- Biotechnology Firms:Mid-cap sponsors lacking internal QC infrastructure rely on third-party certification for IND-enabling studies.
Pharmaceutical Companies dominate absolute spending. Contract Research Organizations are gaining share fastest through testing unbundling.
Technology:
Detection sensitivity and throughput requirements determine platform selection across kinetic monitoring and endpoint applications.
- Chromogenic:Colorimetric endpoint detection enables high-throughput screening in water-for-injection validation and raw material testing. Facility upgrades across the United States are driving platform installations for 0.03 EU/ml sensitivity compliance.
- Turbidimetric:Kinetic turbidity measurement supports real-time endotoxin quantification with broader dynamic range. Biologics manufacturers employ this method for complex sample matrices with interfering substances.
- Gel-Clot:Semi-quantitative limit test remains the reference method for pharmacopeial compliance in release testing.
- Other:Microfluidic and cartridge-based systems address point-of-use detection in single-use bioreactor manufacturing.
Chromogenic leads in throughput-intensive environments. Turbidimetric methods occupy kinetic monitoring applications with the steepest adoption curve in biologics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Delaware Bay's horseshoe crab populations anchor raw material supply for traditional Limulus Amebocyte Lysate production. Regulatory divergence between FDA and EMA standards is fragmenting testing strategies across manufacturing geographies.
United States
FDA's Guidance for Industry on Pyrogen and Endotoxins Testing enforces stringent endotoxin limits on parenteral drug approvals. Water-for-injection standards mandate 0.03 EU/ml sensitivity calibration, driving chromogenic platform installations at facilities across Massachusetts and North Carolina. CDMOs in the Research Triangle Park cluster are building captive testing laboratories to compress batch-release timelines for viral vector manufacturing.
Germany
Biologics manufacturers in Munich and Heidelberg are accelerating internal validation timelines for recombinant Factor C methods. EMA's phased acceptance under European Pharmacopoeia Chapter 2.6.8 creates regulatory cover to abandon animal-derived reagents. The Rhine-Main biotech corridor is prioritizing recombinant methods to streamline batch release for EU-facing production lines.
Switzerland
Novartis and Roche's manufacturing footprints sustain concentrated demand for customized pyrogen detection protocols. Swissmedic maintains aligned bacterial endotoxin testing requirements with EMA guidance while monitoring ICH Q4B harmonization pressure. The Basel biopharma cluster is completing validation transfers for recombinant alternatives within compressed 12-month windows.
India
CDSCO inspection capacity constraints create demand for third-party pyrogen certification across the biologics manufacturing corridor. Hyderabad and Bangalore clusters lack integrated testing infrastructure, opening pathways for analytical service providers. Domestic biologics producers seek reduced import dependency through captive endotoxin detection laboratories.
Japan
PMDA maintains aligned but distinct bacterial endotoxin testing requirements under its pharmacopeial framework. Alignment with ICH Q4B guidelines opens pathway for recombinant acceptance, though LAL primacy persists in validation protocols. The Kanto pharmaceutical manufacturing belt is evaluating automated chromogenic platforms for high-throughput screening applications.
Pyrogen Testing Market Vendor Landscape
Global majors compete with regional champions across reagent sourcing and detection platform deployment. The vendor base stratifies between integrated life science conglomerates and specialized analytical service providers. Three archetypes dominate: synthetic biology platforms supplying recombinant reagents, captive testing laboratories within CDMO manufacturing footprints, and independent analytical laboratories capturing unbundled testing volumes. Competitive moves center on validation protocol licensing and point-of-use cartridge system development.
Among integrated life science conglomerates, Lonza Group, Thermo Fisher Scientific, and Charles River Laboratories exemplify distinct positioning archetypes. Lonza leverages its biologics manufacturing footprint to sustain integrated pyrogen testing services. Thermo Fisher competes by extending its analytical instrument portfolio into automated detection platforms. Charles River anchors its position through specialized endotoxin detection laboratories in North America, representing the captive laboratory archetype.
| Leading Market Players |
|---|
| bioMérieux SA |
| Associates of Cape Cod |
| Charles River Laboratories |
| Ellab A/S |
| GenScript |
| Lonza Group |
| Merck KGaA |
| FUJIFILM Wako Chemicals |
| Thermo Fisher Scientific |
| Others |
Supply Flow & Price Mechanics
Delaware Bay horseshoe crab harvest quotas cascade through LAL reagent pricing into three-tier cost structures across pharmaceutical testing tiers. Recombinant Factor C alternatives are compressing animal-derived premium spreads as synthetic biology platforms achieve production scale.
Pricing Analysis
Service bundling separates validation protocol licensing from per-test reagent consumption in CDMO procurement structures. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from recombinant alternatives achieving cost parity with LAL reagents in high-throughput environments. Mid-tier biotech sponsors lacking captive QC infrastructure exhibit highest price sensitivity, while integrated biopharma manufacturers prioritize assay reliability over unit cost.
Supply Chain Analysis
Reverse logistics for LAL reagents involves cold-chain returns of expired lots and refurbishment of chromogenic platform consumables to secondary markets. Raw material sourcing draws from Delaware Bay harvest operations, recombinant protein fermentation facilities in Germany and Switzerland, and rabbit breeding colonies in specific licensed jurisdictions. Supply chain risk centers on single-source vulnerability for Atlantic horseshoe crab populations amid conservation quota restrictions. Distribution runs through direct sales to integrated pharmaceutical manufacturers and analytical service provider networks serving outsourced testing demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pyrogen testing market is becoming a vertical-integration race as manufacturers pursue captive recombinant reagent production to secure supply continuity and compress validation timelines.
For Market Incumbents: Acquire recombinant protein engineering capabilities to defend against synthetic biology entrants eroding LAL reagent margins. Build captive testing laboratories in Massachusetts and North Carolina viral vector manufacturing clusters to capture disaggregated CDMO volumes. Secure dual pharmacopeial qualification dossiers under FDA and EMA frameworks before regulatory divergence widens compliance costs.
For New Entrants and Emerging Players: Begin with point-of-use cartridge systems for single-use bioreactor integration in Singapore and South Korean CDMO facilities. Target India's Hyderabad and Bangalore biologics corridors where CDSCO inspection constraints create third-party certification demand. Pursue automated chromogenic platform partnerships with water-for-injection system upgrade cycles across United States pharmaceutical manufacturing.
For Investors and Strategic Acquirers: The window for entry favors recombinant Factor C platform specialists with validated European Pharmacopoeia acceptance. Long-term viability hinges on regulatory harmonization trajectories rather than reagent cost curves alone. Monitor ICH Q4B bacterial endotoxins testing guideline adoption rates as the inflection signal for recombinant method primacy.
| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Factor C Validation Transfer | Accelerates batch-release timelines under EMA Chapter 2.6.8 guidance for EU-facing production. |
| Captive Testing Laboratory Buildout | CDMOs in Research Triangle Park compress viral vector manufacturing cycle times through integrated QC. |
| Automated Chromogenic Platform Deployment | United States facilities achieve 0.03 EU/ml water-for-injection compliance with LIMS-integrated systems. |
| Point-of-Use Cartridge Development | Eliminates sample transport delays in disposable bioreactor manufacturing formats. |
| Dual Pharmacopeial Qualification Dossier | Mitigates regulatory divergence risk between FDA LAL primacy and EMA recombinant acceptance. |
Methodological Framework
Independent corroboration across quality control directors at biologics manufacturers, regulatory affairs specialists, CDMO procurement committees, and analytical laboratory managers underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation from FDA Guidance for Industry documents, European Pharmacopoeia Chapter 2.6.8 revisions, USP Chapter 85 standards, and CDSCO inspection capacity reports. Bottom-up testing volume estimates triangulated against top-down reagent manufacturer shipment data.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects in recombinant versus LAL reagent categories. Segmentation modeling incorporated product type, application complexity, end-user procurement sophistication, and detection technology sensitivity tiers. CAGRs were derived from regression against biologics manufacturing capacity expansion, cell and gene therapy clinical pipeline advancement, and pharmacopeial regulatory acceptance trajectories. Forecast inputs included Delaware Bay harvest quota schedules and recombinant protein fermentation capacity buildout announcements.
Regulatory acceptance delays, Atlantic horseshoe crab population volatility, and recombinant validation timeline extensions are the dominant revision risks. Forecasts reflect assumptions about EMA phased acceptance continuity and ICH Q4B harmonization pressure. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Europe Newborn Screening Market
Testing Services
United States Esoteric Testing Market
Testing Services
India GMP Testing Service Market
Testing Services
Asia-Pacific Hereditary Cancer Testing Market
Testing Services
Addison Disease Testing Market
Testing Services
Comprehensive Metabolic Panel (CMP) Testing Market
Testing Services
Urine Testing Cups Market
Testing Services
Global GI Stool Testing Market
Testing Services
Staphylococcus Aureus Testing Market
Testing Services
Global Ovulation Test Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
Global Bioburden Testing Market
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
Global Sterility Testing Market
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
ATP Assays Market