
 Antibiotic Susceptibility Testing Market | 2026-2036
Antibiotic Susceptibility Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Antibiotic Susceptibility Testing Market Analysis
The capital-intensity divergence between automated platform developers and manual test suppliers is redrawing competitive boundaries in antibiotic susceptibility testing. bioMérieux SA leverages its integrated instrument-reagent ecosystem to sustain premium positioning across European hospital networks. Thermo Fisher Scientific anchors North American market presence through extensive clinical distribution infrastructure. Becton, Dickinson and Company differentiates via end-to-end microbiology workflow solutions spanning specimen collection through result reporting.
Antibiotic susceptibility testing encompasses laboratory methodologies that determine bacterial resistance or sensitivity to antimicrobial agents, employing techniques such as disk diffusion zone diameter measurement, broth microdilution minimum inhibitory concentration determination, and automated optical detection of bacterial growth inhibition. These procedures enable clinicians to select effective therapeutic agents and support public health surveillance of resistance patterns. Automated systems command the highest capital investment per installation while delivering superior throughput for high-volume clinical laboratories. Phenotypic methods retain dominant installed base across resource-limited settings where infrastructure constraints limit molecular platform deployment. Antibiotic stewardship applications within hospitals represent the fastest-expanding demand segment as institutions face mandatory reporting requirements for antimicrobial utilization metrics.
FDA oversight of in vitro diagnostic devices governs premarket pathways for novel susceptibility testing platforms, while EMA's In Vitro Diagnostic Regulation mandates clinical evidence standards that influence development timelines for European market entry. The EU Green Deal's chemical hazard restrictions additionally shape reagent formulation decisions for manufacturers seeking unified product architectures across regulatory jurisdictions. Stakeholders must monitor evolving breakpoints from CLSI and EUCAST as these standard-setting bodies increasingly harmonize resistance thresholds that directly determine product clinical validity claims.
Market Dynamics
Hospital-acquired infection surveillance mandates are compressing turnaround time requirements for bloodstream pathogen identification, forcing laboratories to reconfigure capital allocation toward integrated automation platforms.
Growth Catalysts
- CLSI Breakpoint Harmonization:Standard-setting bodies in the United States and Europe are converging resistance threshold definitions, reducing regulatory fragmentation for manufacturers pursuing unified product architectures across jurisdictions.
- Antimicrobial Stewardship Mandates:Hospital systems face mandatory reporting requirements for antibiotic utilization metrics, creating institutional pressure to implement rapid susceptibility screening workflows.
- Molecular Platform Convergence:Polymerase chain reaction and mass spectrometry technologies are integrating with phenotypic methods, enabling same-shift resistance detection for bloodstream infections.
Market Restraints
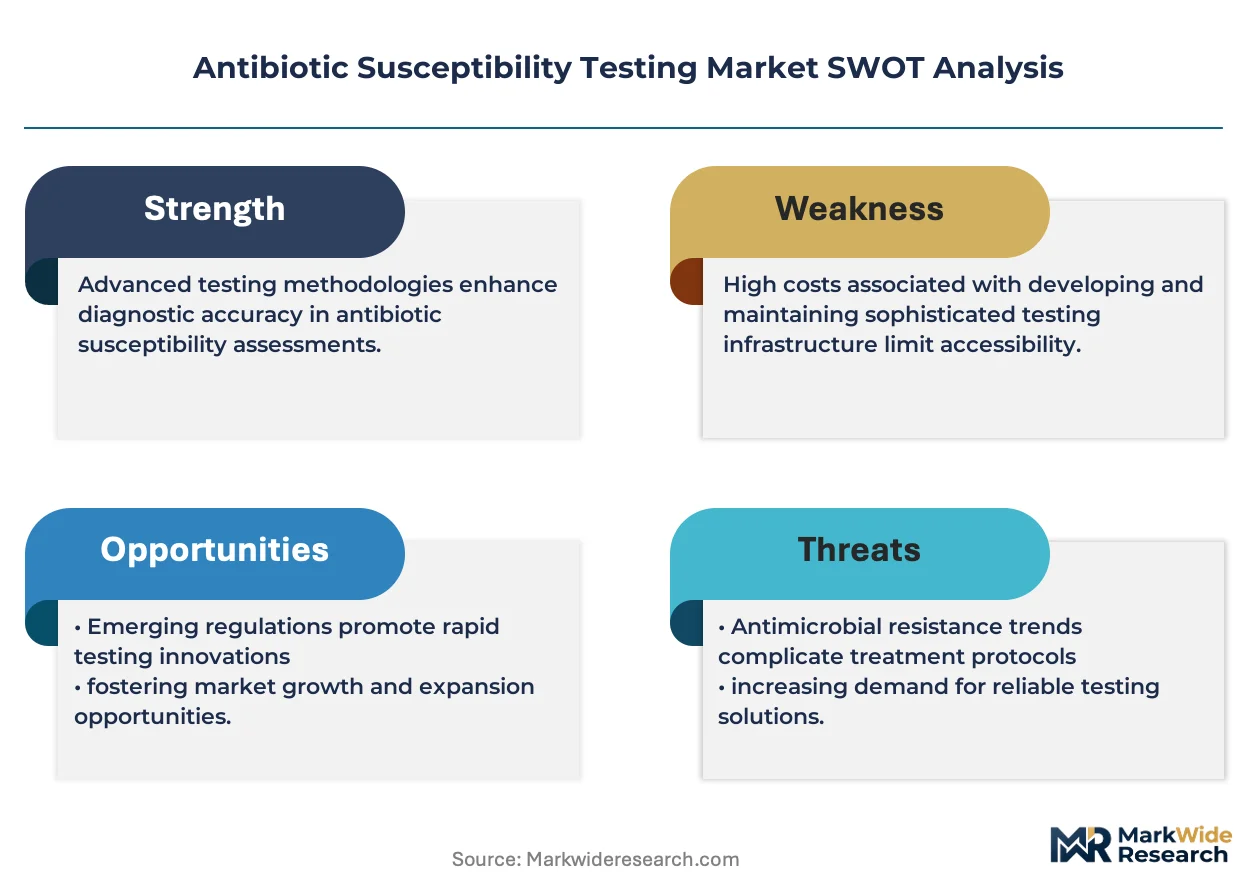
- Capital Intensity Divergence:Automated platform installations require infrastructure investments that exclude mid-volume laboratories and resource-constrained health systems from participation.
- Reagent Supply Concentration:Specialty culture media and antimicrobial agent panels depend on limited European and North American chemical suppliers, creating input vulnerability.
- Breakpoint Revision Cycles:Frequent updates to EUCAST and CLSI resistance thresholds force manufacturers into costly label revision and clinical revalidation protocols.
Strategic Opportunities
- Point-of-Care Expansion:Decentralized susceptibility testing in emergency departments and intensive care units addresses the clinical need for rapid therapeutic guidance outside centralized laboratories.
- EU Green Deal Alignment:Reagent manufacturers can capture preferential positioning by eliminating hazardous preservatives and solvents ahead of ECHA chemical restriction timelines.
- AI-Assisted Interpretation:Machine learning algorithms applied to zone diameter measurement and growth curve analysis reduce technician time requirements and standardize result reporting.
Industry Challenges
- Microbiology Technologist Shortage:Clinical laboratories face recruitment gaps for trained personnel capable of performing manual disk diffusion and broth microdilution procedures.
- Legacy System Integration:Automated susceptibility platforms must interface with existing laboratory information systems and hospital electronic health records through non-standardized data exchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibiotic Susceptibility Testing Market |
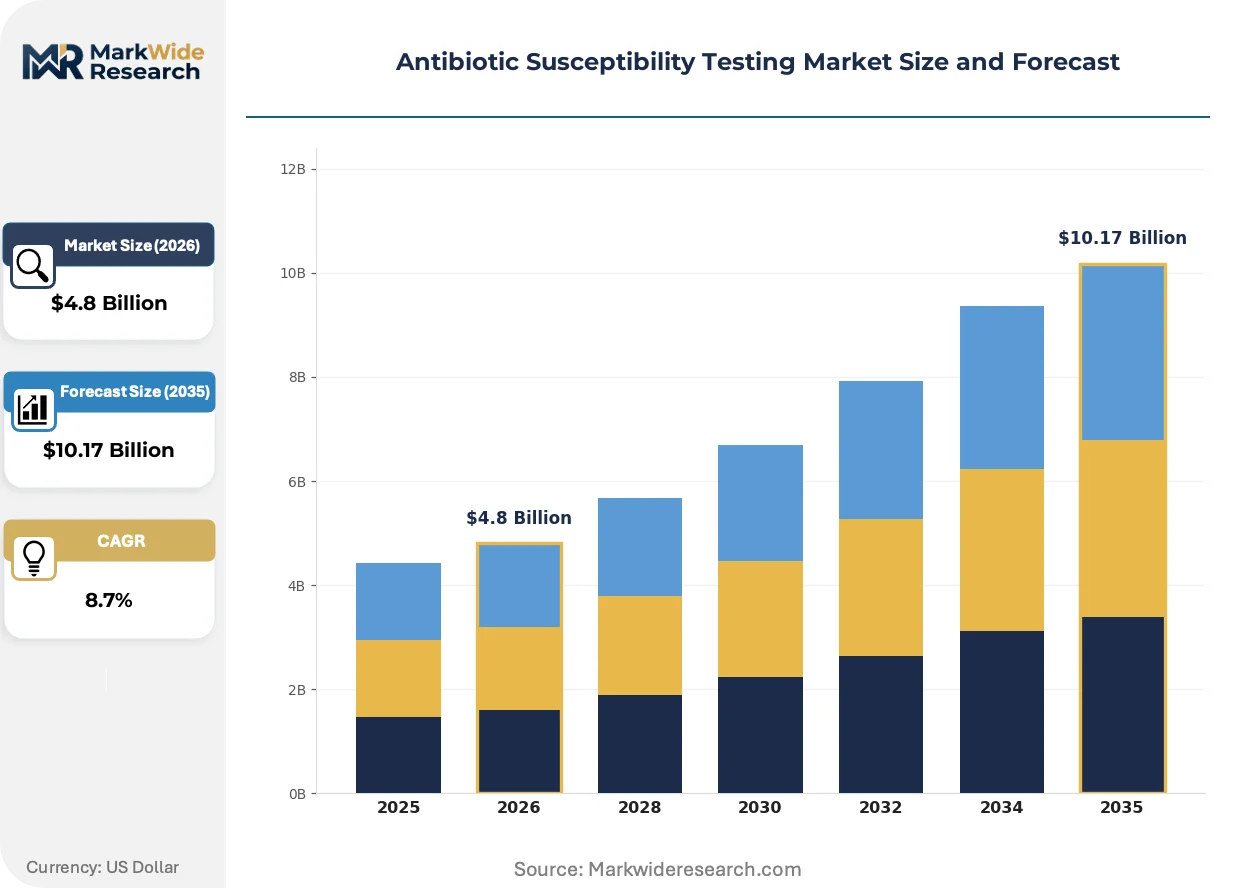
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disk Diffusion, Broth Microdilution, E-test, Automated Systems End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Hospitals Technology: Molecular Methods, Antimicrobial Susceptibility Testing, Phenotypic Methods, Genotypic Methods Application: Infectious Disease Diagnosis, Antibiotic Stewardship, Clinical Research, Epidemiological Studies |
| Companies Covered | bioMérieux SA, Becton, Dickinson and Company, Thermo Fisher Scientific, Danaher Corporation, Bio-Rad Laboratories, Bruker, Accelerate Diagnostics, Merck KGaA, HiMedia Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibiotic Susceptibility Testing Market Emerging Trajectories
Rapid pathogen identification technologies are compressing the diagnostic cascade from specimen collection to targeted therapy selection, reshaping how laboratories allocate space, staff, and capital across testing modalities.
Matrix-assisted laser desorption ionization-time of flight mass spectrometry is decomposing the traditional workflow separation between organism identification and resistance profiling. Academic medical centers in the United States and Germany are deploying integrated platforms that collapse the identification-to-susceptibility interval from 48 hours to under 8 hours. This compression is decomposing the historical division between microbiology and pharmacy stewardship teams, forcing organizational restructuring around rapid response protocols.
The FDA's enforcement of antimicrobial resistance surveillance requirements under the AMR Action Plan is mandating standardized resistance reporting formats for hospital laboratories. Device manufacturers must now pre-validate software modules for electronic transmission to NHSN and equivalent state health departments. European manufacturers face parallel obligations under EMA's In Vitro Diagnostic Regulation clinical evidence standards, extending development timelines for novel platform submissions.
Consolidated service contracts are displacing instrument-reagent unbundling as the dominant procurement model among multi-hospital systems. Purchasing committees now negotiate total cost-per-test agreements spanning installation, maintenance, consumables, and software updates over five-year terms. This shift is most pronounced in United States integrated delivery networks and German hospital federations, where procurement centralization has reduced vendor fragmentation.
Antibiotic Susceptibility Testing Market Segmentation
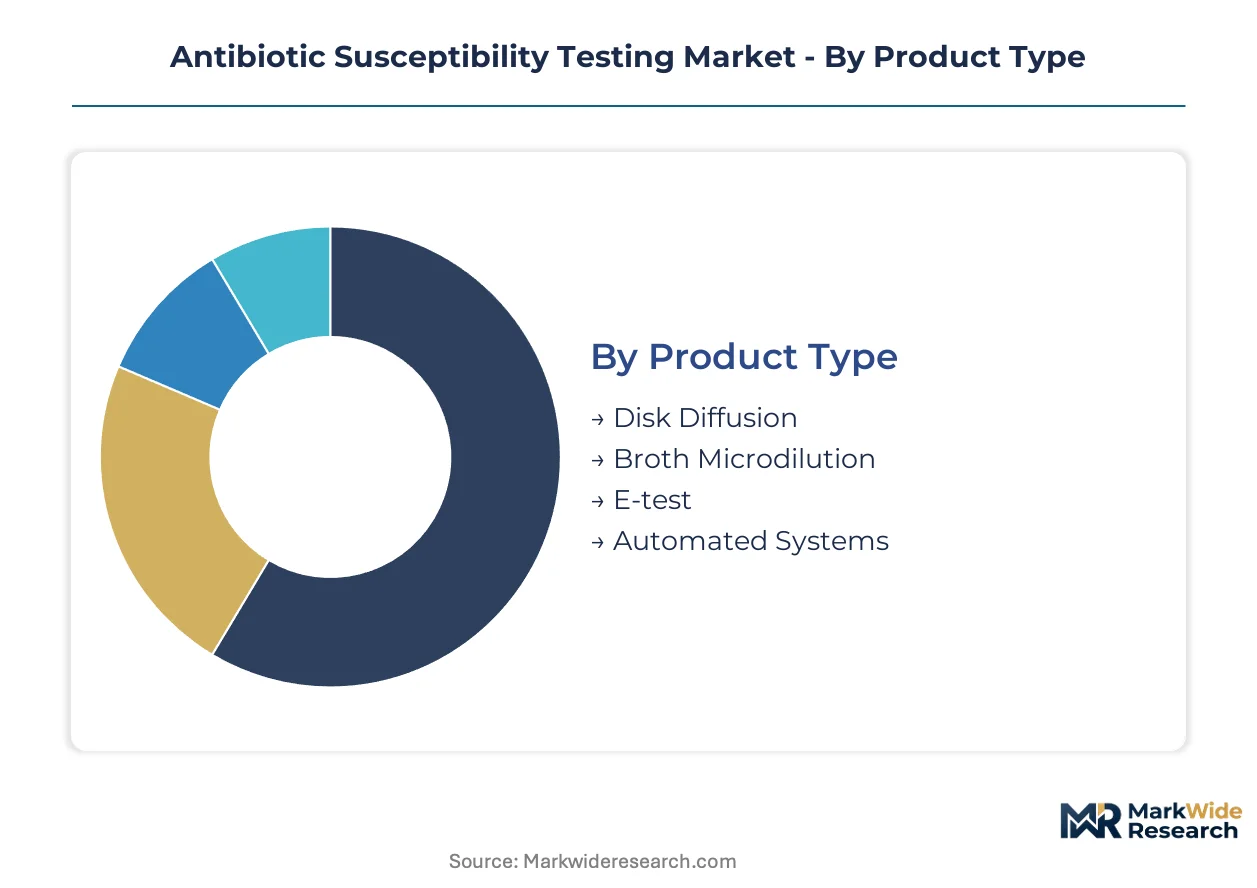
Segmentation in antibiotic susceptibility testing reveals how capital intensity, regulatory pathways, and clinical urgency create divergent margin profiles across product architectures. Laboratories allocate procurement budgets differently depending on throughput requirements, resistance surveillance mandates, and integration with existing microbiology workflows.
Product Type:
Margin pools concentrate in automated systems where instrument-reagent ecosystems generate recurring revenue streams, while manual methods compete on capital accessibility.
- Automated Systems:Integrated platforms combine optical detection, robotic sample handling, and software-based breakpoint interpretation. Demand clusters in United States academic medical centers and German hospital federations where antimicrobial stewardship mandates compress turnaround times for bloodstream infections.
- Broth Microdilution:Manual and semi-automated minimum inhibitory concentration determination remains the reference standard for regulatory submissions. Pharmaceutical manufacturers in Switzerland and the United Kingdom rely on broth microdilution for new antibiotic clinical trial protocols.
- Disk Diffusion:Zone diameter measurement using standardized antibiotic-impregnated disks dominates resource-limited settings.
- E-test:Gradient diffusion strips deliver quantitative MIC values without full automation investment.
Automated systems hold installed capacity. Broth microdilution is rotating up the share rankings.
End User:
Procurement authority and reimbursement pathways differ sharply across customer types, with hospital systems consolidating vendor relationships under multi-year service contracts.
- Hospitals:Integrated delivery networks negotiate total cost-per-test agreements spanning installation through software updates. United States hospital systems face mandatory NHSN resistance reporting under FDA AMR Action Plan enforcement.
- Clinical Laboratories:Independent and hospital-affiliated labs balance throughput demands against capital constraints. French and Italian regional laboratory networks are deploying automated platforms to meet EMA In Vitro Diagnostic Regulation clinical evidence standards.
- Pharmaceutical Companies:Sponsors require validated susceptibility data for regulatory submissions.
- Research Institutions:Academic centers prioritize flexibility across organism panels.
Hospital systems concentrate purchasing volume. Clinical laboratories are gaining procurement sophistication fastest.
Technology:
Platform convergence is blurring historical boundaries between phenotypic and molecular detection, with hybrid architectures capturing investment flows.
- Phenotypic Methods:Growth-based resistance detection maintains regulatory acceptance as the definitive standard. German and Dutch reference laboratories anchor European resistance surveillance networks on phenotypic confirmation protocols.
- Molecular Methods:PCR and mass spectrometry accelerate resistance gene detection before culture growth completes. United States emergency departments are deploying molecular platforms to reduce time-to-effective-therapy for sepsis protocols.
- Genotypic Methods:Whole genome sequencing and targeted resistance gene panels support outbreak investigation.
- Antimicrobial Susceptibility Testing:This category encompasses integrated workflows combining identification and susceptibility determination.
Phenotypic methods retain reference standard status. Molecular methods are climbing the fastest.
Application:
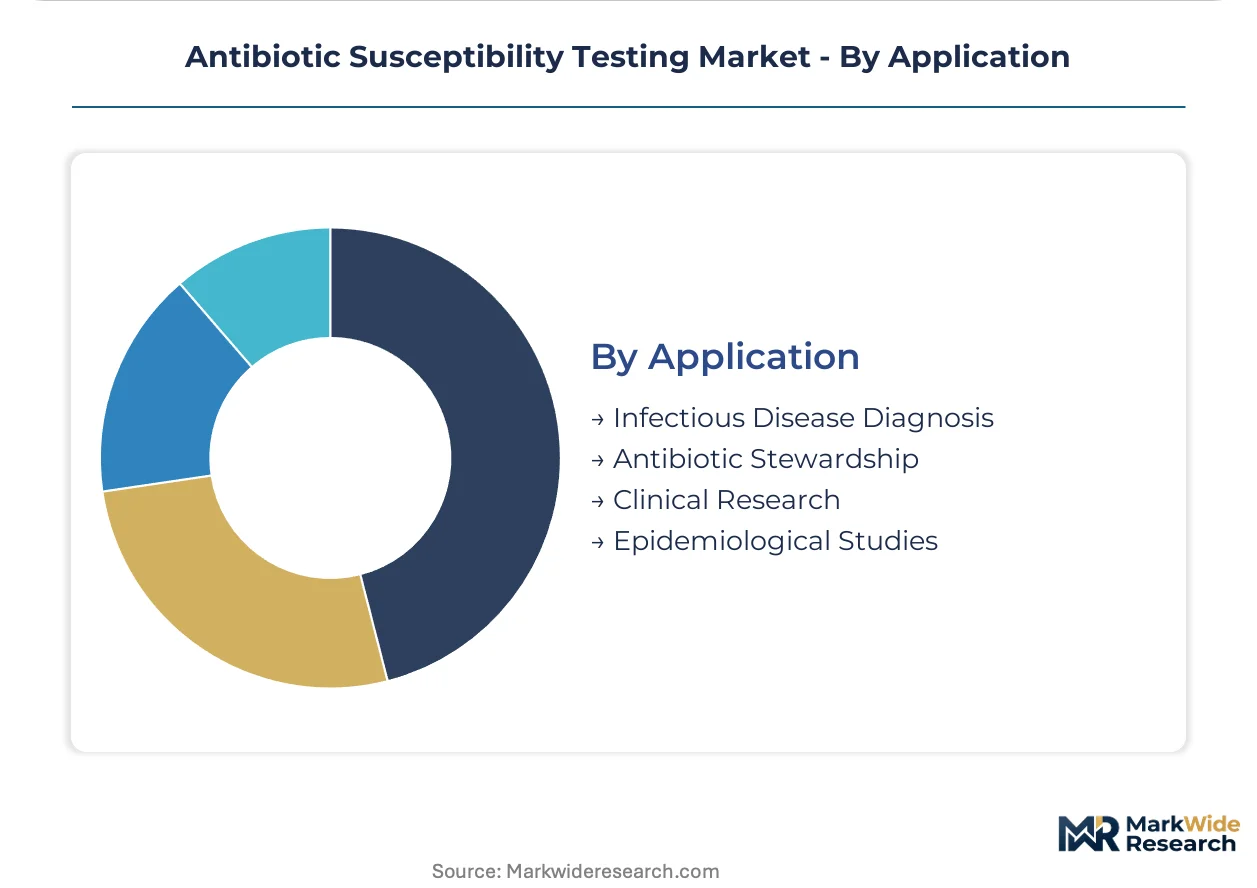
Reimbursement and regulatory tailwinds vary across use cases, with stewardship applications attracting capital allocation due to mandatory reporting requirements.
- Antibiotic Stewardship:Institutional programs require systematic susceptibility screening to meet utilization metric reporting. United States hospitals face CMS and Joint Commission accountability measures driving platform investment.
- Infectious Disease Diagnosis:Individual patient management demands rapid resistance profiling to guide empirical therapy transitions. French and Spanish hospital networks are integrating susceptibility results into pharmacy decision support systems.
- Clinical Research:Trial sponsors require standardized resistance data for regulatory dossiers.
- Epidemiological Studies:Public health surveillance depends on comparable resistance data across laboratory networks.
Infectious disease diagnosis holds procedure volume. Antibiotic stewardship is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States hospitals prioritize rapid turnaround automation for bloodstream infections, while European laboratories emphasize standardized resistance surveillance networks. Resource-constrained settings in Asia-Pacific continue reliance on manual phenotypic methods despite throughput limitations.
United States
Academic medical centers and integrated delivery networks drive automated platform procurement. FDA enforcement of antimicrobial resistance surveillance under the AMR Action Plan mandates standardized NHSN reporting formats. Boston and Baltimore hospital clusters deploy integrated mass spectrometry-susceptibility workflows to compress diagnostic intervals below eight hours.
Germany
Hospital federations negotiate consolidated service contracts spanning installation through software updates. EMA In Vitro Diagnostic Regulation clinical evidence standards extend development timelines for novel platform submissions. Reference laboratories in Berlin and Cologne anchor European resistance surveillance networks on phenotypic confirmation protocols.
France
Regional laboratory networks balance capital constraints against EMA compliance requirements. ANSM oversight of in vitro diagnostic devices governs premarket pathways for susceptibility testing platforms. Paris and Lyon metropolitan clusters integrate susceptibility results into pharmacy decision support systems for empirical therapy transitions.
Japan
PMDA regulatory frameworks emphasize clinical evidence standards for automated susceptibility platform approvals. METI industrial policy supports domestic diagnostic reagent manufacturing capacity. Tokyo and Osaka medical centers deploy hybrid phenotypic-molecular architectures for same-shift resistance detection in sepsis protocols.
India
Mid-volume laboratories and resource-constrained health systems depend on manual disk diffusion and broth microdilution methods. CDSCO oversight of in vitro diagnostic devices shapes premarket pathways for imported automated platforms. Mumbai and Bangalore hospital networks face procurement gaps where infrastructure investments exclude participation in premium automation segments.
Antibiotic Susceptibility Testing Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in antibiotic susceptibility testing. The upper tier commands instrument-reagent ecosystems that generate recurring revenue through locked consumable contracts. Mid-tier specialists compete on capital accessibility for laboratories excluded from premium automation procurement. Consolidated service contracts now displace unbundled instrument-reagent purchasing across multi-hospital systems. Strategic partnerships between platform developers and pharmacy informatics vendors reshape competitive boundaries around stewardship workflow integration.
Within the integrated diagnostics tier, bioMérieux SA and Becton, Dickinson and Company exemplify archetypes sustaining premium positioning through end-to-end microbiology workflow coverage. Thermo Fisher Scientific anchors North American market presence through clinical distribution infrastructure scale. These three occupy positions where instrument-reagent ecosystems and regulatory prevalidation capabilities create defensive moats against specialist challengers.
| Leading Market Players |
|---|
| bioMérieux SA |
| Becton, Dickinson and Company |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Bio-Rad Laboratories |
| Bruker |
| Accelerate Diagnostics |
| Merck KGaA |
| HiMedia Laboratories |
| Others |
Supply Flow & Price Mechanics
Gradient diffusion strip substitution for full automated platforms is redrawing procurement geography across mid-volume laboratories and compressing price premiums in European hospital networks. This input shift simultaneously expands supplier participation from reagent specialists in India and accelerates margin pressure on integrated instrument manufacturers locked into capital-intensive ecosystem models.
Pricing Analysis
Five-year total cost-per-test contracts now dominate procurement between United States integrated delivery networks and platform vendors, displacing unbundled instrument-reagent purchasing. Price differentiation hinges on antimicrobial panel breadth and FDA prevalidation status for NHSN reporting modules. Cost compression in manual method tiers is intensifying because Indian and Chinese reagent suppliers are expanding CE-marked product availability. Mid-volume clinical laboratories exhibit highest price sensitivity, while academic medical centers prioritize turnaround time over per-test economics.
Supply Chain Analysis
Strategic stockpiling of specialty culture media and antimicrobial reference powders prevails among German and Dutch reference laboratories confronting ECHA chemical restriction timelines. Manufacturing concentration in France, Germany, and the United States shapes reagent availability, with key inputs drawing from limited European chemical suppliers and North American pharmaceutical-grade antimicrobial producers. Single-source vulnerability in automated platform optical detection modules creates downstream risk. Distribution runs through consolidated GPO contracts and direct hospital system negotiations rather than fragmented channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibiotic susceptibility testing operates as a regulatory-entrenchment market where FDA and EMA clinical evidence standards create formidable switching costs against challenger platforms. Instrument-reagent ecosystem lock-in sustains incumbent pricing power across multi-year service contracts.
For Market Incumbents: Fortify defensive positioning by deepening backward integration into antimicrobial reference material production and accelerating AI-assisted interpretation modules ahead of breakpoint revision cycles. Molecular platform convergence from Accelerate Diagnostics and Bruker threatens phenotypic-dominant installed bases. Priority investment in pharmacy informatics vendor partnerships secures stewardship workflow anchoring against disintermediation. For New Entrants and Emerging Players: Differentiate on point-of-care deployment architectures for United States emergency departments and intensive care units where turnaround time compression commands premium positioning. White-space concentration sits in AI-assisted zone diameter interpretation tools for resource-constrained settings excluded from automated platform procurement. Direct contracting with mid-volume laboratory networks bypasses GPO consolidation barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated platform developers with regulatory prevalidation capabilities over point-solution specialists. Long-term viability over the next decade hinges on antimicrobial stewardship mandate expansion and NHSN reporting format standardization. Acquisition targets should demonstrate EMA IVDR clinical evidence packages and locked reagent contracts with German hospital federations. Watch for CLSI-EUCAST breakpoint harmonization completion as inflection signal for unified product architecture viability.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Interpretation Development | Machine learning modules for zone diameter analysis reduce technician time and standardize CLSI breakpoint application. |
| Pharmacy Informatics Partnership | Integration with Epic and Cerner stewardship dashboards embeds susceptibility results into clinical decision workflows. |
| EMA IVDR Clinical Evidence Investment | Prevalidation studies for European market entry extend development timelines but secure German hospital federation contracts. |
| Point-of-Care Platform Miniaturization | Decentralized susceptibility testing in emergency departments addresses sepsis protocol time-to-therapy requirements. |
| EU Green Deal Reagent Reformulation | Elimination of hazardous preservatives ahead of ECHA restrictions captures preferential positioning in ANSM-regulated networks. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA IVDR submission databases, hospital GPO contract disclosures, and CLSI breakpoint documentation. Primary interviews spanned microbiology laboratory directors, biomedical engineers at academic medical centers, antimicrobial stewardship pharmacists, and procurement managers at integrated delivery networks. Secondary validation drew from CMS NHSN surveillance protocols, EUCAST resistance threshold publications, and customs data on diagnostic reagent imports. Bottom-up sizing of installed instrument bases and reagent consumption patterns triangulates against top-down hospital laboratory expenditure estimates.
Segmentation dimensions modeled span product type (automated systems, broth microdilution, disk diffusion, E-test strips), end user (hospital systems, clinical laboratories, pharmaceutical sponsors), technology architecture (phenotypic, molecular, genotypic, hybrid), and application (antibiotic stewardship, infectious disease diagnosis, clinical research). CAGRs derive from regression analysis of historical procurement volumes against antimicrobial resistance surveillance mandate expansion timelines and hospital capital expenditure cycles. Forecast inputs incorporate EMA IVDR implementation pace and FDA AMR Action Plan enforcement intensity.
Material uncertainties — breakpoint revision timing, reagent supply disruptions, and antimicrobial stewardship mandate jurisdictional expansion — sit outside the modeled envelope. Forecasts reflect assumptions regarding CLSI-EUCAST harmonization completion and sustained hospital capital allocation to microbiology automation. Revision becomes warranted when molecular platform price-performance crosses thresholds that accelerate phenotypic method displacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pancreatic Elastase Testing Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Urine Sediment Testing Market
Testing Services
Staphylococcus Aureus Testing Market
Testing Services
Adiponectin Testing Market
Testing Services
Hemostasis Testing Systems Market
Testing Services
Global Roadside Drug Testing Devices Market
Testing Services
Redox Meter Market
Testing Services
Global Diagnostic Testing Market
Testing Services
Global Forensic Testing Services Market
Testing Services
Host Cell Protein Testing Market
Testing Services
Antimicrobial Susceptibility Testing Market
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
Helicobacter Pylori Testing Market
Testing Services
Zika Virus Testing Market
Testing Services
Global Multiplex Assays Market