
 Global Virology Testing Market | 2026-2036
Global Virology Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virology Testing Market Foresight
Chinese reagent manufacturers is decoupling from Western supply chains for polymerase chain reaction primers and enzyme mixes. F. Hoffmann-La Roche AG anchors European high-throughput diagnostics through integrated instrument-reagent systems. Abbott Laboratories competes in point-of-care virology with cartridge-based platforms. Danaher Corporation leverages its Life Sciences portfolio to control upstream sample preparation workflows.
Virology testing encompasses laboratory methods that detect, quantify, or characterize viral particles, antigens, nucleic acids, or host immune responses in clinical, research, or public health specimens, typically requiring sensitivity thresholds of 10–1,000 copies per milliliter for molecular assays. These methods serve outbreak surveillance, therapeutic monitoring, transfusion safety, and vaccine efficacy validation across healthcare and biopharmaceutical value chains. Polymerase chain reaction and nucleic acid amplification dominate routine clinical workflows due to established reimbursement and laboratory infrastructure. Next-generation sequencing is displacing single-target panels in research institutions and public health agencies for pathogen discovery and variant tracking.
The FDA regulates in vitro diagnostic assays under CLIA complexity classifications that determine where testing may occur, while the EMA's IVDR framework in Europe demands enhanced clinical evidence for CE-marked virology products. WHO prequalification pathways shape market access for manufacturers targeting low- and middle-income country procurement programs. Stakeholders must monitor how decentralized testing waivers and genomic surveillance mandates reshape capital allocation between centralized laboratory systems and distributed point-of-care networks.
Market Dynamics
The virology testing sector is restructuring around molecular assay complexity tiers, with the FDA's CLIA framework determining where high-sensitivity nucleic acid amplification testing can physically occur and who controls the associated reagent revenue streams.
Growth Catalysts
- Next-generation sequencing uptake:Public health agencies in the United States, Germany, and China are replacing single-target PCR panels with whole-genome pathogen surveillance for outbreak tracking and variant discovery.
- CLIA complexity waivers:The FDA's emergency use authorization pathway for moderate-complexity molecular assays is expanding point-of-care virology access beyond centralized laboratories into physician offices and retail clinics.
- Biopharmaceutical pipeline expansion:Antiviral drug development programs require companion diagnostic partnerships, driving demand for quantitative viral load assays with 10–1,000 copies per milliliter sensitivity thresholds.
Market Restraints
- Reagent supply concentration:Polymerase chain reaction enzyme mixes and synthetic primers depend on concentrated upstream chemical synthesis capacity, with Chinese manufacturers decoupling from Western supply chains.
- Capital intensity of sequencing infrastructure:Next-generation sequencing platforms require instrument investments exceeding two million dollars per installation, limiting adoption to well-capitalized reference laboratories and academic medical centers.
- IVDR clinical evidence requirements:The EMA's In Vitro Diagnostic Regulation demands expanded performance studies for CE-marked virology products, extending time-to-market for European commercialization by 18–24 months.
Strategic Opportunities
- Decentralized testing networks:India's district hospital system and primary health centers present underpenetrated demand for cartridge-based molecular platforms that operate without cold chain logistics.
- Multiplex respiratory panels:Convergence of digital microfluidics with isothermal amplification enables simultaneous detection of SARS-CoV-2, influenza, and RSV from single patient specimens.
- WHO prequalification procurement:Manufacturers achieving WHO prequalification status gain access to Global Fund and PEPFAR purchasing programs targeting low- and middle-income country disease surveillance.
Industry Challenges
- Bioinformatics specialist scarcity:Next-generation sequencing interpretation requires computational biology expertise that outpaces current clinical laboratory training pipelines, creating hiring bottlenecks for variant calling and phylogenetic analysis.
- Laboratory information system integration:Molecular virology instruments generate data formats incompatible with legacy hospital electronic health records, forcing middleware development expenditures and delayed result reporting workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virology Testing Market |
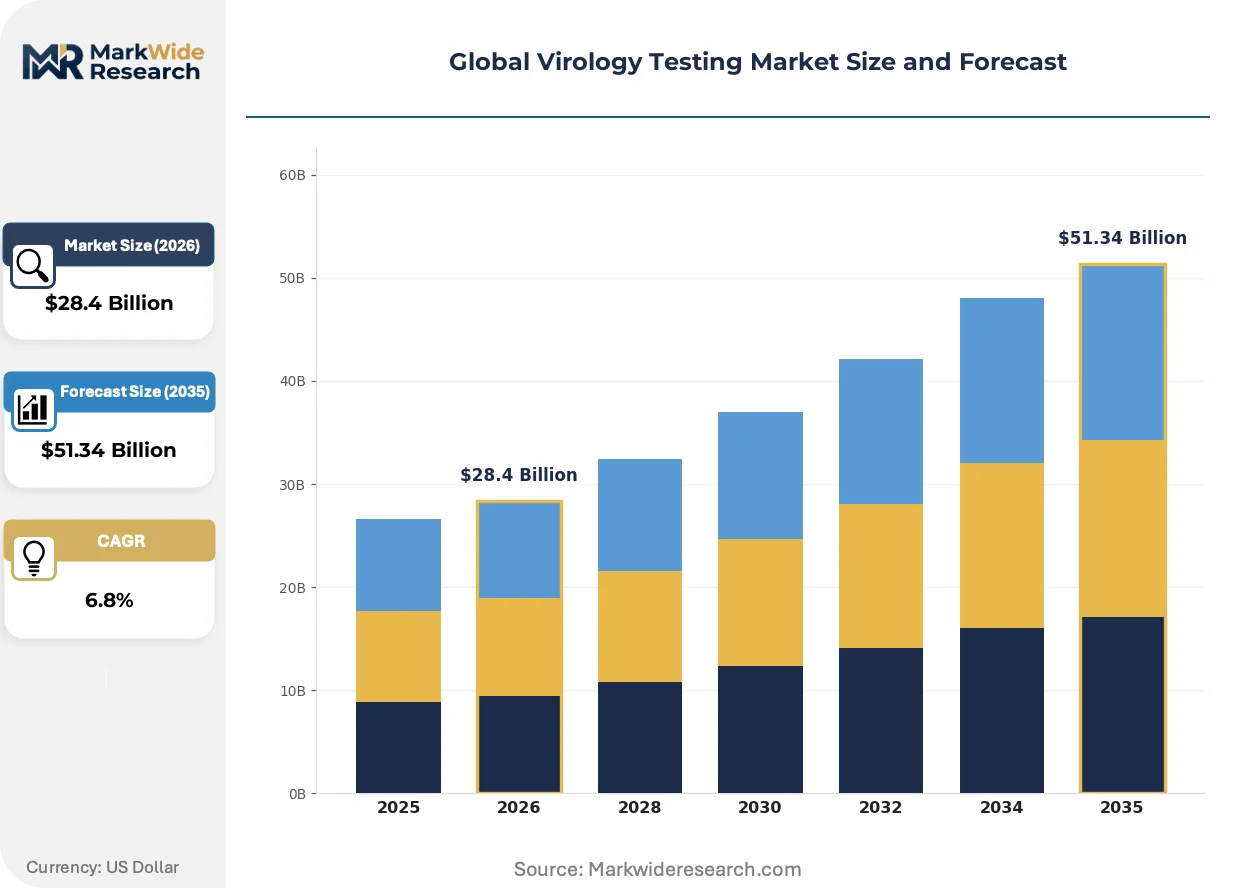
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Polymerase Chain Reaction, Antigen Test, Antibody Test, Viral Culture, Nucleic Acid Amplification, Western Blot Sample Type: Blood, Saliva, Nasal Swab, Urine, Cerebrospinal Fluid, Tissue Biopsy End User: Diagnostic Laboratories, Research Institutions, Blood Banks, Universities, Pharmaceutical Companies, Public Health Agencies Technology: Real-Time PCR, ELISA, Next-Generation Sequencing, Microarray, Immunofluorescence, Flow Cytometry |
| Companies Covered | Hologic Inc., Bio-Rad Laboratories Inc., F. Hoffmann-La Roche AG, Agilent Technologies Inc., bioMérieux SA, Abbott Laboratories, Danaher Corporation, QIAGEN N.V., Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virology Testing Market Shifts & Advancements
Digital PCR platforms are compressing quantitative viral load measurement timelines while CRISPR-based diagnostic methods challenge nucleic acid amplification's cost structure. These shifts are redistributing value capture between instrument manufacturers, reagent suppliers, and service providers.
Digital PCR technology is integrating into therapeutic monitoring workflows for chronic viral infections. Oncology and transplant centers in the United States and Germany are adopting absolute quantification methods that eliminate standard curve dependencies. This technology is integrating viral load tracking into precision medicine protocols, enabling earlier detection of treatment failure and resistance mutations.
The EMA's IVDR framework is tightening clinical evidence requirements for self-declared virology devices. Manufacturers must now submit analytical and clinical performance studies to notified bodies rather than internal technical files. High-volume immunoassay producers serving European diagnostic laboratories are restructuring quality management systems and post-market surveillance programs to maintain CE marking.
Consolidated procurement by integrated delivery networks is displacing individual hospital laboratory purchasing autonomy. Large health systems in the United States are negotiating enterprise-wide reagent contracts with preferred molecular platform vendors. This concentration is most visible in multi-hospital networks spanning Texas, Florida, and California, where standardization reduces assay variability but limits smaller manufacturers' market access.
Global Virology Testing Market Segmentation
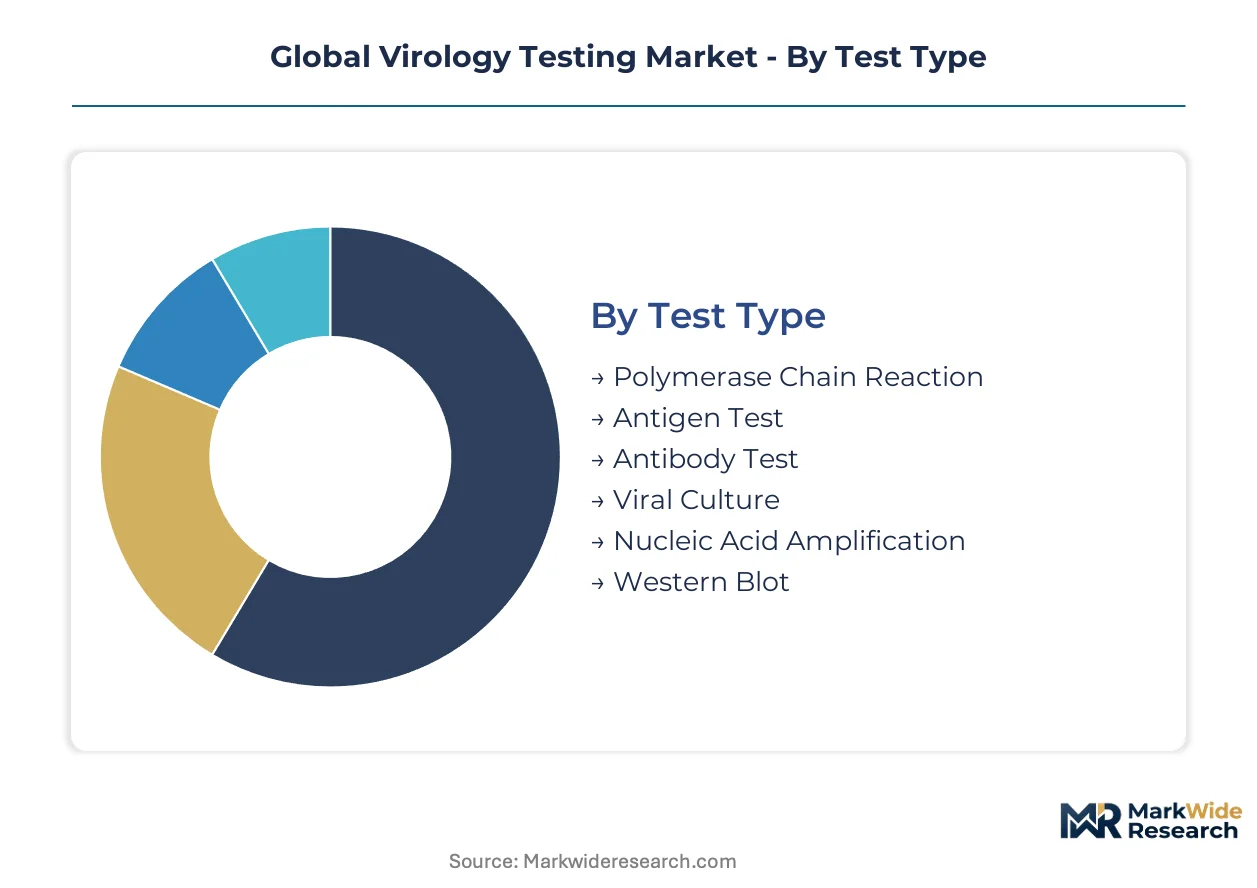
Virology testing segmentation reflects competing priorities between standardized high-throughput workflows and customized assay configurations. Test type and technology choices determine capital allocation, regulatory pathway complexity, and reagent supply relationships across clinical and research settings.
Test Type:
Customization versus standardization tension manifests most acutely in test type selection, where laboratory infrastructure constraints and sensitivity requirements drive divergent procurement patterns.
- Polymerase Chain Reaction:Gold-standard molecular amplification achieving 10–1,000 copies per milliliter sensitivity through thermal cycling and fluorescent probe detection. Demand concentrates in United States diagnostic laboratories and German hospital networks seeking quantitative viral load monitoring for HIV and hepatitis C therapeutic management.
- Antigen Test:Immunochromatographic lateral flow devices delivering qualitative results within 15–30 minutes without laboratory infrastructure. China's primary health centers and India's district hospitals are expanding procurement of cartridge-based formats for point-of-care respiratory virus screening.
- Antibody Test:Serological detection of host immune response through ELISA or rapid immunodiagnostic platforms.
- Viral Culture:Traditional cell-based isolation methods retaining relevance for phenotypic characterization and live vaccine quality control.
- Nucleic Acid Amplification:Isothermal methods including LAMP and NASBA enabling amplification without thermal cyclers.
- Western Blot:Confirmatory serological technique with high specificity for HIV and Lyme disease diagnosis.
Leading the category by volume: Polymerase Chain Reaction. Expanding most quickly: Antigen Test.
Sample Type:
Cost tier stratification separates high-complexity invasive collection from scalable non-invasive alternatives, with reimbursement rates and patient compliance driving portfolio decisions.
- Blood:Plasma and serum specimens enabling quantitative viral load measurement and serological profiling through standardized phlebotomy protocols. United States reference laboratories and German clinical chemistry networks process high volumes for HIV, hepatitis B, and cytomegalovirus monitoring.
- Saliva:Non-invasive collection eliminating healthcare worker exposure and cold chain logistics requirements. China's mass screening programs and United States workplace testing initiatives are validating saliva-based SARS-CoV-2 nucleic acid protocols for population-scale surveillance.
- Nasal Swab:Anterior nares and nasopharyngeal sampling dominating respiratory virus detection workflows.
- Urine:Cytomegalovirus and BK virus detection in transplant recipients through PCR-based protocols.
- Cerebrospinal Fluid:High-sensitivity molecular testing for herpes simplex virus and enterovirus encephalitis diagnosis.
- Tissue Biopsy:Histopathological and in situ hybridization methods for localized viral infection confirmation.
Highest reimbursement tier: Cerebrospinal Fluid and Tissue Biopsy. Steepest volume expansion: Saliva.
End User:
Customer type fragmentation creates divergent purchasing behaviors, with centralized procurement by integrated networks contrasting decentralized academic decision-making.
- Diagnostic Laboratories:High-throughput clinical reference laboratories processing thousands of specimens daily through automated molecular platforms. United States commercial laboratory chains and German hospital-affiliated labs dominate reagent consumption for routine viral load quantification.
- Research Institutions:Academic medical centers and public health institutes requiring flexible assay configurations for pathogen discovery. China's CDC network and United States university laboratories are deploying next-generation sequencing for variant surveillance and novel virus characterization.
- Blood Banks:Nucleic acid testing for transfusion-transmitted virus screening including HIV, hepatitis B, and hepatitis C.
- Universities:Basic virology research programs utilizing cell culture and molecular cloning techniques.
- Pharmaceutical Companies:Companion diagnostic development and clinical trial virology monitoring for antiviral drug programs.
- Public Health Agencies:Population-level surveillance and outbreak investigation through centralized testing capacity.
Dominating procurement volume: Diagnostic Laboratories. Gaining share fastest: Research Institutions.
Technology:
Maturity gradient separates established platforms with proven reimbursement pathways from emerging methods requiring clinical validation investment.
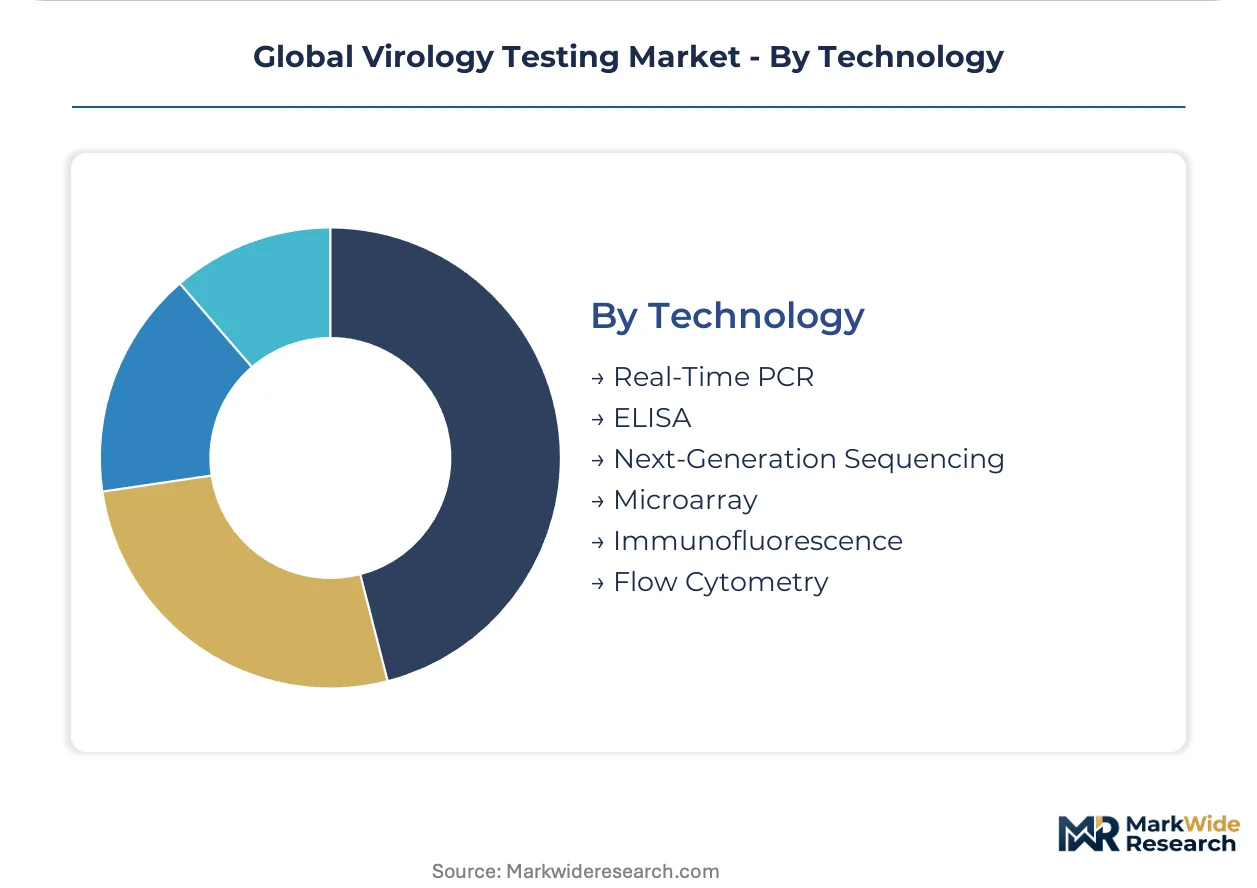
- Real-Time PCR:Quantitative amplification with fluorescent reporter chemistries enabling absolute viral load quantification through standard curve or digital methods. United States oncology centers and German transplant programs require high-precision cytomegalovirus and Epstein-Barr virus monitoring for immunocompromised patient management.
- Next-Generation Sequencing:Massively parallel sequencing platforms delivering whole-genome pathogen identification and variant characterization. China's national surveillance network and United States CDC laboratories are replacing targeted panels with metagenomic approaches for unknown pathogen detection.
- ELISA:Enzyme-linked immunosorbent assays for high-throughput antibody detection in seroprevalence studies.
- Microarray:Multiplexed nucleic acid detection enabling simultaneous screening of multiple viral targets.
- Immunofluorescence:Direct and indirect fluorescent antibody staining for rapid viral antigen visualization.
- Flow Cytometry:Multiparametric cellular analysis for HIV immunophenotyping and viral receptor studies.
Widest installed base: Real-Time PCR. Climbing the fastest: Next-Generation Sequencing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic primer synthesis clusters in China's Jiangsu and Zhejiang provinces anchor reagent supply chains for molecular virology assays worldwide. German chemical manufacturers and United States enzyme engineering firms compete for high-purity polymerase sourcing. Regulatory divergence between FDA, EMA, and NMPA pathways shapes where manufacturers validate new assay formats.
United States
Commercial laboratory chains and integrated delivery networks drive centralized procurement of high-throughput molecular platforms. FDA CLIA complexity waivers expand moderate-complexity testing into physician offices and retail clinics. The Boston-Cambridge corridor concentrates CRISPR diagnostic startups challenging nucleic acid amplification economics.
Germany
Hospital-affiliated diagnostic laboratories and academic medical centers anchor European demand for quantitative viral load monitoring. EMA IVDR implementation demands enhanced clinical evidence studies, extending CE-marking timelines. The Rhine-Main metropolitan region hosts contract research organizations supporting virology assay validation.
China
National CDC network expansion and mass screening programs consume cartridge-based respiratory panels at district hospital level. NMPA regulatory reforms accelerate domestic IVD registration while tightening import requirements. The Yangtze River Delta clusters reagent manufacturers decoupling from Western enzyme supply chains.
India
District hospital systems and primary health centers present underpenetrated demand for cold-chain-independent molecular platforms. CDSCO streamlined approval pathways for WHO-prequalified diagnostics accelerate market entry. Hyderabad-Bengaluru corridor concentrates contract manufacturing for global virology reagent suppliers.
United Kingdom
NIHR-funded research institutions deploy next-generation sequencing for pathogen discovery and variant surveillance. MHRA post-Brexit regulatory autonomy permits divergence from EMA IVDR implementation timelines. The Cambridge-Oxford-London triangle anchors genomic surveillance consortia replacing single-target PCR panels.
Global Virology Testing Market Competitive Landscape
Global majors compete with regional champions across instrument-reagent integration and point-of-care decentralization. Market structure tiers between consolidated high-throughput platform vendors and fragmented specialty reagent suppliers. Three archetypes dominate: integrated system providers controlling workflow automation, cartridge-based point-of-care specialists, and upstream sample preparation technology holders. Competitive moves concentrate on strategic partnerships for companion diagnostic development and vertical integration into enzyme manufacturing.
Within the integrated system tier, F. Hoffmann-La Roche AG and Danaher Corporation exemplify instrument-reagent bundling strategies that capture recurring revenue streams. Abbott Laboratories occupies a distinct position in decentralized testing through cartridge-based platform architectures. These three entities represent divergent bets on where value accrues—centralized laboratory automation versus distributed point-of-care networks versus upstream workflow control.
| Leading Market Players |
|---|
| Hologic Inc. |
| Bio-Rad Laboratories Inc. |
| F. Hoffmann-La Roche AG |
| Agilent Technologies Inc. |
| bioMérieux SA |
| Abbott Laboratories |
| Danaher Corporation |
| QIAGEN N.V. |
| Thermo Fisher Scientific Inc. |
| Others |
Supply & Pricing Matrix
Captive enzyme manufacturing by Chinese reagent producers anchors both supply security and pricing power in molecular virology assays, with in-house polymerase production insulating domestic manufacturers from Western input cost volatility while compressing margins for instrument-reagent bundlers dependent on outsourced chemical synthesis.
Pricing Analysis
Service-bundling separates instrument-reagent contracts from unbundled reagent-only procurement, with Roche and Danaher capturing recurring revenue through multi-year service agreements covering calibration, maintenance, and assay updates. Three-tier pricing structure across premium, standard, and economy levels stratifies by sensitivity threshold and automation grade, with point-of-care cartridge formats commanding premium positioning against laboratory bulk reagents. Pricing pressure stems from Chinese manufacturers undercutting Western enzyme suppliers on PCR master mix costs. Academic medical centers exhibit highest price sensitivity due to constrained capital budgets, while integrated delivery networks leverage volume consolidation for standard-tier pricing.
Supply Chain Analysis
Domestic-content mandates from China's NMPA are reshaping sourcing patterns, requiring local manufacturing for IVD registration and accelerating decoupling from Thermo Fisher and QIAGEN enzyme imports. Synthetic primer synthesis clusters in Jiangsu and Zhejiang provinces, with high-purity polymerase production resting on German chemical engineering and United States enzyme engineering expertise. Single-source vulnerability concentrates in Taq polymerase supply, where three suppliers dominate global pharmaceutical-grade output. Distribution runs through diagnostic laboratory chains and hospital-affiliated reference laboratories in the United States and Germany, with cold-chain logistics requirements limiting direct-to-clinic models for temperature-sensitive reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with control over upstream enzyme manufacturing emerging as the decisive lever separating margin leaders from reagent-dependent followers across the analysis window.
For Market Incumbents: Deepen captive supply of polymerase and reverse transcriptase enzymes through acquisition of Chinese or German chemical synthesis specialists, insulating against NMPA localization requirements and input cost volatility. Reinforce instrument-reagent bundling with predictive maintenance software that locks diagnostic laboratories into proprietary consumable streams, defending against cartridge-based point-of-care disintermediation from Abbott and emerging CRISPR diagnostic platforms. For New Entrants and Emerging Players: Launch via WHO prequalification procurement channels targeting India's district hospital system and sub-Saharan African disease surveillance programs, bypassing entrenched relationships in United States and German reference laboratories. White-space concentrates in cold-chain-independent isothermal amplification platforms for resource-limited settings, with cartridge-based multiplex respiratory panels offering the most penetrable entry point against centralized PCR infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated system providers seeking enzyme manufacturing capabilities, with financial sponsor rollup of regional reagent specialists as secondary liquidity route. Long-term viability hinges on positioning upstream of instrument-reagent bundlers, with bioinformatics software for NGS interpretation representing the acquisition archetype with highest margin expansion potential. Watch FDA CLIA complexity waiver expansion as inflection signal for point-of-care market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | Antiviral drug developers require viral load assays with 10–1,000 copies per milliliter sensitivity thresholds. |
| Enzyme Manufacturing Acquisition | Captive polymerase production insulates against Chinese supply chain decoupling and NMPA localization mandates. |
| WHO Prequalification Pathway | Global Fund and PEPFAR procurement programs unlock low- and middle-income country disease surveillance demand. |
| Digital PCR Platform Launch | Oncology and transplant centers in Germany and the United States adopt absolute quantification for therapeutic monitoring. |
| NGS Bioinformatics Development | Computational biology expertise scarcity creates hiring bottlenecks for variant calling and phylogenetic analysis workflows. |
Research Methodology
Document review covered FDA 510(k) filings, EMA IVDR technical documentation, WHO prequalification assessment reports, and CDC laboratory surveillance databases, complemented by interviews with diagnostic laboratory directors, hospital procurement committee chairs, IVD regulatory affairs specialists, and biopharmaceutical companion diagnostic alliance managers. Secondary validation drew from CMS Medicare reimbursement schedules, GPO contract databases, and NIH research funding disclosures. Bottom-up reagent volume estimates triangulated against top-down instrument installed base calculations.
Quantitative outputs span the projection horizon across test type, technology platform, sample source, and end-user facility tier, with additional segmentation by regulatory approval pathway and reimbursement status. CAGRs were derived from logistic diffusion curves fitted to instrument placement trajectories and reagent consumption per installed unit. Forecast inputs incorporated CLIA complexity waiver expansion scenarios, IVDR implementation delay assumptions, and Chinese domestic substitution elasticity for imported enzyme components.
The model assumes a particular technology adoption path; alternative pathways for CRISPR-based diagnostics displacing nucleic acid amplification would alter the outlook for PCR reagent demand and instrument replacement cycles. Forecasts reflect assumptions about regulatory harmonization timelines, supply chain reshoring momentum, and biopharmaceutical pipeline attrition rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Nipah Virus (Niv) Infection Testing Market
Testing Services
North America Testing Inspection and Certification (TIC) Market
Testing Services
Special Coagulation Tests Market
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
Carbapenem-Resistant Enterobacteriaceae Testing Market
Testing Services
Europe Antimicrobial Susceptibility Testing Market
Testing Services
US Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Point of Care Lipid Test Market
Testing Services
Home Care Testing Market
Testing Services
Thyroid Test Market
Testing Services
Hospital Acquired Disease Testing Market
Testing Services
US C-Reactive Protein Testing Market
Testing Services
Antibiotic Residue Test Kits Market
Testing Services
Antibiotic Susceptibility Testing Market
Testing Services
Platelet Function Test Market
Testing Services
Vaginal Panel Testing Market