
 Global Prefilled Syringes Drug Molecules Market | 2026-2036
Global Prefilled Syringes Drug Molecules Market Size, Share, and Industry Trends Forecast 2026-2036
Global Prefilled Syringes Drug Molecules Market Foresight
Market Context with Strategic Players
Germany is rewriting supply dynamics for glass-based prefilled systems as SCHOTT Pharma anchors European borosilicate capacity with captive tubing operations. Becton Dickinson and Company (BD) dominates North American safety syringe production through backward integration into needle shielding. Gerresheimer AG leverages its dual glass-polymer platform to compete across biologic viscosity ranges.
Technical Definition and Structural Segments
Prefilled syringes drug molecules comprise sterile pharmaceutical agents pre-loaded into ready-to-use injection systems with specified break-loose and glide-force parameters for automated administration. These systems eliminate vial-to-syringe transfer, reducing contamination risk and dosing error in biologic delivery. Monoclonal antibodies occupy the largest formulation volume due to chronic disease dosing frequency, while polymer syringes represent the fastest-expanding technology segment as cyclic olefin polymers displace glass for protein stability. Lyophilized powder formulations command premium positioning where cold-chain constraints limit liquid biologic distribution.
Regulatory Frame and Forward-Looking Close
The FDA enforces container closure integrity under 21 CFR Part 4 for combination products, while EMA MDR requirements and ISO 11040-4 govern dimensional and functional performance across European markets. These frameworks compel manufacturers to validate extractables and leachables profiles before product approval, raising barriers for unqualified component suppliers. Stakeholders must monitor evolving USP <788> particulate standards and polymer biocompatibility testing protocols as material innovation outpaces harmonized guidance.
Market Dynamics
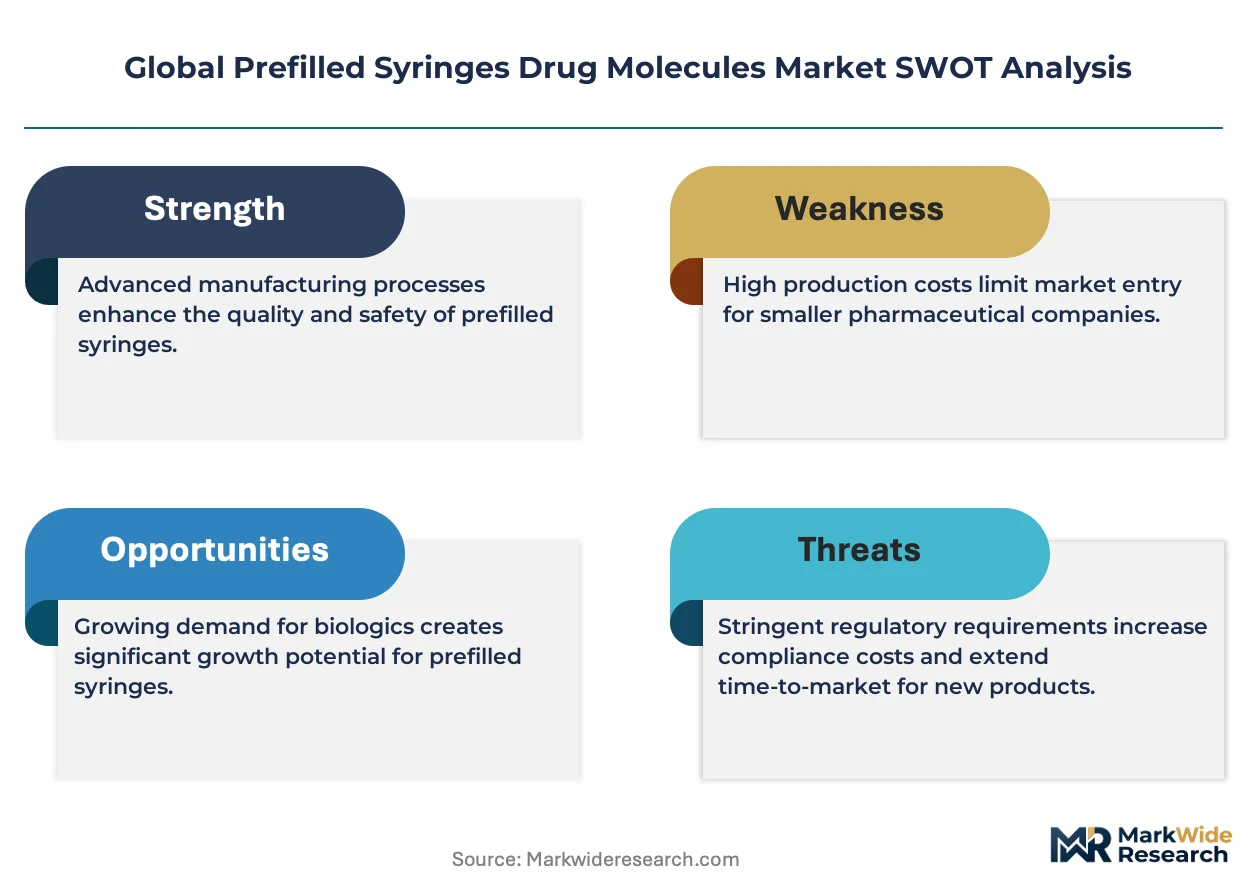
Biologics manufacturers are consolidating procurement around vertically integrated syringe suppliers capable of certifying container closure integrity under 21 CFR Part 4, compressing vendor qualification timelines and raising capital barriers for component specialists.
Growth Catalysts
- MDR compliance mandates:European device manufacturers must validate extractables profiles before 2025 deadlines, forcing rapid upgrades to polymer syringe platforms with documented leachable performance.
- Chronic disease dosing frequency:Rheumatoid arthritis and diabetes patients require weekly self-injection, expanding demand for ready-to-use systems with ergonomic plunger-rod designs.
- Borosilicate glass supply concentration:Germany's captive tubing operations anchor European sterile injectable capacity, reducing lead times for high-viscosity monoclonal antibody formulations.
Market Restraints
- Silicone oil instability:Protein aggregation triggered by lubricant migration limits shelf life for sensitive biologics, forcing secondary packaging investments.
- Specialty polymer feedstock volatility:Cyclic olefin polymer resin prices fluctuate with benzene derivative markets, compressing margins for disposable system manufacturers.
- ISO 11040-4 dimensional tolerances:Sub-millimeter variance requirements for needle hub interfaces disqualify regional molders lacking precision metrology capabilities.
Strategic Opportunities
- Lyophilized powder formats:Cold-chain infrastructure gaps in India and Brazil create demand for reconstitution-ready systems with dual-chamber designs.
- Wearable injector convergence:Integration of prefilled syringe cartridges with electronic autoinjectors opens chronic disease management protocols previously limited to clinical settings.
- Japan's PMDA QMS harmonization:Streamlined quality management system recognition for foreign manufacturers reduces regulatory duplication costs for polymer platform entrants.
Industry Challenges
- Extractables toxicology expertise:Shortage of analytical chemists capable of correlating polymer additive migration with biologic stability endpoints extends validation timelines.
- Legacy glass-to-polymer line conversion:Sterile filling equipment designed for borosilicate dimensional specifications requires substantial retooling for cyclic olefin polymer barrel compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Prefilled Syringes Drug Molecules Market |
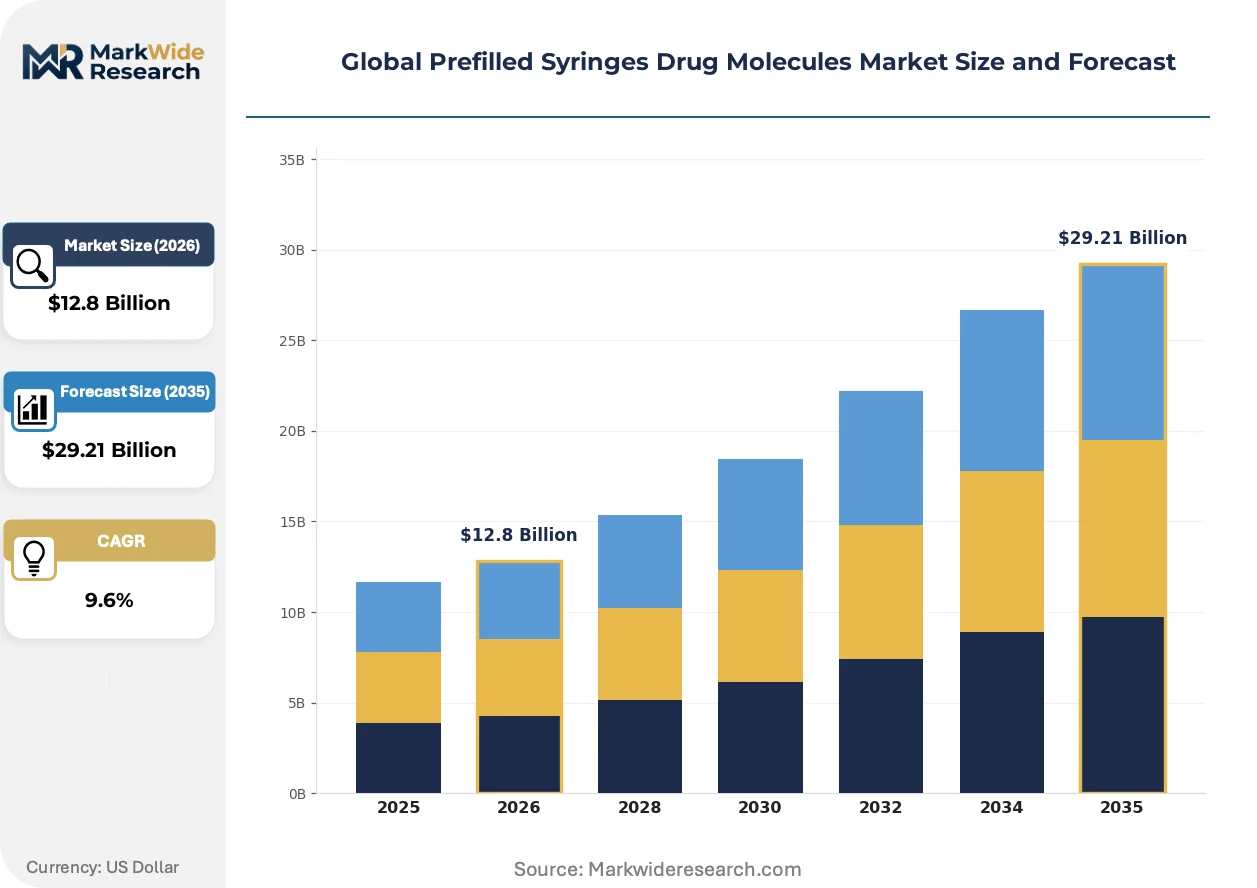
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $29.21 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Molecule Type: Monoclonal Antibodies, Vaccines, Insulin, Hormones, Blood Factors, Peptides Formulation Type: Liquid, Lyophilized Powder, Suspension, Emulsion, Gel, Others End User: Hospitals, Specialty Clinics, Diagnostic Centers, Long-Term Care Facilities, Ambulatory Surgery Centers Technology: Glass Syringes, Polymer Syringes, Hybrid Systems, Safety Injection Devices, Auto-Disable Syringes |
| Companies Covered | Becton Dickinson and Company (BD), Gerresheimer AG, SCHOTT Pharma, West Pharmaceutical Services, Inc., Nipro Corporation, AptarGroup, Inc., Terumo Corporation, Stevanato Group, Ypsomed AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Prefilled Syringes Drug Molecules Market Shifts & Advancements
Material science breakthroughs and regulatory harmonization efforts are converging to redefine performance benchmarks for container closure systems, with particular emphasis on protein stability and patient self-administration ergonomics.
Cyclic olefin polymer syringe barrels are migrating from glass-dominated oncology and immunology applications into broader chronic disease categories. Rheumatology clinics in the United States and Germany are adopting these platforms for temperature-sensitive biologics. The shift is compressing qualification cycles for secondary suppliers while elevating extractables documentation requirements.
EMA's Medical Device Regulation implementation is forcing combination product manufacturers to maintain technical documentation repositories accessible to notified bodies for unannounced audits. Sterile injectable facilities across Italy and the Netherlands are restructuring quality management systems to accommodate device-specific vigilance reporting. Small molecule injectable producers without prior device experience face steepest compliance adaptation costs.
Hospital procurement consortia are consolidating vendor panels around suppliers offering integrated safety-engineered needle shielding. Group purchasing organizations in the United States are disqualifying standalone syringe manufacturers lacking needlestick prevention technology. This concentration is visible most acutely in academic medical center networks across California and Texas, where consolidated sourcing agreements now span prefilled delivery systems for entire therapeutic categories.
Global Prefilled Syringes Drug Molecules Market Segmentation
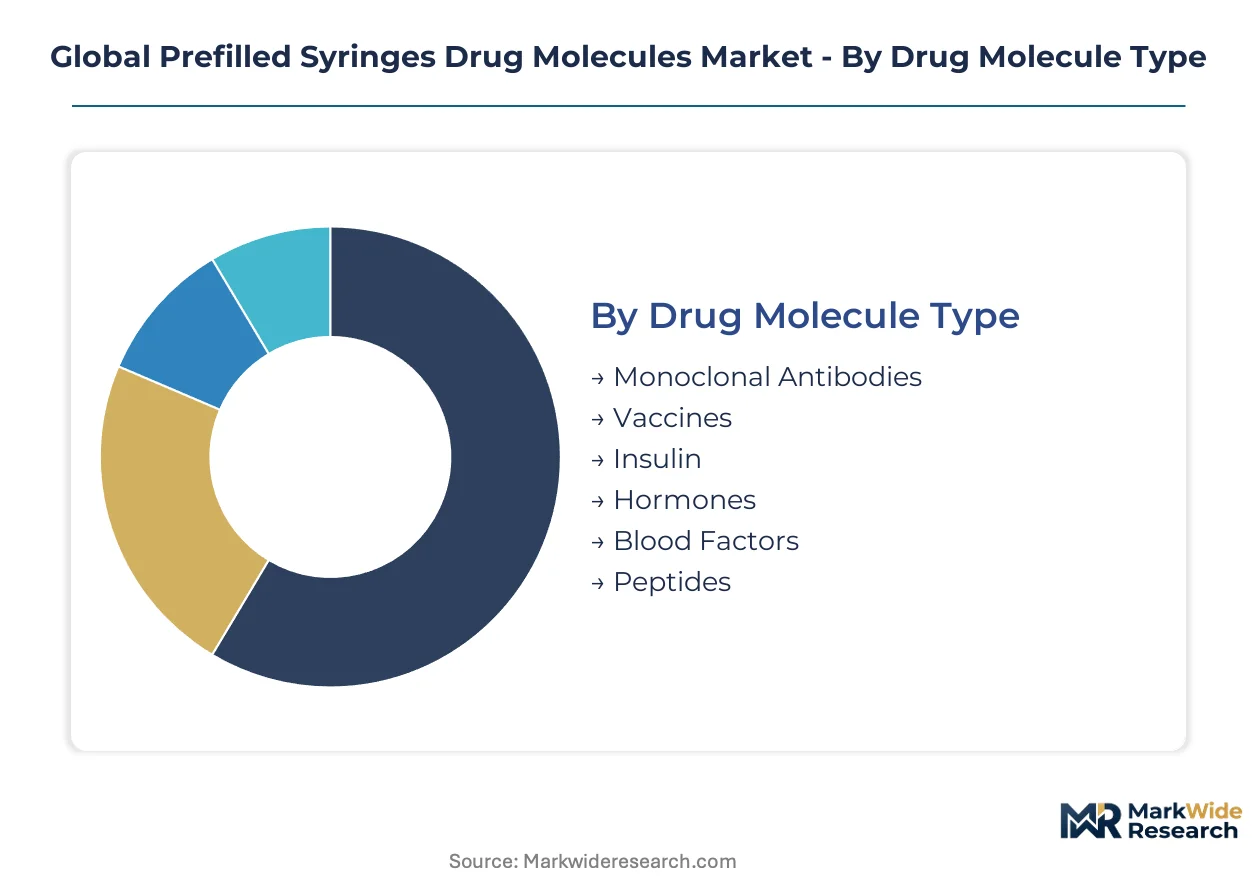
Segmentation in prefilled syringes drug molecules reveals how formulation requirements, delivery technologies, and care settings fragment procurement specifications. Understanding these dimensions exposes where polymer platforms displace glass and which drug classes drive safety-engineered device adoption.
Drug Molecule Type:
Cost tier stratification in drug molecules separates chronic disease biologics from acute intervention therapies, with pricing power concentrated in high-frequency administration categories.
- Monoclonal Antibodies:High-viscosity protein formulations requiring break-loose force below 10N for patient self-administration. Rheumatoid arthritis and psoriasis protocols in the United States and Germany consume the largest volumes, with weekly dosing regimens driving demand for ergonomic plunger-rod designs.
- Vaccines:Temperature-sensitive formulations demanding container closure integrity across cold-chain distribution. Mass immunization programs in India and Brazil prioritize auto-disable syringes for single-use compliance, with UNICEF procurement specifications influencing global tender requirements.
- Insulin:Rapid-acting and long-acting analogues for diabetes management.
- Hormones:Reproductive and endocrine therapies with narrow therapeutic windows.
- Blood Factors:Hemophilia treatments requiring high-purity containment systems.
- Peptides:Short-chain protein therapeutics with stability challenges in liquid formulations.
Monoclonal antibodies hold installed capacity. Peptides are rotating up the share rankings.
Formulation Type:
Application requirements dictate formulation selection, with distribution infrastructure maturity determining whether liquid or reconstitution-ready formats prevail in specific geographies.
- Liquid:Ready-to-inject solutions dominating chronic disease categories where patient compliance depends on elimination of reconstitution steps. United States rheumatology clinics prefer liquid monoclonal antibodies for in-office administration, though silicone oil-induced protein aggregation constrains shelf life for sensitive biologics.
- Lyophilized Powder:Freeze-dried formulations reconstituted at point of use, essential where cold-chain gaps limit liquid biologic distribution. Brazilian public health programs and Indian tertiary hospitals adopt dual-chamber syringes combining diluent and powder compartments, with EMA MDR extractables documentation requirements extending qualification timelines.
- Suspension:Insoluble drug particles requiring resuspension before injection.
- Emulsion:Lipid-based delivery systems for poorly soluble compounds.
- Gel:Viscous depot formulations for extended-release applications.
- Others:Novel delivery formats including nanoparticle suspensions.
Liquid formulations command the dominant revenue position. Lyophilized powder is gaining share fastest in emerging markets.
End User:
Customer type determines device complexity requirements, with institutional purchasers prioritizing safety features and individual patients demanding ergonomic self-administration systems.
- Hospitals:Acute care settings requiring integrated needlestick prevention and automated dosing verification. Academic medical centers in California and Texas consolidate procurement through group purchasing organizations, disqualifying standalone syringe manufacturers lacking safety-engineered shielding technology.
- Specialty Clinics:Rheumatology and endocrinology practices emphasizing patient training for home injection. German outpatient clinics drive adoption of cyclic olefin polymer barrels for temperature-sensitive biologics, with ISO 11040-4 dimensional tolerances compressing supplier qualification panels.
- Diagnostic Centers:Imaging and laboratory settings with occasional contrast media delivery needs.
- Long-Term Care Facilities:Nursing homes requiring simplified administration for non-specialist staff.
- Ambulatory Surgery Centers:Same-day procedure sites prioritizing rapid turnover and waste minimization.
Hospitals anchor procurement volume. Specialty clinics are climbing the fastest in device sophistication requirements.
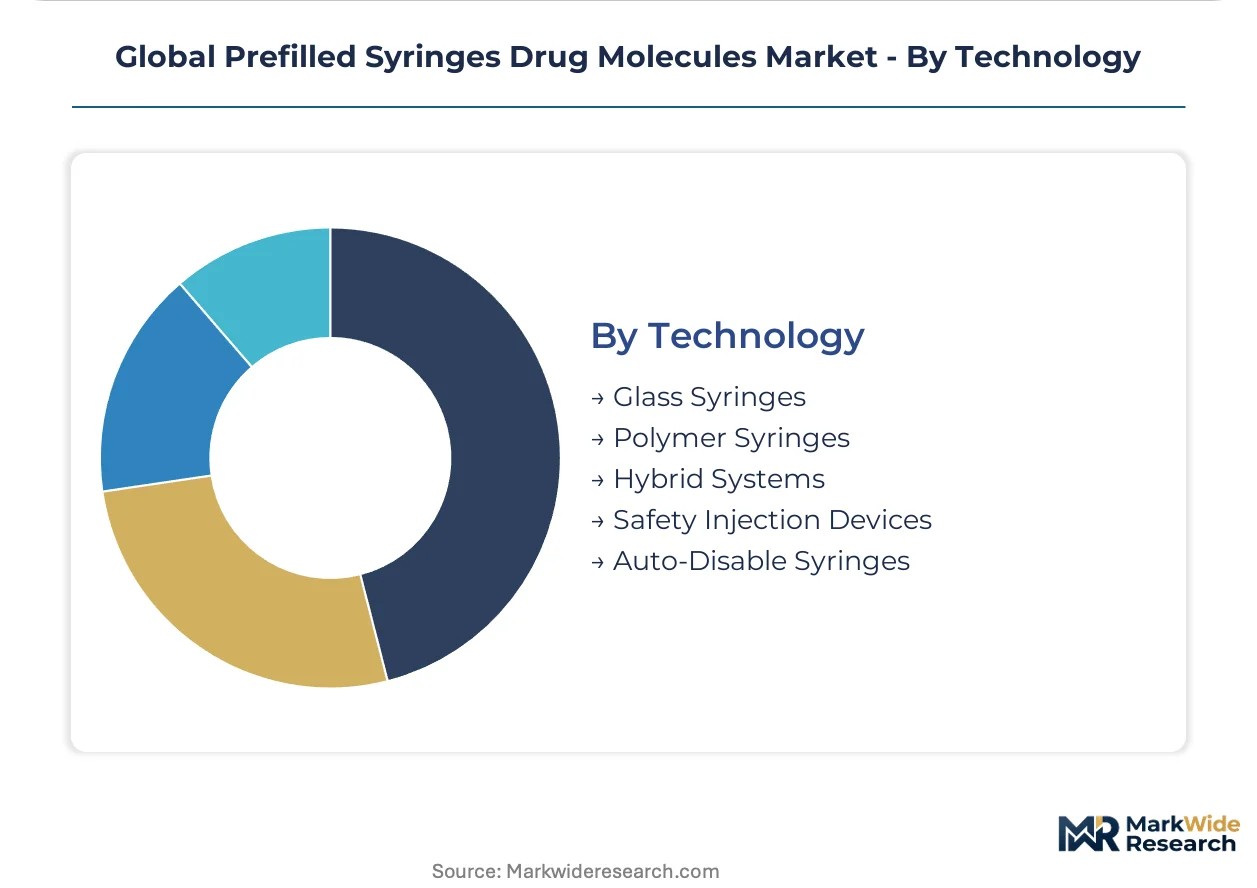
Technology:
Supply concentration in material platforms separates borosilicate glass heritage manufacturers from polymer entrants, with hybrid systems emerging at the intersection of protein stability and breakage resistance demands.
- Glass Syringes:Borosilicate Type I tubing with established extractables profiles and dimensional precision for high-viscosity biologics. SCHOTT Pharma's captive German tubing operations anchor European sterile injectable capacity, reducing lead times for monoclonal antibody formulations while silicone oil lubrication remains a protein aggregation risk.
- Polymer Syringes:Cyclic olefin polymer barrels displacing glass in temperature-sensitive applications. Becton Dickinson's backward integration into needle shielding dominates North American safety syringe production, with benzene derivative feedstock volatility compressing margins for disposable system manufacturers.
- Hybrid Systems:Glass barrels with polymer needle hubs or plunger components.
- Safety Injection Devices:Passive and active needlestick prevention mechanisms.
- Auto-Disable Syringes:Single-use locking mechanisms for immunization programs.
Glass syringes retain the largest installed base. Polymer syringes are expanding most quickly across chronic disease categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States rheumatology clinics consume monoclonal antibody prefilled syringes at weekly dosing frequencies unmatched elsewhere, while German outpatient facilities prioritize cyclic olefin polymer barrels for temperature-sensitive biologics. Japanese regulatory harmonization and Brazilian cold-chain infrastructure gaps create divergent formulation preferences across major markets.
United States
Academic medical centers in California and Texas consolidate procurement through group purchasing organizations, disqualifying standalone syringe manufacturers lacking safety-engineered needle shielding. FDA 21 CFR Part 4 compliance mandates drive validation investments for container closure integrity. The Boston-Cambridge biotech corridor anchors demand for high-viscosity monoclonal antibody delivery systems with ergonomic plunger-rod designs.
Germany
Rheumatology and endocrinology practices emphasize patient training protocols for home injection of temperature-sensitive biologics. EMA MDR extractables documentation requirements compress supplier qualification panels for polymer platform entrants. SCHOTT Pharma's captive borosilicate tubing operations in Mainz anchor European sterile injectable capacity, reducing lead times for high-viscosity formulations.
Japan
Chronic disease management protocols previously limited to clinical settings now incorporate wearable injector convergence with prefilled syringe cartridges. PMDA quality management system harmonization reduces regulatory duplication costs for foreign polymer platform manufacturers. The Kanto region's pharmaceutical manufacturing clusters drive adoption of ISO 11040-4 compliant dimensional tolerances for needle hub interfaces.
Brazil
Public health programs adopt dual-chamber syringes combining diluent and lyophilized powder compartments where cold-chain gaps limit liquid biologic distribution. ANVISA extractables validation timelines extend qualification cycles for secondary suppliers entering the market. São Paulo's tertiary hospital networks concentrate demand for reconstitution-ready systems with documented leachable performance profiles.
India
Mass immunization programs prioritize auto-disable syringes for single-use compliance, with UNICEF procurement specifications influencing domestic tender requirements. CDSCO tightening of container closure integrity standards for combination products raises capital barriers for unqualified component suppliers. Maharashtra's sterile injectable manufacturing corridors expand capacity to serve both domestic distribution and export markets.
Global Prefilled Syringes Drug Molecules Market Competitive Landscape
Capability concentration sits with heritage glass manufacturers possessing captive borosilicate supply chains; scale advantage sits with polymer platform specialists achieving backward integration into needle shielding. The vendor base separates into three functional tiers: integrated system providers certifying end-to-end container closure integrity, component specialists supplying barrels or closures to downstream assemblers, and regional fabricators serving immunization procurement tenders. Dominant competitive moves include M&A to secure extractables toxicology expertise and capacity expansion in cyclic olefin polymer resin processing.
Among integrated system providers, Becton Dickinson and Company exemplifies the scale-driven archetype through its dominance of North American safety syringe production. Gerresheimer AG occupies a position bridging glass heritage and polymer diversification across European markets. SCHOTT Pharma anchors the capability-concentrated tier with its captive German tubing operations and established extractables profiles for high-viscosity biologics.
| Leading Market Players |
|---|
| Becton Dickinson and Company (BD) |
| Gerresheimer AG |
| SCHOTT Pharma |
| West Pharmaceutical Services, Inc. |
| Nipro Corporation |
| AptarGroup, Inc. |
| Terumo Corporation |
| Stevanato Group |
| Ypsomed AG |
| Others |
Supply & Pricing Matrix
The Rotterdam-Frankfurt pharmaceutical freight corridor carries cyclic olefin polymer resin and borosilicate glass tubing across European sterile injectable networks, with its cost dynamics amplifying supply concentration in German captive tubing operations and compressing margins for secondary polymer converters serving price-sensitive immunization tenders.
Pricing Analysis
Long-term offtake contracts dominate procurement for monoclonal antibody delivery systems, with pricing stratifying across premium, standard, and economy tiers based on extractables documentation depth and ISO 11040-4 dimensional certification. Cost compression in economy-tier auto-disable syringes is intensifying because benzene derivative feedstock volatility squeezes disposable system manufacturers. UNICEF procurement managers exhibit highest price sensitivity, while biologics manufacturers prioritizing container closure integrity under FDA 21 CFR Part 4 demonstrate lowest.
Supply Chain Analysis
Tariff exposure between China and the United States disrupts cyclic olefin polymer resin flows for North American safety syringe manufacturers. German, Japanese, and South Korean suppliers anchor borosilicate glass and precision molding capacity, with production drawing from benzene derivatives, silicone oil lubricants, and medical-grade polymer additives. Single-source vulnerability concentrates in German captive tubing operations for high-viscosity biologics. Distribution runs through hospital group purchasing organizations and UNICEF tender networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as biologics manufacturers accelerate prefilled syringe adoption following pandemic-era supply chain recalibration and MDR compliance investment cycles.
For Market Incumbents: Insulate extractables toxicology capabilities through targeted acquisition of analytical chemistry specialists, as shortage of migration-correlation expertise extends validation timelines for competitors. Deepen backward integration into needle shielding production to defend against standalone safety-device entrants. Prioritize capacity addition in cyclic olefin polymer resin processing to capture chronic disease category expansion. For New Entrants and Emerging Players: Establish a beachhead in lyophilized powder dual-chamber systems for Brazilian and Indian public health programs, where cold-chain infrastructure gaps create procurement urgency. Target polymer platform qualification for Japanese PMDA QMS harmonization pathways, as streamlined foreign manufacturer recognition reduces regulatory duplication costs. Pursue GPO contract penetration through integrated safety-engineered needle shielding bundling. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors polymer platform specialists with documented leachable performance and backward integration into resin processing. Five-to-ten year viability hinges on extractables toxicology depth rather than glass heritage alone. The signal to watch is EMA MDR notified body audit frequency acceleration, which will disqualify component specialists lacking technical documentation repositories.| Strategic Initiative | Industry Significance |
|---|---|
| Extractables Toxicology Acquisition | Analytical chemistry expertise shortage extends competitor validation timelines under FDA 21 CFR Part 4. |
| Cyclic Olefin Polymer Capacity Expansion | Backward integration into resin processing captures chronic disease self-injection category growth. |
| Dual-Chamber Lyophilized System Development | Brazilian and Indian cold-chain gaps create procurement urgency for reconstitution-ready formats. |
| PMDA QMS Harmonization Pathway Entry | Streamlined Japanese foreign manufacturer recognition reduces regulatory duplication for polymer entrants. |
| Integrated Safety Needle Shielding Launch | US academic medical center GPO contracts disqualify standalone syringe manufacturers lacking passive prevention. |
Research Methodology
A standing panel of sterile fill-finish operations directors, regulatory affairs leads for combination products, hospital GPO contracts managers, and extractables toxicology specialists provided ongoing calibration across the study period. Primary interviews with biologics manufacturing executives and polymer platform R&D directors combined with secondary validation from FDA 21 CFR Part 4 guidance documents, EMA MDR technical documentation requirements, ISO 11040-4 dimensional standards, and USP particulate matter testing protocols. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Scenario-bracketing around MDR compliance deadline acceleration, benzene derivative price volatility bands, and biologics pipeline concentration in rheumatology versus oncology indications shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include drug molecule viscosity class, formulation stability requirements, end-user procurement sophistication, and regional regulatory cluster stringency. CAGRs derived from installed base replacement cycles and new molecular entity launch densities.
Stress conditions across silicone oil protein aggregation thresholds, cyclic olefin polymer resin price spikes, and notified body audit queue lengths were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about chronic disease dosing frequency persistence and container closure integrity standard harmonization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Multiple Sclerosis Drugs Market
Pharmaceuticals
Global Combination Vaccine Market
Pharmaceuticals
Collagenase Clostridium Histolyticum Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Global Shingles Vaccine Market
Pharmaceuticals
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market
Pharmaceuticals
Small Molecules Contract Development and Manufacturing Organization Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Calcium Channel Blocker Market
Pharmaceuticals
Steroid Injections Market
Pharmaceuticals
Global DNA Repair Drugs Market
Pharmaceuticals
Critical Care Therapeutics Market
Pharmaceuticals
North America Anticoccidial Drugs Market
Pharmaceuticals
Global Orally Disintegrating Tablet Market
Pharmaceuticals
Acetylspiramycin Market
Pharmaceuticals
Europe Contraceptives Market