
 STD Testing Devices Market | 2026-2036
STD Testing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
STD Testing Devices Market Analytics
Point-of-care testing is pivoting toward urgent care centers and retail clinic chains as hospitals decentralize infectious disease workflows. Becton Dickinson and Company leverages its integrated diagnostics platform to sustain channel control across clinic networks. Abbott Laboratories anchors its position through handheld molecular systems that dominate bedside screening workflows. Siemens Healthineers AG competes on automated immunoassay throughput for high-volume laboratory settings.
STD testing devices comprise instruments and consumables designed to detect bacterial, viral, and parasitic sexually transmitted infections through sample collection, nucleic acid amplification, antigen-antibody binding, or microscopic visualization, typically operating with sensitivity thresholds below 100 copies per milliliter for molecular methods. These systems serve public health screening, clinical diagnosis, and partner notification programs where rapid turnaround alters treatment initiation. Rapid test kits capture the largest volume share due to their deployment in resource-limited settings and home testing channels, while PCR test systems command premium positioning through laboratory-grade sensitivity and multiplexing capability. Microfluidics represents the fastest-growing technology dimension as manufacturers miniaturize amplification and detection onto single-use cartridges that reduce operator training requirements.
The FDA regulates these products through the in vitro diagnostic device framework with Class II or III designations depending on intended use and claim complexity, while the EMA's In Vitro Diagnostic Medical Devices Regulation imposes post-market surveillance and performance study obligations across European member states. The WHO prequalification program shapes procurement criteria for low- and middle-income country tenders, directly influencing manufacturer R&D prioritization. Stakeholders must monitor evolving CLIA-waiver expansions and home-testing label claims as regulatory acceptance of patient-collected specimens reshapes channel economics and competitive positioning.
Market Dynamics
Decentralization of infectious disease diagnostics is compressing traditional laboratory workflows into point-of-care environments, forcing manufacturers to reconcile CLIA-waiver requirements with multiplexing performance.
Growth Catalysts
- FDA Emergency Use Authorization Pathway:The streamlined EUA framework accelerates molecular diagnostic deployment during public health emergencies, reducing time-to-market for novel amplification platforms.
- Microfluidic Cartridge Miniaturization:Single-use consumables integrating sample prep, amplification, and detection eliminate cold-chain logistics and enable non-laboratory operation.
- Germany's Statutory Health Insurance:Reimbursement codes covering routine STI screening create predictable demand pull through diagnostic laboratory networks.
Market Restraints
- Reagent Supply Concentration:Polymerase and fluorescent probe manufacturing clusters in South Korea and Germany expose distributors to single-source fragility.
- CLIA Complexity:The FDA's waiver determination process imposes 12-18 month validation timelines that freeze product iteration cycles.
- Antigen-Antibody Test Substitution:Rapid immunoassay kits compete on price against nucleic acid methods in resource-constrained procurement environments.
Strategic Opportunities
- India's National AIDS Control Programme:Government tenders for decentralized HIV and syphilis screening create volume anchors for cartridge-based systems.
- Home Collection Authorization:FDA label expansions permitting patient-collected vaginal swabs and urine specimens unlock direct-to-consumer channels.
- Multiplexing Convergence:Integration of CT/NG/TV detection with antimicrobial resistance genotyping on single cartridges commands premium positioning.
Industry Challenges
- CLIA-Waiver Technical Staffing:Manufacturers lack sufficient regulatory affairs specialists familiar with 21 CFR Part 820 quality system integration.
- Legacy LIS Integration:Point-of-care devices require HL7 FHIR middleware development to connect with hospital electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | STD Testing Devices Market |
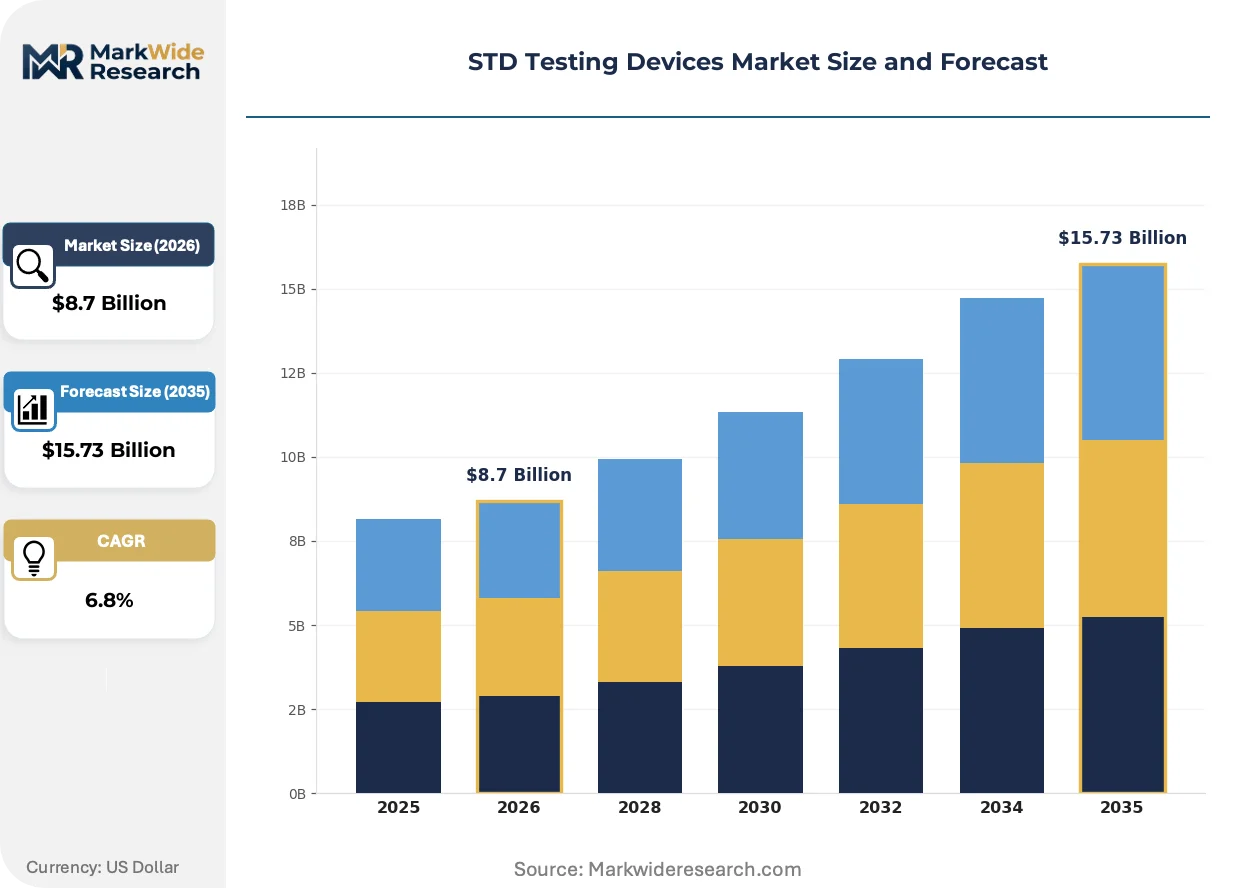
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Test Kits, PCR Test Systems, Microscopy Devices, ELISA Test Kits Technology: Immunoassay, Nucleic Acid Amplification, Microfluidics, Optical Sensors Application: Clinic Use, Home Testing, Laboratory Diagnostics, Point-of-Care Testing End User: Hospitals, Diagnostic Laboratories, Research Institutions, Urgent Care Centers |
| Companies Covered | Becton Dickinson and Company, BioMérieux SA, Abbott Laboratories, Thermo Fisher Scientific Inc., Siemens Healthineers AG, Roche Diagnostics, Danaher Corporation, DiaSorin S.p.A., Hologic, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
STD Testing Devices Market Evolving Landscape
Instrument architecture is collapsing toward handheld formats while detection chemistry advances toward isothermal methods that eliminate thermal cycler hardware. These shifts compress capital requirements and expand addressable testing venues.
Loop-mediated isothermal amplification (LAMP) is absorbing the molecular detection workload previously reserved for PCR thermocyclers. Urgent care chains and retail clinic operators are adopting LAMP-based systems at triple-digit annual placement rates. The technology is absorbing market share from centralized laboratory workflows by delivering 30-minute turnaround without nucleic acid purification steps.
The EMA's In Vitro Diagnostic Medical Devices Regulation imposes post-market surveillance and performance study obligations across European member states. Manufacturers must maintain technical documentation and clinical evidence packages for Class C devices that claim sexually transmitted infection detection. High-complexity laboratory segments in France and Italy are extending procurement cycles to evaluate MDR compliance certificates before contract renewal.
Self-collection protocols are displacing clinician-mediated specimen acquisition in reproductive health and telemedicine channels. Retail pharmacies and direct-to-consumer platforms are capturing screening volume that previously flowed through physician offices. This behavioral pivot is most visible in United States metropolitan markets where digital health startups bundle home test kits with asynchronous consultation services.
STD Testing Devices Market Segmentation
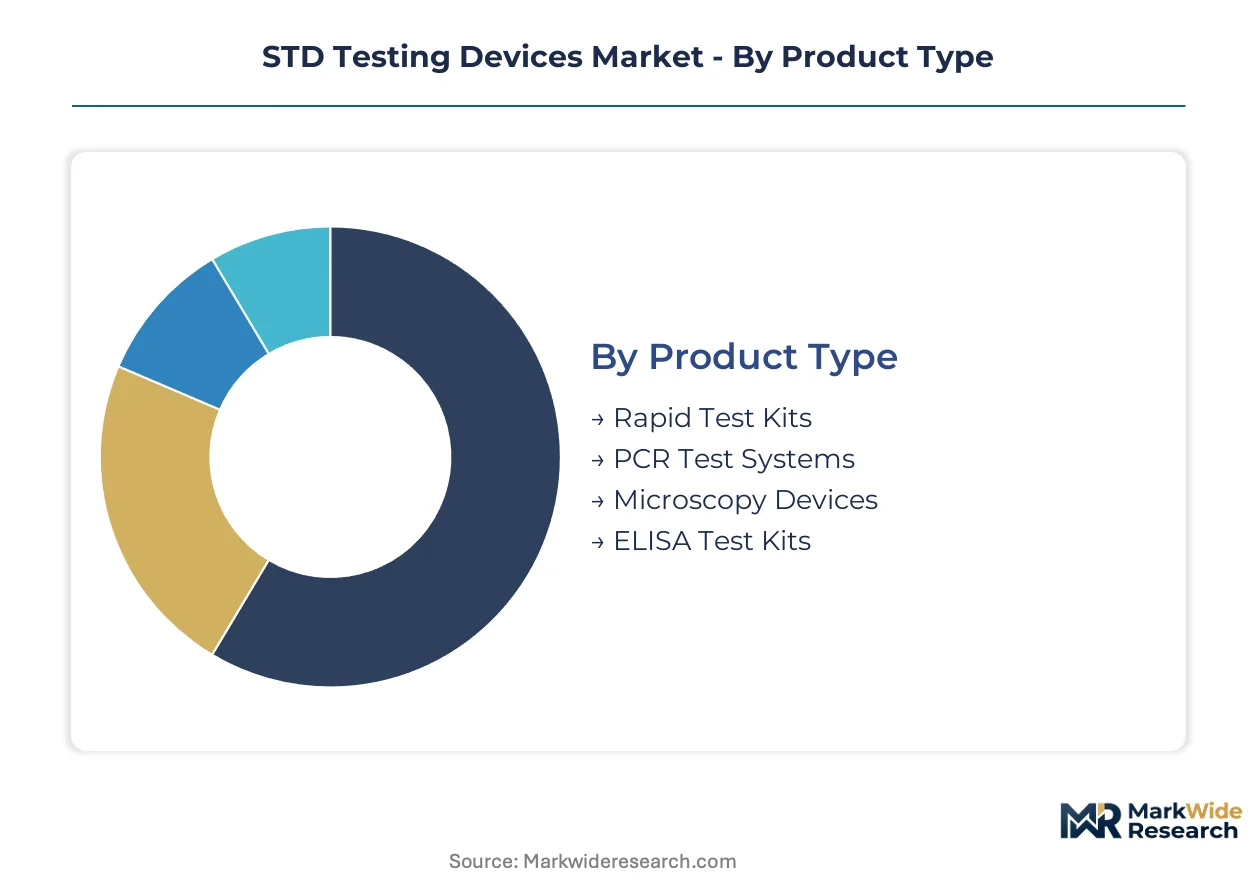
Segmentation in the STD testing devices market reveals how technology choices, testing venues, and end-user workflows create distinct commercial battlegrounds. Manufacturers must align product architecture with the specific performance, cost, and regulatory requirements of each segment to capture sustainable positioning.
Product Type:
Rapid test kits dominate unit volume through their deployment in resource-limited settings and retail channels, while PCR test systems command premium positioning through laboratory-grade sensitivity and multiplexing capability.
- Rapid Test Kits:Lateral flow immunoassays and immunochromatographic strips detect antigens or antibodies within 15-30 minutes without instrumentation. Demand concentrates in sub-Saharan Africa and South Asia where cold-chain independence and minimal operator training enable decentralized HIV and syphilis screening programs.
- PCR Test Systems:Thermocycler-based nucleic acid amplification platforms achieve sensitivity thresholds below 100 copies per milliliter for Chlamydia trachomatis and Neisseria gonorrhoeae detection. High-complexity laboratories in Germany and Japan anchor procurement volume as reimbursement frameworks support routine molecular screening.
- Microscopy Devices:Light microscopy systems for wet mount and Gram stain visualization of Trichomonas vaginalis and bacterial vaginosis remain essential in low-resource clinic settings.
- ELISA Test Kits:Enzyme-linked immunosorbent assays for HIV and hepatitis serology sustain reference laboratory throughput in high-volume diagnostic networks.
Today's leader: Rapid Test Kits. Tomorrow's challenger: PCR Test Systems.
Technology:
Cost tier differentiation separates established chemistries from emerging platforms, with miniaturization driving the steepest expansion trajectory in point-of-care environments.
- Immunoassay:Antigen-antibody binding reactions form the backbone of rapid diagnostic strips and automated laboratory analyzers. Urgent care centers in the United States absorb volume through CLIA-waived lateral flow platforms that eliminate nucleic acid purification steps.
- Nucleic Acid Amplification:PCR and transcription-mediated amplification methods deliver definitive pathogen detection with species-level specificity. Reference laboratories in France and Italy extend procurement cycles to evaluate MDR compliance certificates before contract renewal.
- Microfluidics:Single-use cartridges integrating sample prep, amplification, and detection eliminate cold-chain logistics and enable non-laboratory operation.
- Optical Sensors:Fluorescence and chemiluminescence detection modules enable real-time signal quantification in automated platforms.
Established chemistry: Immunoassay. Platform gaining share fastest: Microfluidics.
Application:
Customer type fragmentation splits the market between institutional procurement and direct-to-consumer channels, reshaping distribution economics and regulatory pathways.
- Clinic Use:Physician office laboratories and reproductive health clinics conduct same-day screening with moderate-complexity devices. India's National AIDS Control Programme tenders drive volume for cartridge-based HIV and syphilis systems in government health facilities.
- Home Testing:Patient-collected specimens and asynchronous telemedicine consultations bypass traditional clinical workflows. Metropolitan markets in the United States show the strongest behavioral pivot toward retail pharmacy and digital health platform channels.
- Laboratory Diagnostics:High-throughput automated platforms process batched specimens in centralized reference facilities.
- Point-of-Care Testing:Bedside and urgent care deployment demands 30-minute turnaround with minimal operator intervention.
Institutional anchor: Clinic Use. Consumer disruptor: Home Testing.
End User:
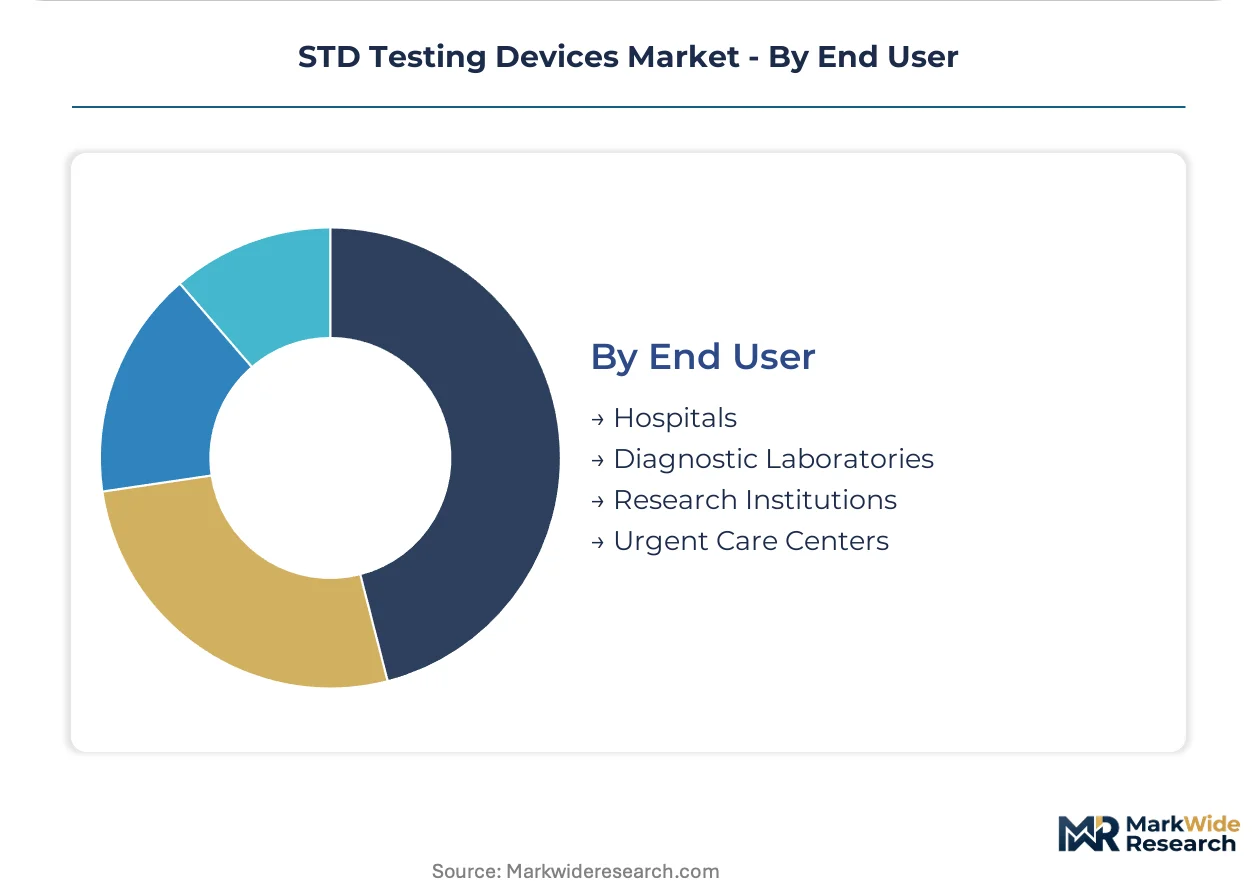
Supply concentration among diagnostic laboratories creates volume predictability, while urgent care expansion opens new placement opportunities for CLIA-waived systems.
- Hospitals:Infectious disease departments and emergency medicine units integrate rapid molecular platforms into admission protocols. Academic medical centers in Japan prioritize multiplexing capability for antimicrobial resistance genotyping alongside CT/NG/TV detection.
- Diagnostic Laboratories:Independent and hospital-affiliated reference labs anchor reagent contract value through long-term service agreements. Germany's statutory health insurance reimbursement codes create predictable demand pull through laboratory network procurement.
- Research Institutions:Academic and government research programs evaluate novel biomarkers and assay chemistries.
- Urgent Care Centers:Retail clinic chains and standalone urgent care operators adopt LAMP-based systems at triple-digit annual placement rates.
Volume foundation: Diagnostic Laboratories. Growth frontier: Urgent Care Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge life sciences corridor anchors molecular diagnostics innovation for infectious disease testing. Reimbursement frameworks and regulatory pathways in specific national markets determine commercial prioritization for device manufacturers.
United States
Urgent care chains and retail clinic operators absorb CLIA-waived molecular platforms at accelerated placement rates. The FDA's emergency use authorization pathway compresses validation timelines for novel amplification systems. The San Diego biotech cluster concentrates contract manufacturers supplying cartridge-based consumables to point-of-care developers.
Germany
Statutory health insurance reimbursement codes create predictable demand pull through diagnostic laboratory networks. The EMA's In Vitro Diagnostic Medical Devices Regulation imposes post-market surveillance obligations that extend procurement evaluation cycles. The Munich-Stuttgart industrial corridor hosts automated immunoassay manufacturers serving high-throughput reference facilities.
Japan
Academic medical centers prioritize multiplexing capability for antimicrobial resistance genotyping alongside pathogen detection. The PMDA's pharmaceutical and medical device agency maintains stringent clinical evidence requirements for novel diagnostic claims. The Kanto region around Tokyo concentrates procurement decision-making for national hospital networks.
India
The National AIDS Control Programme tenders drive volume for decentralized HIV and syphilis screening in government health facilities. The CDSCO regulates in vitro diagnostic imports through registration requirements that favor established multinational suppliers. The Maharashtra-Gujarat pharmaceutical belt hosts contract manufacturers producing rapid test kits for domestic and export markets.
South Korea
Polymerase and fluorescent probe manufacturing clusters expose distributors to single-source supply fragility. The MFDS maintains quality system requirements aligned with international standards for molecular diagnostic components. The Seoul metropolitan area concentrates reagent production capacity serving Asia-Pacific device assembly operations.
STD Testing Devices Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents extend from centralized laboratory systems into point-of-care environments. The vendor base concentrates around integrated diagnostics platforms and handheld molecular systems. Three archetypes prevail: diversified conglomerates with cross-portfolio synergies, specialized molecular diagnostics pure-plays, and rapid test manufacturers serving resource-limited settings. M&A activity and technology licensing agreements represent the dominant competitive moves reshaping market structure.
Among diversified healthcare conglomerates, Becton Dickinson and Company and Abbott Laboratories exemplify archetypes anchoring channel control across clinic networks. Siemens Healthineers AG occupies a position representing automated throughput specialization for high-volume laboratory segments. These three entities sit within the tier commanding premium positioning through integrated system-and-consumable business models.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| BioMérieux SA |
| Abbott Laboratories |
| Thermo Fisher Scientific Inc. |
| Siemens Healthineers AG |
| Roche Diagnostics |
| Danaher Corporation |
| DiaSorin S.p.A. |
| Hologic, Inc. |
| Others |
Value Network & Pricing Analysis
Regulatory affairs specialists concentrated in Boston-Cambridge and Research Triangle Park command wage premiums that compress margin spreads between CLIA-waived rapid test kits and high-complexity PCR systems. Labor-cost differentials between these talent clusters and contract manufacturing zones in Malaysia and Mexico translate directly into pricing-tier spreads across the value chain.
Pricing Analysis
Input-cost pass-through from polymerase and fluorescent probe supply determines contract renegotiation rhythms for laboratory consumables. Three-tier pricing structure across premium, standard, and economy levels separates multiplexed cartridge systems from benchtop thermocyclers and lateral flow strips. Pricing pressure stems from antigen-antibody test substitution in Indian and African procurement tenders. Diagnostic laboratories exhibit lowest price sensitivity due to reimbursement code anchoring, while urgent care chains negotiate aggressively on per-test economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Memphis orchestrate hub-and-spoke patterns for temperature-sensitive reagents. Manufacturing concentrates in South Korea for fluorescent probes, Germany for precision optics, and the United States for molecular assay development. Supply chains draw from rare-earth elements for optical sensors, specialized polymers for microfluidic cartridges, and recombinant enzymes for amplification chemistry. Single-source vulnerability in South Korean probe production exposes distributors to disruption. Distribution runs through diagnostic laboratory networks and GPO contracts in developed markets, with government tender channels dominating emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The STD testing devices market reads as a late-cycle quality story where demand is migrating toward multiplexed molecular platforms with antimicrobial resistance genotyping capability. This specification premium rewards manufacturers with integrated cartridge-and-software architectures.
For Market Incumbents: Deploy CLIA-waiver expansion as the primary lever to lock in urgent care channel control before LAMP-based entrants achieve scale. Consolidate position through backward integration into polymerase production, mitigating single-source exposure from South Korean suppliers. Anticipate regulatory pressure from the FDA's evolving home-collection labeling standards. For New Entrants and Emerging Players: The price-point gap between premium multiplexed systems and economy rapid kits offers entry terrain for mid-tier cartridge platforms with targeted pathogen menus. India's National AIDS Control Programme tenders represent the most penetrable volume anchor for decentralized HIV and syphilis screening. Pursue telemedicine platform partnerships to bypass traditional hospital procurement gatekeepers. For Investors and Strategic Acquirers: Valuations sit cheapest among microfluidics pure-plays with FDA 510(k) clearances but limited commercial scale. Long-term viability hinges on reimbursement strategy execution across German statutory insurance and US Medicare coverage determinations. Monitor FDA label expansions for patient-collected specimens as the inflection signal for direct-to-consumer channel economics.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Waiver Expansion | Accelerates placement in urgent care chains by eliminating laboratory certification requirements. |
| Multiplexing Convergence | Commands premium positioning by integrating CT/NG/TV detection with antimicrobial resistance genotyping. |
| Home Collection Authorization | Unlocks direct-to-consumer channels through FDA label expansions for patient-collected specimens. |
| Reagent Supply Backward Integration | Reduces single-source fragility from South Korean polymerase and probe manufacturing clusters. |
| Telemedicine Platform Partnership | Captures screening volume shifting toward asynchronous consultation and home testing bundles. |
Research Methodology
Multiple input streams — regulatory filing databases, hospital procurement records, and contract manufacturer capacity disclosures — were reconciled to construct market estimates. Primary interviews with CLIA compliance officers, GPO contracts managers, biomedical engineers, and diagnostic laboratory directors informed operational assumptions. Secondary validation drew from FDA 510(k) clearances, EMA MDR technical documentation, WHO prequalification lists, and CMS reimbursement code updates. Bottom-up device placement counts and top-down reagent consumption models were triangulated to anchor volume projections.
Data-stream reconciliation across the projection horizon employed segmented modeling by product type, technology platform, testing venue, and end-user category. CAGRs were derived from fitted growth curves calibrated to historical placement trajectories and reimbursement policy shifts. Industry-specific forecast inputs included CLIA-waiver approval timelines, EMA MDR compliance certification cycles, and National AIDS Control Programme tender award patterns.
Caveats apply where FDA home-testing label expansions, EMA post-market surveillance enforcement intensity, or polymerase supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory pathway durations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
Creatinine Testing Market
Testing Services
At-Home Testing Market
Testing Services
Pharmaceutical Dosage Form Testing Systems Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
In-Vitro Diagnostic Services Market
Testing Services
Staphylococcus Aureus Testing Market
Testing Services
Minimal Residual Disease Testing Market
Testing Services
Indoor Allergen and Particulate Exposure Assessment Test Devices Market
Testing Services
Global Efficacy Testing Market
Testing Services
Rapid Hepatitis Testing Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
Asia-Pacific Viral Clearance Market
Testing Services
Rapid Coagulation Testing Market
Testing Services
Global Vitamin D Testing Market
Testing Services
Nipah Virus (Niv) Infection Testing Market