
 Global Direct-To-Consumer (DTC)Testing Market | 2026-2036
Global Direct-To-Consumer (DTC)Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Direct-To-Consumer (DTC)Testing Market Foresight
At-home saliva-based sequencing and finger-prick microsampling is rewriting the technical architecture of consumer diagnostics, collapsing the distance between laboratory-grade assays and kitchen-table collection. 23andMe leverages its proprietary genotyping arrays and research partnerships to sustain recurring revenue from ancestry and health trait reports. Everlywell anchors its position through CLIA-certified lab networks and broad retail pharmacy distribution. Quest Diagnostics competes by extending its clinical laboratory infrastructure directly into consumer channels.
Direct-to-consumer testing encompasses laboratory analyses performed on self-collected specimens without clinician-mediated ordering, typically requiring CAP/CLIA certification and FDA authorization for high-complexity assays. The product category spans genetic testing, nutritional testing, and infectious disease testing, with genetic testing commanding premium pricing due to sequencing depth and interpretive complexity. Mail-in kits and telehealth integration represent the fastest-expanding delivery models, while pharmacy collection retains structural importance for consumer trust and specimen quality assurance.
FDA premarket review and CLIA laboratory certification govern market access in the United States, with the FTC policing advertising claims for predictive health utilities. The EU In Vitro Diagnostic Regulation and GDPR genetic data protections impose parallel compliance burdens across European markets. Stakeholders must monitor evolving reimbursement policies for telehealth-integrated results and the shifting boundary between wellness screening and diagnostic-grade claims.
Market Dynamics
Telehealth integration with at-home specimen collection is collapsing the traditional clinical laboratory visit, forcing CAP/CLIA-certified facilities to compete directly on consumer convenience and result turnaround speed.
Growth Catalysts
- FDA 510(k) clearance acceleration:Streamlined premarket review for moderate-risk diagnostic devices compresses product launch timelines and expands assay menus available through retail channels.
- Chronic disease self-management:Diabetes and cardiovascular patients in the United States increasingly demand HbA1c and lipid panels without clinic appointments, driving recurring kit purchases.
- Saliva-based DNA extraction chemistry:Stabilization buffers and ambient shipping logistics now preserve nucleic acid integrity across multi-day transit, enabling ancestry and pharmacogenomic testing at scale.
Market Restraints
- CLIA laboratory concentration:A limited number of high-complexity certified facilities handle the majority of DTC sample processing, creating capacity bottlenecks during demand surges.
- Reimbursement exclusion:Most private insurers and Medicare deny claims for consumer-ordered tests without physician authorization, limiting addressable population to out-of-pocket payers.
- Genetic data privacy litigation:Class-action exposure under state biometric laws and GDPR Article 9 restrictions elevates compliance costs and constrains data monetization strategies.
Strategic Opportunities
- India's diagnostic infrastructure gaps:Urban middle-class consumers in Mumbai and Bangalore seek alternatives to overloaded hospital laboratories for routine metabolic panels.
- Longitudinal health monitoring subscriptions:Quarterly biomarker tracking for fitness optimization and hormonal health creates recurring revenue models beyond one-time ancestry purchases.
- EU IVDR companion diagnostic pathways:The 2022 regulation's performance study requirements favor well-capitalized platforms that can generate clinical evidence for wellness-to-diagnostic claim upgrades.
Industry Challenges
- Bioinformatics talent scarcity:Interpretation of polygenic risk scores and rare variant classification requires computational biologists and genetic counselors in short supply across commercial laboratories.
- Specimen quality variability:Self-collection errors in finger-prick microsampling generate insufficient volume or hemolysis, triggering re-collection costs and consumer dissatisfaction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Direct-To-Consumer (DTC)Testing Market |
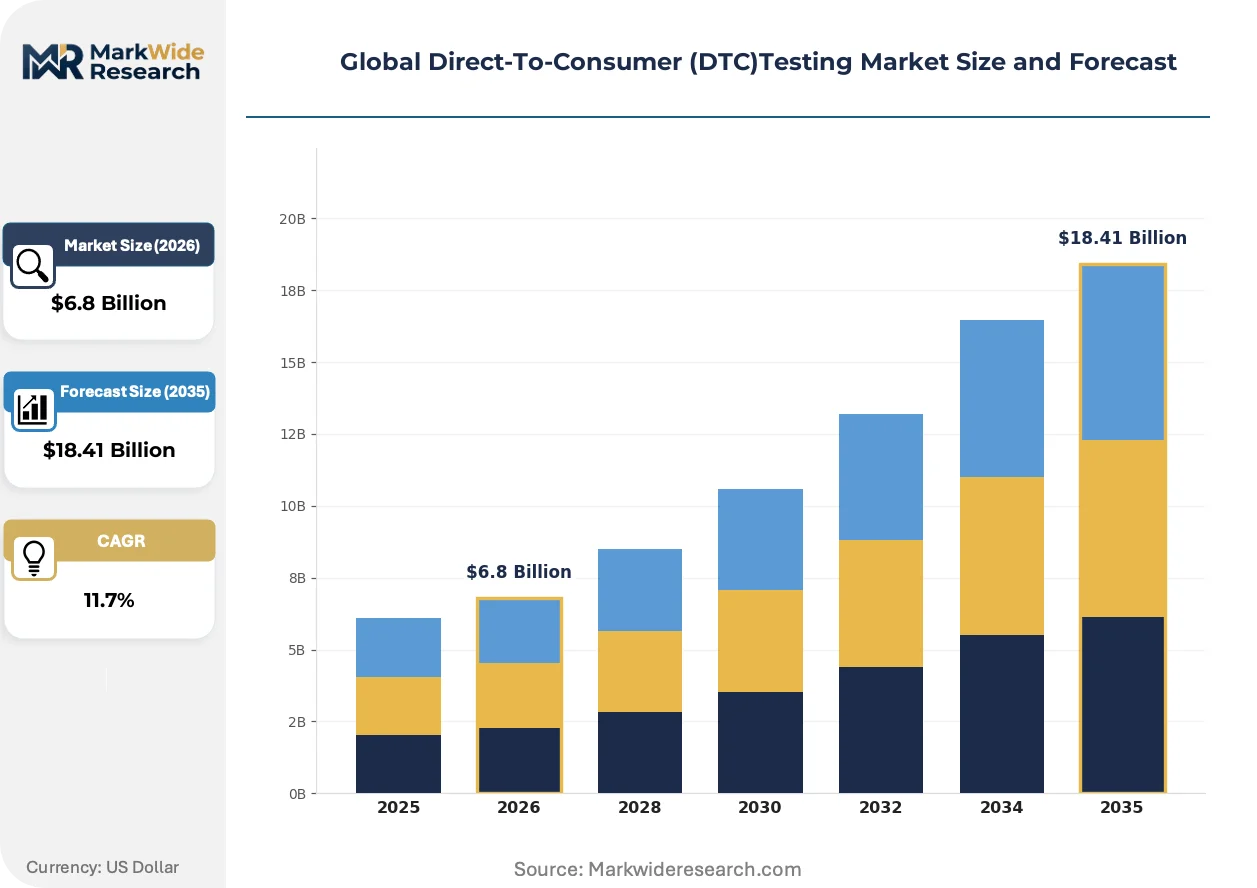
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $18.41 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genetic Testing, Nutritional Testing, Infectious Disease Testing, Hormone Testing, Allergy Testing, Wellness Testing Application: Personal Health Monitoring, Preventive Care, Fitness Enhancement, Disease Risk Assessment, Ancestry Exploration, Lifestyle Optimization Delivery Model: Online Ordering, Mail-In Kits, Mobile Sampling, Pharmacy Collection, Direct Home Collection, Telehealth Integration End User: Individual Consumers, Health Coaches, Fitness Enthusiasts, Genetic Counselors, Nutritionists, Wellness Clinics |
| Companies Covered | 23andMe, Inc., Ancestry, Color Health, Inc., Everlywell, Inc., LetsGetChecked, MyHeritage Ltd., Helix, Inc., Labcorp, Quest Diagnostics Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Direct-To-Consumer (DTC)Testing Market Shifts & Advancements
Digital health platforms are absorbing diagnostic functionality into continuous monitoring ecosystems, blurring the boundary between discrete laboratory tests and real-time biometric streams from wearable devices.
Microfluidic cartridge technology is virtualizing the clinical chemistry analyzer into credit-card-sized disposable units. Consumers in Germany and the United Kingdom now perform liver enzyme and vitamin D quantification on kitchen countertops. This compression eliminates cold-chain logistics and central laboratory batch processing delays.
The EU In Vitro Diagnostic Regulation's 2022 implementation imposes clinical evidence requirements for class C and D devices previously cleared under the IVDD. Manufacturers must now conduct prospective performance studies or systematic literature reviews to maintain CE marking. Genetic health risk tests face the steepest compliance burden, with notified body review timelines extending eighteen to twenty-four months.
Subscription-based biomarker tracking is displacing episodic testing among athletic and longevity-focused consumers in California and Colorado. Quarterly kits measuring cortisol, testosterone, and inflammatory markers arrive on predictable schedules, with telehealth physicians interpreting trajectories rather than single values. This shift locks in customer lifetime value and reduces customer acquisition costs compared to one-time ancestry purchases.
Global Direct-To-Consumer (DTC)Testing Market Segmentation
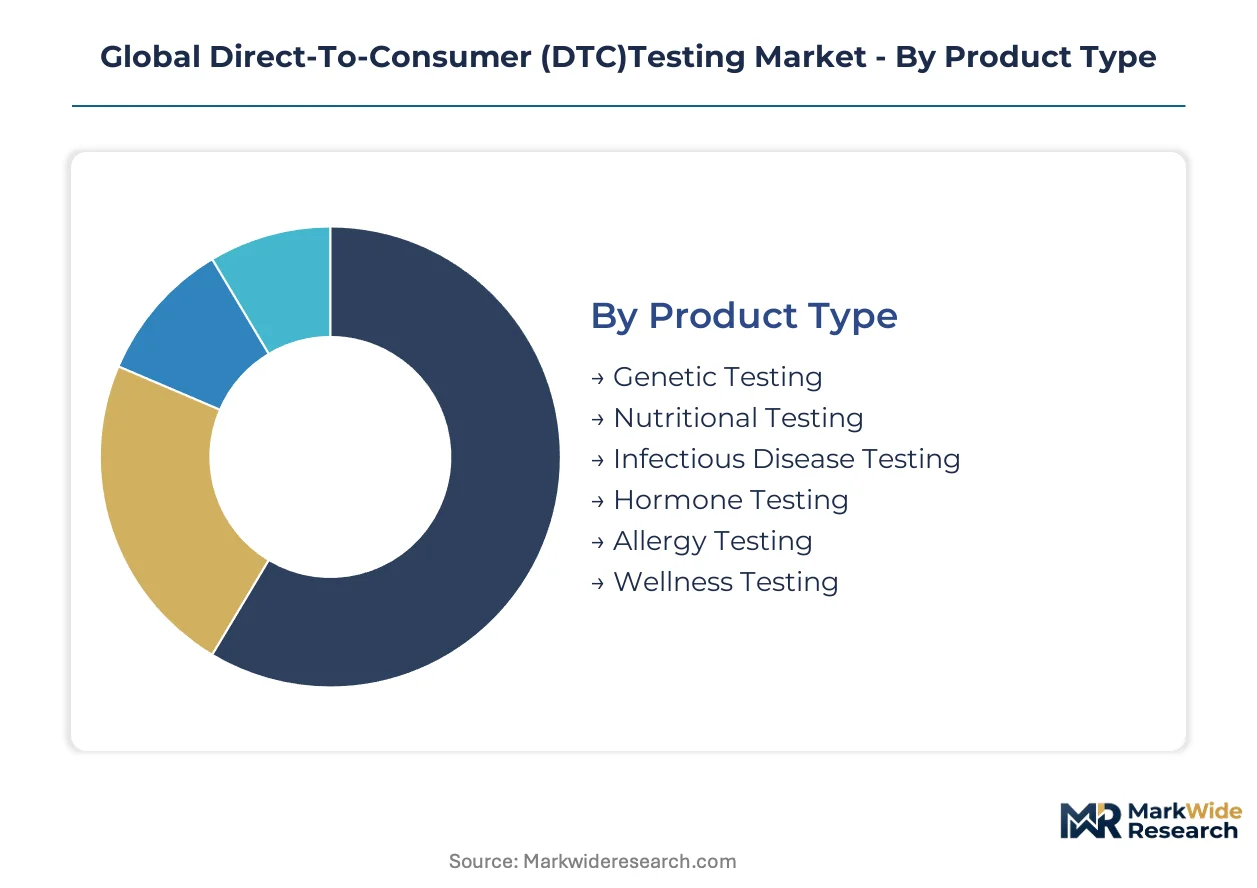
Product architecture in DTC testing demands distinct post-purchase support protocols. Genetic and infectious disease assays require genetic counselor follow-up and result hotlines, while wellness panels operate with minimal service touchpoints. This service intensity gradient shapes margin structures and customer retention economics across segment boundaries.
Product Type:
After-sales service intensity varies dramatically by assay complexity. Pharmacogenomic reports trigger ongoing medication consultation needs, while vitamin D panels conclude at result delivery.
- Genetic Testing:High-complexity sequencing of germline variants for ancestry, carrier status, and drug response prediction. Demand concentrates in the United States and Germany where FDA and BfArM pathways legitimize health risk claims, though reimbursement exclusion limits expansion beyond affluent self-pay consumers.
- Nutritional Testing:Quantification of micronutrient deficiencies and metabolic markers from blood or urine specimens. Fitness enthusiasts in California and Colorado drive recurring purchases for quarterly biomarker tracking tied to personalized supplementation protocols.
- Infectious Disease Testing:PCR and antigen detection for respiratory and sexually transmitted pathogens. STI screening demand in the United Kingdom and Netherlands surged through pharmacy collection networks.
- Hormone Testing:Saliva and dried blood spot assays for cortisol, thyroid, and reproductive hormones. Perimenopausal women in Australia and Canada purchase serial panels to guide hormone replacement decisions.
- Allergy Testing:IgE and IgG4 antibody profiling against food and environmental triggers. Pediatric applications in South Korea and Japan expand through clinic-affiliated wellness programs.
- Wellness Testing:Broad metabolic panels assessing liver enzymes, lipids, and inflammatory markers. Corporate wellness programs in Singapore and Switzerland subsidize employee screening.
By volume, Wellness Testing leads. By growth pace, Genetic Testing is expanding most quickly.
Application:
Cost tier stratification separates episodic purchasers from subscription-locked users. Preventive care and fitness applications command premium pricing through longitudinal engagement models.
- Personal Health Monitoring:Continuous tracking of biomarkers for chronic condition self-management. Diabetics in the United States purchase recurring HbA1c kits through telehealth-integrated platforms.
- Preventive Care:Population-level screening for cardiovascular and cancer risk factors. Middle-aged consumers in France and Italy access subsidized metabolic panels through pharmacy networks.
- Fitness Enhancement:Optimization of training load and recovery through hormone and inflammation tracking. Endurance athletes in Colorado and Norway drive demand for cortisol and testosterone serial testing.
- Disease Risk Assessment:Polygenic risk scoring for type 2 diabetes, Alzheimer's, and cardiovascular conditions. Consumers in the United Kingdom navigate GDPR Article 9 restrictions to access pharmacogenomic reports.
- Ancestry Exploration:Ethnic composition and migration pattern inference from autosomal DNA. Initial customer acquisition hook for platforms cross-selling health traits in Brazil and Mexico.
- Lifestyle Optimization:Sleep, stress, and nutrition biomarker alignment with wearable data. Biohackers in California integrate continuous glucose monitors with quarterly metabolic panels.
Preventive Care generates the highest revenue per user. Fitness Enhancement shows the steepest expansion trajectory among subscription models.
Delivery Model:
Customer type determines channel preference. Privacy-sensitive users favor direct home collection, while quality-conscious consumers prefer pharmacy-mediated specimen handling.
- Online Ordering:E-commerce platforms with kit delivery to residential addresses. Urban professionals in India and China bypass hospital queues for routine metabolic panels.
- Mail-In Kits:Self-collection with ambient shipping to CLIA-certified laboratories. The dominant model for ancestry and nutritional testing across North American and European markets.
- Mobile Sampling:Phlebotomy services dispatched to homes or offices. Corporate wellness contracts in London and New York City deploy nurse visits for executive health screening.
- Pharmacy Collection:Supervised specimen collection at retail pharmacy chains. CVS and Walgreens networks in the United States assure sample integrity for diagnostic-grade assays.
- Direct Home Collection:Unsupervised finger-prick or saliva collection without clinical oversight. Cost-sensitive consumers in Southeast Asia prefer this lowest-touch option.
- Telehealth Integration:Physician-ordered testing with at-home collection and virtual result consultation. Medicare Advantage plans in Florida and Texas now cover select panels through this channel.
Mail-In Kits dominate transaction volume. Telehealth Integration is gaining share fastest through reimbursement expansion.
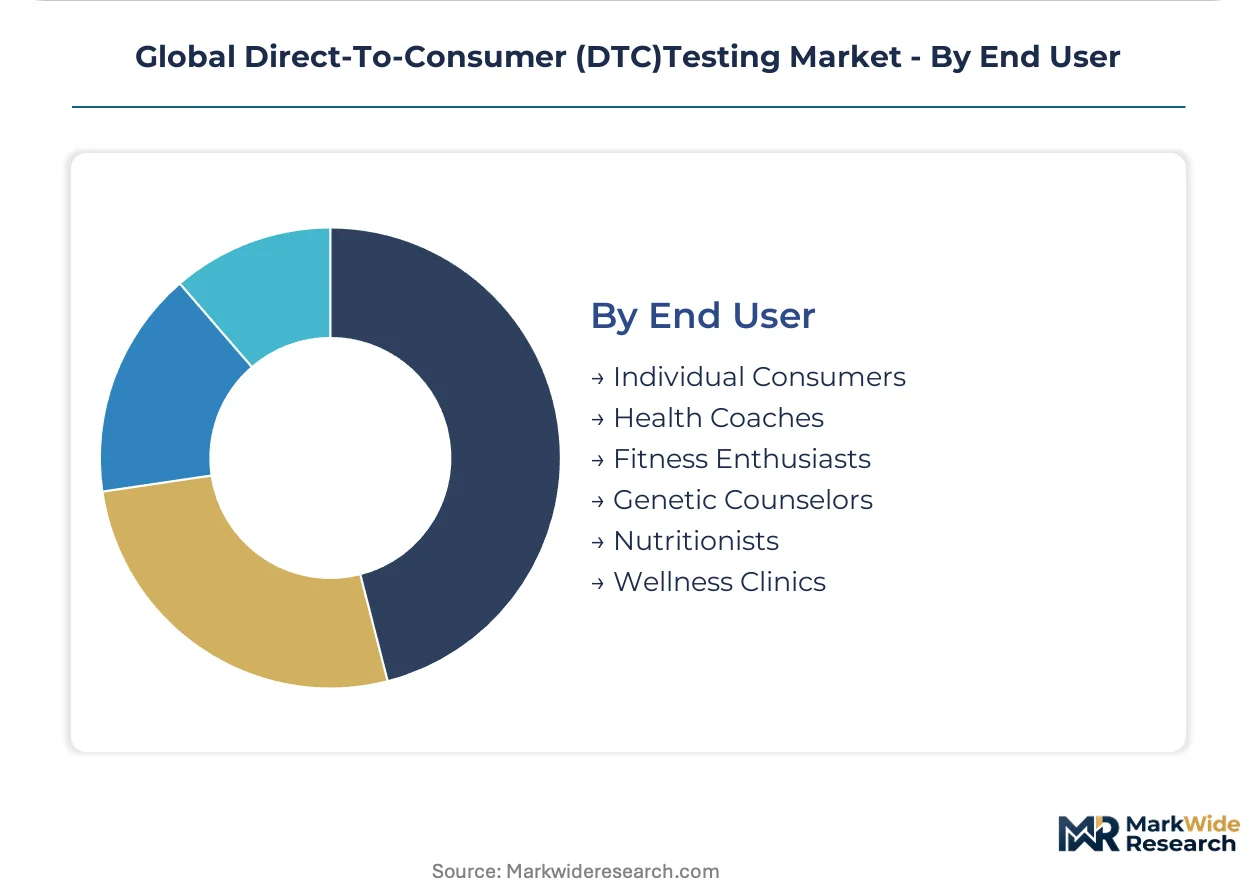
End User:
Volume concentration sits with individual consumers, though margin accretion flows to professional-guided applications where interpretation services justify premium pricing.
- Individual Consumers:Self-directed purchasers seeking health insights without clinical mediation. The mass-market foundation for ancestry and wellness testing in the United States and United Kingdom.
- Health Coaches:Certified practitioners incorporating biomarker data into lifestyle intervention programs. Functional medicine practices in California and Arizona drive recurring panel orders.
- Fitness Enthusiasts:Amateur and professional athletes optimizing training through physiological monitoring. CrossFit affiliates in Texas and Colorado bulk-purchase hormone and inflammation panels.
- Genetic Counselors:Licensed professionals interpreting pathogenic variant findings from expanded carrier screening. Hospital-affiliated practices in Massachusetts and Pennsylvania require CLIA-certified confirmatory testing.
- Nutritionists:Registered dietitians using micronutrient data to personalize supplementation protocols. Private practices in Germany and Switzerland integrate organic acid testing into metabolic assessments.
- Wellness Clinics:Integrative health facilities offering bundled diagnostic and treatment services. Concierge practices in New York and Los Angeles markup DTC kits through physician interpretation fees.
Individual Consumers anchor volume. Wellness Clinics extract the highest per-test margins through service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in direct-to-consumer diagnostic services, exporting CLIA-certified laboratory processing to Canadian and Australian consumers while importing specialized genetic arrays from East Asian contract manufacturers. Germany and the United Kingdom represent net importers of DTC testing infrastructure, relying on US-based bioinformatics platforms for polygenic risk interpretation.
United States
FDA 510(k) clearance acceleration and Medicare Advantage telehealth reimbursement expansion drive domestic kit volumes. The FTC polices advertising claims for predictive health utilities under Section 5 authority. California's Bay Area hosts the densest concentration of CAP/CLIA-certified facilities processing saliva-based sequencing for ancestry and pharmacogenomic applications.
Germany
BfArM oversight of health risk claims and BfDI enforcement of GDPR Article 9 genetic data protections shape market access conditions. The EU IVDR's 2022 implementation imposes eighteen-month notified body review timelines for class C devices. Munich and Berlin clusters specialize in microfluidic cartridge manufacturing for kitchen-counter chemistry analyzers.
United Kingdom
MHRA recognition of US FDA clearances streamlines parallel market entry for transatlantic platforms. The UK National Screening Committee's evolving stance on consumer-ordered cancer risk panels influences private payer behavior. London's Harley Street wellness clinics bundle DTC kits with physician interpretation services at premium markups.
India
Urban middle-class consumers in Mumbai and Bangalore seek alternatives to overloaded hospital laboratories for routine metabolic panels. CDSCO medical device rules apply to imported diagnostic kits, while domestic manufacturers benefit from PLI scheme incentives for in vitro diagnostic production. Hyderabad's diagnostic reagent cluster supplies stabilization buffers for ambient-temperature specimen shipping.
Australia
TGA inclusion of DTC genetic tests on the Australian Register of Therapeutic Goods requires local clinical evidence generation. The country's Therapeutic Goods Order mandates post-market surveillance for direct-access pathology services. Melbourne's biomedical precinct houses telehealth platforms integrating at-home collection with virtual result consultation for rural patient populations.
Global Direct-To-Consumer (DTC)Testing Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated laboratory networks, specialized genetic testing platforms, and retail-distributed wellness brands. Vertically integrated clinical laboratory giants compete against nimble digital health startups on specimen logistics speed and telehealth integration depth. Dominant competitive moves include CLIA laboratory acquisitions to secure processing capacity and exclusive retail pharmacy distribution agreements to lock in consumer access points.
Within the genetic testing archetype, 23andMe, Inc. and Ancestry occupy positions defined by proprietary biobank scale and consumer-facing brand recognition. Everlywell, Inc. exemplifies the retail-distributed wellness model, while Quest Diagnostics Incorporated anchors the clinical laboratory tier extending infrastructure into consumer channels. Color Health, Inc. represents the preventive care specialization vector, and Labcorp sits within the reference laboratory network category competing on turnaround velocity.
| Leading Market Players |
|---|
| 23andMe, Inc. |
| Ancestry |
| Color Health, Inc. |
| Everlywell, Inc. |
| LetsGetChecked |
| MyHeritage Ltd. |
| Helix, Inc. |
| Labcorp |
| Quest Diagnostics Incorporated |
| Others |
Supply & Pricing Matrix
Hyderabad's diagnostic reagent cluster supplies stabilization buffers for ambient-temperature specimen shipping, concentrating manufacturing leverage among a handful of chemical formulators who dictate terms to kit assemblers downstream. This geographic chokepoint amplifies pricing power for consumables while compressing margins at the brand level.
Pricing Analysis
Individual consumers anchor a subscription-dominant pricing structure where recurring biomarker panels lock in lifetime value against one-time ancestry purchases. Price differentiation rests on CLIA certification tier and telehealth integration depth, with diagnostic-grade assays commanding premiums over wellness screens. Cost compression in the entry-tier wellness segment is intensifying because of private-label pharmacy competition. Price sensitivity peaks among uninsured, self-pay users seeking routine metabolic panels.
Supply Chain Analysis
Extended payment terms from East Asian contract manufacturers now stretch to ninety days for genotyping array procurement, straining working capital for mid-tier platforms. Manufacturing concentrates in China, South Korea, and the United States for microfluidic cartridges, DNA extraction chemistry, and CAP/CLIA-certified laboratory automation. Raw material dependencies include stabilized saliva buffers, dried blood spot cards, and polymerase reagents. Single-source vulnerability sits with specialized genotyping chip foundries. Distribution runs through direct-to-consumer e-commerce platforms and retail pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-consumer testing sits in early-cycle expansion as telehealth reimbursement carve-outs and FDA 510(k) pathway acceleration unlock payer-covered segments previously confined to out-of-pocket purchase.
For Market Incumbents: Build captive CLIA laboratory networks as the defensive moat against capacity bottlenecks during demand surges. Acquire regional high-complexity certified facilities to secure processing throughput. Deepen backward integration into stabilization buffer chemistry to offset raw material cost volatility from Hyderabad suppliers. For New Entrants and Emerging Players: India's urban middle-class consumers in Mumbai and Bangalore represent the most penetrable entry point, bypassing overloaded hospital laboratories for routine metabolic panels. Telehealth-integrated subscription models for quarterly hormone tracking in perimenopausal populations offer a second white-space vector. Partner with corporate wellness programs to secure bulk kit commitments and reduce customer acquisition burn. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because CLIA certification scarcity and bioinformatics talent shortages favor scaled incumbents with captive laboratory infrastructure. Target acquisition profiles center on telehealth-integrated platforms with recurring revenue cohorts and established FDA clearance track records. The signal to watch is Medicare Advantage plan expansion of at-home diagnostic coverage as inflection indicator for reimbursement normalization.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Acquisition | Captive processing capacity insulates against demand surge bottlenecks and supplier concentration. |
| FDA 510(k) Clearance Pathway | Regulatory authorization unlocks retail pharmacy distribution and telehealth reimbursement integration. |
| Telehealth Platform Integration | Virtual physician consultation layers transform wellness screens into diagnostic-grade reimbursable services. |
| Subscription Biomarker Tracking | Quarterly kit cadence locks customer lifetime value and reduces acquisition cost versus one-time purchases. |
| Corporate Wellness Partnership | Employer-subsidized screening expands addressable population beyond self-pay consumer base. |
Research Methodology
Cross-validation between primary interviews with CLIA laboratory directors, telehealth platform executives, and genetic counselors and secondary validation through FDA 510(k) filings, CMS reimbursement databases, and EU IVDR notified body registries anchors the qualitative findings. Bottom-up triangulation against top-down macroeconomic indicators ensures segmentation coherence across product type, application, delivery model, and end user dimensions.
Calibration against historical kit volume trajectories and telehealth adoption curves shapes the analytical framework across the projection horizon. Segmentation modeling spans genetic versus wellness assay categories, subscription versus transactional revenue models, and CLIA-certified versus non-certified processing tiers. CAGRs derive from weighted average growth rates across these segments, with inputs including laboratory capacity expansion schedules and regulatory approval timelines.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending and private insurance reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions about FDA clearance velocity and telehealth parity legislation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Solid Tumor Testing Market
Testing Services
Home DNA Testing Market
Testing Services
Mask Bacterial Filtration Efficiency Tester Market
Testing Services
Blood Pressure Test Market
Testing Services
In-Vitro Toxicology Testing Market
Testing Services
Global Newborn Screening Market
Testing Services
Endocrine Peptides Test Market
Testing Services
Nipah Virus (Niv) Infection Testing Market
Testing Services
Urine Sediment Testing Market
Testing Services
North America Testing Inspection and Certification (TIC) Market
Testing Services
Global Endotoxin and Pyrogen Testing Market
Testing Services
IVD Quality Control Market
Testing Services
Over-The-Counter Tests Market
Testing Services
Sterilization Monitoring Technologies Market
Testing Services
Global Sleep Testing Services Market
Testing Services
Global Molecular Quality Controls Market