
 D-Dimer Market | 2026-2036
D-Dimer Market Size, Share, and Industry Trends Forecast 2026-2036
D-Dimer Market Analysis
Instrument-embedded software licensing is recalibrating how laboratories acquire D-dimer testing capability, shifting capital expenditure into recurring subscription streams. Siemens Healthineers leverages this model across its Atellica platforms, while Roche Diagnostics sustains high-margin consumable pull-through on cobas systems. Abbott Laboratories competes through point-of-care instruments that reduce sample-to-result intervals in emergency settings.
D-dimer denotes fibrin degradation products circulating after plasmin-mediated clot dissolution, specifically measuring cross-linked fibrin fragments with molecular weights spanning 180-240 kDa; clinicians deploy this biomarker primarily to exclude thromboembolic disease when pre-test probability is low. Reagents and assays capture the dominant share of product-type revenue, reflecting recurring purchase patterns tied to instrument installed bases. Point-of-care testing represents the fastest-growing technology segment, driven by emergency department demand for rapid turnaround. Hospitals remain the largest end-user channel, though diagnostic laboratories are gaining share through centralized high-throughput workflows.
The FDA governs analytical performance claims for D-dimer assays through 510(k) clearance pathways, while Clinical Laboratory Improvement Amendments mandate proficiency testing for laboratories performing moderate- and high-complexity testing. ISO 15189 accreditation shapes quality management expectations for diagnostic laboratories in Europe and Asia-Pacific markets. Stakeholders must monitor evolving regulatory frameworks for assay harmonization and inter-laboratory standardization as multiplex thrombosis panels enter clinical validation.
Market Dynamics
Emergency department triage protocols are compressing turnaround-time requirements for D-dimer assays, forcing laboratories to reconfigure workflows around rapid-result instrumentation and recalibrating capital deployment toward point-of-care platforms.
Growth Catalysts
- Outpatient thrombosis protocols:Diagnostic laboratories in the United States are expanding testing volumes as physician practices adopt same-day rule-out algorithms for venous thromboembolism.
- ISO 15189 accreditation:European diagnostic laboratories pursuing this quality management standard are driving demand for harmonized assay performance across multi-site networks.
- Multiplex thrombosis panels:Clinical validation of combined biomarker platforms is creating pull-through for D-dimer as a standard component in integrated coagulation testing.
Market Restraints
- Assay harmonization gaps:Inter-laboratory variability in D-dimer cutoffs limits clinical utility and complicates multi-site standardization efforts.
- Input cost volatility:Monoclonal antibody reagents face supply concentration risks from Chinese contract manufacturing organizations.
- Substitution pressure:Computed tomography pulmonary angiography retains diagnostic primacy in intermediate-risk patients despite radiation exposure tradeoffs.
Strategic Opportunities
- Rural emergency departments:Underpenetrated United States facilities lack on-site coagulation testing and represent white space for cartridge-based instruments.
- Subscription licensing models:Instrument-embedded software agreements convert capital expenditure into recurring revenue streams for manufacturers.
- WHO prequalification pathway:Emerging market access programs could accelerate deployment in low-resource settings lacking centralized laboratory infrastructure.
Industry Challenges
- Proficiency testing complexity:Clinical Laboratory Improvement Amendments mandates for moderate- and high-complexity testing impose ongoing compliance burdens on hospital laboratories.
- Legacy system integration:Point-of-care instruments require middleware connectivity to existing laboratory information systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | D-Dimer Market |
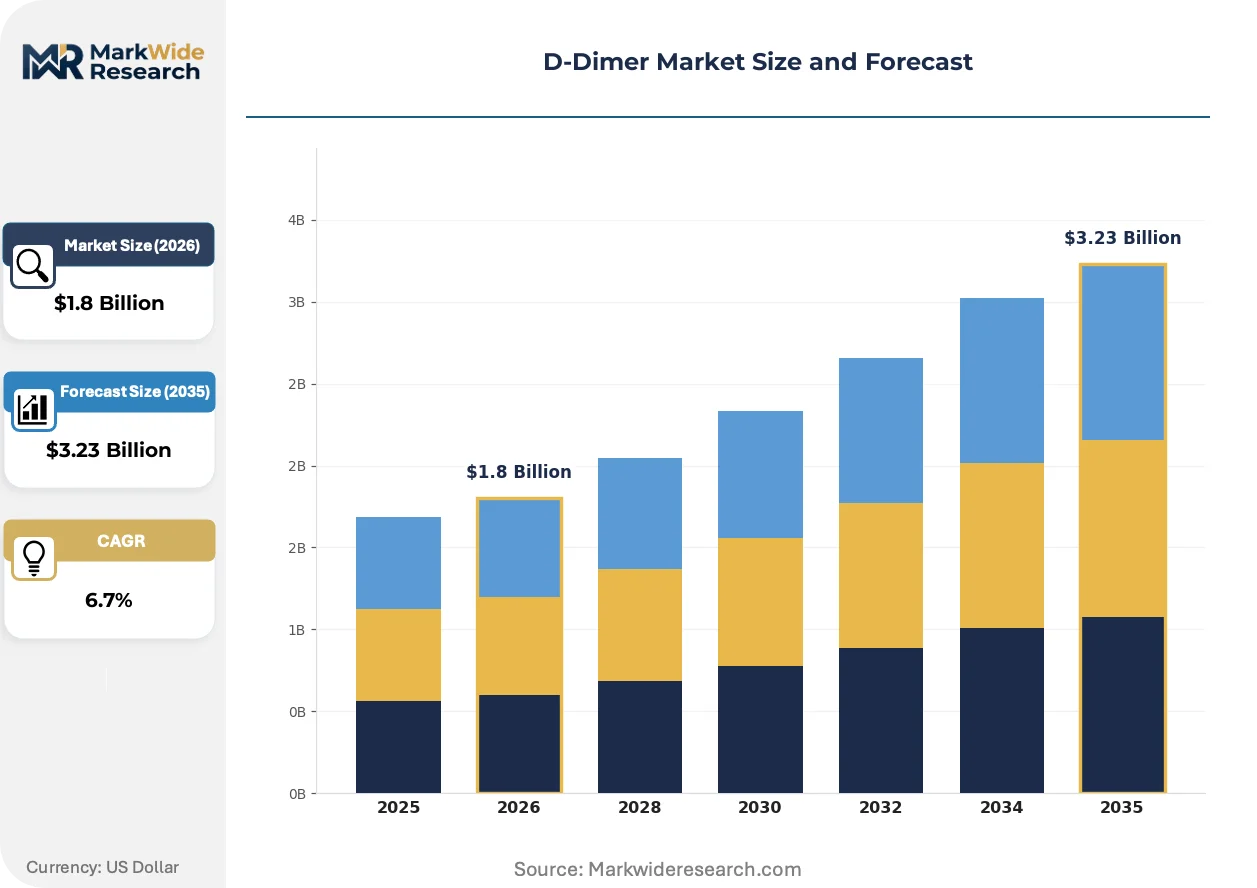
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Assays, Test Kits, Instruments End User: Hospitals, Diagnostic Laboratories, Clinics, Research Institutions Technology: Immunoassays, Enzymatic Assays, Molecular Diagnostics, Point-of-Care Testing Application: Thrombosis Detection, Pulmonary Embolism, Deep Vein Thrombosis, Routine Screening |
| Companies Covered | Siemens Healthineers, Roche Diagnostics, Abbott Laboratories, Thermo Fisher Scientific, bioMérieux, Beckman Coulter, Sysmex Corporation, Sekisui Diagnostics, Diazyme Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
D-Dimer Market Emerging Trajectories
Workflow compression in acute care settings is redefining competitive advantage around speed-to-result rather than throughput volume alone, reshaping how manufacturers architect instrument portfolios and service delivery models.
Microfluidic cartridge technology is modularizing D-dimer testing by embedding sample preparation, reagent storage, and optical detection into disposable single-use cassettes. Emergency departments in the United States are adopting these platforms to bypass central laboratory queues. This architecture is modularizing the traditional separation between near-patient testing and laboratory-grade analytical performance.
The FDA's evolving guidance on in vitro diagnostic performance standards is tightening analytical sensitivity requirements for 510(k) cleared assays. Manufacturers must now demonstrate improved precision at clinical decision thresholds to maintain market access. High-throughput laboratory segments are responding by consolidating purchasing around platforms with demonstrated harmonization across multiple FDA-cleared methods.
Academic medical centers are unbundling after-sales service contracts from instrument procurement, negotiating standalone preventive maintenance agreements with third-party service organizations. This behavior is compressing manufacturer service margins while creating openings for independent service providers. The United States market exhibits this pattern most acutely as health system consolidation concentrates purchasing leverage.
D-Dimer Market Segmentation
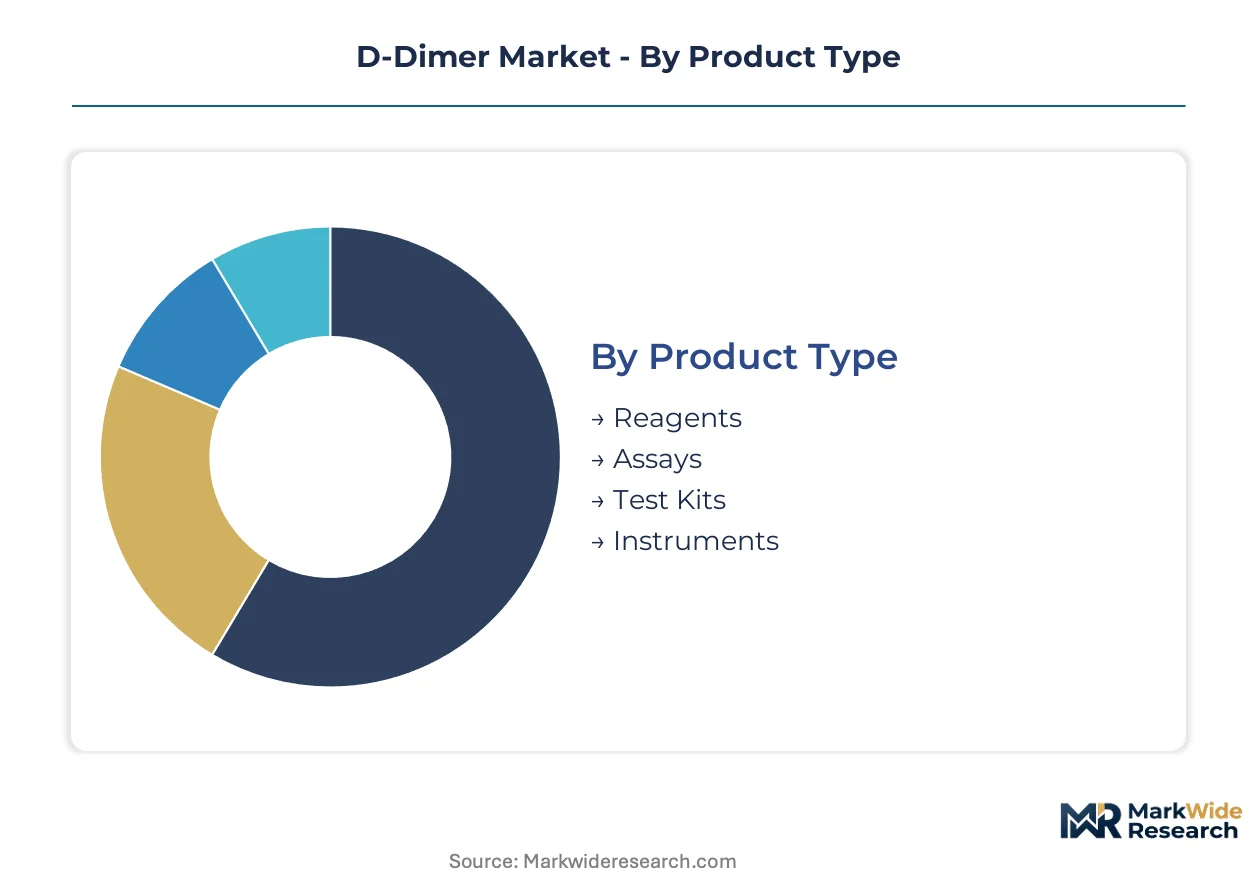
D-dimer market segmentation reveals divergent margin structures across product categories. Laboratories prioritize consumable economics while emergency departments optimize for speed-to-result, creating distinct purchasing logics within the same biomarker category.
Product Type:
Volume concentration sits with recurring consumables while instruments command premium placement through capital cycles.
- Reagents:Monoclonal antibody formulations targeting D-dimer epitopes with molecular specificity requirements. United States hospital laboratories concentrate procurement here, driven by CLIA-mandated proficiency testing compliance burdens that lock in validated reagent suppliers.
- Assays:Pre-configured test protocols with established analytical sensitivity claims for FDA 510(k) clearance. Diagnostic laboratories expanding outpatient thrombosis protocols in the United States favor these for workflow standardization across multi-site networks.
- Test Kits:Bundled consumable packages for specific instrument platforms.
- Instruments:Analytical hardware with embedded software licensing for result interpretation.
Today's leader: Reagents. Tomorrow's challenger: Instruments.
End User:
Customer type determines speed requirements versus throughput economics, splitting procurement between emergency triage and centralized laboratory models.
- Hospitals:Integrated health systems with emergency department triage protocols demanding sub-60-minute turnaround times. United States facilities concentrate purchasing leverage through group purchasing organizations, compressing reagent pricing while prioritizing instrument reliability metrics.
- Diagnostic Laboratories:Centralized high-throughput operations processing venous thromboembolism rule-out panels. ISO 15189-accredited European networks drive harmonization requirements across multi-site quality management systems.
- Clinics:Physician practices adopting same-day outpatient thrombosis protocols.
- Research Institutions:Academic medical centers validating multiplex thrombosis biomarker platforms.
Centralized laboratories capture volume leadership. Point-of-care deployment in hospitals gains the steepest expansion trajectory.
Technology:
Maturity gradients separate established immunoassay platforms from emerging cartridge architectures.
- Point-of-Care Testing:Microfluidic cartridge systems embedding sample preparation, reagent storage, and optical detection into single-use cassettes. United States emergency departments adopt these to bypass central laboratory queues, with rural facilities representing underpenetrated white space.
- Immunoassays:Enzyme-linked and chemiluminescent methods with established FDA-cleared performance claims. High-throughput laboratories consolidate purchasing here, responding to tightened FDA analytical sensitivity guidance through demonstrated harmonization across multiple cleared methods.
- Enzymatic Assays:Alternative detection chemistries with specific substrate kinetics.
- Molecular Diagnostics:Nucleic acid amplification methods with limited current D-dimer application.
Established platforms anchor current revenue. Cartridge-based near-patient systems are climbing the fastest.
Application:
Clinical utility intensity varies from definitive rule-out protocols to population screening with lower specificity requirements.
- Pulmonary Embolism:Emergency department triage algorithms incorporating age-adjusted D-dimer cutoffs to exclude thromboembolic disease when pre-test probability is low. United States facilities drive demand concentration here, with algorithm adoption expanding same-day discharge protocols.
- Deep Vein Thrombosis:Outpatient rule-out pathways requiring rapid result turnaround. Diagnostic laboratories in the United States expand testing volumes as physician practices adopt centralized venous thromboembolism assessment protocols.
- Thrombosis Detection:General coagulation disorder assessment across inpatient populations.
- Routine Screening:Asymptomatic population testing with elevated false-positive risk.
Pulmonary embolism exclusion commands premium positioning. Deep vein thrombosis protocols are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates emergency department demand for rapid D-dimer testing, while Germany drives harmonization requirements through ISO 15189-accredited laboratory networks. National regulatory frameworks and purchasing structures diverge sharply across major markets.
United States
Emergency department triage algorithms and outpatient thrombosis protocols propel testing volume expansion. The FDA governs analytical performance claims through 510(k) clearance pathways with tightening sensitivity requirements. Hospital systems in the Northeast Corridor leverage group purchasing organizations to compress reagent pricing while prioritizing instrument reliability.
Germany
Diagnostic laboratory consolidation and multi-site quality management systems create demand for harmonized assay performance. The country's national pharmaceutical regulator enforces MDR compliance for in vitro diagnostic devices. Industrial clusters in Baden-Württemberg host precision instrument manufacturing for high-throughput coagulation platforms.
Japan
Aging demographics and venous thromboembolism screening programs expand testing volumes in acute care settings. METI coordinates industrial policy for domestic diagnostic equipment production. The Kanto region around Tokyo concentrates purchasing decisions for major university hospital networks.
China
Centralized laboratory infrastructure expansion in tier-two cities creates demand for automated coagulation systems. NMPA oversees clinical trial requirements for imported diagnostic assays. The Yangtze River Delta region hosts contract manufacturing organizations producing monoclonal antibody reagents.
India
Diagnostic laboratory chains in metropolitan areas adopt international quality standards for thrombosis testing panels. CDSCO regulates import licensing for IVD reagents and instruments. Maharashtra state concentrates private diagnostic infrastructure investment in Mumbai and Pune corridors.
D-Dimer Market Vendor Landscape
Top-tier vendors anchor the high-throughput laboratory segment, while mid-tier specialists occupy point-of-care and regional diagnostic niches. Siemens Healthineers and Roche Diagnostics command installed base advantages through embedded software licensing models. The competitive terrain splits between platform-integrated systems and cartridge-based emergency instruments. Consolidation pressure intensifies as health system purchasing leverage concentrates procurement decisions.
Among diversified health technology conglomerates, Siemens Healthineers, Roche Diagnostics, and Abbott Laboratories occupy positions spanning laboratory automation and near-patient testing. These entities exemplify contrasting commercial architectures: subscription-based software licensing, high-margin consumable pull-through, and point-of-care speed optimization respectively. Their collective presence shapes pricing benchmarks and service delivery expectations across hospital and laboratory channels.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Roche Diagnostics |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| bioMérieux |
| Beckman Coulter |
| Sysmex Corporation |
| Sekisui Diagnostics |
| Diazyme Laboratories |
| Others |
Supply Flow & Price Mechanics
Performance-grade stratification between FDA-cleared high-sensitivity assays and standard laboratory methods manifests divergent margin architectures across procurement channels, with premium tiers commanding subscription-based software licensing while commodity reagents face group purchasing organization compression in United States hospital systems.
Pricing Analysis
Capacity additions in Chinese contract manufacturing organizations are reshaping price floors for monoclonal antibody reagents while tightening margins on consumable supply contracts. Three-tier pricing structure across premium, standard, and economy levels separates Siemens Healthineers' embedded software licensing from Roche's high-margin consumable pull-through and Abbott's point-of-care cartridge economics. Cost compression in standard immunoassay reagents is intensifying because diagnostic laboratory consolidation concentrates purchasing leverage. Emergency departments exhibit least price sensitivity due to speed-to-result imperatives, while rural clinics demonstrate highest sensitivity to per-test costs.
Supply Chain Analysis
Monoclonal antibody production rests on Chinese contract manufacturing organizations, German precision instrument fabrication, and United States optical detection component suppliers. Raw material dependencies span recombinant protein substrates, specialized fluorophores, and precision-molded microfluidic polymers. Single-source vulnerability concentrates in Chinese reagent manufacturing amid geopolitical trade friction. Distribution runs through group purchasing organizations for United States hospital systems, direct instrument leasing for European ISO 15189-accredited networks, and third-party diagnostic distributors for emerging market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The D-dimer market represents a late-cycle quality story where emergency department triage protocols and outpatient thrombosis algorithms are elevating analytical sensitivity requirements toward premium-tier assay performance.
For Market Incumbents: Deploy embedded software licensing as the defensive anchor, converting capital expenditure into recurring revenue streams that lock in consumable pull-through. Siemens Healthineers and Roche Diagnostics should deepen backward integration into monoclonal antibody production to mitigate Chinese supply concentration risks. Incumbents must preempt cartridge-based point-of-care substitution by accelerating microfluidic platform development for rural emergency department white space.
For New Entrants and Emerging Players: Digital-channel direct contracting with independent service organizations offers bypass around incumbent after-sales service moats. Underpenetrated rural United States emergency departments lacking on-site coagulation testing represent the most accessible entry segment. New entrants should target WHO prequalification pathway acceleration for emerging market access where centralized laboratory infrastructure remains underdeveloped.
For Investors and Strategic Acquirers: Asymmetric upside sits with point-of-care microfluidic specialists possessing cartridge manufacturing scale and FDA 510(k) clearance momentum. The five-to-ten year viability window favors platforms integrating D-dimer into multiplex thrombosis panels. Watch FDA analytical sensitivity guidance tightening as the signal for consolidation acceleration around harmonization-capable assay portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidic Cartridge Development | Emergency departments in the United States bypass central laboratory queues through single-use cassette architectures. |
| FDA 510(k) Submission Acceleration | Tightened analytical sensitivity requirements demand improved precision at clinical decision thresholds for market access. |
| Hospital System Partnership | Group purchasing organizations in the United States consolidate procurement leverage around instrument reliability metrics. |
| Software Companion Development | Embedded licensing models on Atellica and cobas platforms convert capital expenditure into recurring subscription revenue. |
| Reimbursement Strategy | CMS coverage determinations for same-day venous thromboembolism rule-out protocols shape test volume economics. |
Methodological Framework
Direct dialogue with emergency department physicians, hospital laboratory directors, diagnostic reagent procurement managers, and FDA regulatory affairs specialists grounded qualitative findings, cross-referenced against FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, hospital procurement contract disclosures, and ISO 15189 accreditation registries. Bottom-up and top-down triangulation validated segment-level assumptions across product categories and end-user channels.
Bottom-up modeling anchored volume projections to instrument installed bases, reagent consumption patterns, and test-per-patient protocol adoption rates across the analysis window. Segmentation dimensions spanned technology maturity gradients, end-user workflow requirements, and regional regulatory cluster variations. CAGRs derived from logistic diffusion curves for point-of-care adoption and linear extrapolation for mature immunoassay segments. Forecast inputs incorporated emergency department triage algorithm penetration rates and outpatient thrombosis protocol expansion trajectories.
The model assumes a particular technology adoption path; alternative pathways for microfluidic cartridge standardization would alter the outlook. Forecasts reflect assumptions around FDA analytical sensitivity guidance evolution, Chinese contract manufacturing stability, and group purchasing organization consolidation momentum. A small set of named triggers—WHO prequalification pathway acceleration, MDR compliance enforcement in Europe, and rural emergency department infrastructure investment—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Germany in-Vitro Diagnostics Market
Diagnostics
LDL Test Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
South Africa in-Vitro Diagnostics Market
Diagnostics
Home Diagnostics Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market
Diagnostics
North America Autoimmune Disease Diagnostics Market
Diagnostics
North America Non-Hodgkin Lymphoma Diagnostics Market
Diagnostics
Global RSV Diagnostics Market
Diagnostics
Chile in Vitro Diagnostics Market
Diagnostics
Pathogen Detection Market
Diagnostics
UAE in Vitro Diagnostics Market
Diagnostics
Liver Function Tests Market
Diagnostics
Creatinine Test Market
Diagnostics
Haptoglobin Reagent Market