
 At-Home Hematology Testing Market | 2026-2036
At-Home Hematology Testing Market Size, Share, and Industry Trends Forecast 2026-2036
At-Home Hematology Testing Market Analytics
Silicon photonics is repositioning the cost structure of optical sensor modules in at-home hematology devices, displacing legacy LED-photodiode assemblies that dominated earlier generations. Abbott Laboratories leverages its diagnostic R&D infrastructure to sustain technology leadership in miniaturized assay platforms. Sysmex Corporation anchors its competitive stance through precision manufacturing scale in automated cell counting subsystems. Siemens Healthineers differentiates via channel control across hospital-at-home networks in North America and Western Europe.
At-home hematology testing encompasses the quantitative and qualitative analysis of blood parameters conducted outside clinical laboratories, typically requiring sample volumes below 500 microliters and delivering results through integrated digital interfaces within 10 minutes for key metrics such as hemoglobin, hematocrit, and white blood cell differentials. The primary purpose is enabling chronic disease surveillance and therapeutic monitoring without facility-based phlebotomy. Test kits and portable devices currently occupy the largest revenue pools, though microfluidics-based platforms represent the fastest-expanding technology tier as lab-on-a-chip architectures reduce reagent consumption and device footprint. Digital monitors serving health monitoring applications are maturing fastest, while blood collection tools face margin compression from commoditization.
FDA 510(k) pathways and Clinical Laboratory Improvement Amendments standards govern U.S. market access, while the EU Medical Device Regulation imposes stricter post-market surveillance and notified body oversight on hematology devices sold in Europe. These frameworks elevate compliance costs but simultaneously validate product reliability for risk-averse home users and payer organizations. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring as these determinations will dictate which at-home hematology applications achieve sustainable commercial scale.
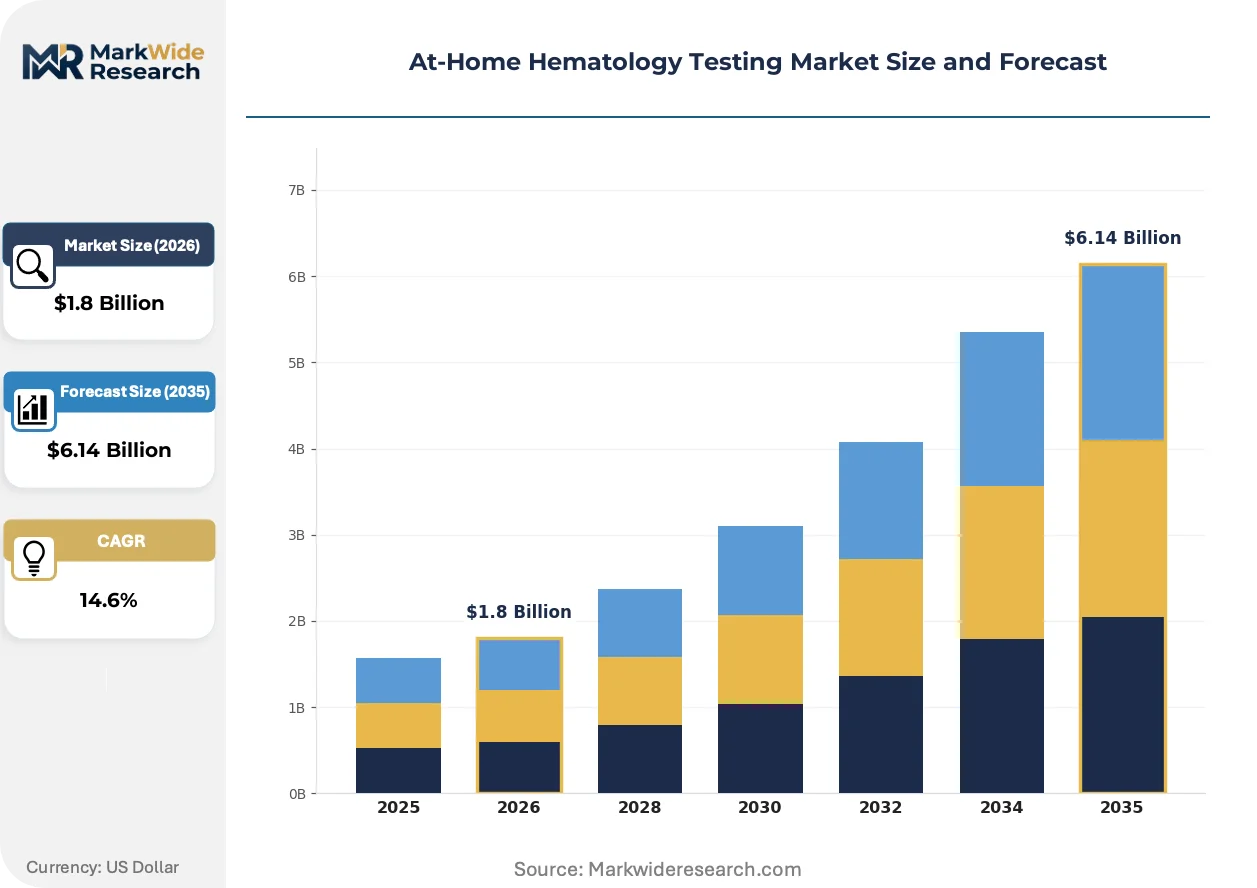
Market Dynamics
Silicon photonics is compressing bill-of-materials costs for optical sensor modules while FDA 510(k) pathways accelerate clearance timelines for over-the-counter hematology devices, creating simultaneous supply-side and demand-side momentum for home-based diagnostics.
Growth Catalysts
- FDA 510(k) Pathway Compression:Streamlined clearance protocols for Class II hematology devices reduce time-to-market by 40-60 percent versus premarket approval routes, enabling faster commercialization of finger-prick analyzers.
- Chronic Disease Self-Monitoring Protocols:Oncology and hematology patients now manage therapeutic drug monitoring at home, eliminating facility-based phlebotomy for routine complete blood count surveillance.
- Silicon Photonics Integration:Wafer-scale manufacturing of photonic integrated circuits replaces discrete LED-photodiode assemblies, collapsing per-unit sensor costs for optical detection subsystems.
Market Restraints
- EU MDR Post-Market Surveillance Burden:Stricter notified body oversight and clinical follow-up requirements under the Medical Device Regulation elevate compliance costs for hematology platforms seeking European market access.
- Reagent Stability Constraints:Lyophilized reagent cartridges face temperature sensitivity limitations that complicate distribution through direct-to-consumer channels without cold chain infrastructure.
- Clinical Validation Requirements:Demonstrating equivalence to laboratory-grade analyzers demands large-scale studies against predicate devices, creating capital intensity barriers for mid-stage developers.
Strategic Opportunities
- Remote Patient Monitoring Reimbursement Codes:CMS reimbursement determinations for CPT codes covering home-based hematology monitoring will dictate which applications achieve sustainable commercial scale in the United States.
- Microfluidics-Paper Hybrid Architectures:Converging lab-on-a-chip precision with lateral flow simplicity enables sub-dollar test costs for anemia screening in resource-limited settings.
- Hospital-at-Home Network Integration:Siemens Healthineers and integrated delivery networks are embedding hematology devices into acute-level home care protocols, expanding addressable volume beyond traditional chronic disease management.
Industry Challenges
- CLIA Waived Test Complexity:Achieving Clinical Laboratory Improvement Amendments waiver status requires simplified operator procedures that conflict with multi-parameter analytical performance goals for white blood cell differentials.
- Interoperability with Electronic Health Records:Home hematology devices must integrate with Epic, Cerner, and other dominant EHR platforms through HL7 FHIR standards, creating software validation bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | At-Home Hematology Testing Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Test Kits, Digital Monitors, Blood Collection Tools Application: Blood Disorders, Health Monitoring, Chronic Disease Management, Preventive Testing End User: Home Users, Patients, Caregivers, Healthcare Professionals Technology: Microfluidics, Lab-on-a-Chip, Colorimetric Assays, Optical Sensors |
| Companies Covered | Sysmex Corporation, HORIBA Ltd, Abbott Laboratories, Beckman Coulter, Mindray Medical International Limited, Siemens Healthineers, F. Hoffmann-La Roche Ltd, Hemocue, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
At-Home Hematology Testing Market Evolving Landscape
Technology convergence, regulatory pathway evolution, and channel restructuring are simultaneously reshaping how hematology diagnostics reach end users outside clinical laboratories.
Photonic integrated circuits are unifying excitation, detection, and signal processing functions onto single silicon substrates. Chronic disease patients in the United States are adopting these platforms fastest as self-monitoring protocols expand. This unification is collapsing the cost floor for optical sensor modules, enabling sub-fifty-dollar device price points that unlock mass-market anemia screening.
EU Medical Device Regulation notified body capacity constraints are extending certification timelines for hematology platforms seeking CE marking. Manufacturers are responding by front-loading clinical evidence generation and engaging multiple notified bodies simultaneously. In-vitro diagnostic subclasses with established predicate devices face shorter queues than novel microfluidics architectures.
Direct-to-consumer diagnostic channels are displacing traditional clinical laboratory referral networks as the primary patient acquisition pathway. Amazon, CVS MinuteClinic, and specialized telehealth platforms now bundle home hematology testing with virtual consultation services. This channel shift concentrates demand in the United States where consumer diagnostic regulations and retail pharmacy integration are most developed.
At-Home Hematology Testing Market Segmentation
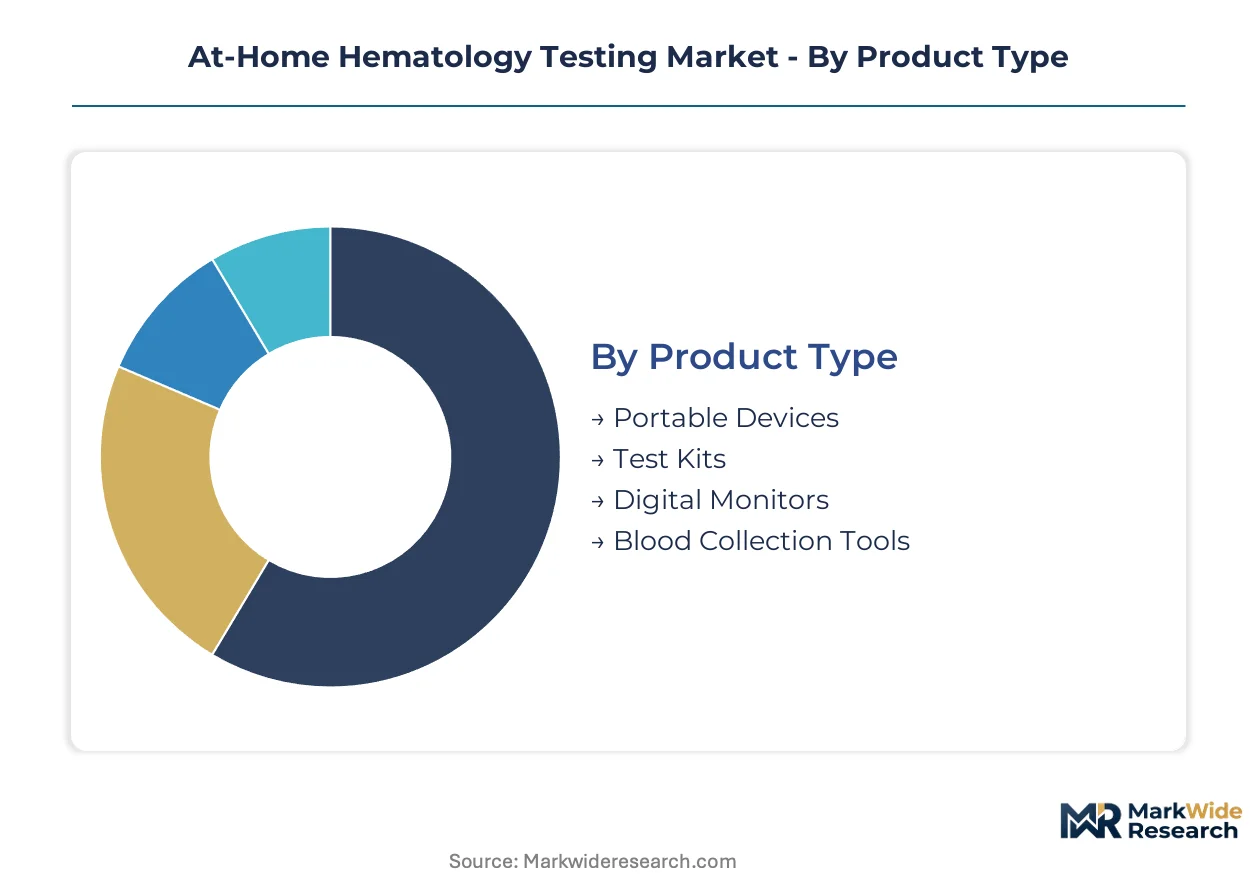
Segmentation in at-home hematology testing reveals how device complexity, user sophistication, and reimbursement pathways fragment commercial opportunity. Each axis—product form, clinical use case, user type, and underlying technology—carries distinct margin profiles and regulatory requirements that shape go-to-market strategy.
Product Type:
Silicon photonics integration is collapsing the cost floor across optical detection subsystems, reshaping which product formats achieve mass-market viability versus premium positioning.
- Portable Devices:Handheld analyzers integrating microfluidic cartridges with photonic sensors deliver multi-parameter complete blood counts from finger-prick samples. Demand concentrates in the United States where CMS reimbursement for remote patient monitoring codes validates out-of-pocket spending by chronic disease patients.
- Test Kits:Disposable reagent cartridges and lateral flow cassettes enable single-use anemia screening without capital equipment investment. European adoption lags due to EU MDR notified body backlogs extending CE marking timelines for novel IVD platforms.
- Digital Monitors:Bluetooth-enabled readers transmitting results to smartphone applications and EHR systems. These platforms mature fastest as Epic and Cerner integration becomes table stakes for hospital-at-home network inclusion.
- Blood Collection Tools:Micro-needle arrays and capillary tube systems for low-volume sampling. Margin compression from commoditization intensifies as Chinese manufacturers scale lancet production.
Test kits lead on scale; portable devices lead on momentum.
Application:
Reimbursement code specificity determines which clinical use cases sustain commercial viability versus remaining niche direct-to-consumer propositions.
- Chronic Disease Management:Therapeutic drug monitoring for oncology and hematology patients eliminating facility-based phlebotomy. United States demand accelerates as integrated delivery networks embed these protocols into hospital-at-home programs.
- Health Monitoring:Wellness-oriented tracking of hemoglobin and hematocrit for fitness and nutritional optimization. Direct-to-consumer channels through Amazon and CVS MinuteClinic dominate patient acquisition.
- Blood Disorders:Sickle cell, thalassemia, and hemophilia surveillance requiring precise white blood cell differentials. CLIA waiver constraints limit multi-parameter performance in simplified operator formats.
- Preventive Testing:Population-scale anemia screening in resource-limited settings. Microfluidics-paper hybrid architectures target sub-dollar test costs for India and sub-Saharan Africa distribution.
Chronic disease management commands premium pricing; health monitoring expands addressable volume fastest.
End User:
Operator capability stratification dictates interface design, regulatory pathway, and support infrastructure requirements across user categories.
- Patients:Individuals managing diagnosed conditions with prescribed monitoring protocols. FDA 510(k) clearance for over-the-counter use compresses time-to-market versus prescription-only devices.
- Home Users:Undiagnosed consumers seeking proactive health insights. Liability exposure from false negative results elevates error-proofing requirements in industrial design.
- Caregivers:Family members administering tests for elderly or pediatric populations. Training burden reduction becomes critical design priority for dementia and pediatric applications.
- Healthcare Professionals:Nurse practitioners and physician assistants in retail clinic and telehealth settings. CLIA waived status mandatory for point-of-care deployment without laboratory director oversight.
Patients generate recurring revenue; home users represent untapped penetration upside.
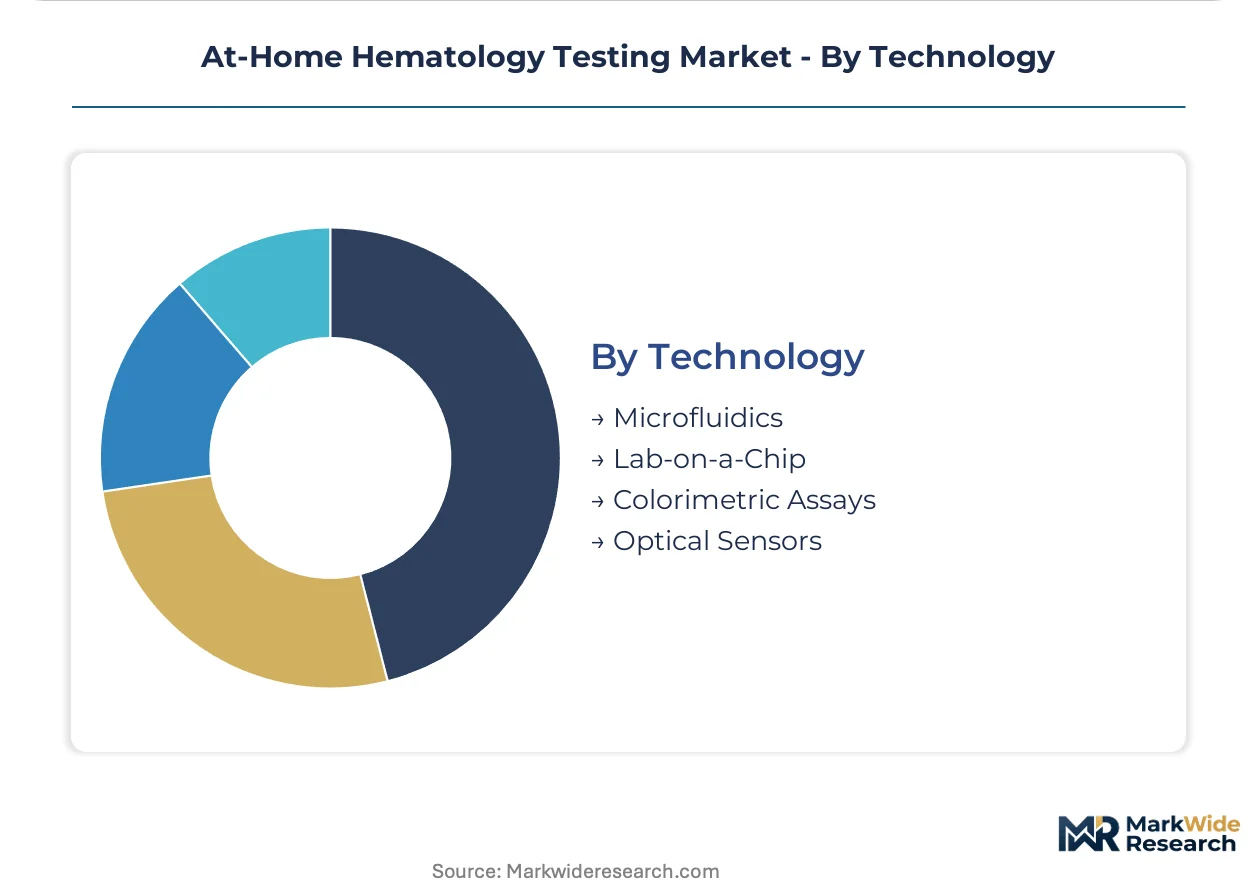
Technology:
Wafer-scale manufacturing economics and optical detection performance specifications determine which technology platforms achieve cost-parity with laboratory analyzers.
- Microfluidics:Precision-molded channels manipulating sub-microliter reagent volumes. Abbott Laboratories and Sysmex anchor manufacturing scale in automated cell counting subsystems.
- Lab-on-a-Chip:Monolithic integration of sample preparation, reaction, and detection on single substrates. EU MDR clinical evidence requirements extend development timelines for novel architectures.
- Optical Sensors:Photonic integrated circuits replacing discrete LED-photodiode assemblies. Silicon foundry partnerships with Tower Semiconductor and GlobalFoundries enable sub-fifty-dollar module costs.
- Colorimetric Assays:Visual or camera-based interpretation of reagent color change. Lateral flow simplicity suits resource-limited distribution without cold chain infrastructure.
Optical sensors dominate cost reduction; microfluidics delivers performance differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's photonics foundry ecosystem anchors supply-side concentration for optical sensor modules serving at-home hematology devices. Demand fragmentation across regulatory jurisdictions creates divergent commercialization timelines. National reimbursement frameworks and diagnostic device classifications determine which regional markets sustain premium pricing versus commodity penetration.
United States
Oncology therapeutic drug monitoring and hospital-at-home network integration drive patient adoption of finger-prick analyzers. FDA 510(k) clearance pathways compress regulatory timelines for Class II hematology devices versus premarket approval routes. Abbott Laboratories and Danaher Corporation concentrate R&D operations in San Diego and Boston corridors respectively.
Germany
EU MDR notified body oversight extends CE marking timelines for novel microfluidics platforms entering European markets. Siemens Healthineers leverages domestic manufacturing scale in Erlangen for automated cell counting subsystems. Bavaria's precision engineering clusters supply molded polymer microchannels to device integrators.
Japan
Aging demographics and home-based chronic disease management protocols expand addressable volume for self-monitoring hematology platforms. PMDA consultation pathways guide manufacturers through quality management system requirements for in-vitro diagnostics. Sysmex Corporation anchors production in Kobe for hematology analyzer subsystems.
China
Domestic anemia screening programs in rural health stations create volume demand for sub-dollar test formats. NMPA Class II medical device registration requires clinical validation studies conducted at designated testing institutions. Shenzhen's electronics manufacturing clusters produce Bluetooth-enabled digital monitors for export markets.
India
Thalassemia and sickle cell surveillance programs in Maharashtra and Gujarat generate institutional procurement for portable hemoglobinometers. CDSCO medical device rules mandate import license requirements for foreign-manufactured diagnostic platforms. Bengaluru's medical technology startups develop colorimetric assay readers for resource-limited settings.
At-Home Hematology Testing Market Competitive Landscape
Strategic partnerships dominate the current landscape as device manufacturers secure silicon foundry capacity and distribution channel access. The vendor base stratifies across three tiers: diversified diagnostics conglomerates with CLIA-waived portfolios, precision manufacturing specialists in automated cell counting, and emerging microfluidics platform developers. Technology licensing agreements and hospital-at-home network integration represent the primary competitive vectors reshaping market positions.
Within the diversified diagnostics tier, Abbott Laboratories and Danaher Corporation exemplify integrated device-reagent business models spanning professional and consumer channels. Siemens Healthineers occupies a position at the intersection of hospital-at-home infrastructure and regulatory-scale manufacturing. Sysmex Corporation anchors the precision manufacturing archetype through automated hematology subsystem supply. Among emerging platform developers, Mindray Medical International Limited represents Chinese manufacturing scale targeting cost-sensitive diagnostic segments. HORIBA Ltd exemplifies optical detection specialization derived from core analytical instrumentation expertise.
| Leading Market Players |
|---|
| Sysmex Corporation |
| HORIBA Ltd |
| Abbott Laboratories |
| Beckman Coulter |
| Mindray Medical International Limited |
| Siemens Healthineers |
| F. Hoffmann-La Roche Ltd |
| Hemocue |
| Danaher Corporation |
| Others |
Value Network & Pricing Analysis
Integrated delivery networks and hospital-at-home programs in the United States concentrate procurement volume for multi-parameter analyzers, anchoring a contract-based pricing model where annual device-reagent bundles dominate transactional single-unit sales. This buyer concentration enables manufacturers to extract premium positioning through exclusive network integration while squeezing margin from commoditized consumables.
Pricing Analysis
Silicon photonics wafer-scale manufacturing passes through cost compression into optical sensor modules, collapsing per-unit detection subsystem expenses by half versus legacy LED-photodiode assemblies. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared hospital-at-home devices from CLIA-waived retail clinic units and unregulated direct-to-consumer wellness trackers. Pricing pressure stems from Chinese manufacturers scaling Bluetooth-enabled digital monitors for export markets. Home users seeking proactive health insights exhibit highest price sensitivity, while oncology therapeutic drug monitoring programs demonstrate lowest elasticity due to reimbursement code coverage.
Supply Chain Analysis
Dual-sourcing requirements for photonic integrated circuits mandate qualification across Tower Semiconductor and GlobalFoundries foundries, insulating device integrators from single-fab disruption. Supply concentrates in Taiwan for silicon wafer fabrication, the United States for precision-molded microfluidic polymer channels, and China for Bluetooth module assembly and lancet production. Raw material dependencies span silicon substrates, medical-grade polycarbonate cartridges, and lyophilized reagent chemistries. Single-source vulnerability concentrates in EU MDR-notified body capacity for CE marking validation. Distribution runs through Amazon and CVS MinuteClinic direct-to-consumer channels alongside traditional clinical laboratory referral networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon photonics integration and microfluidics-paper hybrid architectures are expanding margin capture opportunities by collapsing cost floors in optical detection while opening premium positioning in precision cell-counting subsystems.
For Market Incumbents: Cement technology leadership through captive silicon foundry partnerships that lock in wafer-scale photonics capacity before capacity constraints emerge. Defend against emerging Chinese manufacturers by accelerating FDA 510(k) clearance pipelines for over-the-counter finger-prick analyzers that establish brand preference before commoditization penetrates multi-parameter segments. Channel control through hospital-at-home network exclusivity represents the critical defensive lever. For New Entrants and Emerging Players: Launch via microfluidics-paper hybrid architectures targeting sub-dollar anemia screening in India's thalassemia surveillance programs and sub-Saharan Africa rural health stations, where procurement runs through government tenders rather than reimbursement code validation. White-space concentration sits in preventive testing for resource-limited settings, where laboratory-grade performance requirements relax and cold chain infrastructure gaps favor dry-reagent formats. Direct institutional procurement bypasses the consumer regulatory burden that blocks retail clinic penetration. For Investors and Strategic Acquirers: Diversified diagnostics conglomerates with CLIA-waived portfolios and silicon photonics R&D infrastructure represent the most active acquirer category in this space, seeking precision manufacturing capabilities in automated cell counting. Long-term viability hinges on reimbursement code expansion for remote patient monitoring applications beyond current chronic disease management boundaries. The signal to watch is CMS determination on CPT code coverage for home-based white blood cell differential monitoring, which would validate premium pricing for multi-parameter platforms and trigger consolidation among mid-stage microfluidics developers lacking hospital-at-home network integration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Streamlined Class II pathways compress time-to-market for finger-prick analyzers by 40-60 percent versus premarket approval routes. |
| Silicon Foundry Partnership | Wafer-scale photonics capacity agreements with Tower Semiconductor and GlobalFoundries lock in cost advantages for optical detection subsystems. |
| Hospital-at-Home Network Integration | Siemens Healthineers and integrated delivery networks embed hematology devices into acute-level home care protocols, expanding addressable volume. |
| Microfluidics-Paper Hybrid Development | Converging lab-on-a-chip precision with lateral flow simplicity enables sub-dollar test costs for anemia screening in resource-limited settings. |
| Remote Patient Monitoring Reimbursement Strategy | CMS CPT code coverage determinations dictate which at-home hematology applications achieve sustainable commercial scale in the United States. |
Research Methodology
Bottom-up chronic disease patient and home user modeling reconciled against top-down silicon foundry capacity and microfluidic cartridge production tracking forms the analytical core of this study. Primary interviews with hematology device R&D directors, FDA regulatory affairs consultants, hospital purchasing committee members, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, CMS reimbursement code databases, EU MDR notified body registries, and silicon photonics foundry capacity disclosures. Triangulation across these sources anchors volume and value estimates.
Input-output matrices linking microfluidic channel production volumes to finished device assembly rates, reagent cartridge consumption patterns, and end-user adoption curves across the projection horizon generate segment-level forecasts. Segmentation dimensions span product type, application, end user, and technology platform, with geographic regulatory clusters modeled separately. CAGRs derive from fitted growth curves against historical adoption analogs in point-of-care diagnostics, adjusted for reimbursement code expansion trajectories and silicon photonics cost reduction slopes.
Several conditions sit outside the modeled scope, including EU MDR notified body capacity constraints extending beyond current backlogs, sudden CLIA waiver requirement modifications, and tariff disruptions affecting Chinese-manufactured Bluetooth modules. Forecasts reflect assumptions on reimbursement code expansion timelines and silicon foundry yield improvements that could shift materially. Deviation in CMS remote patient monitoring coverage determinations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Graft Versus Host Disease (Gvhd) Treatment Market
Hematology
Global Immunohematology Market
Hematology
Global Disposable Hemoperfusion Market
Hematology
Chronic Immune Thrombocytopenia Treatment Market
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Marginal Zone Lymphoma Treatment Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Global Bleeding Disorders Market
Hematology
Rare Hematology Market
Hematology
Heparin-Induced Thrombocytopenia (HIT) Treatment Market
Hematology
Lymphoma Treatment Market
Hematology
Mantle Cell Lymphoma Treatment Market
Hematology
Hemoglobinopathy Treatment Drug Market
Hematology
Hemoglobin Analyzer Market
Hematology
Anemia Drugs Market
Hematology
Hematology Analyzers Market