
 Global Metabolic Testing Market | 2026-2036
Global Metabolic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metabolic Testing Market Foresight
A shortage of board-certified clinical laboratory geneticists is redrawing competitive boundaries across metabolic diagnostics. GE HealthCare leverages its installed base of imaging and informatics platforms to bundle metabolic profiling into integrated care workflows. COSMED srl anchors its position in cardiopulmonary exercise testing, a niche where breath-by-breath gas exchange analysis commands premium placement. MGC Diagnostics Corporation specializes in indirect calorimetry systems that feed directly into bariatric and sports medicine protocols.
Metabolic testing encompasses the quantitative measurement of biochemical intermediates, energy expenditure, and substrate utilization through blood, breath, or tissue sampling, typically requiring sensitivity thresholds in the nanomolar to micromolar range depending on analyte class. Its primary commercial purpose lies in stratifying patient risk, guiding therapeutic intervention, and monitoring metabolic disease progression across clinical and performance settings. Blood glucose and lipid profile testing occupy mature, high-volume positions where economies of scale compress margins, while mass spectrometry-based hormone panels and enzyme activity assays attract faster growth and richer pricing due to analytical complexity and lower automation penetration. Diagnostic centers dominate end-user demand by procedure count, though home care providers are gaining share as electrochemical sensor platforms miniaturize and remote patient monitoring reimbursement expands.
The FDA's 510(k) and CLIA complexity categorization shape device entry pathways and laboratory operational requirements for metabolic assay deployment in the United States, while the EMA's In Vitro Diagnostic Regulation and CE marking framework govern conformity and post-market surveillance obligations across European member states. Japan's PMDA enforces stringent analytical performance standards that filter out lower-specification instruments and sustain incumbent positions for validated platforms. Stakeholders must weigh capital allocation between automated high-throughput systems for centralized labs and decentralized point-of-care formats as payment models shift toward value-based metabolic risk management.
Market Dynamics
Reimbursement migration toward preventive metabolic screening is compressing test economics while expanding procedure volumes across hospital networks and outpatient chains.
Growth Catalysts
- FDA 510(k) clearance acceleration:Streamlined premarket pathways for novel biomarker assays shorten commercialization timelines from 18 months to under 12 months for predicate-eligible devices.
- Electrochemical sensor miniaturization:Nanomolar-sensitivity glucose and lactate platforms enable continuous monitoring formats that penetrate home care and ambulatory settings previously served by centralized labs.
- Japan's aging demographic density:Tokyo and Osaka prefectures concentrate demand for diabetes and lipid disorder screening where PMDA-validated platforms command premium placement.
Market Restraints
- Board-certified clinical laboratory geneticist shortage:Credential scarcity in the United States and Germany limits test interpretation capacity and constrains service expansion.
- Mass spectrometry reagent cost volatility:Noble metal catalysts and isotopically labeled internal standards expose hormone panel margins to supply chain shocks.
- EMA IVDR conformity burden:Post-market surveillance obligations and notified body bottlenecks delay CE-marked product launches by 8-14 months.
Strategic Opportunities
- India's diagnostic center consolidation:Fragmented pathology networks in Mumbai and Bangalore present acquisition targets for automated high-throughput metabolic profiling systems.
- Remote patient monitoring reimbursement expansion:CMS and German statutory health insurance frameworks now cover home-based continuous glucose monitoring for prediabetic populations.
- AI-augmented breath analysis convergence:Machine learning pattern recognition combined with portable mass spectrometry creates cardiopulmonary exercise testing formats for sports medicine clinics.
Industry Challenges
- CLIA complexity categorization navigation:US laboratories face operational recalibration when novel assays trigger high-complexity status and personnel requirements.
- Legacy LIS integration friction:Hospital information systems built on HL7 v2 standards resist seamless data exchange with cloud-native metabolic informatics platforms.
- ISO 15189 accreditation timelines:Medical laboratory quality management certification cycles extend 14-22 months, delaying competitive positioning in tender-driven markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metabolic Testing Market |
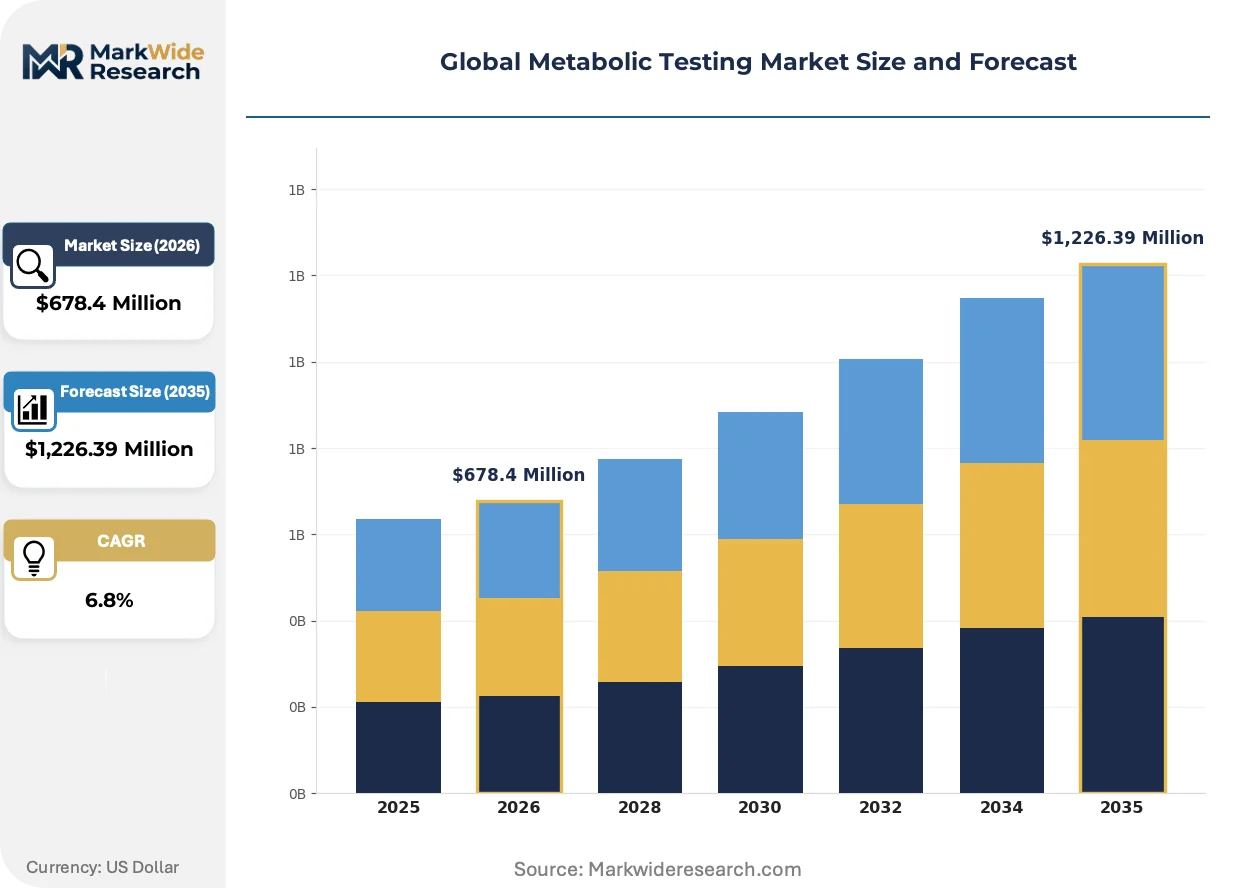
| Market Size in 2026 | $678.4 Million |
| Market Size in 2035 | $1,226.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Blood Glucose, Lipid Profile, Thyroid Function, Enzyme Activity, Hormone Levels Technology: Mass Spectrometry, Chromatography, Immunoassay, Electrochemical Sensors, Colorimetric Analysis Application: Diabetes Management, Cardiovascular Risk, Endocrine Disorder Diagnosis, Nutritional Assessment, Sports Physiology End User: Diagnostic Centers, Research Institutes, Home Care Providers, Fitness Clinics, Pharmaceutical Companies |
| Companies Covered | GE HealthCare, KORR Medical Technologies, COSMED srl, MGC Diagnostics Corporation, CORTEX Biophysik GmbH, Geratherm Medical AG, AEI Technologies, Parvo Medics, OSI Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metabolic Testing Market Shifts & Advancements
Portable breath analysis and wearable metabolite sensors are displacing stationary laboratory formats while regulatory frameworks recalibrate to accommodate decentralized testing.
Silicon photonics-based optical glucose sensors is miniaturizing continuous monitoring into patch formats that dermatology-tolerate 14-day wear. Outpatient diabetes clinics in Germany and Japan are adopting these platforms at triple-digit annual placement rates. The technology is compressing centralized laboratory glucose testing volumes while expanding total addressable procedure counts.
EMA's In Vitro Diagnostic Regulation (IVDR) performance evaluation requirements are forcing manufacturers to generate clinical evidence from European Union member state populations rather than extrapolating US FDA 510(k) data. This regulatory friction most impacts mass spectrometry-based steroid hormone assays where analytical sensitivity claims require prospective validation studies. Manufacturers are responding by establishing captive clinical trial sites in France and the Netherlands.
Bundled per-member-per-month metabolic risk contracts are displacing fee-for-service reimbursement in US accountable care organizations. Health systems in Texas and Florida are consolidating indirect calorimetry, lipid profiling, and continuous glucose monitoring into single-vendor agreements. This procurement compression favors platform suppliers with imaging and informatics integration capabilities.
Global Metabolic Testing Market Segmentation
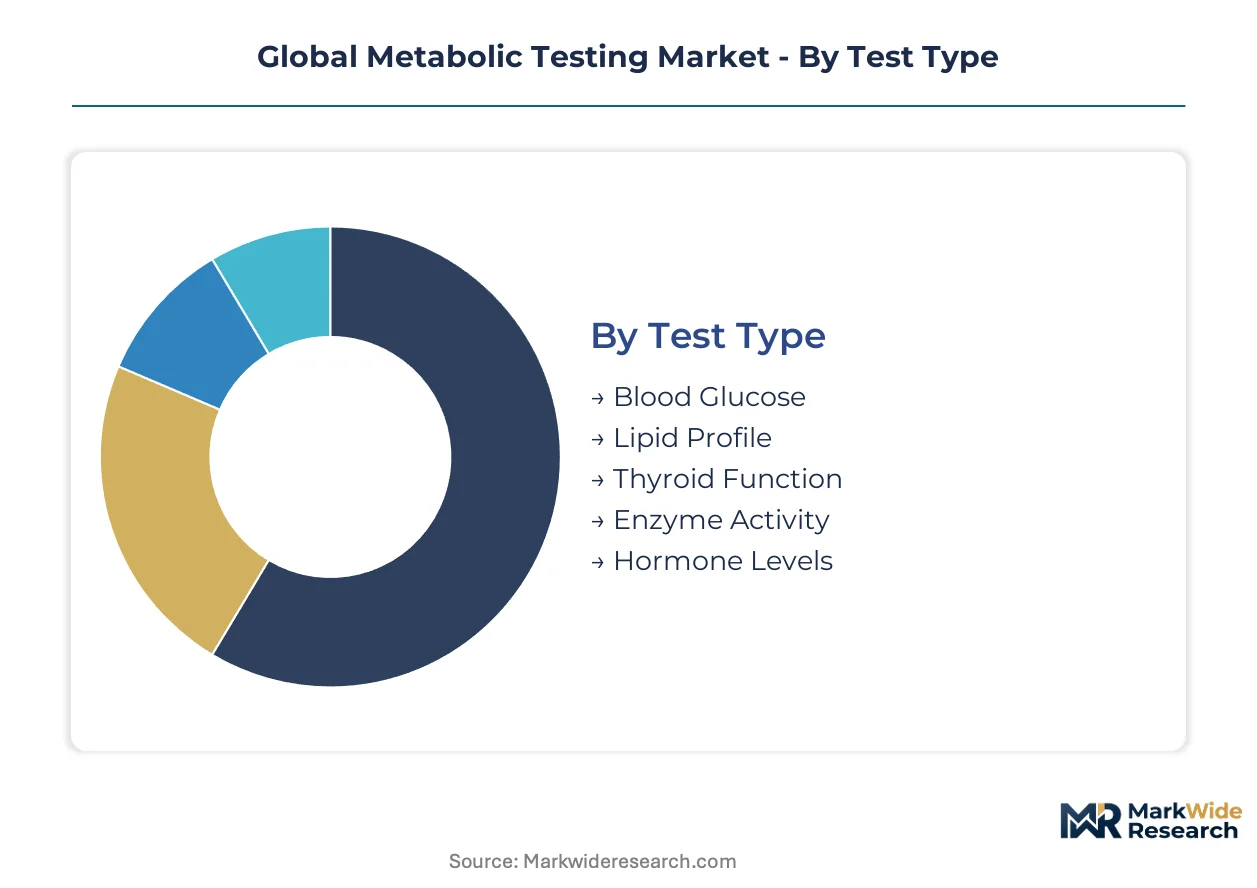
Metabolic testing segments fragment across four dimensions that determine procurement patterns, reimbursement pathways, and technology substitution risks. Channel economics and regulatory complexity vary sharply between centralized laboratory formats and emerging decentralized modalities.
Test Type:
Blood Glucose and Lipid Profile testing flow through high-volume hospital networks and outpatient chains where economies of scale compress margins, while specialized hormone and enzyme assays concentrate in reference laboratories commanding premium placement.
- Blood Glucose:Electrochemical strip-based and continuous monitoring platforms dominate procedure volumes. Demand concentrates in United States and Japan diabetes management networks where CMS and PMDA reimbursement frameworks cover preventive screening for prediabetic populations. Sensor miniaturization is displacing centralized laboratory glucose testing into home care formats.
- Lipid Profile:Enzymatic colorimetric and direct homogeneous assays measure cholesterol fractions and triglycerides. German statutory health insurance funds cardiovascular risk screening programs in Bavaria and North Rhine-Westphalia, though reagent cost volatility compresses margin structures for high-throughput processors.
- Thyroid Function:TSH, free T4, and antibody panels serve endocrine disorder diagnosis in tertiary care settings.
- Enzyme Activity:Lysosomal and mitochondrial enzyme assays support rare disease identification in specialized reference laboratories.
- Hormone Levels:Mass spectrometry-based steroid panels attract premium pricing due to analytical complexity and lower automation penetration.
Blood Glucose dominates installed base. Hormone Levels is where expansion concentrates.
Technology:
Cost tier stratification separates capital-intensive mass spectrometry and chromatography systems from disposable electrochemical formats, with mid-range immunoassay platforms serving the volume core of hospital laboratory networks.
- Mass Spectrometry:LC-MS/MS and GC-MS platforms deliver nanomolar sensitivity for hormone panels and metabolic profiling. EMA IVDR performance evaluation requirements force manufacturers to generate EU-specific clinical evidence rather than extrapolating FDA 510(k) data, delaying CE-marked launches by 8-14 months.
- Chromatography:HPLC and gas chromatography systems separate complex biological matrices for research and clinical applications. Academic medical centers in the United States and Germany anchor demand for high-resolution metabolite identification.
- Immunoassay:Chemiluminescent and ELISA formats automate high-throughput protein and hormone quantification in centralized laboratories.
- Electrochemical Sensors:Amperometric glucose and lactate platforms enable continuous monitoring with dermatology-tolerated patch formats.
- Colorimetric Analysis:Enzyme-coupled spectrophotometric assays serve mature lipid and liver function testing segments.
Immunoassay captures the highest procedure volume. Electrochemical Sensors is climbing the fastest.
Application:
Customer type determines pricing power, with sports physiology and nutritional assessment commanding out-of-pocket premiums while diabetes and cardiovascular applications depend on reimbursement density.
- Diabetes Management:Glycemic monitoring and complication risk stratification drive the largest procedure volumes across hospital networks and home care channels. Bundled per-member-per-month contracts in US accountable care organizations consolidate testing into single-vendor agreements.
- Cardiovascular Risk:Lipid profiling and inflammatory marker assessment support preventive cardiology programs. Japanese prefectural health authorities in Tokyo and Osaka concentrate screening demand where aging demographics sustain premium placement for validated platforms.
- Endocrine Disorder Diagnosis:Thyroid, adrenal, and pituitary dysfunction testing serves tertiary referral pathways.
- Nutritional Assessment:Indirect calorimetry and micronutrient analysis support bariatric and sports medicine protocols.
- Sports Physiology:Cardiopulmonary exercise testing and metabolic cart analysis command premium placement in performance clinics.
Diabetes Management anchors revenue scale. Sports Physiology is gaining share fastest.
End User:
Supply concentration favors platform suppliers with imaging and informatics integration capabilities as health systems consolidate indirect calorimetry, lipid profiling, and continuous monitoring into unified procurement frameworks.
- Diagnostic Centers:High-throughput centralized laboratories process the majority of blood glucose, lipid, and thyroid panels. India's fragmented pathology networks in Mumbai and Bangalore present acquisition targets for automated metabolic profiling systems.
- Home Care Providers:Remote patient monitoring reimbursement expansion under CMS and German statutory frameworks now covers continuous glucose monitoring for prediabetic populations, accelerating electrochemical sensor placement.
- Research Institutes:Mass spectrometry and chromatography platforms serve metabolomics and biomarker discovery programs.
- Fitness Clinics:Portable breath analysis and metabolic cart systems support sports physiology applications.
- Pharmaceutical Companies:Drug development and clinical trial biomarker strategies drive specialized hormone and enzyme assay demand.
Diagnostic Centers dominate installed base. Home Care Providers is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the regulatory benchmark that shapes commercialization timelines for metabolic testing platforms worldwide. Reimbursement density for preventive screening and aging demographic concentrations in Germany and Japan sustain premium placement for validated instruments.
United States
CMS coverage expansion for continuous glucose monitoring in prediabetic populations drives home care channel growth. The FDA's streamlined 510(k) pathways compress device approval timelines to under 12 months for predicate-eligible assays. Texas and Florida health systems consolidate indirect calorimetry and lipid profiling into single-vendor accountable care contracts.
Germany
Statutory health insurance funds cardiovascular risk screening programs across Bavaria and North Rhine-Westphalia. The EMA's IVDR conformity framework imposes 8-14 month delays on CE-marked product launches. Outpatient diabetes clinics in Berlin and Munich adopt silicon photonics-based glucose sensors at triple-digit annual placement rates.
Japan
PMDA-enforced analytical performance standards filter out lower-specification instruments and sustain incumbent platform positions. Tokyo and Osaka prefectures concentrate diabetes and lipid disorder screening demand where aging demographics exceed 28% population share. Bundled municipal health contracts favor validated metabolic cart systems in Kanto region cardiopulmonary clinics.
India
Diagnostic center consolidation in Mumbai and Bangalore creates acquisition targets for automated high-throughput metabolic profiling systems. The country's national pharmaceutical regulator enforces CDSCO medical device rules that classify most metabolic analyzers as Class B or C imports. Maharashtra and Karnataka state health missions expand lipid screening access through public-private pathology networks.
United Kingdom
NHS England's diabetes prevention programme funds HbA1c and lipid testing across integrated care systems in Greater London and the Midlands. MHRA post-Brexit recognition routes for EU-approved devices create parallel conformity pathways. Research institutes in Cambridge and Oxford anchor demand for mass spectrometry-based metabolomics platforms.
Global Metabolic Testing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that commands premium placement in narrow application niches. Imaging and informatics conglomerates bundle metabolic profiling into enterprise care workflows, while breath analysis and calorimetry specialists defend margin positions through analytical complexity. Three archetypes dominate: platform integrators with installed base leverage, cardiopulmonary testing specialists with gas exchange expertise, and electrochemical sensor miniaturization firms penetrating home care channels. Competitive moves concentrate on strategic partnerships for LIS integration and geographic expansion through diagnostic center acquisitions in fragmented Asian markets.
Within the integrated platform tier, GE HealthCare leverages imaging and informatics infrastructure to anchor bundled metabolic risk contracts. COSMED srl occupies a specialist position in cardiopulmonary exercise testing where breath-by-breath gas exchange analysis commands premium clinical placement. MGC Diagnostics Corporation exemplifies the indirect calorimetry archetype, with systems feeding directly into bariatric and sports medicine protocols where reimbursement density supports capital equipment acquisition cycles.
| Leading Market Players |
|---|
| GE HealthCare |
| KORR Medical Technologies |
| COSMED srl |
| MGC Diagnostics Corporation |
| CORTEX Biophysik GmbH |
| Geratherm Medical AG |
| AEI Technologies |
| Parvo Medics |
| OSI Systems |
| Others |
Supply & Pricing Matrix
FDA 510(k) clearance tiers and EMA IVDR conformity classes gate both supplier qualification and price stratification in metabolic testing, compressing margins for predicate-eligible devices while preserving premium placement for novel biomarker platforms with prospective validation requirements.
Pricing Analysis
United States-Germany price spreads of 15-25% reflect reimbursement density differentials and regulatory compliance cost allocation. Three-tier pricing structure across premium, standard, and economy levels segments by analytical complexity and automation penetration, with mass spectrometry-based hormone panels commanding the highest tier. Cost compression in electrochemical glucose sensors is intensifying because of silicon photonics displacement and home care channel expansion. Diagnostic centers exhibit highest price sensitivity due to bundled procurement contracts, while sports physiology clinics show lowest sensitivity for cardiopulmonary exercise testing systems.
Supply Chain Analysis
Germany and Japan anchor precision manufacturing of mass spectrometry platforms and metabolic cart systems, while the United States concentrates electrochemical sensor fabrication and cloud-native informatics development. Noble metal catalysts for reagent production and isotopically labeled internal standards draw from limited chemical synthesis capacity in Switzerland and the Netherlands. Single-source vulnerability in isotope supply chains exposes hormone panel margins to disruption. Distribution runs through hospital procurement committees and GPO contracts in consolidated health systems, with direct-to-clinic channels gaining share in sports medicine and home care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through health system consolidation in Texas, Florida, and Germany's statutory insurance networks, fragmenting vendor leverage across diagnostic center chains and accountable care organizations.
For Market Incumbents: Fortify platform integration capabilities to defend against cloud-native informatics entrants seeking to displace legacy LIS infrastructure. Deepen backward integration into electrochemical sensor manufacturing to capture margin compression from silicon photonics substitution. Invest in ISO 15189-accredited captive clinical trial sites across France and the Netherlands to accelerate EMA IVDR performance evaluation timelines. For New Entrants and Emerging Players: Differentiate on AI-augmented breath analysis convergence for sports medicine clinics where incumbent gas exchange expertise has not penetrated machine learning pattern recognition. Target India's fragmented diagnostic center networks in Mumbai and Bangalore with automated high-throughput metabolic profiling systems. Pursue white-label partnerships with established imaging and informatics conglomerates to bypass hospital procurement committee barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across electrochemical sensor miniaturization as semiconductor fabrication scales absorb metabolic monitoring functions. Five-to-ten-year viability favors platform suppliers with reimbursement strategy capabilities and bundled contract execution experience. Acquisition target archetype: mid-cap indirect calorimetry specialists with bariatric channel relationships and sports medicine placement. Signal to watch: CMS remote patient monitoring reimbursement expansion into prediabetic populations as volume inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Strategy | Streamlined pathways compress commercialization timelines for eligible biomarker assays below 12 months. |
| EMA IVDR Captive Trial Sites | EU-specific clinical evidence generation avoids 8-14 month notified body bottlenecks in CE marking. |
| Hospital System Partnership | Texas and Florida accountable care organizations consolidate metabolic testing into single-vendor agreements. |
| Software Companion Development | Cloud-native informatics platforms displace legacy HL7 v2 LIS infrastructure in hospital networks. |
| Reimbursement Strategy Execution | CMS and German statutory frameworks now cover home-based continuous glucose monitoring expansion. |
Research Methodology
Initial hypotheses were tested against primary input from hospital laboratory directors, clinical laboratory geneticists, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EMA IVDR performance evaluation summaries, CMS reimbursement bulletins, and hospital procurement databases. Bottom-up instrument placement modeling and top-down health system expenditure analysis were triangulated to reconcile volume and value estimates.
Variance-decomposition across test type, technology platform, application setting, and end-user channel dimensions structured the analytical framework throughout the forecast period. CAGRs were derived from procedure volume trajectories and price evolution assumptions segmented by reimbursement density and regulatory complexity. Indirect calorimetry system placement rates and continuous glucose monitoring sensor adoption curves served as industry-specific forecast anchors.
Material uncertainties — regulatory pathway delays, isotope supply disruptions, and reimbursement policy recalibration — sit outside the modeled envelope. Forecasts reflect assumptions about predicate device eligibility, notified body capacity, and preventive screening coverage expansion that industry stakeholders provided. Recalibration cycles align with material shifts in FDA guidance documents, EMA implementing acts, and CMS national coverage determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
North America Drug Screening Market
Testing Services
US & Europe Extractable and Leachable Testing Services Market
Testing Services
Pancreatic Elastase Testing Market
Testing Services
Skin Perfusion Pressure Testing Devices Market
Testing Services
Global Diagnostic Testing Market
Testing Services
Monkeypox Testing Market
Testing Services
Hospital Microbiology Testing Market
Testing Services
Addison Disease Testing Market
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
Tuberculosis Testing Market
Testing Services
Global Thyroid Function Test Market
Testing Services
North America Endotoxin and Pyrogen Testing Market
Testing Services
Passive Dosimetry Equipment and Service Market
Testing Services
US Bowie Dick Test Pack Market
Testing Services
US Viral Clearance Market