
 United States Hospital Acquired Disease Testing Market | 2026-2036
United States Hospital Acquired Disease Testing Market Size, Share, and Industry Trends Forecast 2026-2036
United States Hospital Acquired Disease Testing Market Intelligence
Clinical microbiologist staffing shortages across American hospital networks is reorganizing how institutions deploy automated diagnostic platforms. Abbott Laboratories leverages integrated molecular systems to sustain reference lab partnerships, while Thermo Fisher Scientific anchors its position through broad PCR and next-generation sequencing portfolios. Becton Dickinson and Company differentiates via closed-system automation that reduces manual specimen handling in understaffed facilities.
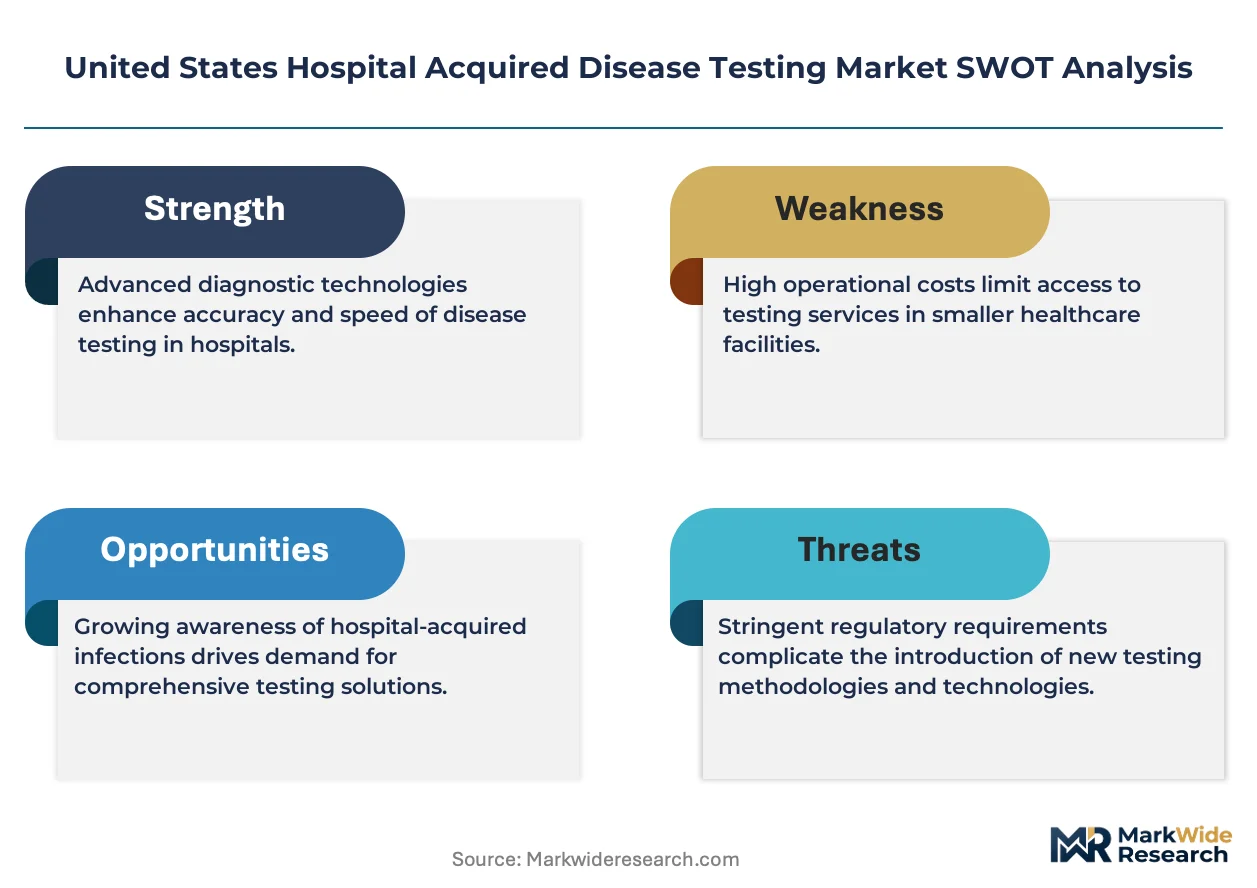
Hospital acquired disease testing encompasses laboratory and point-of-care diagnostic methods designed to detect pathogens transmitted during inpatient care, including antimicrobial resistance profiling with turnaround targets under two hours for bloodstream infection panels. PCR-based respiratory and bloodstream panels command the dominant revenue share due to established CPT coding and predictable reimbursement, while next-generation sequencing applications in outbreak surveillance represent the fastest-expanding margin pool despite capital intensity. Point-of-care testing segments in emergency departments show structural acceleration as hospitals decentralize testing to reduce bed-day costs and improve sepsis bundle compliance.
FDA premarket notification pathways for moderate-complexity devices and CMS Clinical Laboratory Improvement Amendments oversight shape product development priorities and capital deployment timelines for manufacturers. CDC National Healthcare Safety Network reporting requirements for multidrug-resistant organisms drive recurring demand surveillance testing contracts. Stakeholders must monitor evolving FDA guidance on artificial-intelligence-enabled infectious disease diagnostics and corresponding CLIA complexity determinations that will reshape competitive positioning in decentralized testing environments.
Market Dynamics
CMS reimbursement compression is forcing tertiary care centers across Texas, California, and New York to consolidate reference laboratory contracts while accelerating point-of-care testing decentralization in emergency departments.
Growth Catalysts
- CDC NHSN Reporting Mandates:Mandatory multidrug-resistant organism surveillance drives recurring demand for molecular testing contracts in large hospital networks.
- Sepsis Bundle Compliance:Two-hour turnaround requirements for bloodstream infection panels push emergency departments toward integrated PCR systems.
- Antimicrobial Stewardship Programs:Hospital infection control committees prioritize rapid resistance profiling to reduce broad-spectrum antibiotic utilization.
Market Restraints
- Capital Intensity of NGS Platforms:Next-generation sequencing infrastructure demands substantial upfront investment with extended depreciation cycles.
- Clinical Microbiologist Shortages:American hospital networks face persistent staffing gaps that constrain manual specimen processing capacity.
- CLIA Complexity Determinations:FDA premarket notification pathways for moderate-complexity devices create extended product development timelines.
Strategic Opportunities
- AI-Enabled Diagnostics:Artificial intelligence integration into infectious disease platforms awaits evolving FDA guidance on algorithm-based complexity classifications.
- Decentralized Emergency Department Testing:Point-of-care molecular systems reduce bed-day costs and improve sepsis protocol adherence.
- Outbreak Surveillance Applications:Next-generation sequencing for epidemiological tracing represents underpenetrated white space in infection control budgets.
Industry Challenges
- Automated System Integration:Closed-system automation requires reconfiguration of existing laboratory information management infrastructure.
- Workforce Retraining Requirements:Molecular platform deployment demands specialized technical competencies scarce in current hospital staffing pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Hospital Acquired Disease Testing Market |
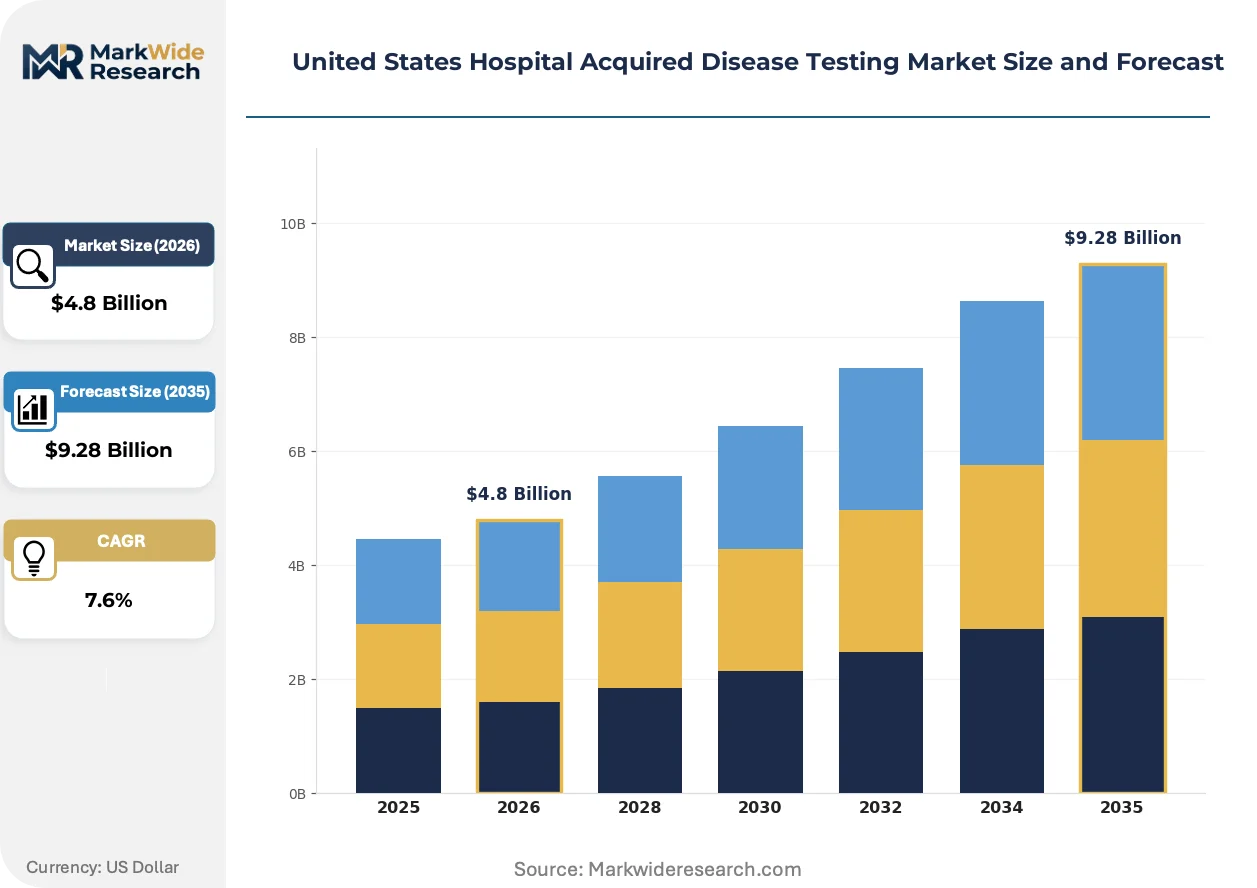
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infection Tests, Diagnostic Kits, Monitoring Devices, Screening Tools Technology: PCR, ELISA, Microarray, Next-Generation Sequencing Application: Clinical Laboratories, Research Facilities, Point-of-Care Testing, Emergency Rooms End User: Hospitals, Clinics, Diagnostic Centers, Healthcare Facilities |
| Companies Covered | Abbott Laboratories, Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd., Becton Dickinson and Company, bioMérieux SA, Danaher Corporation, Siemens Healthineers, Hologic, QIAGEN, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Hospital Acquired Disease Testing Market Strategic Shifts & Innovations
Multiplex PCR panels are compressing turnaround times while regulatory pathways for artificial intelligence diagnostics are creating new competitive entry points for platform manufacturers.
Next-generation sequencing is fragmenting outbreak surveillance capabilities across hospital networks. Whole-genome epidemiological tracing enables real-time transmission mapping. Infection control departments in tertiary centers are adopting these platforms despite capital constraints. The technology is fragmenting traditional reference laboratory relationships by bringing genomic surveillance in-house.
FDA emergency use authorization pathways for diagnostic platforms during public health emergencies have permanently altered product development timelines. Manufacturers now maintain parallel regulatory track strategies for EUA and traditional 510(k) submissions. Moderate-complexity device classifications under CLIA shape automation design priorities. This regulatory flexibility most affects respiratory and bloodstream panel developers targeting hospital emergency departments.
Service unbundling is separating instrument placement from reagent supply contracts in hospital procurement. Large health systems negotiate direct platform acquisitions while locking multi-year consumable commitments. Reference laboratories respond with outcome-based testing guarantees for high-volume accounts. This restructuring concentrates most visibly in California and Texas integrated delivery networks.
United States Hospital Acquired Disease Testing Market Segmentation
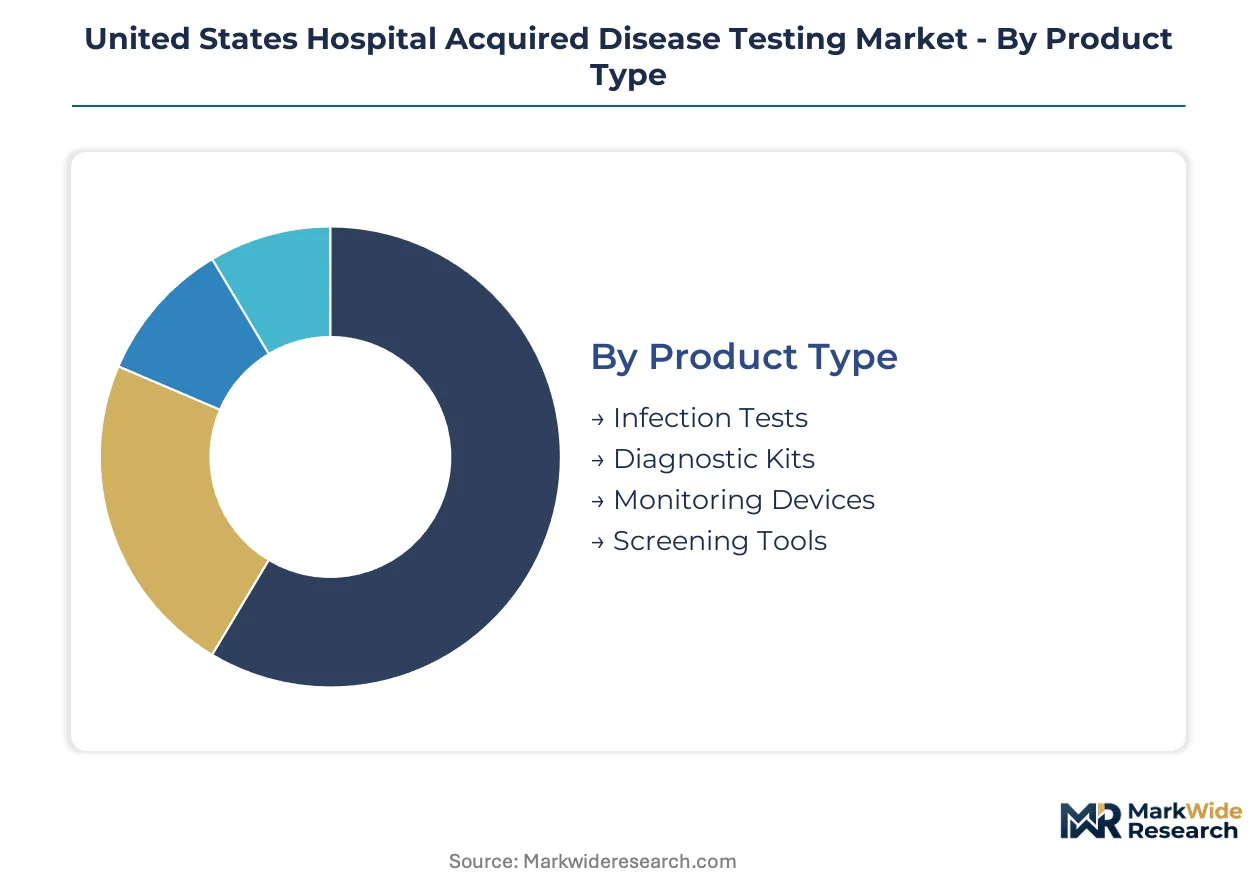
Hospital acquired disease testing segments reveal distinct procurement patterns across American healthcare networks. Product configurations and technology choices vary sharply between tertiary centers in Texas and California versus community hospitals in the Midwest and Southeast.
Product Type:
Infection tests and diagnostic kits dominate domestic hospital procurement, while monitoring devices show stronger concentration in integrated delivery networks with centralized supply chains.
- Infection Tests:Bloodstream and respiratory pathogen panels using multiplex PCR configurations. Demand concentrates in tertiary care centers across Texas, California, and New York where sepsis bundle compliance mandates rapid turnaround.
- Diagnostic Kits:Self-contained reagent systems for antimicrobial resistance profiling. Large hospital networks in Florida and Illinois are consolidating kit procurement through reference laboratory partnerships to reduce per-test costs.
- Monitoring Devices:Automated culture systems and continuous surveillance platforms. Community hospitals in Ohio and Pennsylvania deploy these to offset clinical microbiologist staffing gaps.
- Screening Tools:Rapid antigen and lateral flow devices for admission screening. These gain traction in emergency departments seeking to decentralize testing workflows.
Infection tests hold the largest share; momentum sits with diagnostic kits as health systems renegotiate reagent supply contracts.
Technology:
Cost tiers separate established platforms from emerging systems, with capital intensity determining adoption speed across hospital budget categories.
- PCR:Real-time and multiplex configurations for respiratory and bloodstream panels. Established CPT coding and predictable CMS reimbursement sustain dominance in clinical laboratories across the Northeast and Pacific states.
- ELISA:Enzyme-linked immunosorbent assays for antibody detection and serological surveillance. Reference laboratories in Texas and Arizona maintain capacity for high-throughput batch processing.
- Microarray:Hybridization-based pathogen identification with moderate complexity classification. Academic medical centers in Massachusetts and North Carolina deploy these for resistance gene profiling.
- Next-Generation Sequencing:Whole-genome epidemiological tracing for outbreak surveillance. Tertiary centers in California and New York are bringing these platforms in-house despite substantial upfront investment requirements.
PCR holds the largest share; next-generation sequencing is expanding most quickly as infection control budgets reallocate toward genomic surveillance capabilities.
Application:
Volume concentration varies by care setting, with emergency departments driving the steepest expansion trajectory for point-of-care configurations.
- Clinical Laboratories:Centralized molecular testing with batch processing efficiency. Large hospital networks in Illinois and Michigan consolidate reference contracts here to capture economies of scale.
- Research Facilities:Academic medical centers and public health laboratories conducting surveillance studies. CDC National Healthcare Safety Network reporting requirements sustain recurring contracts in Atlanta and state capitals.
- Point-of-Care Testing:Decentralized molecular systems in emergency departments and intensive care units. Texas and Florida hospitals deploy these to reduce bed-day costs and improve sepsis protocol adherence.
- Emergency Rooms:Rapid turnaround panels for admission screening and triage. Two-hour bloodstream infection requirements push procurement in California and New York metropolitan areas.
Clinical laboratories hold the largest share; point-of-care testing is gaining share fastest as hospitals decentralize to reduce length-of-stay metrics.
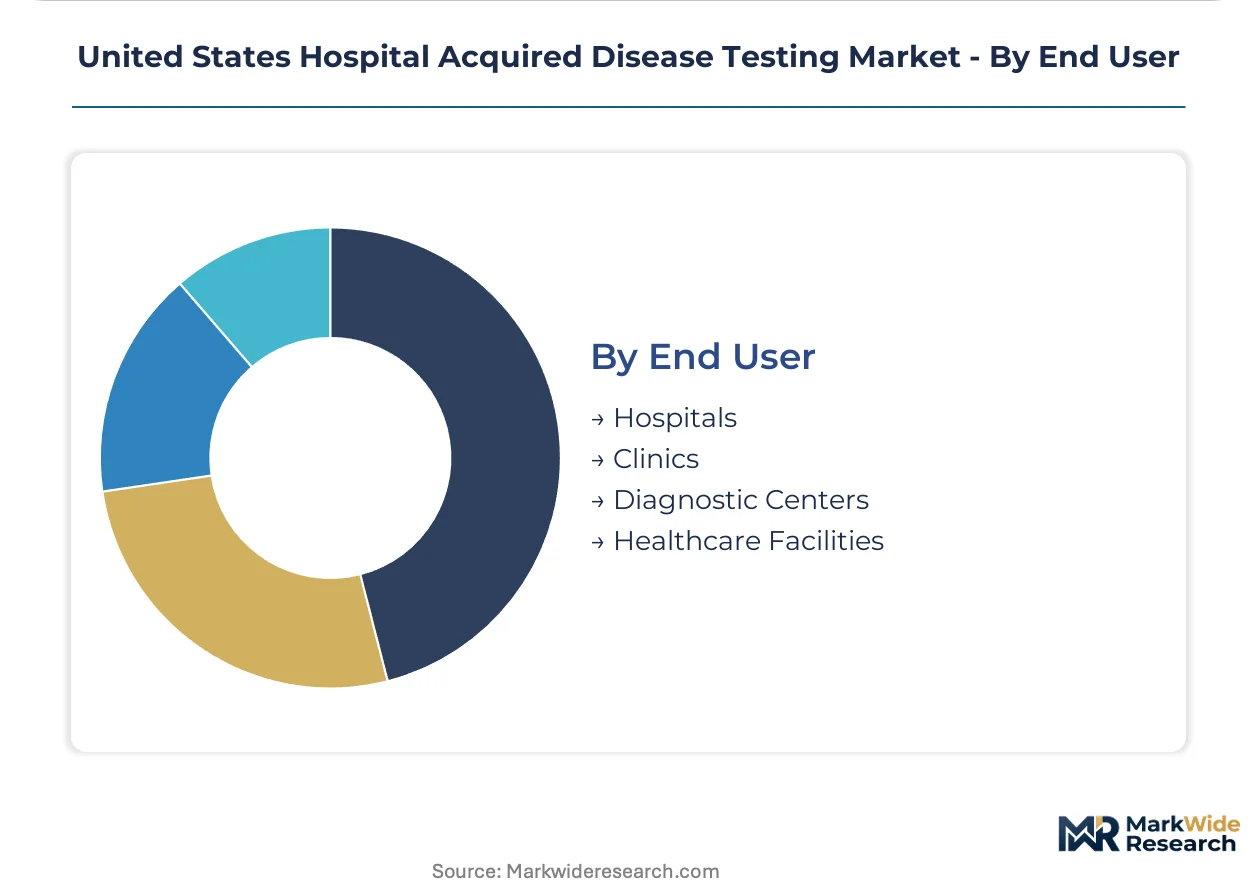
End User:
Customer type determines procurement sophistication, with hospitals commanding complex integrated systems versus clinics selecting modular configurations.
- Hospitals:Tertiary and community acute care facilities with comprehensive infection control programs. CMS reimbursement compression forces consolidation of reference laboratory contracts in California and Texas integrated delivery networks.
- Clinics:Outpatient and ambulatory surgery centers with limited on-site laboratory capacity. These facilities rely on send-out arrangements with regional reference laboratories.
- Diagnostic Centers:Independent laboratories processing specimens from multiple health systems. Large networks in Florida and Pennsylvania negotiate outcome-based testing guarantees for high-volume accounts.
- Healthcare Facilities:Long-term acute care hospitals and skilled nursing facilities with elevated infection risk profiles. These settings show rising demand for admission screening tools.
Hospitals hold the largest share; diagnostic centers are climbing the fastest as service unbundling separates instrument placement from reagent supply contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA emergency use authorization pathways and CMS reimbursement frameworks anchor procurement cycles across American hospital networks. Tertiary care centers in Texas, California, and New York concentrate molecular testing capacity. Regional variation reflects state-level Medicaid expansion status and integrated delivery network consolidation patterns.
Texas
Sepsis bundle compliance mandates and antimicrobial stewardship programs drive demand for rapid bloodstream infection panels in Houston and Dallas medical centers. Texas Medicaid managed care contracts influence point-of-care testing reimbursement rates for emergency departments. The Texas Medical Center in Houston anchors the nation's largest concentration of in-house next-generation sequencing platforms for outbreak surveillance.
California
Integrated delivery networks in Los Angeles and San Francisco consolidate reference laboratory contracts under CMS reimbursement compression. California Department of Public Health reporting requirements for multidrug-resistant organisms sustain surveillance testing demand. Stanford Medicine and UCSF Medical Center deploy closed-system automation to offset clinical microbiologist staffing gaps in the Bay Area.
New York
Two-hour turnaround requirements for bloodstream infection panels push New York City metropolitan hospitals toward decentralized emergency department testing. New York State Department of Health regulations mandate carbapenem-resistant Enterobacteriaceae screening in long-term acute care facilities. Mount Sinai Health System and NewYork-Presbyterian anchor molecular testing capacity in Manhattan and Brooklyn.
Florida
Large hospital networks in Miami and Tampa renegotiate reagent supply contracts through reference laboratory partnerships to reduce per-test costs. Florida Agency for Health Care Administration oversight shapes point-of-care testing deployment in emergency departments. Mayo Clinic Florida and Tampa General Hospital concentrate diagnostic kit procurement for antimicrobial resistance profiling.
Illinois
Clinical laboratories in Chicago and Rockford consolidate reference contracts to capture economies of scale in molecular batch processing. Illinois Department of Public Health CDC National Healthcare Safety Network reporting contracts sustain recurring surveillance demand. Northwestern Medicine and University of Chicago Medicine anchor academic medical center testing capacity for resistance gene profiling.
United States Hospital Acquired Disease Testing Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the United States Hospital Acquired Disease Testing Market. Abbott Laboratories and Thermo Fisher Scientific anchor the integrated tier through broad molecular portfolios and reference lab partnerships. Becton Dickinson and bioMérieux occupy the automation-specialist tier with closed-system designs. Danaher and Siemens Healthineers represent diversified conglomerates leveraging diagnostics scale. Competitive moves concentrate on strategic partnerships for AI-enabled platforms and geographic expansion through integrated delivery network contracts.
Among integrated molecular system providers, Abbott Laboratories and Thermo Fisher Scientific exemplify the platform-leader archetype through sustained reference laboratory relationships. Becton Dickinson occupies a differentiated position within the automation tier. These three companies represent the dominant competitive anchors shaping procurement patterns in understaffed American hospital facilities.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche Ltd. |
| Becton Dickinson and Company |
| bioMérieux SA |
| Danaher Corporation |
| Siemens Healthineers |
| Hologic |
| QIAGEN |
| Others |
Cost & Logistics Intelligence
Reagent kit consolidation replacing standalone instrument purchases simultaneously redraws procurement geography across Texas and California health systems and compresses per-test economics for reference laboratory partnerships. This substitution dynamic concentrates purchasing power within integrated delivery networks while fragmenting vendor pricing leverage.
Pricing Analysis
Price spreads between Northeast and Southwest tertiary centers reflect divergent CMS reimbursement rates and state Medicaid managed care contracting intensity. Three-tier pricing structure across premium, standard, and economy levels separates closed-system automation from modular PCR configurations and basic lateral flow devices. Pricing pressure stems from service unbundling that separates instrument placement from multi-year consumable commitments. Community hospitals in the Midwest exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers in Massachusetts and California prioritize turnaround performance over unit cost.
Supply Chain Analysis
Extended lead times for semiconductor components in automated diagnostic platforms have stretched instrument delivery schedules to twelve-to-eighteen month windows. Manufacturing concentration centers on the United States, Germany, and Japan for precision optics and fluidic systems, while reagent production draws from Ireland and Singapore for polymerase enzymes and fluorescent probes. Single-source vulnerability persists for specialized thermal cyclers sourced from discrete East Asian foundries. Distribution runs through regional GPO contracts and direct hospital system agreements rather than traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Hospital Acquired Disease Testing Market tracks a cyclical recovery anchored to CMS reimbursement rate resets that historically trigger capital equipment refresh cycles every five-to-seven years.
For Market Incumbents: Fortify reference laboratory partnerships through outcome-based testing guarantees that lock multi-year reagent supply commitments ahead of competitive platform placements. Deepen automation integration to offset clinical microbiologist staffing gaps that constrain competitor manual processing capacity. Prioritize FDA premarket notification pathway investments for moderate-complexity device classifications that accelerate emergency department procurement cycles. For New Entrants and Emerging Players: Differentiate on AI-enabled diagnostic algorithms awaiting FDA guidance on complexity determinations, a white-space segment where established players hold limited patent positions. Target outbreak surveillance applications in tertiary centers bringing next-generation sequencing in-house, the most penetrable subsegment for capital-light software solutions. Pursue hospital infection control committee direct engagement rather than traditional laboratory sales channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed diagnostic platform manufacturers seeking exit liquidity ahead of reimbursement cycle peaks. Long-term viability hinges on recurring revenue streams from consumable reagent contracts rather than instrument placement economics. Watch FDA emergency use authorization pathway utilization rates as inflection indicators for platform manufacturer order backlog acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Expedited premarket notification pathways compress product development timelines for bloodstream infection panels targeting CMS reimbursement windows. |
| Hospital System Partnership | Direct integrated delivery network contracts in Texas and California consolidate reference laboratory relationships and lock multi-year consumable commitments. |
| Software Companion Development | Artificial intelligence integration into infectious disease platforms awaits FDA guidance on algorithm-based CLIA complexity classifications. |
| Reimbursement Strategy | CPT coding optimization for multiplex PCR panels secures predictable CMS payment rates that sustain clinical laboratory capital deployment. |
| CE Marking Pathway | Parallel EU regulatory track builds manufacturing scale and validates quality systems for domestic FDA submission reinforcement. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, CMS Medicare payment rate schedules, and CDC National Healthcare Safety Network surveillance reports. Interviews with hospital infection control officers, clinical laboratory directors, GPO contracts managers, and biomedical engineers inform procurement pattern assessments. Secondary validation draws from hospital procurement databases, SEC diagnostics segment filings, and state health department reporting requirements. Bottom-up testing volume estimates triangulate against top-down molecular platform installed base calculations.
Segmentation dimensions modeled span product type, technology platform, application setting, and end-user category across the analysis window. Geographic clustering captures state-level Medicaid expansion status and integrated delivery network consolidation patterns. CAGR derivation rests on instrument placement cycle analysis, reagent consumption per installed unit, and reimbursement rate trajectory assumptions. Forecast inputs incorporate clinical microbiologist staffing gap projections and FDA guidance timeline expectations for AI-enabled diagnostics.
The analysis sits within stated boundaries; outcomes outside stable CMS reimbursement frameworks or accelerated FDA regulatory timelines would require recalibration. Forecasts reflect documented assumptions regarding sepsis bundle compliance mandate persistence and antimicrobial stewardship program expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
India GMP Testing Service Market
Testing Services
Bleeding Disorders Testing Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
Fungal Testing Kits Market
Testing Services
Vaginal Panel Testing Market
Testing Services
Anti-Asthma TDM Assay Kits Market
Testing Services
Friability Tester Market
Testing Services
Apolipoprotein Testing Market
Testing Services
Warfarin Sensitivity Test Market
Testing Services
Global Medical Device Testing and Certification Market
Testing Services
Nipah Virus (Niv) Infection Testing Market
Testing Services
Cholesterol Testing Services Market
Testing Services
Global Creatinine Assay Kits Market
Testing Services
Global Direct-To-Consumer (DTC)Testing Market
Testing Services
Endocrine Peptides Test Market
Testing Services
Mask Bacterial Filtration Efficiency Tester Market