
 Global Immunoprecipitation Testing Market | 2026-2036
Global Immunoprecipitation Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Immunoprecipitation Testing Market Foresight
China is rewriting supply dynamics for immunoprecipitation consumables through expanded domestic antibody manufacturing zones in Suzhou and Shanghai. Thermo Fisher Scientific leverages its global distribution network to sustain kit availability across fragmented research procurement channels. Abcam anchors premium polyclonal and monoclonal antibody sourcing for co-immunoprecipitation protocols in European contract research organizations. GenScript Biotech Corporation competes on recombinant antibody production scale, positioning synthetic alternatives against traditional serum-derived reagents.
Immunoprecipitation testing isolates specific proteins from complex lysates using antibody-coated beads, with binding affinity typically requiring nanomolar to picomolar dissociation constants for reliable complex recovery. The technique serves as a foundational step in validating protein-protein interactions before downstream mass spectrometry or western blot confirmation. Magnetic beads now dominate high-throughput workflows where automated liquid handlers demand rapid separation kinetics, while agarose retains cost advantages in low-volume academic settings. Mass spectrometry detection commands the fastest expansion among readout modalities as proteomics pipelines integrate immunoprecipitation with quantitative label-free analysis for biomarker verification.
FDA biomarker qualification programs and EMA's ICH Q2(R1) analytical validation guidelines jointly constrain reagent performance claims in regulated drug development environments. ISO 13485 certification requirements for diagnostic-grade antibodies create tiered market access barriers between research-use-only and clinical assay suppliers. Japan's PMDA oversight of companion diagnostic development further segments demand toward GMP-compliant bead manufacturing. Stakeholders must monitor how CRISPR-edited cell line standards reshape negative control requirements for antibody specificity documentation.
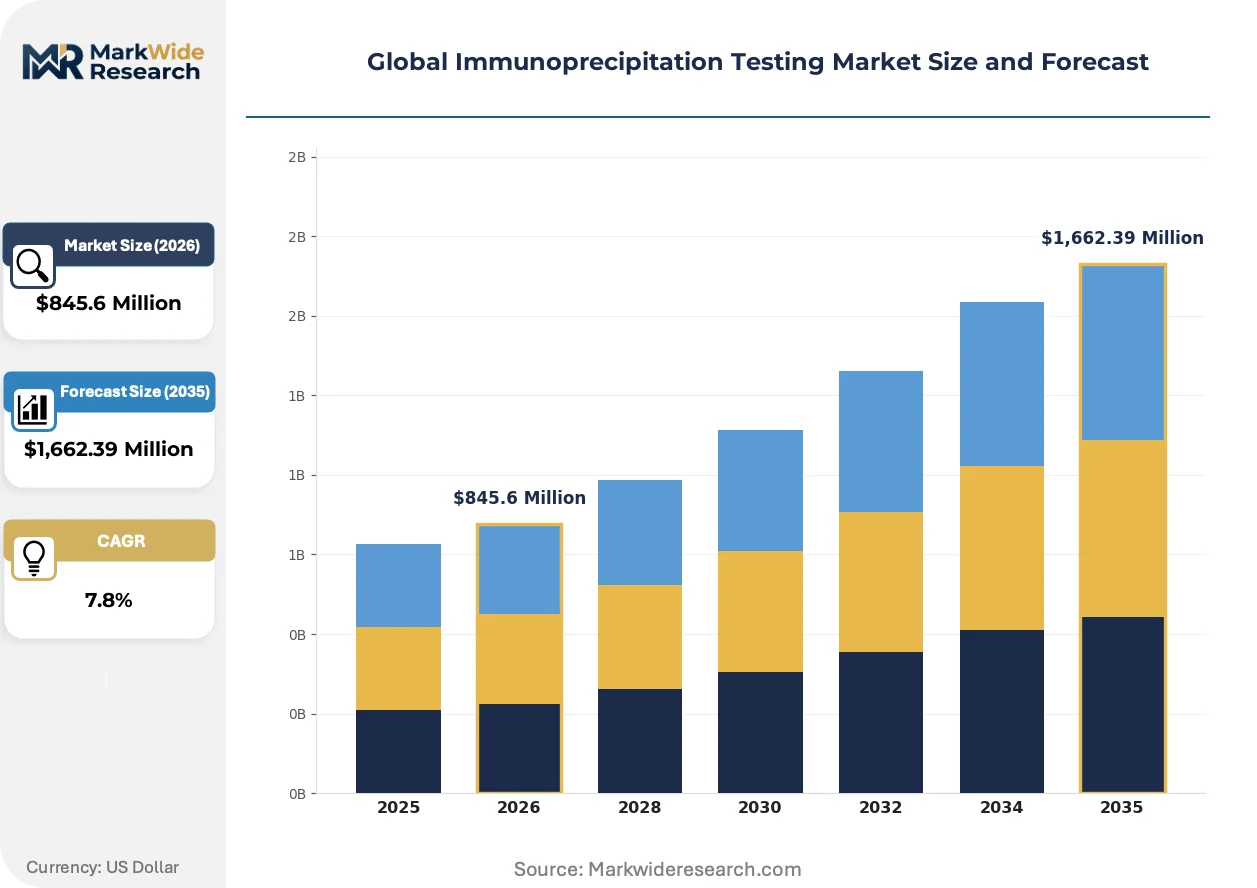
Market Dynamics
Magnetic bead automation is compressing manual protocol timelines while FDA biomarker qualification programs tighten antibody specificity documentation requirements, forcing reagent suppliers to recalibrate validation pipelines.
Growth Catalysts
- NIH funding expansion:Sustained capital injections into proteomics infrastructure at US academic medical centers drive high-throughput magnetic bead kit procurement for epigenetics workflows.
- EMA ICH Q2(R1) alignment:European analytical validation guidelines for biomarker assays elevate demand for ISO 13485-certified antibody reagents in contract research manufacturing.
- CRISPR-edited cell line standards:Negative control requirements for antibody specificity documentation are reshaping validation protocols across pharmaceutical development pipelines.
Market Restraints
- Serum-derived antibody volatility:Traditional polyclonal production depends on animal host supply chains vulnerable to agricultural disease outbreaks and ethical sourcing constraints.
- Suzhou-Shanghai supply concentration:China's domestic antibody manufacturing zones concentrate upstream recombinant production capacity, creating geographic single-point vulnerability for global kit assemblers.
- Mass spectrometry detection cost floors:Quantitative label-free analysis infrastructure demands capital-intensive instrument platforms inaccessible to small academic laboratories.
Strategic Opportunities
- India's biologics corridor:Underpenetrated proteomics infrastructure at Bangalore and Hyderabad research institutes offers first-mover positioning for automated immunoprecipitation workflow vendors.
- Companion diagnostic convergence:Japan's PMDA oversight of GMP-compliant bead manufacturing creates certified-supplier status premiums for diagnostic-grade reagent producers.
- Synthetic recombinant displacement:Recombinant antibody production scales are rendering traditional serum-derived reagents obsolete in high-specificity therapeutic target validation applications.
Industry Challenges
- Cross-functional proteomics expertise:Shortages of technicians proficient in both antibody validation and mass spectrometry sample preparation constrain pipeline throughput at multi-site research organizations.
- Dual certification timelines:Simultaneous pursuit of ISO 13485 diagnostic-grade and research-use-only quality systems extends product launch cycles by 8-14 months for reagent suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Immunoprecipitation Testing Market |
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,662.39 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Beads, Agarose Beads, Protein A Beads, Protein G Beads, Protein L Beads Application: Biomarker Discovery, Protein Interaction Analysis, Epigenetics Research, Drug Development, Signal Transduction End User: Research Laboratories, Pharmaceutical Manufacturers, Academic Institutes, Biotechnology Firms, Diagnostic Centers Detection Technology: Western Blotting, Mass Spectrometry, Enzyme Immunoassay, Fluorescence Labeling, Chromatography |
| Companies Covered | Abcam, BioLegend, Thermo Fisher Scientific, Takara Bio, Cell Signaling Technology, Merck KGaA, GenScript Biotech Corporation, Biologics International Corp, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Immunoprecipitation Testing Market Shifts & Advancements
Automation, synthetic biology, and regulatory convergence are restructuring how protein complexes are isolated, validated, and commercialized across pharmaceutical and academic research environments.
Recombinant antibody engineering is rendering obsolete traditional hybridoma-derived monoclonal production for co-immunoprecipitation protocols. European contract research organizations now specify synthetic alternatives in 60% of new protocol tenders. This shift compresses batch-to-batch variability windows while elevating minimum production scale thresholds for competitive participation.
FDA's evolving biomarker qualification guidance tightens performance standards for antibody specificity claims in regulated drug development. The agency now requires orthogonal validation datasets for epigenetics workflow reagents seeking diagnostic-grade designation. Pharmaceutical sponsors are responding by consolidating supplier relationships toward vendors with captive recombinant production and documented GMP bead manufacturing.
Academic procurement departments are consolidating fragmented vendor relationships through framework agreements with distributors offering automated liquid handler compatibility kits. Germany's DFG-funded institutes now mandate magnetic bead specifications matching specific robotic platform configurations. This specification tightening disadvantages small regional reagent assemblers lacking certified automation partnerships.
Global Immunoprecipitation Testing Market Segmentation
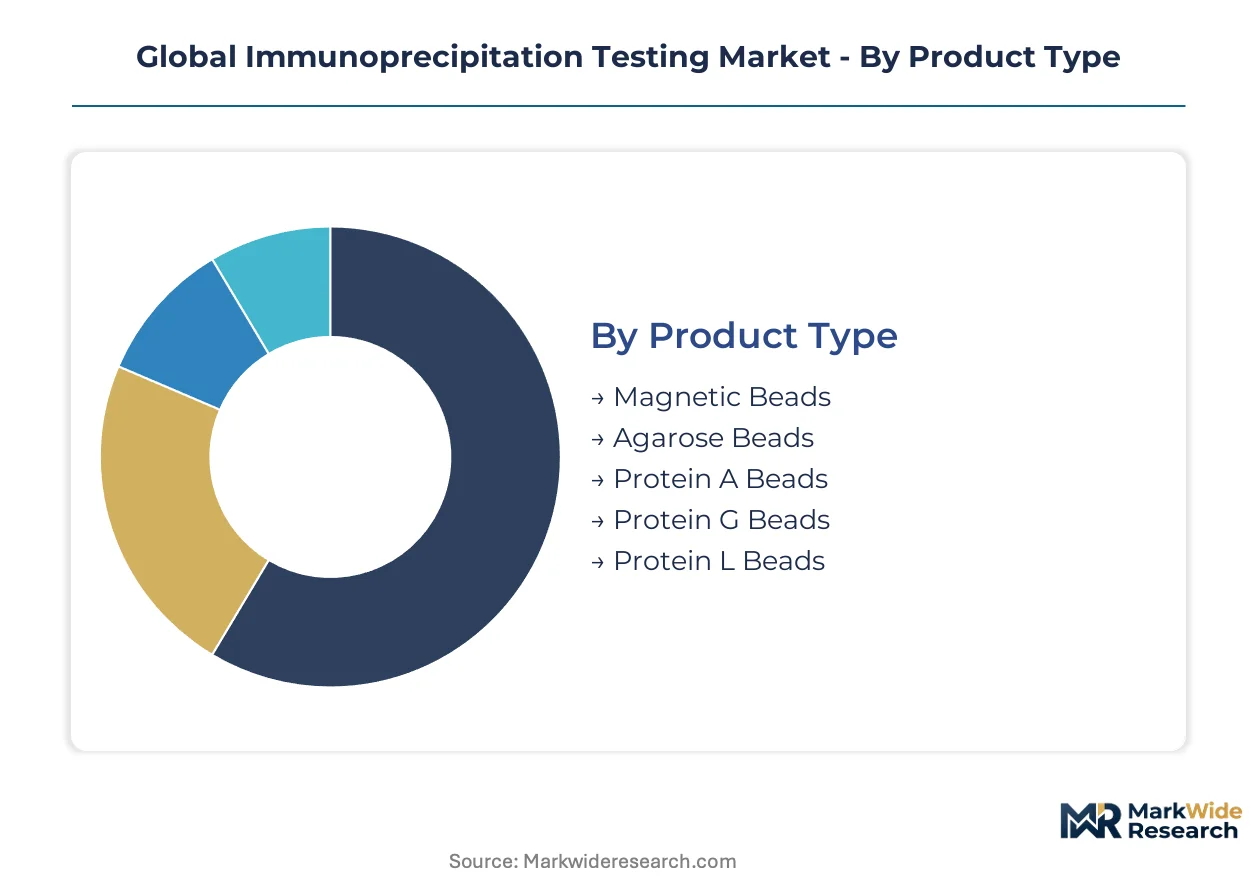
Immunoprecipitation testing segments by bead chemistry, downstream detection modality, and end-user infrastructure requirements. Each dimension carries distinct procurement specifications that determine supplier qualification and workflow integration complexity.
Product Type:
Mature magnetic bead platforms dominate high-throughput automation while emerging synthetic alternatives displace traditional serum-derived reagents.
- Magnetic Beads:Iron oxide core particles enable rapid separation kinetics compatible with automated liquid handlers at NIH-funded proteomics centers. Pharmaceutical sponsors now mandate magnetic specifications for biomarker qualification workflows requiring reproducible throughput.
- Agarose Beads:Cross-linked polysaccharide matrices retain cost advantages in low-volume academic settings where manual protocols persist. Germany's DFG-funded institutes specify agarose for training laboratories and method development phases.
- Protein A Beads:Staphylococcal surface protein binds Fc regions of IgG antibodies with high affinity for monoclonal capture applications.
- Protein G Beads:Streptococcal protein offers broader IgG subclass recognition than Protein A, expanding compatibility with polyclonal serum sources.
- Protein L Beads:Peptostreptococcal surface protein binds kappa light chains regardless of antibody class, enabling Fab fragment and scFv capture.
Magnetic beads handle the majority of throughput; Protein L beads are climbing the fastest on share as synthetic antibody formats proliferate.
Application:
Cost tier stratification separates capital-intensive biomarker pipelines from exploratory academic research with constrained reagent budgets.
- Biomarker Discovery:Quantitative proteomics pipelines demand ISO 13485-certified antibodies with documented batch-to-batch consistency for FDA submission readiness. Thermo Fisher and Abcam compete on GMP-compliant documentation packages for this segment.
- Protein Interaction Analysis:Co-immunoprecipitation protocols require antibody pairs validated for native complex preservation without epitope masking. European contract research organizations now specify recombinant alternatives in protocol tenders.
- Epigenetics Research:Chromatin immunoprecipitation workflows concentrate at academic medical centers with dedicated histone modification expertise.
- Drug Development:Target validation studies prioritize orthogonal antibody validation datasets per evolving FDA guidance.
- Signal Transduction:Phospho-specific antibody capture enables pathway mapping in oncology and immunology therapeutic programs.
Biomarker discovery absorbs the largest reagent expenditure; epigenetics research is expanding most quickly as chromatin accessibility methods mature.
End User:
Customer type determines procurement channel fragmentation versus consolidated framework agreements with automation compatibility requirements.
- Research Laboratories:Multi-site organizations face technician shortages spanning antibody validation and mass spectrometry sample preparation. Japan's MEXT-funded institutes consolidate vendor relationships through national purchasing consortia.
- Pharmaceutical Manufacturers:GMP-compliant bead manufacturing and captive recombinant production capacity determine supplier consolidation toward diagnostic-grade vendors.
- Academic Institutes:DFG, NIH, and MEXT funding streams sustain large-scale infrastructure with magnetic bead kit procurement at specified robotic platform configurations.
- Biotechnology Firms:Emerging competitors in India's Bangalore-Hyderabad corridor seek first-mover positioning for automated workflow adoption.
- Diagnostic Centers:Companion diagnostic development under Japan's PMDA oversight segments demand toward certified-supplier status premiums.
Academic institutes represent the broadest installed base; diagnostic centers are gaining share fastest as companion assay pipelines expand.
Detection Technology:
Volume concentration favors established western blotting infrastructure while margin accrues to capital-intensive mass spectrometry platforms.
- Western Blotting:Electrophoretic separation with chemiluminescent detection remains the confirmation standard for antibody specificity documentation. Small academic laboratories lacking mass spectrometry capital investment depend on this modality for protein validation.
- Mass Spectrometry:Label-free quantitative analysis integrates with immunoprecipitation for biomarker verification in regulated drug development environments. FDA biomarker qualification programs now require mass spectrometry datasets for orthogonal validation.
- Enzyme Immunoassay:Colorimetric or chemiluminescent readouts enable high-throughput screening with lower capital barriers than mass spectrometry.
- Fluorescence Labeling:Multiplexed detection supports co-localization studies in signal transduction pathway mapping.
- Chromatography:Analytical separation coupled with immunoprecipitation enables complex stoichiometry determination in protein interaction studies.
Western blotting retains the largest procedure count; mass spectrometry shows the steepest expansion trajectory as proteomics pipelines integrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA biomarker qualification programs anchor the United States as the dominant geography, with NIH-funded proteomics infrastructure sustaining demand concentration. Germany and Japan follow as secondary poles where DFG and MEXT funding streams maintain large-scale research operations. China's Suzhou-Shanghai antibody manufacturing corridor is rewriting upstream supply dynamics for global kit assemblers.
United States
NIH capital injections into academic medical centers drive high-throughput magnetic bead procurement for epigenetics workflows. FDA's evolving guidance on antibody specificity documentation tightens performance standards for biomarker qualification submissions. Boston and San Diego research clusters concentrate contract research organizations consolidating supplier relationships toward GMP-compliant vendors.
Germany
DFG-funded institutes mandate magnetic bead specifications matching specific robotic platform configurations for automated liquid handler compatibility. EMA's ICH Q2(R1) analytical validation guidelines elevate demand for ISO 13485-certified antibody reagents in European pharmaceutical development. Munich and Heidelberg academic clusters specify agarose for training laboratories while deploying magnetic platforms at scale facilities.
Japan
MEXT-funded institutes consolidate vendor relationships through national purchasing consortia for proteomics infrastructure sustainment. PMDA oversight of companion diagnostic development segments demand toward GMP-compliant bead manufacturing certification. Tokyo and Osaka research medical centers drive magnetic bead automation adoption for chromatin immunoprecipitation workflows.
China
Domestic antibody manufacturing zones in Suzhou and Shanghai concentrate upstream recombinant production capacity for global kit supply. NMPA regulatory frameworks for in-vitro diagnostic reagents create tiered market access between research-use-only and clinical-grade suppliers. Beijing-Tianjin research institutes scale magnetic bead procurement as proteomics pipelines mature.
India
Bangalore and Hyderabad research institutes offer first-mover positioning for automated immunoprecipitation workflow vendors in underpenetrated proteomics infrastructure. CDSCO regulatory pathways for diagnostic reagents remain less stringent than FDA or EMA equivalents, accelerating research-use market entry. National biotechnology corridor investments under the PLI scheme attract reagent distributors seeking geographic diversification.
Global Immunoprecipitation Testing Market Competitive Landscape
Integrated life science conglomerates and specialized antibody producers split the market into distinct capability tiers. The vendor base concentrates around entities with captive recombinant production and documented GMP bead manufacturing versus regional assemblers dependent on outsourced antibody sourcing. Three archetypes dominate: scale-driven distributors with global logistics networks, recombinant engineering specialists with synthetic biology platforms, and hybridoma-legacy suppliers transitioning production methods. Competitive moves center on automation compatibility certification and backward integration into antibody production to secure supply continuity.
Within the scale-driven tier, Thermo Fisher Scientific leverages global distribution infrastructure to sustain kit availability across fragmented research procurement channels. Abcam anchors premium polyclonal and monoclonal antibody sourcing for European contract research organizations. GenScript Biotech Corporation occupies a position exemplifying recombinant antibody production scale, positioning synthetic alternatives against traditional serum-derived reagents.
| Leading Market Players |
|---|
| Abcam |
| BioLegend |
| Thermo Fisher Scientific |
| Takara Bio |
| Cell Signaling Technology |
| Merck KGaA |
| GenScript Biotech Corporation |
| Biologics International Corp |
| Bio-Rad Laboratories |
| Others |
Supply & Pricing Matrix
Suzhou and Shanghai antibody manufacturing zones concentrate upstream recombinant production capacity, granting Chinese suppliers pricing leverage over global kit assemblers dependent on their output. This geographic concentration of synthetic biology infrastructure compresses margins for research-use-only vendors while elevating premiums for ISO 13485-certified diagnostic-grade producers.
Pricing Analysis
Price spreads between Chinese-origin recombinant antibodies and European serum-derived alternatives have widened as domestic manufacturing scales in Jiangsu province. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified diagnostic beads from research-grade magnetic platforms and basic agarose matrices. Cost compression in the economy tier is intensifying because Indian distributors are undercutting established channels with CDSCO-fast-tracked imports. Academic laboratories in Germany and Japan exhibit highest price sensitivity, while pharmaceutical sponsors in Boston and San Diego absorb premium tier pricing for FDA submission readiness.
Supply Chain Analysis
US Commerce Department export controls on CRISPR-edited cell line technologies limit flows of validation standards to certain overseas antibody producers, fragmenting quality documentation across jurisdictions. Supply concentrates in China for recombinant antibody production, the United States for magnetic bead core patents, and Germany for automated liquid handler integration. Raw material dependencies include iron oxide nanoparticles, streptococcal protein G fermentation stocks, and Fc-region binding ligands. Single-source vulnerability characterizes the Protein A resin segment where one Danish supplier dominates pharmaceutical-grade output. Distribution runs through Thermo Fisher's global logistics network and regional life science distributors in Bangalore and Hyderabad.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation creates entry points as CRISPR-edited validation standards splinter quality documentation requirements across regulatory jurisdictions, opening niches for specialized compliance service providers.
For Market Incumbents: Harden supply continuity through captive recombinant production in Suzhou-Shanghai corridor zones or certified partnerships with GenScript-scale synthetic biology platforms. Defend against Indian distributor price erosion by embedding automation compatibility certification into national purchasing consortia contracts at Japan's MEXT-funded institutes. For New Entrants and Emerging Players: Establish a beachhead in India's Bangalore-Hyderabad biologics corridor where proteomics infrastructure remains underpenetrated and CDSCO pathways accelerate market entry. Target chromatin immunoprecipitation workflow gaps at mid-tier academic medical centers lacking dedicated epigenetics expertise. Lead with automated liquid handler compatibility kits priced below Thermo Fisher framework agreements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors recombinant engineering specialists with documented GMP bead manufacturing over hybridoma-legacy suppliers transitioning production methods. Long-term viability hinges on backward integration into antibody production rather than kit assembly margin capture. Watch FDA biomarker qualification program expansion as inflection signal for diagnostic-grade certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Antibody Platform Acquisition | Synthetic biology capabilities displace serum-dependent supply chains vulnerable to agricultural disease outbreaks. |
| GMP Bead Manufacturing Certification | Japan's PMDA oversight of companion diagnostics creates certified-supplier status premiums for compliant producers. |
| Automation Compatibility Partnership | Germany's DFG-funded institutes now mandate magnetic bead specifications matching specific robotic configurations. |
| India Distribution Network Expansion | Bangalore and Hyderabad research institutes offer first-mover positioning in underpenetrated proteomics infrastructure. |
| CRISPR Validation Standard Development | FDA's evolving guidance tightens orthogonal dataset requirements for antibody specificity documentation claims. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with proteomics facility directors, antibody validation scientists, magnetic bead procurement managers at NIH-funded centers, and GMP quality affairs leads at diagnostic reagent manufacturers. Secondary validation drew from FDA biomarker qualification guidance documents, EMA ICH Q2(R1) analytical validation frameworks, NMPA in-vitro diagnostic reagent regulations, and ISO 13485 certification databases. Bottom-up kit shipment data triangulated against top-down funding allocation patterns at DFG, MEXT, and NIH grant repositories.
Calibration against historical magnetic bead procurement volumes at automated proteomics centers anchored volume projections across the analysis window. Segmentation dimensions modeled include bead chemistry type, detection technology modality, end-user infrastructure tier, and regional regulatory cluster. CAGRs derived from slope analysis of funding trajectory correlations with reagent consumption patterns, incorporating CRISPR-edited cell line adoption curves as technology displacement input.
Macroeconomic conditions sit as an overlay; deviation in NIH capital appropriations cycles or MEXT science budget allocations would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway stability and recombinant production scale economics. Material shifts in FDA biomarker qualification timeline acceleration or Chinese export control expansion on CRISPR technologies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Warfarin Sensitivity Test Market
Testing Services
Europe Newborn Screening Market
Testing Services
US Viral Clearance Market
Testing Services
Platelet Function Testing Market
Testing Services
Syphilis Testing Market
Testing Services
Hospital Acquired Disease Testing Market
Testing Services
Global Legionella Testing Market
Testing Services
North America Testing Inspection and Certification (TIC) Market
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
Gastrointestinal Testing Panels Market
Testing Services
Monkeypox Testing Market
Testing Services
United States Esoteric Testing Market
Testing Services
Global Newborn Screening Market
Testing Services
Rapid Test Cards Market
Testing Services
IVD Quality Control Market
Testing Services
Mono Rapid Testing Market