
 Diagnostic Shipper Market | 2026-2036
Diagnostic Shipper Market Size, Share, and Industry Trends Forecast 2026-2036
Diagnostic Shipper Market Outlook
Expanded polystyrene is decoupling from premium diagnostic shipper designs as phase-change materials and vacuum-insulated panels reshape product economics. Pelican BioThermal leverages advanced thermal engineering to sustain leadership in active temperature-controlled systems for high-value specimen transport. Sonoco Products anchors its position through integrated manufacturing of molded foam and corrugated hybrid shippers. Inmark competes with specialized blood-sample bag configurations that meet clinical laboratory workflow requirements.
A diagnostic shipper is a temperature-validated container engineered to maintain specified thermal ranges—typically 2°C to 8°C or frozen conditions—using insulated walls, refrigerant bricks, and sensor-ready cavities to protect specimen integrity during transit from collection site to testing facility. Refrigerated shippers occupy the highest margin tier due to validation documentation and regulatory compliance burdens, while passive temperature control dominates unit volume across routine specimen transport. Cloud-based tracking is expanding fastest among technology segments as laboratories seek real-time chain-of-custody verification for genetic testing and vaccine shipping applications.
FDA 21 CFR Part 11 and Good Distribution Practice standards shape validation protocols, while the EPA governs refrigerant chemistries and disposal pathways for cold-chain consumables. The EU AI Act and MDR frameworks in Europe are beginning to influence connected shipper architectures that incorporate diagnostic data streams. Stakeholders must monitor how evolving temperature-excursion documentation requirements affect shipper selection criteria and total cost of ownership models across laboratory and hospital procurement functions.
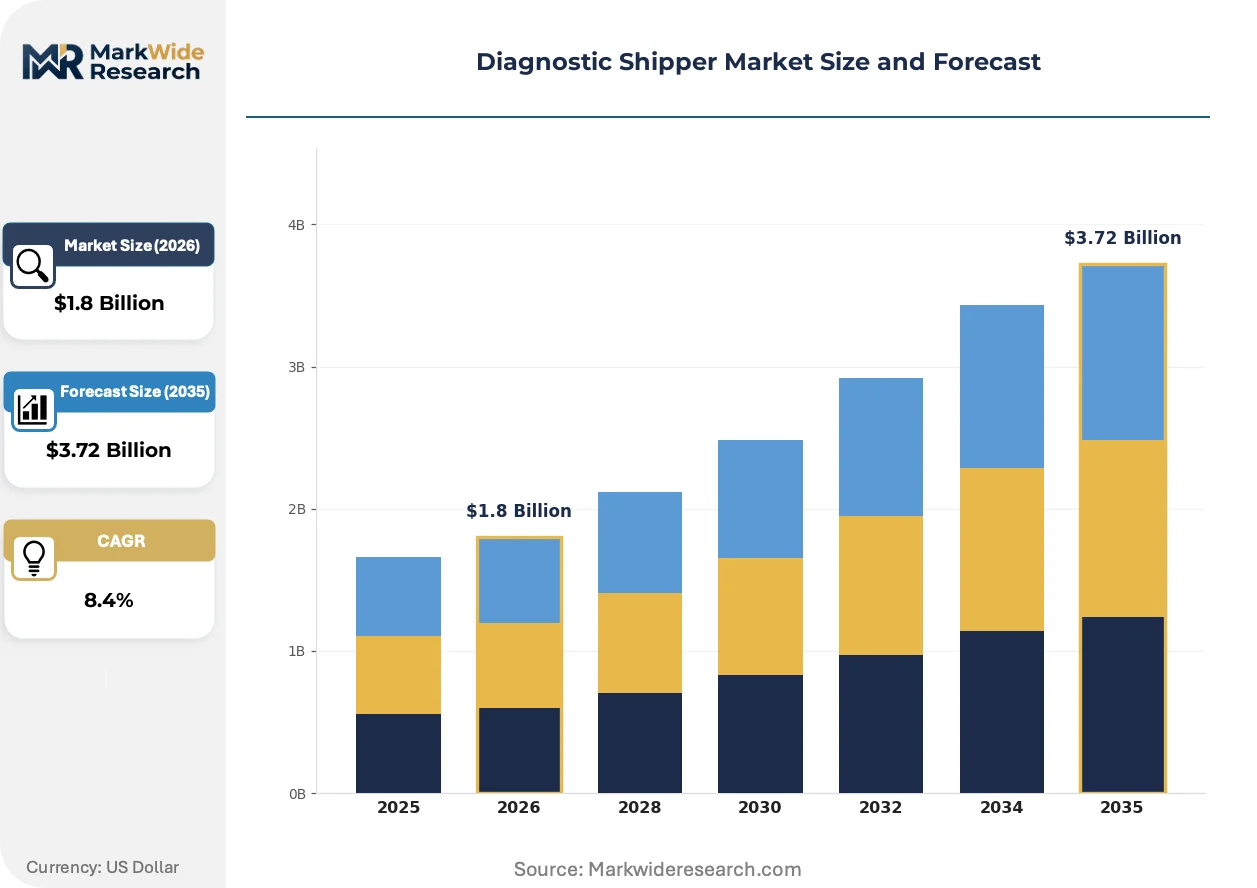
Market Dynamics
Phase-change materials and vacuum-insulated panels are compressing the cost-performance frontier for temperature-validated specimen transport, forcing legacy expanded polystyrene designs into commodity positioning while premium refrigerant systems capture margin expansion.
Growth Catalysts
- EU MDR framework:The Medical Device Regulation mandates enhanced traceability for in-vitro diagnostic specimen integrity, compelling laboratories across Germany, France, and Italy to upgrade to validated cold-chain shippers with documented thermal performance.
- Precision medicine logistics:Biobanks and reference laboratories in the United States are scaling collection networks for genetic testing samples, creating sustained demand for 2°C to 8°C validated containers with sensor integration.
- Vaccine distribution protocols:WHO cold-chain guidelines for temperature-sensitive biologics are tightening last-mile requirements, accelerating adoption of active temperature-controlled systems in emerging market immunization programs.
Market Restraints
- Refrigerant chemistry constraints:EPA regulations on hydrofluorocarbon disposal and phase-out timelines are increasing compliance costs for gel pack and phase-change material formulations used in passive shipper systems.
- Input material concentration:Vacuum-insulated panel manufacturing depends on specialized silica core suppliers concentrated in East Asian industrial clusters, exposing shipper producers to supply disruption and freight cost volatility.
- Validation documentation burden:FDA 21 CFR Part 11 electronic record requirements extend shipper qualification timelines, compressing effective product lifecycles and raising total cost of ownership for clinical laboratory procurement functions.
Strategic Opportunities
- Cloud-based tracking convergence:Integration of IoT temperature loggers with chain-of-custody software creates new revenue streams in genetic testing and cell therapy logistics where real-time excursion alerts command premium positioning.
- India biobank infrastructure:CDSCO regulatory alignment with ICH guidelines is accelerating cold-chain investment for clinical trial specimen export, opening demand for validated shippers meeting dual US-India compliance standards.
- Reusable shipper models:Reverse logistics programs for high-value active temperature-controlled systems reduce per-shipment costs for hospital networks while capturing recurring service revenue from calibration and refurbishment.
Industry Challenges
- Thermal engineering talent scarcity:The intersection of materials science, regulatory compliance, and pharmaceutical logistics requires specialized expertise that outpaces current vocational and university training pipelines.
- Multi-jurisdiction certification complexity:Simultaneous FDA, EMA, and PMDA validation for a single shipper design extends development cycles and fragments R&D resource allocation across incompatible documentation standards.
- Legacy laboratory integration:Hospital information systems and laboratory information management systems often lack API connectivity for automated temperature data ingestion, requiring costly middleware development for sensor-enabled shippers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diagnostic Shipper Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transport Containers, Blood Sample Bags, Test Tube Holders, Refrigerated Shippers End User: Laboratories, Hospitals, Research Facilities, Diagnostic Companies Technology: Passive Temperature Control, Active Temperature Control, Cloud-Based Tracking, RFID Solutions Application: Specimen Transport, Vaccine Shipping, Biological Samples, Genetic Testing |
| Companies Covered | InfeKta Packaging International, Polar Tech Industries, Com-Pac International, Inmark, Sonoco Products, Pelican BioThermal, Medline Industries, MarketLab, Sonoco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diagnostic Shipper Market Strategic Shifts
Diagnostic shipper technology is bifurcating between premium active systems with real-time telemetry and cost-optimized passive designs, with material science advances compressing the performance gap between the two categories.
Vacuum-insulated panels incorporating aerogel cores are absorbing thermal protection duties previously assigned to expanded polystyrene in mid-tier shipper designs. Reference laboratories in the United States are adopting these panels for 48-hour specimen stability requirements. The technology is absorbing volume from conventional foam shippers while enabling thinner wall profiles that reduce dimensional weight charges.
FDA updated guidance on specimen integrity during transit is tightening validation requirements for temperature-controlled packaging used in clinical diagnostic applications. The industrial consequence is expanded demand for third-party thermal qualification studies and documented performance mapping across seasonal ambient profiles. High-complexity reference laboratories are responding by specifying shipper systems with pre-qualified lane data covering summer and winter extremes.
Consolidated procurement by multi-site health systems is displacing fragmented purchasing across individual hospital laboratories. Group purchasing organizations are centralizing shipper selection for standardized cold-chain performance, compressing supplier diversity in favor of validated national contracts. This concentration is most visible in United States metropolitan health systems managing centralized reference laboratory networks with standardized specimen collection workflows.
Diagnostic Shipper Market Segmentation
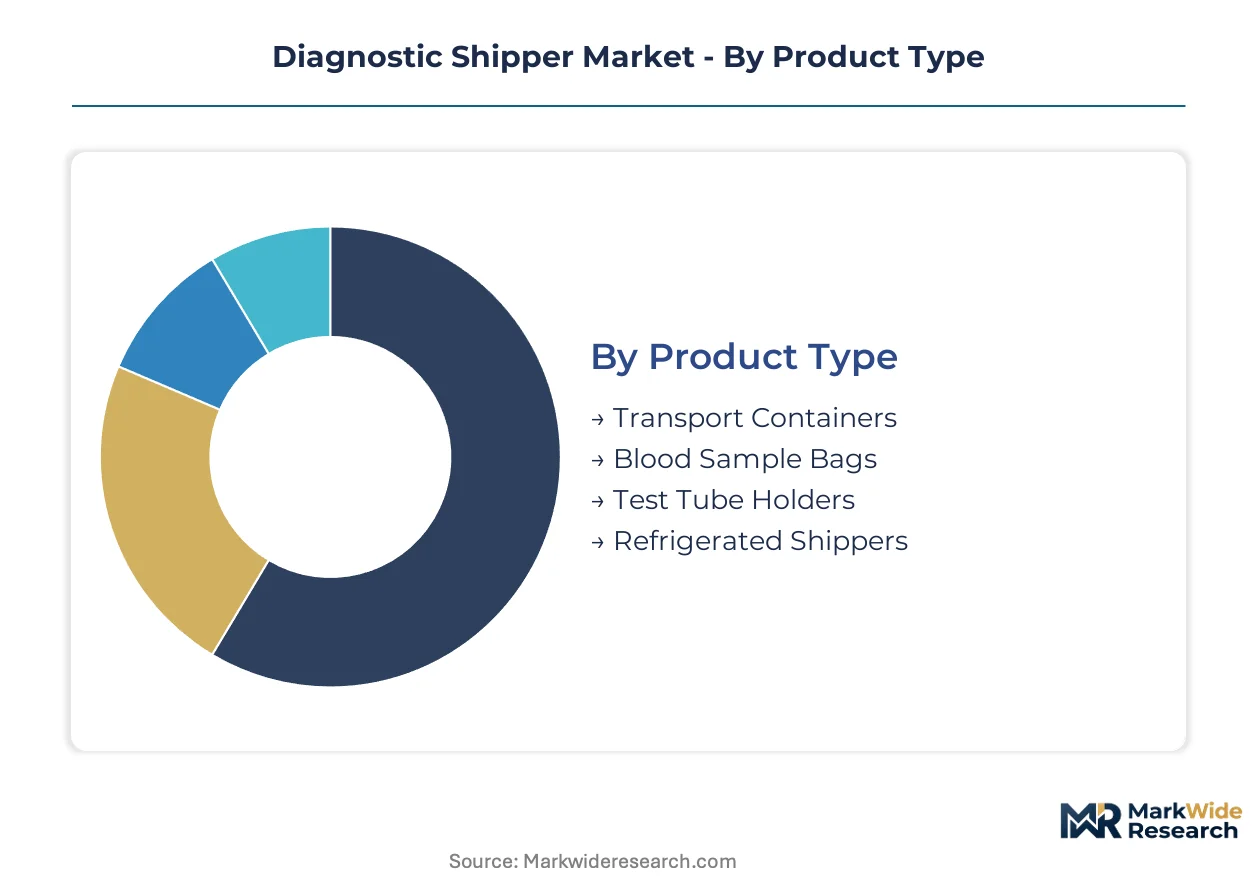
Segmentation in diagnostic shippers maps directly to regulatory burden tiers, with each category carrying distinct validation requirements under FDA 21 CFR Part 11 and EU MDR frameworks. Procurement functions use these divisions to match thermal performance specifications against specimen value and compliance risk.
Product Type:
FDA thermal qualification protocols and EU GDP standards impose divergent documentation loads across container formats, with refrigerated shippers demanding the most extensive validation studies.
- Refrigerated Shippers:Engineered with compressor-based or thermoelectric cooling systems maintaining 2°C to 8°C across ambient extremes. Reference laboratories in the United States specify these for high-complexity genetic testing workflows where excursion tolerance approaches zero.
- Transport Containers:Passive insulation systems utilizing phase-change materials or vacuum-insulated panels for 24-72 hour stability windows. Hospital networks deploying centralized laboratory models drive standardization around validated lane data for seasonal temperature profiles.
- Blood Sample Bags:Flexible pouch configurations with integrated gel packs for short-haul clinical specimen collection. These address phlebotomy workflow integration requirements across multi-site health systems.
- Test Tube Holders:Rigid molded designs securing primary collection vessels during transit. Research facilities utilize these for batch shipment standardization in multi-center clinical trials.
Transport Containers sit at the top of the volume ranking, with Refrigerated Shippers climbing the fastest.
End User:
Customer type determines contract structure, with laboratories negotiating multi-year validation agreements while hospitals favor spot purchasing for episodic demand.
- Laboratories:Reference and clinical laboratories constitute the core demand base for validated cold-chain systems. These facilities in the United States specify pre-qualified shippers with documented thermal performance across summer and winter ambient profiles.
- Diagnostic Companies:Commercial in-vitro diagnostic manufacturers internalize shipper procurement for direct-to-laboratory distribution of temperature-sensitive reagents and control materials. CDSCO alignment with ICH guidelines in India is accelerating their investment in dual US-India compliant systems.
- Hospitals:Acute care facilities manage decentralized specimen collection requiring point-of-care compatibility. Group purchasing organization consolidation is displacing fragmented purchasing across individual hospital laboratories.
- Research Facilities:Academic and contract research organizations prioritize specimen integrity for longitudinal biobank studies. These facilities specify extended-duration thermal protection for irreplaceable biological materials.
Laboratories command the largest procurement volumes, with Diagnostic Companies expanding most quickly into emerging market regulatory regimes.
Technology:
Technology selection tracks specimen value gradient, with cloud-connected systems commanding premiums for irreplaceable genetic materials while passive systems dominate high-volume routine testing.
- Cloud-Based Tracking:IoT temperature loggers integrated with chain-of-custody software enabling real-time excursion alerts. Genetic testing and cell therapy logistics in the United States command premium positioning for this capability.
- Passive Temperature Control:Insulated containers with refrigerant bricks or phase-change materials requiring no external power. This technology captures dominant unit volume across routine specimen transport from collection sites to processing facilities.
- Active Temperature Control:Powered refrigeration systems with precise setpoint management for high-value biologics. WHO cold-chain guidelines for temperature-sensitive vaccines are tightening last-mile requirements for these systems in emerging market immunization programs.
- RFID Solutions:Automated identification and tracking without real-time environmental monitoring. These address workflow efficiency requirements in high-throughput clinical laboratories with existing middleware infrastructure.
Passive Temperature Control maintains volume leadership, with Cloud-Based Tracking gaining share fastest as real-time chain-of-custody verification becomes standard for precision medicine logistics.
Application:
Application segmentation aligns with regulatory pathway complexity, with vaccine shipping subject to WHO prequalification and genetic testing falling under CLIA laboratory certification requirements.
- Specimen Transport:Routine clinical diagnostic samples including blood, urine, and tissue specimens. Reference laboratories in the United States are scaling collection networks, creating sustained demand for 2°C to 8°C validated containers with sensor integration.
- Genetic Testing:DNA and RNA samples requiring frozen or refrigerated stability for molecular diagnostic workflows. Biobank infrastructure expansion is concentrating demand in specialized shipper configurations with documented nucleic acid preservation performance.
- Vaccine Shipping:Temperature-sensitive biologics distribution under strict cold-chain protocols. WHO guidelines are accelerating adoption of active temperature-controlled systems in emerging market immunization programs.
- Biological Samples:Research-grade specimens including cell lines, tissues, and primary cultures. These applications prioritize extended thermal stability for international shipment scenarios.
Specimen Transport leads by shipment volume, with Genetic Testing showing the steepest expansion trajectory as precision medicine collection networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentration of reference laboratories and biobanks generates the dominant demand cluster for validated cold-chain specimen transport, with procurement centralization through group purchasing organizations reshaping supplier relationships across metropolitan health systems.
United States
Reference laboratories in Indianapolis and Research Triangle Park scale genetic testing collection networks, creating sustained procurement of 2°C to 8°C validated containers. FDA 21 CFR Part 11 electronic record requirements extend shipper qualification timelines for clinical laboratory procurement. The Boston-Cambridge biotech corridor concentrates demand for extended-duration thermal protection in cell therapy logistics.
Germany
Clinical laboratories across Munich and Hamburg upgrade cold-chain infrastructure under EU MDR traceability mandates for in-vitro diagnostic specimen integrity. The Medical Device Regulation compels documented thermal performance validation across summer and winter ambient profiles. The Rhine-Ruhr industrial cluster hosts specialized vacuum-insulated panel fabricators serving mid-tier shipper designs.
India
CDSCO regulatory alignment with ICH guidelines accelerates cold-chain investment for clinical trial specimen export from Bangalore and Hyderabad biotech parks. The national pharmaceutical regulator mandates dual US-India compliance standards for validated shipper systems. Contract research organizations in Mumbai and Pune drive demand for reusable active temperature-controlled configurations.
Japan
PMDA validation requirements for temperature-controlled packaging fragment development cycles for manufacturers serving Tokyo-Osaka laboratory networks. The national pharmaceutical regulator maintains incompatible documentation standards with FDA and EMA protocols. The Kanto region concentrates biobank infrastructure investment requiring real-time chain-of-custody verification for precision medicine samples.
United Kingdom
NHS consolidation of pathology services into regional hubs standardizes shipper selection for centralized reference laboratory networks in London and Manchester. The Medicines and Healthcare products Regulatory Agency enforces GDP standards for specimen integrity during transit. The Cambridge life science cluster generates specialized demand for nucleic acid preservation performance documentation.
Diagnostic Shipper Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers expand from passive insulation into active temperature-controlled systems and cloud-based tracking services. The vendor base segments across three tiers: multinational packaging conglomerates with integrated manufacturing, specialized thermal engineering firms, and regional fabricators of molded foam components. Two strategic archetypes predominate: materials science specialists leveraging phase-change material advances, and logistics-technology hybrids integrating IoT telemetry with physical containers. Competitive intensity concentrates on M&A activity targeting thermal engineering talent and strategic partnerships with laboratory information management system providers.
Among diversified packaging conglomerates, Sonoco Products and Sonoco exemplify integrated manufacturing archetypes spanning molded foam and corrugated hybrid configurations. Pelican BioThermal occupies a position within the premium active-systems tier, while Inmark sits within specialized clinical workflow integration. These three anchors demonstrate how competitive positioning separates material-science-driven cost optimization from regulatory-validation-driven premium capture across the specimen transport value chain.
| Leading Market Players |
|---|
| InfeKta Packaging International |
| Polar Tech Industries |
| Com-Pac International |
| Inmark |
| Sonoco Products |
| Pelican BioThermal |
| Medline Industries |
| MarketLab |
| Sonoco |
| Others |
Value Chain & Pricing Dynamics
Vacuum-insulated panel manufacturing scaling in East Asian industrial clusters is simultaneously compressing unit economics for mid-tier thermal protection and concentrating supply leverage among specialized silica core fabricators. This dual effect forces shipper producers into long-term offtake negotiations while passing material cost volatility through to laboratory procurement functions.
Pricing Analysis
Input-cost pass-through from refrigerant chemistry and aerogel core materials dominates pricing dynamics across passive and active system tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated active systems with telemetry integration from lane-qualified passive containers and commodity expanded polystyrene designs. Price differentiation hinges on thermal qualification documentation depth and after-sales calibration service bundling. Pricing pressure stems from EPA hydrofluorocarbon phase-out timelines elevating gel pack formulation costs. Hospital group purchasing organizations exhibit highest price sensitivity, while cell therapy logistics operators absorb premiums for excursion-proof performance.
Supply Chain Analysis
Direct-to-laboratory channels handle reference laboratory demand, while distributor networks serve fragmented hospital procurement. Geographic supply concentration centers on China for vacuum-insulated panel cores, Germany for precision molding equipment, and the United States for phase-change material formulations. Raw material dependencies draw from specialized silica aerogels, hydrofluorocarbon chemistries, and medical-grade corrugated substrates. Supply chain risk rests on single-source vulnerability for aerogel core suppliers concentrated in Shandong province industrial zones. Distribution runs through laboratory supply distributors, group purchasing organization contracts, and direct OEM relationships with diagnostic manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in reusable active system service models and cloud-based tracking subscription tiers, justified by phase-change material cost compression enabling premium positioning at standard-tier economics.
For Market Incumbents: Hedge refrigerant chemistry exposure by securing dual-source phase-change material formulations ahead of EPA hydrofluorocarbon restrictions. Deepen backward integration into vacuum-insulated panel core production through captive supply agreements with East Asian fabricators. Prioritize calibration and refurbishment service revenue streams to offset hardware margin compression from group purchasing organization consolidation. For New Entrants and Emerging Players: EU MDR traceability mandates in Germany, France, and Italy open a window for validated shipper systems with pre-qualified thermal documentation. Target India biobank infrastructure buildout in Bangalore and Hyderabad for dual US-CDSCO compliance positioning. Pursue cloud-based tracking integration as primary go-to-market differentiator against legacy passive system incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized thermal engineering firms lacking integrated manufacturing scale. Long-term viability favors materials science specialists with proprietary phase-change formulations and established laboratory relationships. Monitor EPA refrigerant disposal rulemaking as inflection signal for compliance-cost-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Shipper Service Model | Captures recurring calibration revenue from hospital networks while reducing per-shipment costs. |
| Cloud-Based Tracking Integration | Enables real-time excursion alerts for genetic testing logistics commanding premium positioning. |
| Dual US-India Compliance Certification | Opens CDSCO-aligned clinical trial specimen export demand from Bangalore biotech parks. |
| Phase-Change Material Formulation Investment | Reduces EPA hydrofluorocarbon exposure while sustaining thermal performance specifications. |
| Laboratory Information System API Development | Resolves middleware gaps blocking automated temperature data ingestion in hospital networks. |
Study Parameters
Multiple input streams — thermal engineering specialists, clinical laboratory procurement managers, diagnostic company logistics directors, and cold-chain regulatory consultants — were reconciled against secondary validation from FDA 21 CFR Part 11 guidance documents, EPA refrigerant disposal regulations, EU MDR traceability frameworks, and WHO cold-chain guidelines. Bottom-up shipment estimates by product type and technology tier were cross-referenced with top-down diagnostic logistics spending analysis across United States, German, Indian, and Japanese market clusters.
Historical volume trajectories were cross-referenced against expert panel assessments of precision medicine logistics scaling and vaccine distribution protocol evolution across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, technology tier, and application with regional regulatory cluster overlays. CAGRs were derived from slope-intercept analysis of validated shipper adoption curves and phase-change material cost-down trajectories. Industry-specific forecast inputs incorporated biobank infrastructure investment pipelines and group purchasing organization contract renewal cycles.
Revisions become necessary when EPA refrigerant phase-out timelines accelerate, vacuum-insulated panel supply disruptions materialize, or FDA thermal qualification documentation requirements expand beyond current guidance. Forecasts reflect assumptions regarding laboratory consolidation trajectories and precision medicine sample volume scaling. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Thyroid Test Market
Testing Services
Global HPV Testing and Pap Test Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
Allergy Skin Test Market
Testing Services
Staphylococcus Aureus Testing Market
Testing Services
Passive Dosimetry Equipment and Service Market
Testing Services
Service Laboratory Market
Testing Services
Global Direct-To-Consumer (DTC)Testing Market
Testing Services
Drug Testing Systems Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
US Bowie Dick Test Pack Market
Testing Services
Global Creatinine Assay Kits Market
Testing Services
Nipah Virus (Niv) Infection Testing Market
Testing Services
Skin Perfusion Pressure Testing Devices Market
Testing Services
Blood Testing Market
Testing Services
Endocrine Peptides Test Market