
 North America Laboratory Hoods and Enclosure Market | 2026-2036
North America Laboratory Hoods and Enclosure Market Size, Share, and Industry Trends Forecast 2026-2036
North America Laboratory Hoods and Enclosure Market Analytics
Epoxy resin is pivoting toward polypropylene and advanced composite surfaces in fume hood construction, cutting weight and improving chemical resistance for high-throughput labs. Thermo Fisher Scientific leverages its distribution depth across the United States and Canada to sustain specification dominance in academic and government accounts. Labconco anchors its position through made-in-USA manufacturing and deep customization capabilities for pharmaceutical clients. Esco Group competes on energy-efficient blower technology, differentiating its biological safety cabinet portfolio against legacy airflow designs.
North America laboratory hoods and enclosures are engineered containment systems designed to isolate personnel from hazardous vapors, particulates, or biological agents, typically operating at face velocities between 80 and 120 feet per minute with HEPA or carbon filtration integration. Their primary purpose spans chemical synthesis protection, sterile cell culture isolation, and controlled storage of flammable or toxic reagents across institutional and industrial settings. Fume hoods retain the largest installed base but face margin compression as replacement cycles lengthen, while biological safety cabinets capture expanding value pools from cell and gene therapy manufacturing scale-ups. Ventilated enclosures for powder handling and chemical storage cabinets represent faster-growing niches, driven by OSHA-compliant solvent management mandates and nanoparticle containment protocols in pharmaceutical research.
The EPA enforces emissions thresholds that push laboratories toward ductless filtration and recirculating fume hood architectures, while OSHA ventilation standards dictate minimum face velocity and alarm system requirements that filter non-compliant suppliers from bid pools. NFPA 45 and ANSI Z9.5 provide the technical backbone for fire safety and performance testing that manufacturers must certify against for institutional procurement eligibility. Buyers should monitor how proposed EPA revisions to laboratory ventilation guidelines and state-level energy codes in California and Massachusetts reshape total cost-of-ownership calculations for new installations versus retrofits.
Market Dynamics
EPA ventilation mandates and OSHA chemical exposure thresholds are compressing replacement cycles for legacy ducted systems while accelerating specification upgrades toward ductless filtration architectures across pharmaceutical and academic installations.
Growth Catalysts
- Cell and gene therapy manufacturing:Biopharmaceutical cleanroom expansions in Massachusetts and New Jersey are driving demand for Class II biological safety cabinets with unidirectional airflow certification.
- OSHA laboratory ventilation standards:Revised face velocity requirements are disqualifying non-compliant suppliers from institutional procurement pools and forcing facility-wide hood replacement programs.
- Polypropylene surface adoption:Advanced composite materials are displacing epoxy resin in fume hood construction, cutting installation weight and improving chemical resistance for high-throughput synthesis labs.
Market Restraints
- Stainless steel and HEPA filter cost volatility:Input price swings for pharmaceutical-grade steel and certified filtration media are squeezing margins on custom enclosure builds.
- Canadian supplier concentration:Regional dependence on Ontario-based blower motor manufacturers creates vulnerability to cross-border logistics disruptions and tariff exposure.
- NFPA 45 fire safety compliance:Stringent flame resistance testing for chemical storage cabinets extends product development timelines and raises certification costs for smaller fabricators.
Strategic Opportunities
- California energy code alignment:Title 24 building efficiency standards are creating first-mover advantage for variable-air-volume hood systems with demand-controlled ventilation.
- Nanoparticle containment protocols:Pharmaceutical R&D facilities are specifying ventilated enclosures for powder handling that exceed standard fume hood specifications.
- Remote monitoring integration:Convergence of IoT airflow sensors with cloud-based compliance dashboards is opening recurring revenue streams for service-contract bundling.
Industry Challenges
- Certified containment specialist scarcity:Qualified technicians for ANSI Z9.5 performance testing and NSF/ANSI 49 field certification are concentrated in legacy Northeast pharmaceutical corridors.
- Retrofit integration complexity:Ductless filtration retrofits must reconcile with existing HVAC infrastructure, extending project timelines and requiring specialized mechanical contractor coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Laboratory Hoods and Enclosure Market |
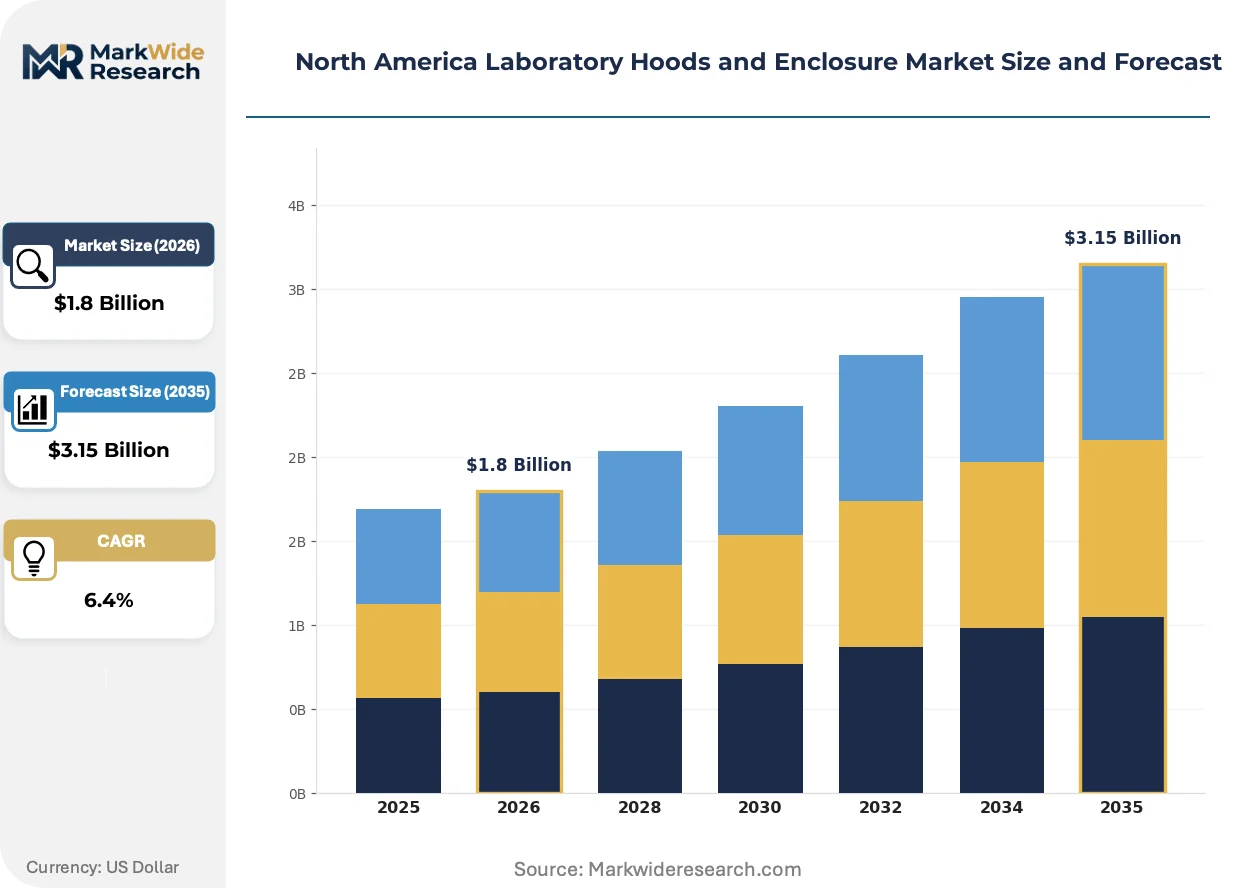
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fume Hoods, Biological Safety Cabinets, Ventilated Enclosures, Chemical Storage Cabinets Application: Pharmaceutical Research, Chemical Analysis, Academic Laboratories, Industrial Applications End User: Research Institutions, Quality Control Labs, Healthcare Facilities, Manufacturing Plants Material: Stainless Steel, Polypropylene, Epoxy Resin, Aluminum |
| Companies Covered | Thermo Fisher Scientific, Labconco, Esco Group, Terra Universal, AirClean Systems, Flow Sciences, HEMCO, NuAire, Mott Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Laboratory Hoods and Enclosure Market Evolving Landscape
Material substitution and connected monitoring architectures are displacing legacy specification patterns across North American laboratory infrastructure procurement.
Variable-air-volume fume hoods with automatic sash sensors and real-time face velocity feedback are electrifying energy efficiency benchmarks for new pharmaceutical construction. Massachusetts and New Jersey biotech clusters are specifying these systems for LEED-compliant facilities. The technology is compressing operating cost differentials between premium and standard hood categories.
EPA proposed revisions to laboratory ventilation guidelines are tightening emissions thresholds for perchloric acid and radioactive material handling. Research institutions are pre-emptively upgrading to dedicated canopy hoods and snorkel exhaust systems. California and Massachusetts facilities face the steepest compliance timelines under state-level energy and safety code convergence.
Consolidated procurement through group purchasing organizations is concentrating buying power among multi-site academic health systems. Traditional distributor relationships are yielding to direct manufacturer contracts with standardized specification templates. The shift is most pronounced in Texas and Florida where state university system capital programs are centralizing laboratory equipment acquisition.
North America Laboratory Hoods and Enclosure Market Segmentation
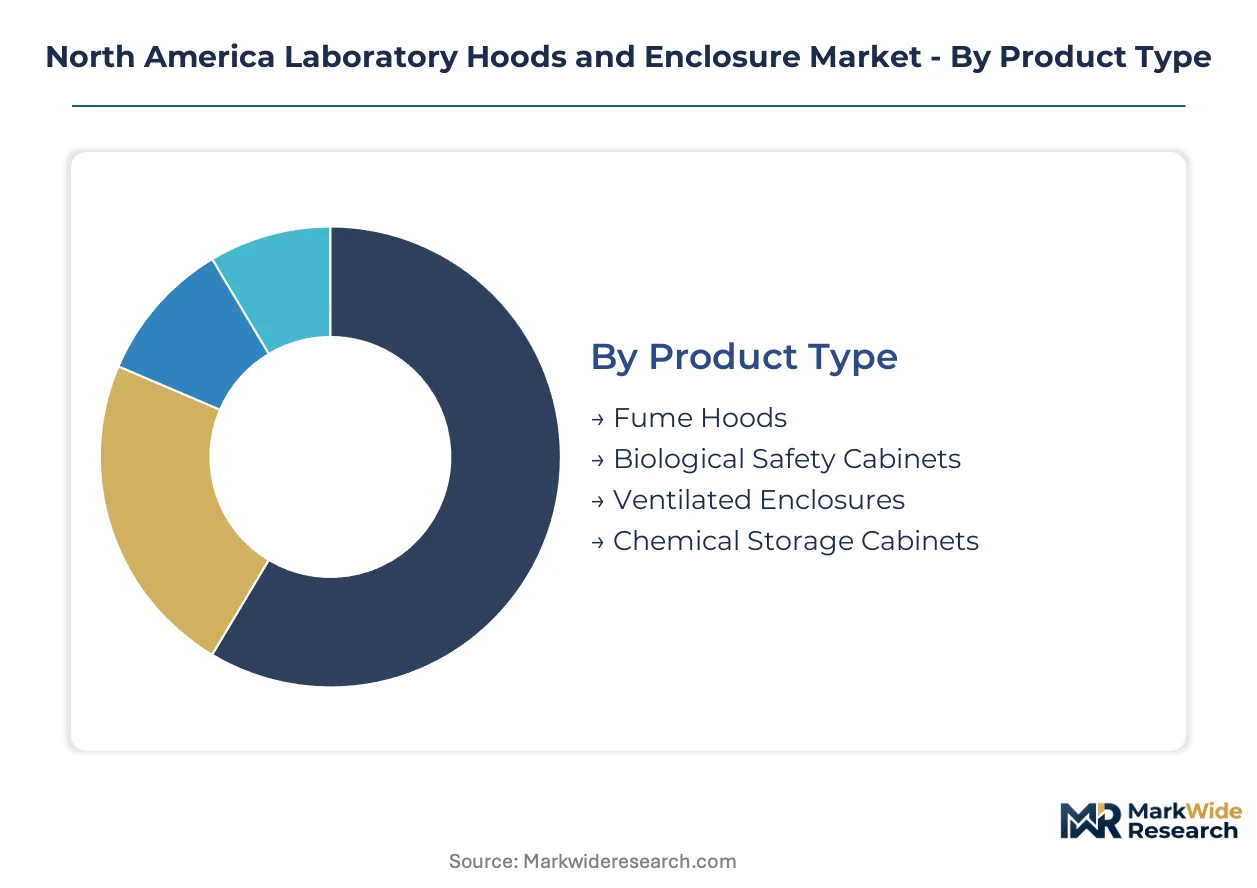
Laboratory hood procurement in North America follows distinct specification pathways shaped by containment requirements, energy codes, and facility upgrade cycles. Segmentation reveals where replacement demand concentrates versus where new installation growth emerges.
Product Type:
Replacement cycles vary dramatically across hood categories, with legacy ducted systems facing accelerated obsolescence under evolving EPA emissions thresholds.
- Fume Hoods:Ducted and ductless architectures dominate chemical synthesis protection, with variable-air-volume systems capturing specification preference in Massachusetts and New Jersey pharmaceutical construction. Face velocity compliance mandates are compressing replacement timelines for pre-2015 installations.
- Biological Safety Cabinets:Class II Type A2 and B2 configurations anchor cell and gene therapy manufacturing scale-ups. Unidirectional airflow certification requirements from NSF/ANSI 49 are filtering non-compliant suppliers from biopharmaceutical procurement pools.
- Ventilated Enclosures:Powder handling and nanoparticle containment applications are driving specification above standard fume hood performance thresholds.
- Chemical Storage Cabinets:NFPA 45 flame resistance compliance is extending development timelines for smaller fabricators serving solvent management mandates.
Fume Hoods sits at the top of the volume ranking, with Biological Safety Cabinets climbing the fastest.
Application:
Cost tier differentiation separates specification-intensive pharmaceutical installations from price-sensitive academic procurement.
- Pharmaceutical Research:Cleanroom expansions in Boston and New Jersey corridors demand HEPA-integrated containment with real-time monitoring. OSHA ventilation standards and FDA facility inspections enforce premium specification tiers with minimal price elasticity.
- Chemical Analysis:High-throughput synthesis labs prioritize chemical-resistant surfaces and automated sash controls for perchloric acid and radioactive material handling.
- Academic Laboratories:Consolidated procurement through group purchasing organizations is compressing margins for standard fume hood categories across state university systems.
- Industrial Applications:Quality control and pilot-scale manufacturing facilities balance containment performance against total cost-of-ownership calculations.
Pharmaceutical Research commands the highest specification tier, while Academic Laboratories shows the steepest price compression.
End User:
Customer type determines service bundling potential and contract structure, with multi-site health systems consolidating vendor relationships.
- Research Institutions:NIH-funded universities and federal laboratories specify ANSI Z9.5-certified systems with documented performance testing. Grant-funded capital cycles create lumpy demand concentration in Q2-Q3 fiscal periods.
- Quality Control Labs:FDA-regulated pharmaceutical manufacturing quality units require validated containment with audit trail documentation.
- Healthcare Facilities:Hospital clinical laboratories face Joint Commission inspection protocols driving replacement of non-compliant legacy hoods.
- Manufacturing Plants:Cell and gene therapy commercial production facilities are specifying biological safety cabinets with isolator integration for aseptic processing.
Research Institutions represent the deepest installed base, with Manufacturing Plants expanding most quickly.
Material:
Supply concentration for pharmaceutical-grade inputs is reshaping material selection economics across custom enclosure builds.
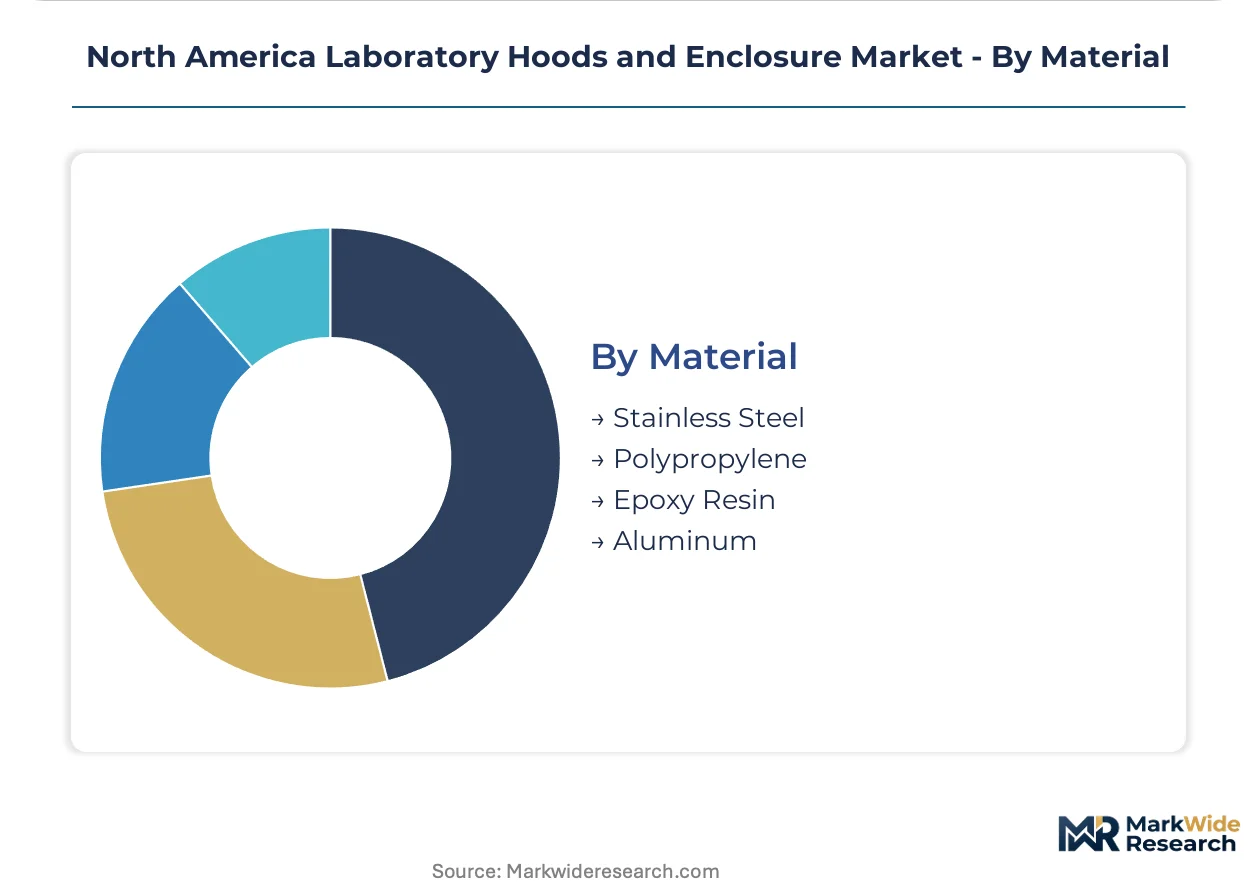
- Stainless Steel:316L and 304 grades dominate biological safety cabinet construction for cleanroom compatibility. Price volatility in nickel and chromium markets is squeezing margins on pharmaceutical-grade fabrications.
- Polypropylene:Advanced composite formulations are displacing legacy epoxy in high-throughput synthesis labs, cutting installation weight while improving chemical resistance to acids and solvents.
- Epoxy Resin:Traditional fume hood construction material facing specification erosion as polypropylene and thermoplastic alternatives capture share.
- Aluminum:Lightweight structural components for canopy hoods and snorkel exhaust systems in perchloric acid handling applications.
Stainless Steel retains specification dominance in biological containment, with Polypropylene gaining share fastest in chemical fume hood applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston pharmaceutical corridor anchors North American demand for laboratory containment systems, with Massachusetts and New Jersey biotech clusters driving specification upgrades for cell and gene therapy manufacturing facilities.
United States
Pharmaceutical cleanroom expansions in Massachusetts and New Jersey are accelerating biological safety cabinet procurement for cell therapy production. EPA ventilation mandates and OSHA face velocity requirements are compressing replacement cycles for legacy ducted fume hoods. Texas and Florida state university systems are consolidating laboratory equipment acquisition through centralized capital programs.
Canada
Ontario-based blower motor manufacturers supply critical components to cross-border pharmaceutical installations in Quebec and British Columbia. Health Canada facility inspection protocols align with FDA standards, driving validated containment specifications for biologics manufacturing. Toronto and Montreal academic medical centers are upgrading clinical laboratory infrastructure under Joint Commission-aligned protocols.
Mexico
Nearshoring of pharmaceutical quality control operations to Nuevo León and Jalisco is creating demand for ANSI Z9.5-certified fume hood installations. Mexican federal environmental regulations are tightening emissions standards for chemical synthesis facilities. Mexico City metropolitan research institutes are modernizing containment infrastructure for NIH-funded collaborative programs.
North America Laboratory Hoods and Enclosure Market Competitive Landscape
Global majors compete with regional champions across distribution depth and customization capabilities in the North American laboratory hood market. The vendor base organizes around three strategic tiers: diversified life science conglomerates with specification dominance in institutional accounts, mid-sized domestic fabricators with made-in-USA positioning, and specialized containment technology developers focused on energy efficiency and connected monitoring. Competitive intensity is concentrating through direct manufacturer contracts displacing traditional distributor relationships, and through portfolio diversification into service-contract bundling for compliance monitoring.
Within the diversified conglomerate tier, Thermo Fisher Scientific exemplifies specification dominance through distribution breadth across academic and government accounts. Labconco occupies a position as a domestic fabricator archetype, anchoring made-in-USA manufacturing and deep customization capabilities for pharmaceutical clients. Esco Group represents the specialized technology developer archetype, competing on energy-efficient blower differentiation against legacy airflow designs in biological safety cabinet applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Labconco |
| Esco Group |
| Terra Universal |
| AirClean Systems |
| Flow Sciences |
| HEMCO |
| NuAire |
| Mott Manufacturing |
| Others |
Value Network & Pricing Analysis
Captive in-house production of HEPA filtration media and blower motor assemblies anchors pricing power for integrated manufacturers serving pharmaceutical-grade specifications. This vertical control over critical components insulates premium suppliers from raw material volatility while forcing price discipline on smaller fabricators dependent on outsourced Ontario motor suppliers and Asian steel distributors.
Pricing Analysis
Stainless steel and nickel alloy pass-through costs dominate margin pressure for biological safety cabinet fabricators. Pricing stratifies across NSF/ANSI 49-certified premium tiers, standard ANSI Z9.5-compliant systems, and economy-grade academic installations. Cost compression in the economy tier is intensifying because state university GPO consolidation concentrates buying power. Academic laboratories exhibit the steepest price sensitivity, while cell therapy manufacturers show minimal elasticity due to FDA validation requirements.
Supply Chain Analysis
Dual-sourcing mandates from biopharmaceutical buyers require qualified backup suppliers for HEPA filtration media and certified blower motors. Manufacturing concentrates in the United States, Canada, and Mexico under USMCA alignment. Supply chains draw from 316L stainless steel distributors, polypropylene resin compounders, and specialized motor winders. Single-source vulnerability concentrates in Ontario-based blower motor manufacturers facing cross-border tariff exposure. Distribution runs through direct manufacturer contracts with multi-site health systems and legacy distributor networks serving fragmented academic accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America laboratory hood market compounds steadily as EPA and OSHA ventilation mandates force recurring replacement cycles across installed base infrastructure.
For Market Incumbents: Lock in specification dominance by securing ANSI Z9.5 and NSF/ANSI 49 certification maintenance contracts with Boston and New Jersey biotech clusters. Deepen backward integration into HEPA media production to defend margins against filter cost volatility. Channel control through direct manufacturer contracts with Texas and Florida state university systems neutralizes distributor disintermediation threats. For New Entrants and Emerging Players: E-commerce specification tools and digital compliance dashboards offer low-friction entry into mid-tier academic procurement. Target ventilated enclosures for nanoparticle handling, where pharmaceutical R&D facilities lack established supplier relationships. White-space exists in remote monitoring service contracts bundling IoT airflow sensors with cloud-based OSHA documentation. For Investors and Strategic Acquirers: Roll-up economics work for regional fabrication specialists because certification barriers and made-in-USA positioning create durable local moats. The 5-10 year viability window favors platforms consolidating domestic custom enclosure builders with pharmaceutical client books. Watch California Title 24 energy code enforcement as the inflection signal for variable-air-volume system adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HEPA Media | Captive filtration production insulates margins from certified media cost swings. |
| Remote Monitoring Platform Launch | IoT airflow sensors unlock recurring SaaS revenue from compliance-conscious pharmaceutical clients. |
| California Energy Code Alignment | Variable-air-volume certification captures LEED-driven construction in Massachusetts and New Jersey corridors. |
| Direct Manufacturer Contract Expansion | Bypassing distributors concentrates margin capture in consolidated academic health system procurement. |
| Nanoparticle Enclosure Development | Powder handling specifications exceed standard fume hood performance for pharmaceutical R&D facilities. |
Research Methodology
Bottom-up pharmaceutical and academic installation modeling reconciled against top-down blower motor and filtration media supply tracking forms the analytical core. Primary interviews with facility managers at NIH-funded research institutions, GPO procurement directors, HVAC mechanical contractors, and containment certification technicians combined with secondary validation from EPA enforcement databases, OSHA ventilation standard dockets, NSF/ANSI 49 registration listings, and state university capital expenditure disclosures. Triangulation across these sources calibrated installed base estimates against replacement cycle assumptions.
Historical trendline analysis of fume hood and biological safety cabinet shipments anchored projection trajectories across the analysis window. Segmentation dimensions modeled include product architecture, application intensity, end-user procurement structure, and regional energy code stringency. CAGRs derived from fitted growth curves incorporating biopharmaceutical cleanroom expansion pipelines, academic capital cycle timing, and regulatory compliance deadline clustering. Industry-specific inputs captured polypropylene substitution rates and variable-air-volume specification penetration.
The model assumes a particular technology adoption path; alternative pathways for ductless filtration architectures would alter the outlook if EPA emissions thresholds tighten faster than projected. Deviation in Canadian cross-border logistics conditions or Ontario motor supplier consolidation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Blood Testing Equipment Market
Laboratory Equipment
Global Graduated Cylinder Market
Laboratory Equipment
Laboratory Furnaces Market
Laboratory Equipment
South Korea Pipette Tips Market
Laboratory Equipment
Absorbance Micro Plate Reader Market
Laboratory Equipment
Global Blood Gas Analyzers Market
Laboratory Equipment
Muffle Laboratory Furnaces Market
Laboratory Equipment
Laboratory Glassware and Plasticware Market
Laboratory Equipment
Ion-Selective Clinical Lab Analyzers Market
Laboratory Equipment
Latin America Laboratory Equipment and Disposables Market
Laboratory Equipment
Blood Volume Analyzer Market
Laboratory Equipment
Test Tube Market
Laboratory Equipment
Middle East and Africa Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Laboratory Equipment and Disposables Market