
 Hemotransmissive Infections Testing Market | 2026-2036
Hemotransmissive Infections Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Hemotransmissive Infections Testing Market Foresight
Asset-light leasing models for automated diagnostic platforms is fragmenting capital barriers across mid-sized laboratories. Abbott leverages its installed base of molecular systems to sustain recurring reagent revenue in high-throughput settings. Bio-Rad Laboratories anchors its position through specialized quality controls that laboratories require for assay validation. Grifols competes through vertical integration from plasma collection to finished diagnostic kits, controlling supply security for blood bank customers.
Hemotransmissive infections testing encompasses serological and molecular assays designed to detect blood-borne pathogens in donor and patient samples, typically achieving analytical sensitivity below 50 copies per milliliter for viral nucleic acid targets. These tests serve the critical purpose of preventing pathogen transmission through transfused blood components and organ grafts. Nucleic acid testing commands premium positioning due to its window-period reduction capabilities, while rapid tests occupy emergency and point-of-care channels where speed outweighs sensitivity. Blood donation screening generates the most stable volume commitments, though diagnostic testing for at-risk populations represents the fastest-expanding application segment as clinical guidelines broaden screening criteria.
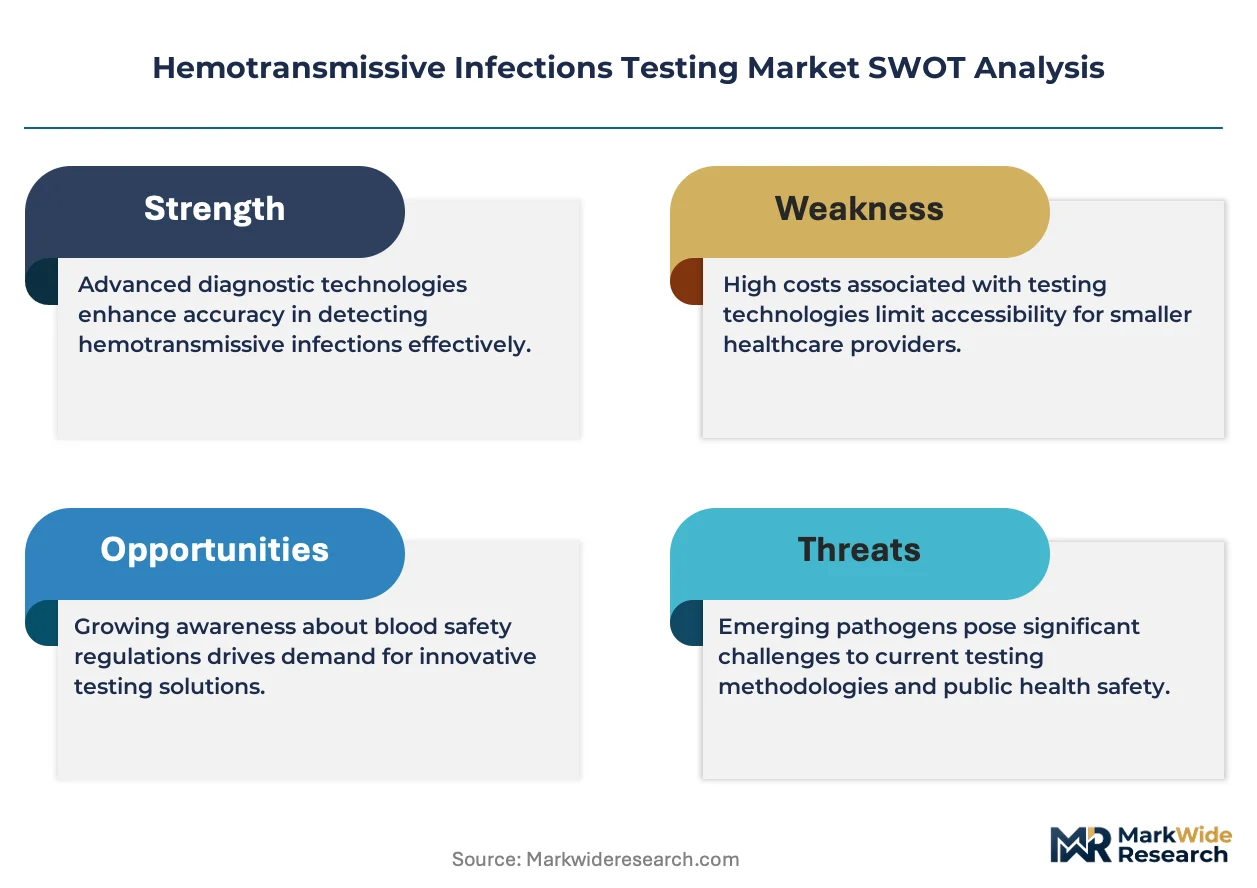
The FDA enforces nucleic acid testing requirements for HIV-1 and hepatitis C virus in all donated blood and tissue, directly mandating technology upgrades across blood bank networks. The EMA's CE-IVDR framework tightens performance documentation for serological assays entering European markets, raising compliance costs for manufacturers. India's CDSCO implements mandatory hepatitis B surface antigen screening under national blood safety programs, shaping procurement specifications for public hospital tenders. Stakeholders must monitor evolving multiplex panel approvals that consolidate pathogen detection into single-reaction workflows.
Market Dynamics
Molecular diagnostics is migrating from centralized reference laboratories toward mid-sized hospital blood banks, compressing testing turnaround times and forcing equipment manufacturers to redesign platform footprints for smaller operational spaces.
Growth Catalysts
- FDA Nucleic Acid Testing Mandates:The FDA's requirement for HIV-1 and HCV NAT screening in all donated blood creates mandatory technology refresh cycles across US blood bank networks, locking in sustained reagent demand.
- India Hepatitis C Expansion:The CDSCO's push for wider HCV detection in regional hospital networks concentrates procurement volume in public tenders, accelerating platform installations in tier-2 and tier-3 cities.
- Multiplex Panel Consolidation:Single-reaction workflows combining HIV, HBV, and HCV detection reduce per-test labor costs and consumable waste, driving replacement demand for discrete serological systems.
Market Restraints
- Reagent Cost Volatility:Proprietary chemistries and enzyme formulations face input pressure from specialized polymer supply chains concentrated in German and Japanese chemical manufacturers.
- CE-IVDR Documentation Burden:The EMA's tightened performance documentation requirements for serological assays entering European markets extend compliance timelines and raise regulatory filing costs for manufacturers without established quality management systems.
- Point-of-Care Sensitivity Gap:Rapid immunoassay platforms cannot match molecular analytical sensitivity, limiting their penetration in donor screening applications where window-period detection remains non-negotiable.
Strategic Opportunities
- Brazil Blood Bank Modernization:ANVISA's evolving technical standards for transfusion safety create first-mover advantage for NAT platform suppliers in Latin America's largest hospital network.
- Automated Quality Control Integration:Convergence of liquid handling robotics with real-time assay validation software reduces manual intervention and shifts competitive differentiation toward software-enabled workflow optimization.
- Direct Hospital Procurement Channels:Blood bank networks in Saudi Arabia and the UAE are bypassing traditional distributor relationships, creating margin recovery opportunity for manufacturers with localized technical service capabilities.
Industry Challenges
- Molecular Diagnostics Specialist Shortage:Blood banks struggle to recruit trained personnel for NAT platform operation and troubleshooting, particularly in rural and semi-urban collection centers where salary competitiveness lags metropolitan reference laboratories.
- Legacy System Integration Friction:New multiplex platforms must interface with established laboratory information systems and blood bank management software, extending deployment timelines and requiring customized middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemotransmissive Infections Testing Market |
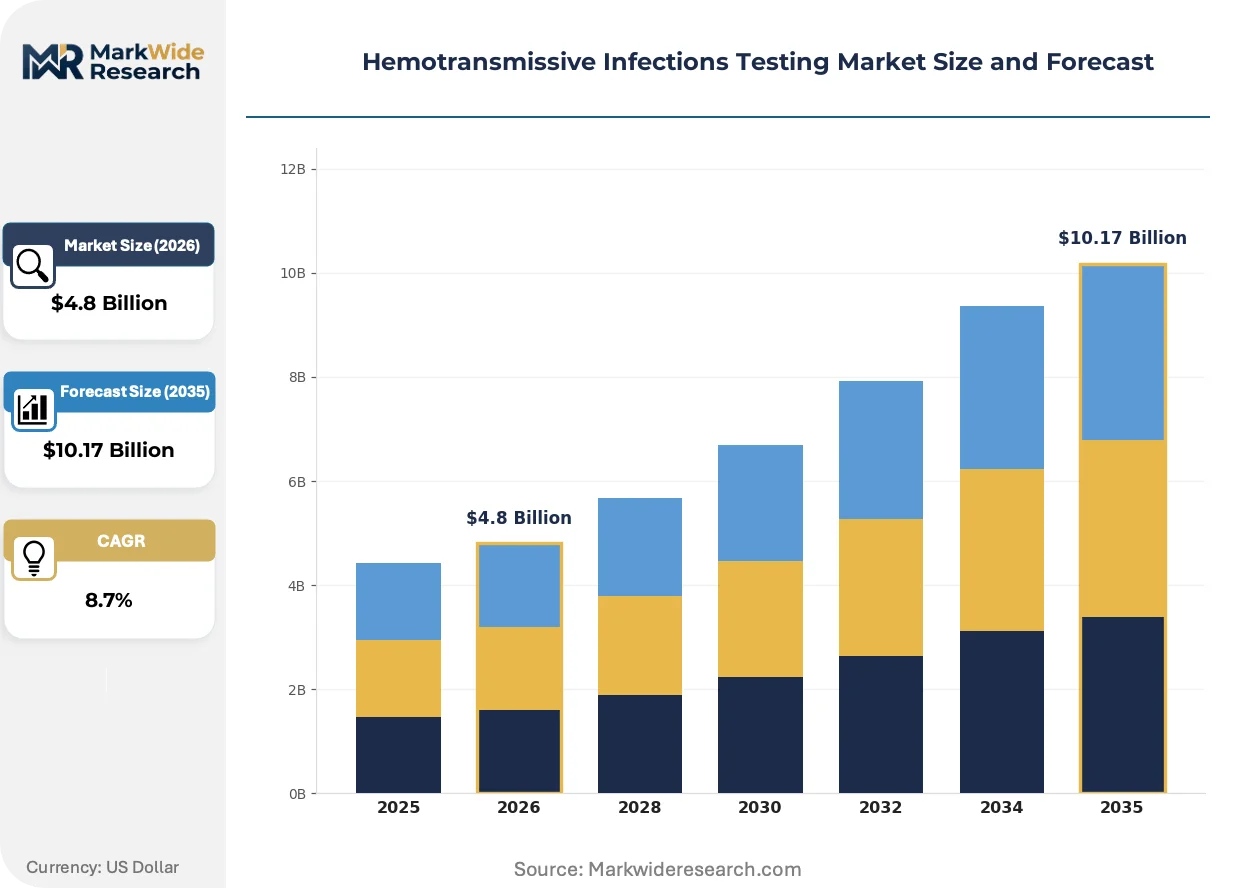
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: ELISA, Nucleic Acid Testing, Rapid Tests, Western Blot Pathogen Type: HIV, Hepatitis B, Hepatitis C, Syphilis Application: Blood Donation Screening, Blood Transfusion, Diagnostic Testing, Research End User: Hospitals, Blood Banks, Diagnostic Laboratories, Research Institutions |
| Companies Covered | Grifols, Bio-Rad Laboratories, Immucor, QuidelOrtho Corporation, Abbott, F. Hoffmann-La Roche Ltd, Ortho Clinical Diagnostics, BioMérieux, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemotransmissive Infections Testing Market Shifts & Advancements
Assay miniaturization and cloud-connected instrument telemetry are compressing the gap between high-throughput reference laboratories and distributed testing nodes, enabling real-time quality monitoring across fragmented blood bank networks.
Digital PCR technology is migrating from research oncology applications into transfusion medicine quality control workflows. Large regional blood centers in Germany and Japan are adopting absolute quantification methods for viral load standardization. This migration from relative to absolute measurement is compressing inter-laboratory variability and enabling direct assay harmonization across multi-site collection networks.
The EU's In Vitro Diagnostic Regulation (IVDR) reclassification of serological assays is forcing manufacturers to generate clinical performance data for legacy products previously grandfathered under the IVDD directive. Manufacturers with diversified geographic revenue bases are prioritizing MDR-compliant technical documentation to maintain European market access. Smaller assay developers without dedicated regulatory affairs functions are exiting the European market, consolidating supplier options for blood bank procurement officers.
Hospital networks are consolidating blood bank operations into centralized regional hubs, eliminating redundant testing capacity at individual collection sites. This consolidation is displacing standalone rapid test procurement in favor of contracted reference laboratory services with guaranteed turnaround service levels. The shift is most visible in Australia's public health system, where state-based blood services have standardized on two national testing providers.
Hemotransmissive Infections Testing Market Segmentation
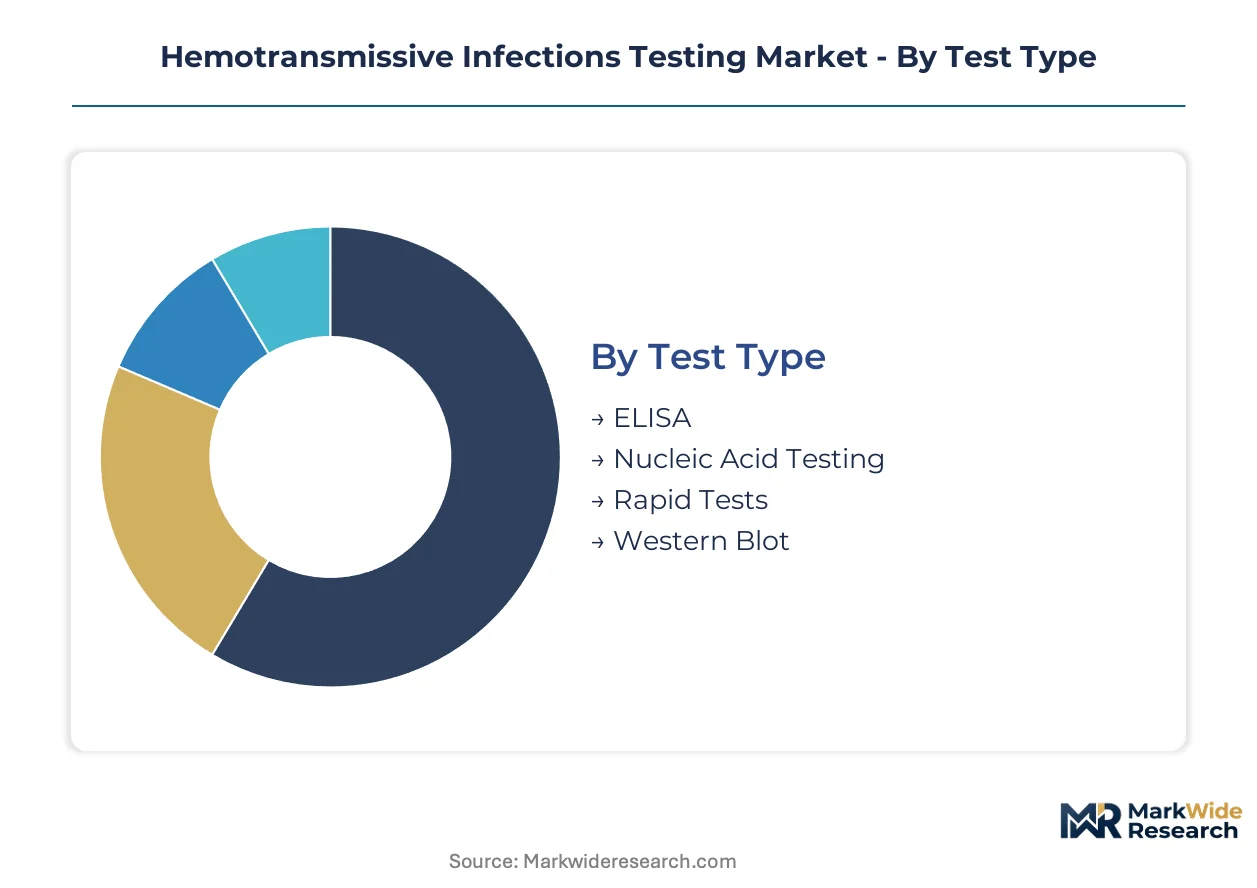
Hemotransmissive infections testing fragments across four distinct classification axes, each shaping procurement patterns and margin structures differently. Test type determines capital intensity and reagent economics. Pathogen focus dictates regulatory validation pathways and tender specifications.
Test Type:
Nucleic acid testing platforms command the longest replacement cycles due to capital lock-in, while rapid tests turn over fastest as emergency departments refresh stock continuously.
- Nucleic Acid Testing:Polymerase chain reaction and transcription-mediated amplification methods detect viral genetic material below 50 copies per milliliter. Blood banks in the United States concentrate procurement here as FDA mandates eliminate serological alternatives for donor screening.
- ELISA:Enzyme-linked immunosorbent assays detect antibody and antigen responses with established workflow integration. Diagnostic laboratories in India leverage ELISA for hepatitis B surface antigen screening under CDSCO-mandated programs where throughput exceeds NAT capacity constraints.
- Rapid Tests:Lateral flow immunoassays deliver results within 20 minutes at point-of-care nodes.
- Western Blot:Confirmatory protein detection methods resolve indeterminate serological results in reference settings.
Nucleic acid testing anchors the volume base while rapid tests gain share at the steepest rate.
Pathogen Type:
Cost tier differentiation separates premium-priced multiplex panels from single-target commodity assays.
- HIV:Dual detection of p24 antigen and antibodies compresses the serological window period. Blood donation screening in Germany and Japan drives demand for fourth-generation assay formats with nucleic acid confirmation workflows.
- Hepatitis C:Core and NS3 antigen detection enables earlier infection identification. India's CDSCO pushes HCV RNA testing expansion through regional hospital network tenders, concentrating procurement volume in public sector channels.
- Hepatitis B:Surface antigen and core antibody screening prevents transmission from occult carriers.
- Syphilis:Treponemal and non-treponemal antibody detection supports transfusion safety protocols.
Hepatitis B screening anchors the volume base while hepatitis C detection climbs the fastest as guidelines broaden testing criteria.
Application:
Customer workflow integration separates scheduled batch processing from stat turnaround requirements.
- Blood Donation Screening:High-throughput mandatory testing of volunteer donors generates stable reagent commitments. Blood banks in Australia have consolidated operations into state-based hubs with contracted service levels, displacing fragmented rapid test procurement.
- Diagnostic Testing:Clinical screening of at-risk populations follows expanded guideline criteria. Hospital networks in Saudi Arabia and the UAE bypass distributors for direct manufacturer relationships, reshaping procurement channel economics.
- Blood Transfusion:Pre-transfusion compatibility and infection verification at point of care.
- Research:Epidemiological surveillance and assay development in academic and government laboratories.
Blood donation screening anchors the volume base while diagnostic testing expands most quickly as clinical criteria widen.
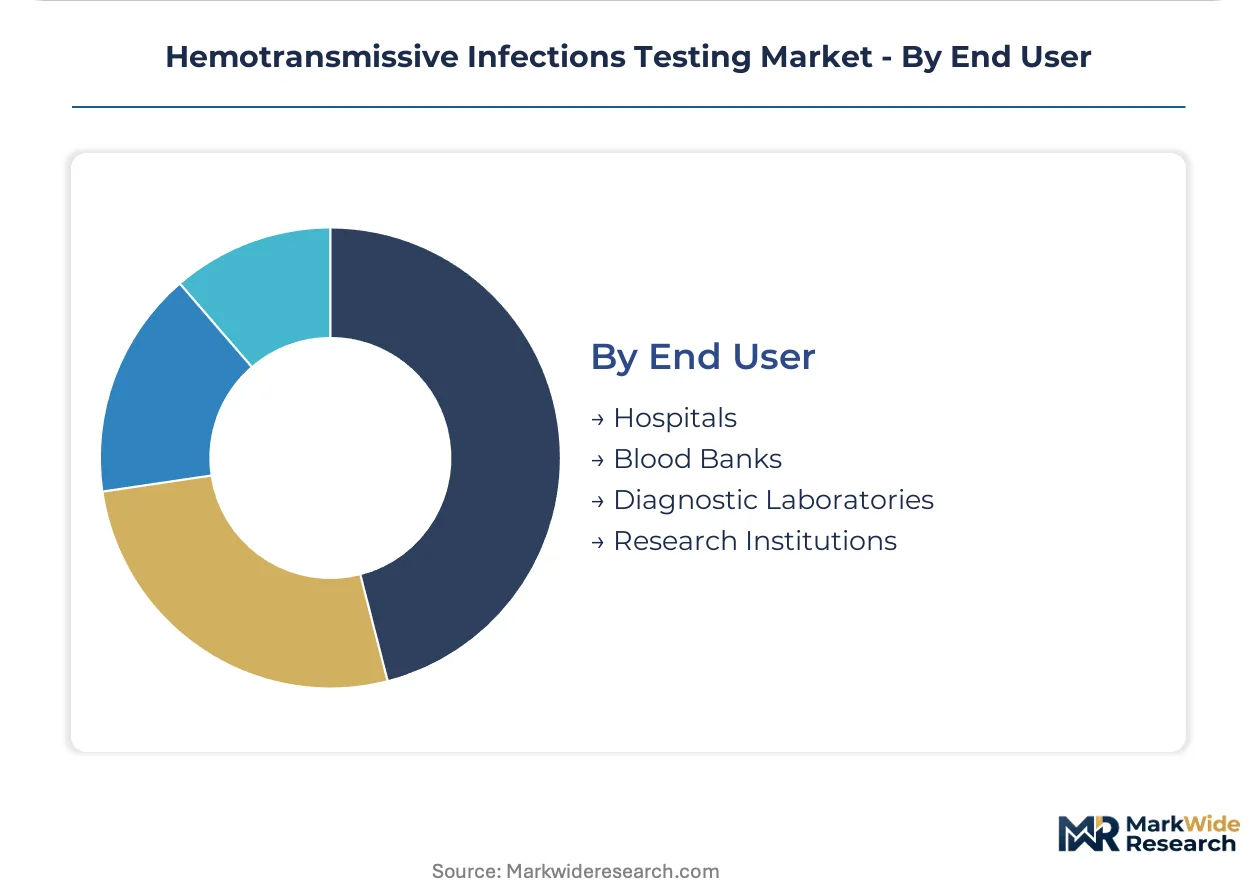
End User:
Supply concentration varies sharply between centralized reference laboratories and distributed hospital nodes.
- Blood Banks:Dedicated collection and processing facilities with standardized high-volume workflows. ANVISA's evolving technical standards in Brazil create first-mover opportunities for NAT platform suppliers in Latin America's largest hospital network.
- Diagnostic Laboratories:Independent and hospital-affiliated testing facilities with flexible menu configurations. Asset-light leasing models fragment capital barriers across mid-sized laboratories in tier-2 and tier-3 Indian cities.
- Hospitals:Integrated clinical and transfusion services with mixed stat and routine demand.
- Research Institutions:Academic and government facilities with specialized protocol requirements.
Blood banks anchor the volume base while diagnostic laboratories gain share fastest as molecular testing migrates from centralized hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for NAT reagents concentrates in Germany and Japan, while the United States and India drive platform installation growth. Export-oriented diagnostics manufacturers in Switzerland and the Netherlands supply quality control materials globally. Regional procurement patterns diverge sharply between mandatory blood bank screening programs and diagnostic testing expansion.
United States
Blood bank networks in Chicago, Los Angeles, and New York Metro are upgrading molecular platforms as FDA nucleic acid testing mandates eliminate serological alternatives for HIV-1 and HCV screening. The FDA's donor testing requirements lock in sustained reagent demand across high-throughput collection centers. Abbott and Roche maintain installed base dominance in these metropolitan hubs through recurring consumable contracts.
Germany
Large regional blood centers in Bavaria and North Rhine-Westphalia are adopting digital PCR for viral load standardization and inter-laboratory harmonization. The EMA's CE-IVDR framework tightens performance documentation for serological assays entering European markets. Frankfurt and Munich clusters concentrate quality control manufacturing for export to blood bank networks across the continent.
India
Regional hospital networks in Maharashtra, Karnataka, and Tamil Nadu are expanding hepatitis C detection capacity under CDSCO procurement mandates. Asset-light leasing models fragment capital barriers across mid-sized laboratories in tier-2 and tier-3 cities. Delhi-NCR and Hyderabad hubs drive platform installation growth as public tenders concentrate procurement volume.
Brazil
ANVISA's evolving technical standards for transfusion safety are creating first-mover opportunities for NAT platform suppliers in São Paulo and Rio de Janeiro. Blood bank modernization in the Southeast region displaces fragmented rapid test procurement. Minas Gerais and Rio Grande do Sul are consolidating testing operations into centralized regional hubs.
Japan
Metropolitan blood centers in Tokyo, Osaka, and Nagoya are migrating to absolute quantification methods for viral load standardization. METI-supported quality initiatives compress inter-laboratory variability across multi-site collection networks. Kanto and Kansai regions anchor demand for specialized polymer supply chains concentrated in domestic chemical manufacturers.
Hemotransmissive Infections Testing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagents and quality controls. The market structures around three tiers: multinational conglomerates with installed base leverage, mid-sized specialists in assay validation materials, and regional distributors with localized service capabilities. Consolidation pressures favor players with captive reagent supply and regulatory documentation depth. Competitive moves center on multiplex panel approvals and automated workflow integration.
Within the platform integrator tier, Abbott and Roche exemplify archetypes leveraging molecular system installed bases for recurring consumable revenue. Grifols occupies a position spanning plasma collection through finished diagnostic kits, representing vertical integration from raw material to blood bank customer. Bio-Rad Laboratories anchors the quality control specialist segment, supplying assay validation materials that laboratories require for regulatory compliance. These three players represent distinct strategic positions: system lock-in, supply chain control, and regulatory enablement.
| Leading Market Players |
|---|
| Grifols |
| Bio-Rad Laboratories |
| Immucor |
| QuidelOrtho Corporation |
| Abbott |
| F. Hoffmann-La Roche Ltd |
| Ortho Clinical Diagnostics |
| BioMérieux |
| Thermo Fisher Scientific |
| Others |
Supply & Pricing Matrix
Overcapacity in NAT reagent production across German and Japanese chemical manufacturers is compressing supplier pricing power while blood banks exploit volume consolidation to extract preferential contract terms. This utilization dynamic forces reagent suppliers to bundle quality control materials and technical service into base pricing, eroding standalone premium tiers.
Pricing Analysis
Blood bank procurement officers anchor contract-based long-term offtake structures, locking in multi-year reagent commitments that trade price certainty for volume guarantees. Price differentiation rests on FDA tier certification and after-sales field service density, with metropolitan reference laboratories least sensitive and tier-3 hospital networks most price-responsive. Cost compression in rapid immunoassay segments is intensifying because lateral flow manufacturers face polymer substrate input pressure from concentrated Asian suppliers. Multiplex panel providers command premium positioning over discrete serological assays due to labor savings and consumable efficiency.
Supply Chain Analysis
Specialized polymer and enzyme formulation capacity concentrates in Germany, Japan, and Switzerland, with Frankfurt and Munich clusters anchoring quality control material output for global blood bank networks. NAT platform assembly draws from Taiwanese precision electronics, German optical components, and Japanese thermal cycling hardware. Single-source vulnerability in reverse transcriptase enzyme supply chains creates disruption exposure if Japanese chemical manufacturers face export restrictions. Distribution runs through regional laboratory distributors in fragmented markets and direct manufacturer relationships in Saudi Arabia and UAE hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-moat defense story where FDA nucleic acid testing mandates create switching costs that lock blood banks into validated platform ecosystems. Compliance documentation depth functions as the structural barrier protecting incumbent positions.
For Market Incumbents: Pre-empt emerging point-of-care molecular platforms by embedding cloud-connected telemetry into existing installed bases, converting hardware relationships into recurring software revenue streams. Consolidate quality control material suppliers to secure captive reagent supply chains before CE-IVDR documentation requirements eliminate smaller assay developers from European tenders. Defensive priority centers on multiplex panel R&D investment to maintain window-period sensitivity advantages over rapid test substitutes.
For New Entrants and Emerging Players: Tier-2 and tier-3 Indian cities with CDSCO-mandated hepatitis C expansion represent the most penetrable entry point, where asset-light leasing models fragment capital barriers for mid-sized laboratories. Brazil's ANVISA blood bank modernization in Southeast regional hubs offers first-mover positioning before incumbent platform contracts solidify. Go-to-market execution should prioritize localized technical service capabilities over distributor relationships to capture direct hospital procurement channels in Gulf Cooperation Council markets.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform integrators with installed base leverage and captive reagent supply, positioning these archetypes for sustained cash flow quality across the analysis window. Acquisition targets should demonstrate regulatory documentation depth under CE-IVDR or FDA premarket pathways, with quality control material specialists offering defensive margin profiles. The signal to watch is multiplex panel approval velocity at FDA and EMA, as consolidation into single-reaction workflows accelerates replacement demand for discrete serological systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex Panel Regulatory Submission | FDA 510(k) pathway for HIV-HBV-HCV combined detection compresses competitor window-period advantages. |
| Cloud-Connected Instrument Telemetry | Real-time quality monitoring across fragmented blood bank networks shifts differentiation toward software-enabled workflow optimization. |
| Asset-Light Leasing Model Expansion | Equipment-as-a-service structures fragment capital barriers across mid-sized laboratories in tier-2 Indian cities. |
| Backward Integration into Polymer Supply | In-house production of specialized enzyme formulations reduces exposure to German and Japanese chemical manufacturer concentration. |
| Direct Hospital Procurement Channel Development | Bypassing distributor relationships in Saudi Arabia and UAE blood bank networks recovers margin compression from traditional channel economics. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearances, EMA CE-IVDR technical documentation, and CDSCO tender specifications. Primary interviews engaged blood bank operations directors, clinical laboratory managers, diagnostic platform engineers, and GPO contracts managers across United States, German, Indian, and Brazilian hospital networks. Secondary validation drew from hospital procurement databases, blood safety regulatory filings, and customs records for NAT reagent trade flows. Bottom-up platform installation counts triangulated against top-down reagent consumption estimates across the analysis window.
Forecast inputs considered test type segmentation by technology platform, pathogen focus by regulatory validation pathway, application by workflow integration requirements, and end user by supply concentration patterns. Modeled dimensions included nucleic acid testing versus serological assay format, donor screening versus diagnostic testing application, and centralized reference laboratory versus distributed hospital node end user. CAGRs derived from reagent consumption trajectory analysis and platform replacement cycle modeling. Industry-specific inputs incorporated FDA mandate implementation timelines and CDSCO procurement tender velocity.
Practitioners should monitor multiplex panel approval decisions at FDA and EMA, CDSCO tender award patterns in Maharashtra and Karnataka, and ANVISA technical standard evolution for early signals of competitive positioning shifts. Forecasts reflect assumptions regarding regulatory mandate enforcement continuity and reagent supply chain stability. Quarterly review of platform installation data, reagent pricing indices, and quality control material supplier consolidation indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Redox Meter Market
Testing Services
Global HIV Self Test Kits Market
Testing Services
Hospital Acquired Disease Testing Market
Testing Services
Global HPV Testing and Pap Test Market
Testing Services
Urine Sediment Testing Market
Testing Services
Fecal Pancreatic Elastase Testing Market
Testing Services
Special Coagulation Tests Market
Testing Services
Global Ovulation Test Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
US Pharmaceutical Sterility Testing Market
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
Pyrogen Testing Market
Testing Services
Asia Pacific Pregnancy and Ovulation Testing Market
Testing Services
Biological Indicator Incubators Market
Testing Services
Ovulation Test Kit Market
Testing Services
Lipase Testing Reagents Market