
 Cryogenic Insulation Market | 2026-2036
Cryogenic Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Insulation Market Intelligence
The capital-intensity gap between aerogel specialists and commodity foam producers is collapsing as scale thresholds fall. Aspen Aerogels leverages proprietary manufacturing to sustain premium positioning in aerospace fuel tank applications. Dow Inc. anchors its presence through backward integration into petrochemical feedstocks for foam insulation systems. Saint-Gobain differentiates via ceramic fiber expertise that competes directly in industrial gas pipeline retrofits.
Cryogenic insulation comprises engineered materials and systems designed to maintain temperatures below minus 150 degrees Celsius while minimizing heat flux through low thermal conductivity barriers, typically employing vacuum-degassed powders, multilayer reflective films, or nanoporous silica structures. These systems prevent boil-off losses in liquefied gas storage and protect structural integrity in extreme cold environments. Aerogel blankets command expanding share in LNG storage installations where space constraints and thermal performance requirements intensify. Multilayer insulation dominates aerospace fuel tank applications due to weight-critical performance demands. Foam insulation retains volume leadership across industrial gas pipelines where cost sensitivity shapes procurement decisions.
EPA guidelines and the EU F-Gas Regulation are tightening permissible thermal conductivity thresholds, forcing reformulation of legacy foam chemistries and accelerating validation cycles for new materials. ISO 12241 and BSI standards for cryogenic piping further constrain market access for uncertified suppliers. Stakeholders must monitor evolving methane emissions accounting rules and their cascading impact on insulation lifecycle valuation methodologies.
Market Dynamics
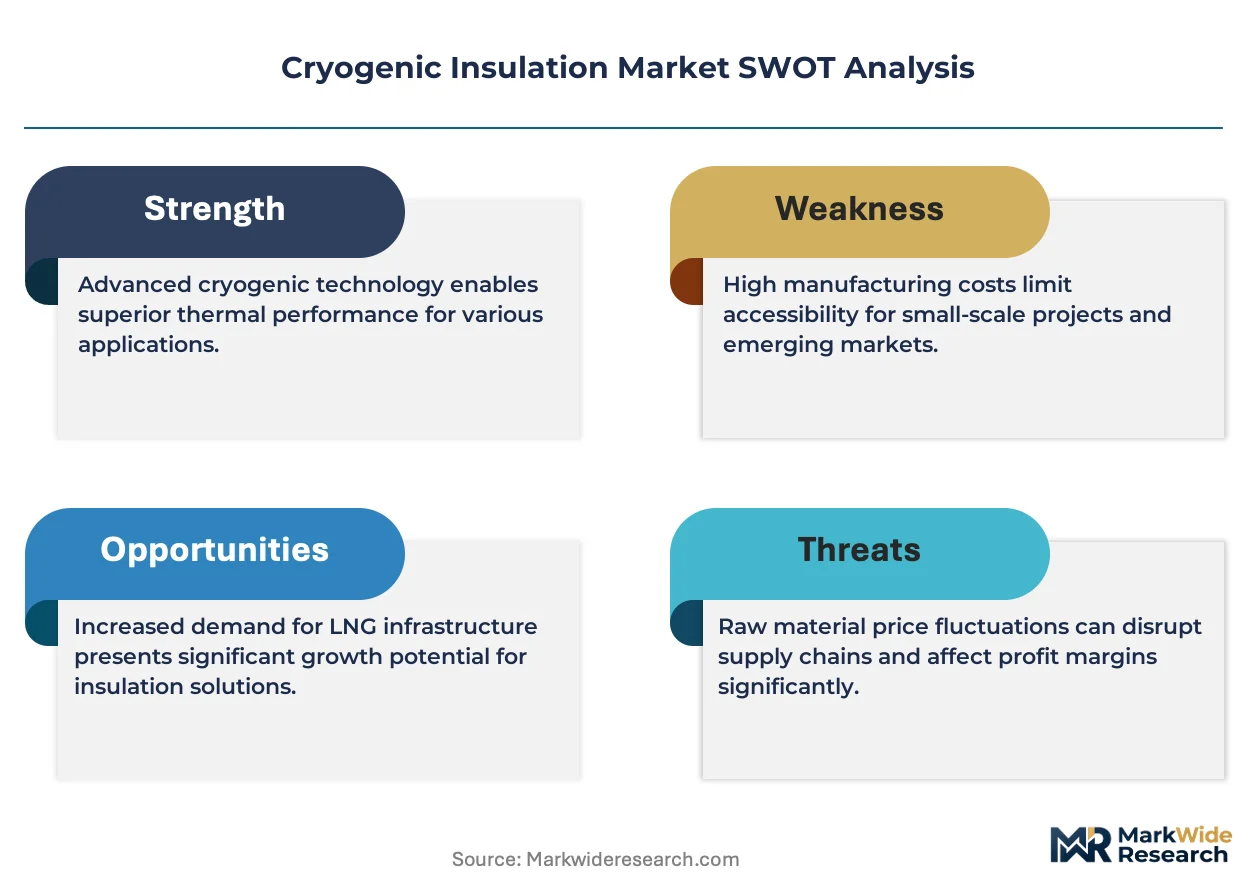
EU F-Gas Regulation thermal conductivity mandates are forcing wholesale material reformulation across legacy foam systems, collapsing validation timelines and compressing supplier margins while opening entry paths for aerogel alternatives.
Growth Catalysts
- LNG Terminal Buildout:Energy majors are expanding liquefaction capacity at marine terminals in the United States, China, and Germany, pulling multilayer insulation and vacuum-insulated panel demand for storage tanks and transfer lines.
- REACH Chemical Restrictions:The European Chemicals Agency is accelerating phase-out of high-GWP blowing agents in polyurethane foams, redirecting procurement toward nanoporous silica and aerogel blanket systems.
- Space Launch Frequency:NASA and private launch operators are scaling liquid hydrogen and liquid oxygen tank production, creating sustained demand for weight-optimized multilayer insulation in aerospace fuel systems.
Market Restraints
- Silica Precursor Volatility:Tetraethyl orthosilicate and sodium silicate prices fluctuate with semiconductor and construction sector demand, squeezing aerogel producer margins unpredictably.
- Single-Source Vacuum Equipment:Cryogenic vacuum panel manufacturing depends on specialized degassing chambers concentrated in German and Japanese equipment suppliers, creating supply bottlenecks.
- Foam Thermal Performance Ceiling:Rigid polyurethane and polyisocyanurate foams face fundamental conductivity limits around 20 mW/m·K, blocking adoption in next-generation LNG carrier designs.
Strategic Opportunities
- India LNG Import Infrastructure:The Petroleum and Natural Gas Regulatory Board is licensing new floating storage regasification units at Dahej and Hazira, opening first-mover positions for vacuum-insulated piping systems.
- Green Hydrogen Storage:Liquid hydrogen tanks for renewable energy storage are emerging as a high-specification application where aerogel-MLI hybrid systems command performance premiums.
- ISO 12241 Certification Services:Third-party validation laboratories are creating recurring revenue streams by pre-certifying insulation systems for cryogenic piping contractors.
Industry Challenges
- Cryogenic Materials Engineering Talent:Universities produce insufficient specialists in low-temperature thermodynamics and vacuum science, forcing manufacturers to train internally.
- Multi-Standard Compliance Burden:Suppliers must simultaneously satisfy EPA SNAP program requirements, EU F-Gas phase-down schedules, and BSI cryogenic piping standards, extending product development cycles.
- Legacy Pipeline Retrofit Integration:Industrial gas distributors face technical complexity bonding new insulation to aged carbon steel surfaces without thermal bridge formation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Insulation Market |
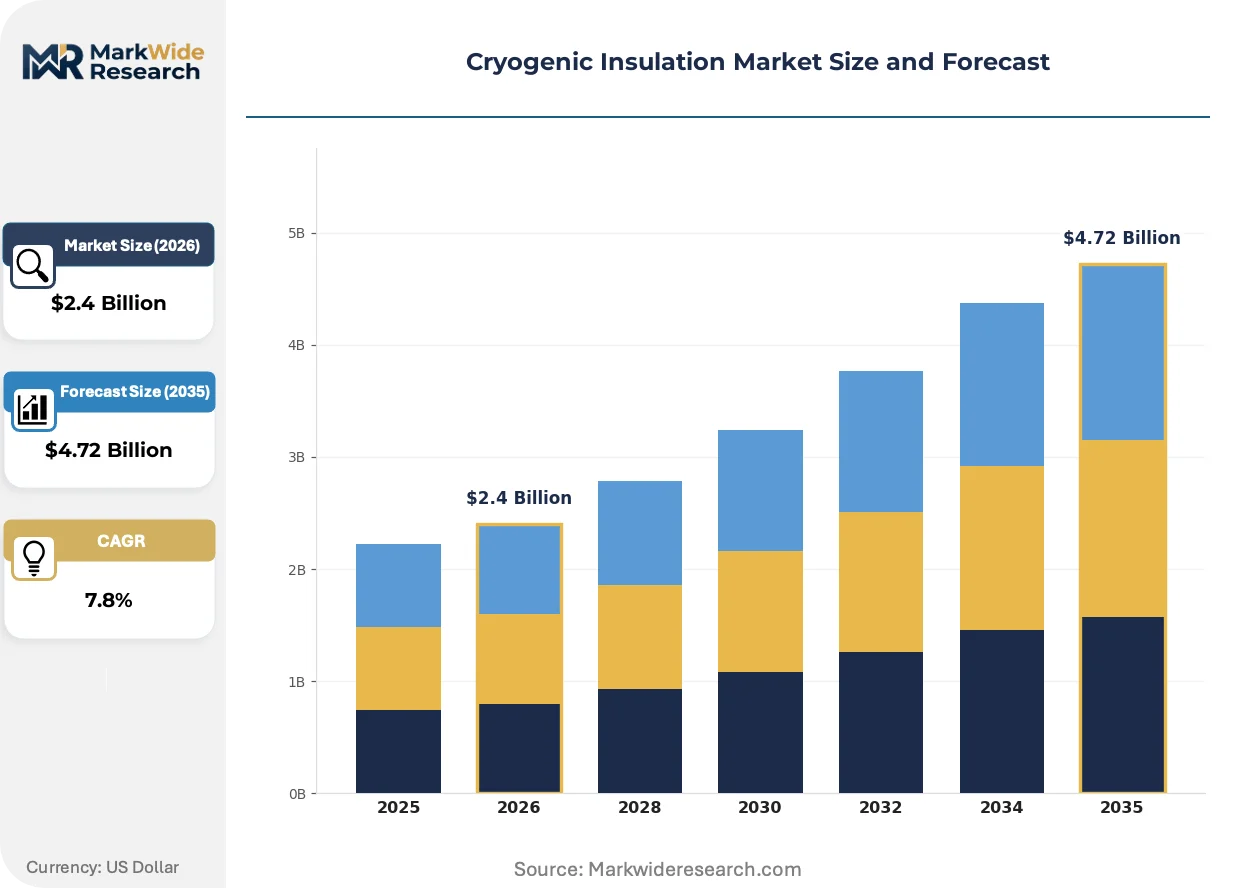
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Insulation, Vacuum Insulation Panels, Aerogel Blankets, Cryogenic Fiberglass, Multilayer Insulation Application: Liquefied Natural Gas Storage, Industrial Gas Pipelines, Aerospace Fuel Tanks, Medical Gas Systems, Cryogenic Freeze Drying End User: Energy Companies, Aerospace Manufacturers, Chemical Processors, Medical Facilities, Research Laboratories Installation Type: Prefabricated Panels, On-Site Application, Retrofits, Modular Systems, Custom Fabrications |
| Companies Covered | Aspen Aerogels, Dow Inc., Armacell, Zotefoams, Saint-Gobain, BASF SE, Owens Corning, Alkegen, Cabot Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Insulation Market Strategic Shifts & Innovations
Material science breakthroughs are compressing the performance-cost tradeoff that historically separated aerospace-grade systems from industrial commodity foams, enabling technology migration across application tiers.
Aerogel composite blankets are decomposing the traditional segmentation between premium aerospace insulation and cost-constrained industrial applications. LNG terminal operators in Germany and the United States are adopting these systems for above-ground storage tanks where space constraints intensify. The technology is decomposing incumbent foam market share by delivering sub-15 mW/m·K conductivity without vacuum dependency.
The EU F-Gas Regulation is tightening permissible global warming potential thresholds for insulation blowing agents through 2030. Foam manufacturers are reformulating with hydro-olefin and water-blown chemistries, accelerating validation costs. Industrial gas pipeline retrofits across France, Italy, and Spain face material substitution timelines compressed by enforcement deadlines.
Buyers are consolidating insulation procurement under engineering-procurement-construction contractors rather than fragmented maintenance budgets. LNG liquefaction project developers in Texas, Louisiana, and British Columbia now specify single-source accountability for tank, piping, and transfer system insulation. This concentration is compressing supplier bases and elevating certification requirements as selection criteria.
Cryogenic Insulation Market Segmentation
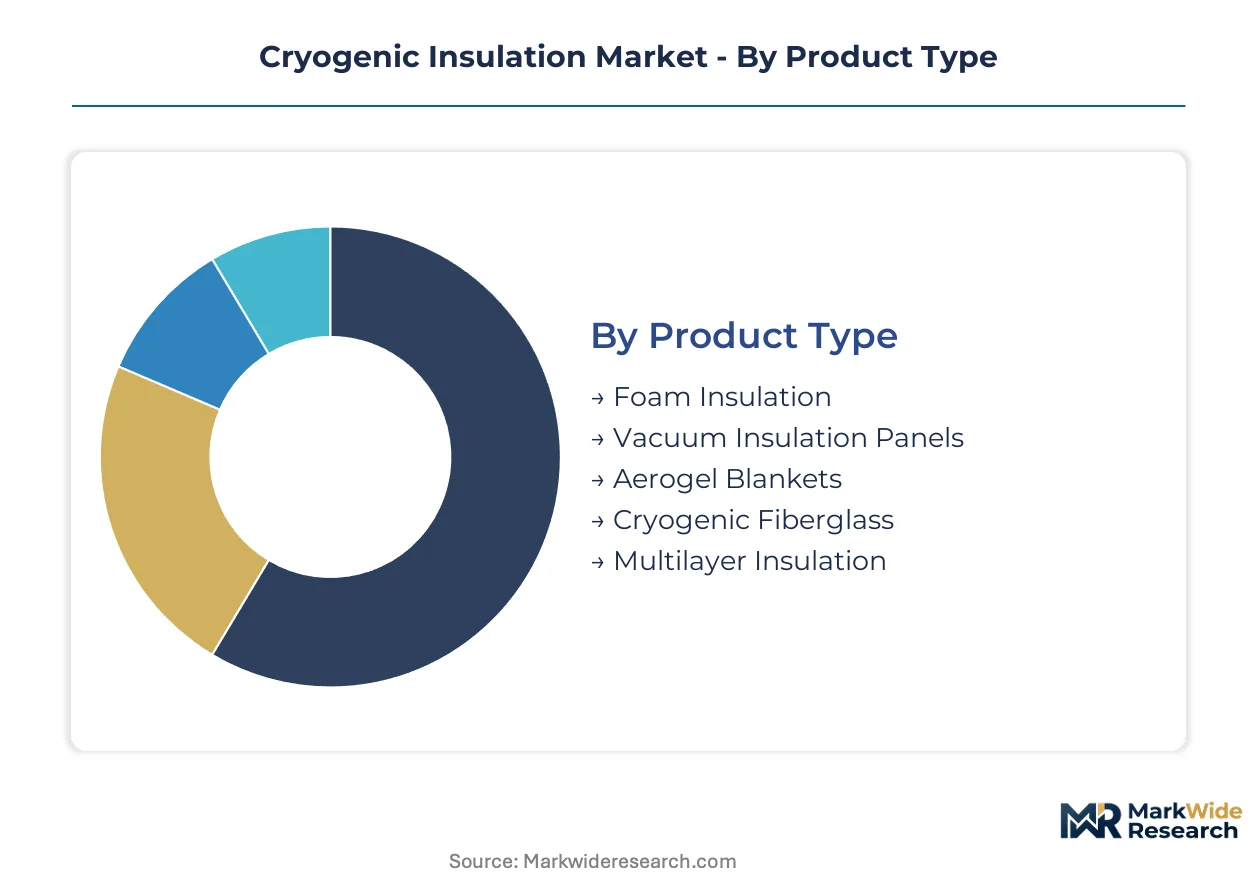
Cryogenic insulation procurement splits across five distinct dimensions, each carrying different technical certification burdens and margin structures. Product type segmentation reveals the clearest substitution dynamics as aerogel alternatives displace legacy foam in high-specification installations.
Product Type:
Foam insulation faces the most acute substitution pressure from nanoporous silica alternatives as thermal conductivity mandates tighten across energy infrastructure projects.
- Foam Insulation:Rigid polyurethane and polyisocyanurate systems dominate industrial gas pipelines where cost sensitivity shapes procurement. Dow Inc. anchors supply through backward integration into petrochemical feedstocks. REACH chemical restrictions on high-GWP blowing agents are forcing wholesale reformulation across European installations.
- Aerogel Blankets:Nanoporous silica structures deliver sub-15 mW/m·K conductivity without vacuum dependency. LNG terminal operators in Germany and the United States are adopting these systems for above-ground storage tanks where space constraints intensify. Aspen Aerogels leverages proprietary manufacturing to sustain premium positioning.
- Vacuum Insulation Panels:Degassed powder cores sealed in metallized films serve space-constrained applications.
- Cryogenic Fiberglass:Woven glass fiber mats with specialized binders target industrial retrofit markets.
- Multilayer Insulation:Alternating reflective films and spacer materials dominate aerospace fuel tank applications.
Foam insulation anchors the volume base while aerogel blankets gain share at the steepest rate.
Application:
Cost tier segmentation separates commodity pipeline work from premium aerospace specifications with tenfold price differentials.
- Liquefied Natural Gas Storage:Above-ground and marine tank insulation must withstand thermal cycling and mechanical stress across decades of service. Energy majors expanding liquefaction capacity in Texas, Louisiana, and British Columbia are consolidating procurement under single-source EPC contractors.
- Aerospace Fuel Tanks:Liquid hydrogen and liquid oxygen systems demand weight-optimized multilayer insulation with stringent outgassing specifications. NASA and private launch operators scaling production are creating sustained demand for aerospace-grade systems.
- Industrial Gas Pipelines:Distribution networks for nitrogen, oxygen, and argon require cost-effective thermal protection.
- Medical Gas Systems:Hospital bulk oxygen and nitrogen storage prioritizes safety certification over thermal performance optimization.
- Cryogenic Freeze Drying:Pharmaceutical lyophilization equipment uses specialized insulation for process temperature control.
LNG storage commands the largest procurement volumes while aerospace fuel tanks carry the highest specification premiums.
End User:
Customer type segmentation tracks procurement concentration from fragmented maintenance budgets toward consolidated EPC-led project sourcing.
- Energy Companies:LNG liquefaction developers and industrial gas distributors drive bulk procurement for new-build infrastructure. These buyers are shifting from fragmented maintenance budgets to consolidated EPC contractor accountability.
- Aerospace Manufacturers:Launch vehicle producers and satellite builders specify custom multilayer insulation for propellant systems. Boeing and SpaceX production ramps are pulling dedicated supply capacity.
- Chemical Processors:Petrochemical and specialty chemical plants require cryogenic insulation for process equipment.
- Medical Facilities:Hospital systems purchase standardized insulation for bulk gas storage installations.
- Research Laboratories:National labs and university facilities need specialized systems for scientific equipment.
Energy companies dominate absolute procurement volumes while aerospace manufacturers set the performance ceiling for material specifications.
Installation Type:
Supply concentration varies sharply between factory-controlled prefabrication and field-dependent on-site application.
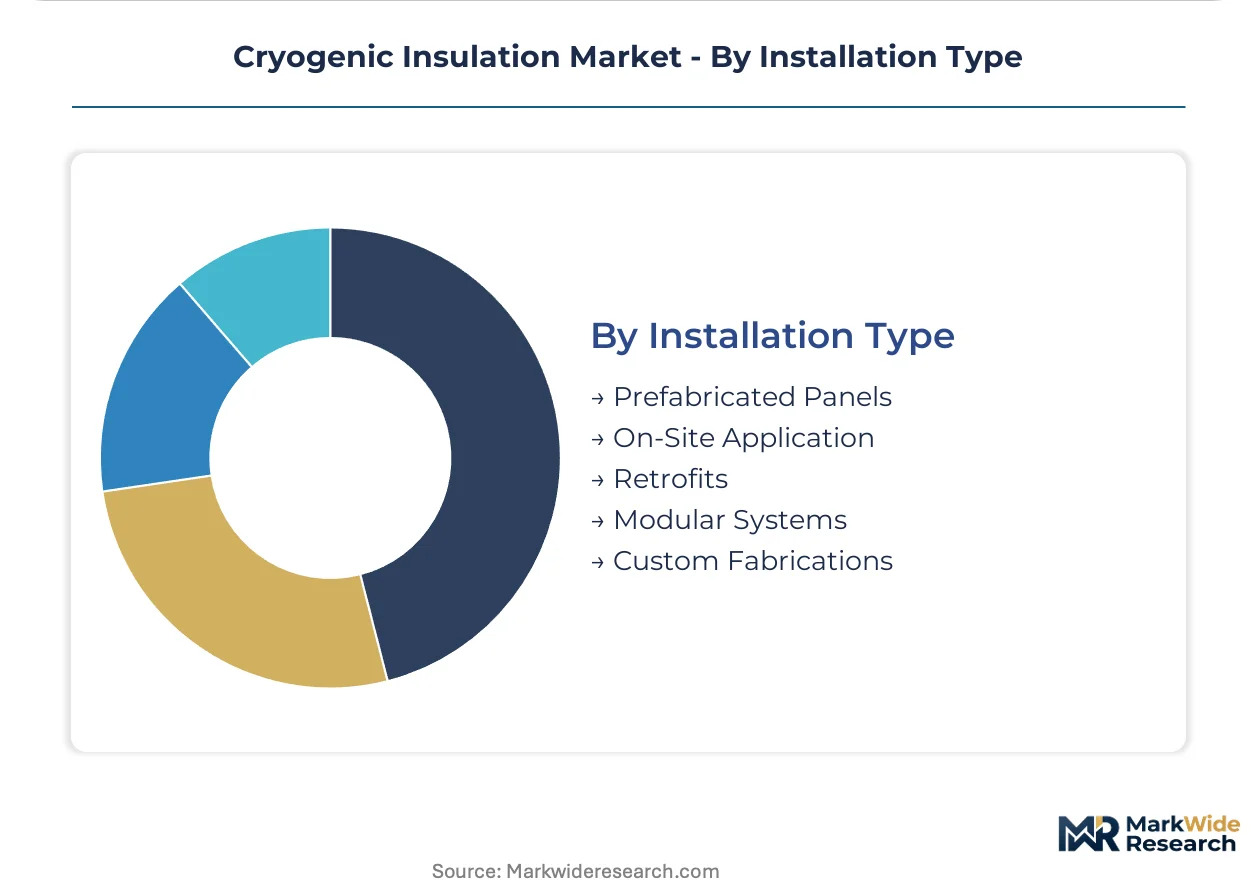
- Prefabricated Panels:Factory-produced insulation sections with integrated vapor barriers enable rapid field assembly. German and Japanese equipment suppliers concentrate vacuum panel manufacturing capacity.
- On-Site Application:Spray and pour-in-place foam systems serve complex geometries and tight schedules. Skilled applicator availability constrains project timelines in North American markets.
- Retrofits:Bonding new insulation to aged carbon steel surfaces without thermal bridge formation presents technical complexity.
- Modular Systems:Pre-engineered skids with integrated insulation reduce field labor requirements.
- Custom Fabrications:One-off designs serve specialized research and aerospace applications.
On-site application handles the greatest project volume while prefabricated panels capture share in schedule-critical LNG terminal builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States absorb premium pricing for aerogel systems without volume elasticity, while procurement teams in India and China negotiate aggressively on foam insulation for pipeline networks.
United States
LNG liquefaction developers in Texas and Louisiana are consolidating procurement under single-source EPC contractors for above-ground storage tanks. EPA SNAP program requirements are accelerating phase-out of high-GWP blowing agents in polyurethane foam formulations. The Gulf Coast industrial corridor anchors North American demand as Cheniere Energy and Venture Global expand export terminal capacity.
Germany
Industrial gas distributors across the Rhine-Ruhr region are retrofitting aged carbon steel pipelines with ceramic fiber insulation systems. The EU F-Gas Regulation mandates thermal conductivity thresholds that collapse validation timelines for legacy foam chemistries. Bavaria's aerospace cluster around Munich pulls multilayer insulation demand for satellite propellant tank production.
China
State-owned energy majors are licensing floating storage regasification units at Ningbo and Zhoushan marine terminals. MIIT standards for cryogenic equipment certification constrain market access for uncertified foreign suppliers. The Yangtze River Delta concentration of shipyards is scaling vacuum-insulated panel production for LNG carrier construction.
India
The Petroleum and Natural Gas Regulatory Board is licensing new import terminals at Dahej and Hazira on the Gujarat coast. BIS certification requirements for cryogenic piping materials extend product development cycles for international entrants. Mumbai's engineering-procurement-construction hub is consolidating insulation procurement away from fragmented maintenance budgets.
Japan
Specialized degassing chamber manufacturers in Osaka and Nagoya concentrate vacuum panel production capacity for regional supply. METI efficiency standards for LNG infrastructure are tightening permissible heat flux thresholds in storage applications. The Chubu industrial belt serves as the primary equipment supplier to South Korean and Chinese terminal developers.
Cryogenic Insulation Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with aerogel specialists commanding specification premiums while petrochemical-integrated foam producers anchor volume tiers. The market structure concentrates around three strategic positions: backward-integrated chemical conglomerates, specialized nanoporous material developers, and ceramic fiber industrial incumbents. Dominant competitive moves include captive supply of petrochemical feedstocks and proprietary manufacturing scale-up for sub-15 mW/m·K conductivity systems.
Among North American specialists, Aspen Aerogels exemplifies the premium-tier archetype through proprietary nanoporous silica manufacturing, while Dow Inc. anchors the cost-driven segment with in-house production of polyurethane feedstocks. Saint-Gobain occupies a position bridging industrial and aerospace specifications through ceramic fiber expertise.
| Leading Market Players |
|---|
| Aspen Aerogels |
| Dow Inc. |
| Armacell |
| Zotefoams |
| Saint-Gobain |
| BASF SE |
| Owens Corning |
| Alkegen |
| Cabot Corporation |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between LNG terminal developers and insulation suppliers lock in both feedstock allocation and price visibility across multi-year project horizons, compressing spot market liquidity while stabilizing margin structures for certified manufacturers.
Pricing Analysis
After-sales service revenue from installation supervision and thermal performance warranties drives lifetime value for insulation system providers. Three-tier pricing structure across aerospace-grade multilayer systems, industrial aerogel blankets, and commodity foam separates specification tiers by thermal conductivity thresholds and certification burden. Cost compression in rigid polyurethane segments is intensifying because REACH-mandated blowing agent reformulation elevates raw material expenses. Pipeline retrofit contractors exhibit highest price sensitivity, while aerospace fuel tank manufacturers absorb premium positioning without volume elasticity.
Supply Chain Analysis
German and Japanese equipment suppliers for specialized degassing chambers create chokepoints that constrain vacuum-insulated panel manufacturing scale-up. Raw material flows draw from Chinese sodium silicate production, Middle Eastern petrochemical feedstocks for polyurethane precursors, and Appalachian silica sand deposits for aerogel synthesis. Single-source vulnerability concentrates in metallized film suppliers for multilayer insulation reflective layers. Distribution runs through engineering-procurement-construction contractors consolidating procurement for LNG liquefaction projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory certification entrenchment creates switching costs that lock in incumbent positions across multi-year validation cycles.
For Market Incumbents: Shield market position by deepening captive supply of petrochemical feedstocks for foam insulation systems and accelerating ISO 12241 pre-certification investments ahead of EU F-Gas enforcement deadlines. Emerging aerogel specialists threaten premium-tier margins through sub-15 mW/m·K conductivity offerings without vacuum dependency. Capacity addition in the US Gulf Coast anchors volume defense against import competition. For New Entrants and Emerging Players: Anchor in India's floating storage regasification unit licensing wave at Dahej and Hazira, where BIS certification gaps delay established foreign suppliers. Green hydrogen liquid storage tank applications represent the most penetrable high-specification segment for aerogel-MLI hybrid systems. Joint development agreements with German equipment suppliers bypass vacuum chamber supply bottlenecks. For Investors and Strategic Acquirers: Nanoporous silica technology developers with proprietary manufacturing scale-up capabilities present the most attractive acquisition archetype for portfolio exposure to thermal conductivity mandate tightening. Long-term viability hinges on material science differentiation surviving foam chemistry reformulation cost compression. Watch EU F-Gas phase-down enforcement intensity as the critical inflection signal for aerogel substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | Dow Inc.'s captive supply of polyurethane precursors anchors cost position against reformulation headwinds. |
| ISO 12241 Pre-Certification Investment | Third-party validation laboratories create recurring revenue streams from cryogenic piping contractors. |
| Aerogel-MLI Hybrid System Development | Aspen Aerogels targets green hydrogen storage applications where performance premiums command pricing power. |
| Joint Venture with German Equipment Suppliers | Japanese vacuum chamber manufacturers expand capacity access for LNG carrier panel production. |
| Long-term Supply Agreement with LNG Developers | Cheniere Energy and Venture Global consolidate procurement under single-source EPC accountability. |
Research Approach
A standing panel of LNG terminal project engineers, cryogenic equipment procurement managers, aerospace fuel tank designers, and industrial gas distribution maintenance directors provided ongoing calibration against field installation realities. Primary interviews with EPC contractors and insulation system applicators combined with secondary validation from customs trade data, SEC 10-K filings of petrochemical suppliers, and EU ECHA regulatory submissions. Bottom-up project pipeline tracking and top-down energy infrastructure investment flows enabled triangulation across modeling approaches.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type tier, application specification level, end-user procurement concentration, and regional regulatory framework cluster. CAGRs derived from installer capacity expansion announcements and thermal efficiency mandate implementation schedules. Forecast inputs incorporated silica precursor price volatility indices and LNG liquefaction project sanctioning velocity.
Material uncertainties — EU F-Gas enforcement intensity, REACH chemical restriction timelines, and semiconductor sector demand swings for silica precursors — sit outside the modeled envelope. Forecasts reflect assumptions about certification validation cycle durations and EPC contractor consolidation trajectories. Practitioners should keep alternative scenarios live as green hydrogen storage demand scaling and aerospace launch frequency trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Lip Seals Market
Industrial Materials
Asia-Pacific Industrial Flooring Market
Industrial Materials
Global Polyurethane Screen Panels Market
Industrial Materials
Industrial Brushes Market
Industrial Materials
Tension Spring Market
Industrial Materials
Ribbed Smoke Sheet Market
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
Global Industrial Dust Collector Market
Industrial Materials
Global Machined Seals Market
Industrial Materials
Global Friction Materials Market
Industrial Materials
Global Graphite Electrodes Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
GCC Welding Consumables Market
Industrial Materials
Air Classifiers Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Anode Carbon Block Market