
 Anode Carbon Block Market | 2026-2036
Anode Carbon Block Market Size, Share, and Industry Trends Forecast 2026-2036
Anode Carbon Block Market Insights
Market Dynamics
Primary aluminum smelters is unwinding legacy procurement patterns toward integrated carbon suppliers. SGL Carbon leverages captive needle coke refining to secure raw material streams across European smelter networks. Tokai Carbon anchors Japanese supply chains through dedicated portside blending facilities. Mersen competes in specialty chemical processing grades where thermal shock resistance commands premium positioning.
Product Landscape
Anode carbon blocks are dense carbonaceous structures manufactured from calcined petroleum coke and coal tar pitch binder, typically formed by vibro-pressing or isostatic pressing to achieve electrical resistivity below 55 μΩ·m for stable electrolytic cell performance. Graphite carbon blocks dominate aluminum smelting applications where dimensional stability under thermal cycling protects pot linings. Isostatic pressing technology leads premium segment supply due to uniform density distribution, while extrusion occupies cost-sensitive foundry demand.
Regulatory Environment
China's MEE enforces dual carbon goals tightening emission intensity benchmarks for electrolytic aluminum, forcing smelters to specify higher-grade anode blocks that reduce per-tonne CO2 output. The EU Green Deal and REACH framework restrict polycyclic aromatic hydrocarbon content in coal tar pitch binders, reshaping formulation chemistry across European supply chains. Stakeholders must monitor carbon border adjustment mechanisms and evolving green aluminum certification standards to align product roadmaps with buyer compliance requirements.
Market Dynamics
Primary aluminum smelters are consolidating procurement around integrated carbon suppliers capable of guaranteeing needle coke supply security amid volatile petroleum feedstock markets. This structural pull toward supply chain control is compressing spot-market participation and elevating long-term offtake contracting.
Growth Catalysts
- China's dual carbon goals:The MEE enforces stricter emission intensity benchmarks on electrolytic aluminum production, compelling smelters to specify higher-density anode blocks that reduce per-tonne CO2 output and extend pot lining life cycles.
- Middle East smelter investments:New capacity builds in Saudi Arabia and the UAE require premium anode grades with superior thermal shock resistance, creating concentrated demand pull for isostatic-pressed products.
- Needle coke refining:Captive production of this critical raw material secures supply streams for integrated carbon manufacturers serving European smelter networks.
Market Restraints
- Needle coke supply concentration:Asian refiners dominate high-quality needle coke output, exposing non-integrated anode producers to feedstock bottlenecks and price volatility.
- Coal tar pitch formulation limits:REACH restrictions on polycyclic aromatic hydrocarbon content constrain binder chemistry options, forcing reformulation costs across European supply chains.
- Inert anode substitution threat:Experimental oxygen-evolving anode technologies promise elimination of carbon consumption entirely, threatening long-term demand destruction if commercialized at scale.
Strategic Opportunities
- Green aluminum certification standards:Emerging buyer mandates for low-carbon primary metal create premium positioning for anode blocks with verified emission reductions through the supply chain.
- Carbon border adjustment mechanisms:The EU CBAM incentivizes smelters to document embedded carbon in anode inputs, favoring suppliers with transparent Scope 3 accounting.
- Integrated digital twin systems:Convergence of potline sensor networks with predictive anode performance modeling enables outcome-based supply contracts linking block quality to operational metrics.
Industry Challenges
- Specialized carbon materials engineering talent:The shallow pool of professionals combining petroleum coke characterization expertise with electrolytic cell thermal modeling constrains R&D velocity.
- Isostatic press capacity expansion:Premium-grade production requires capital-intensive equipment with long lead times, creating timing mismatches with smelter procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anode Carbon Block Market |
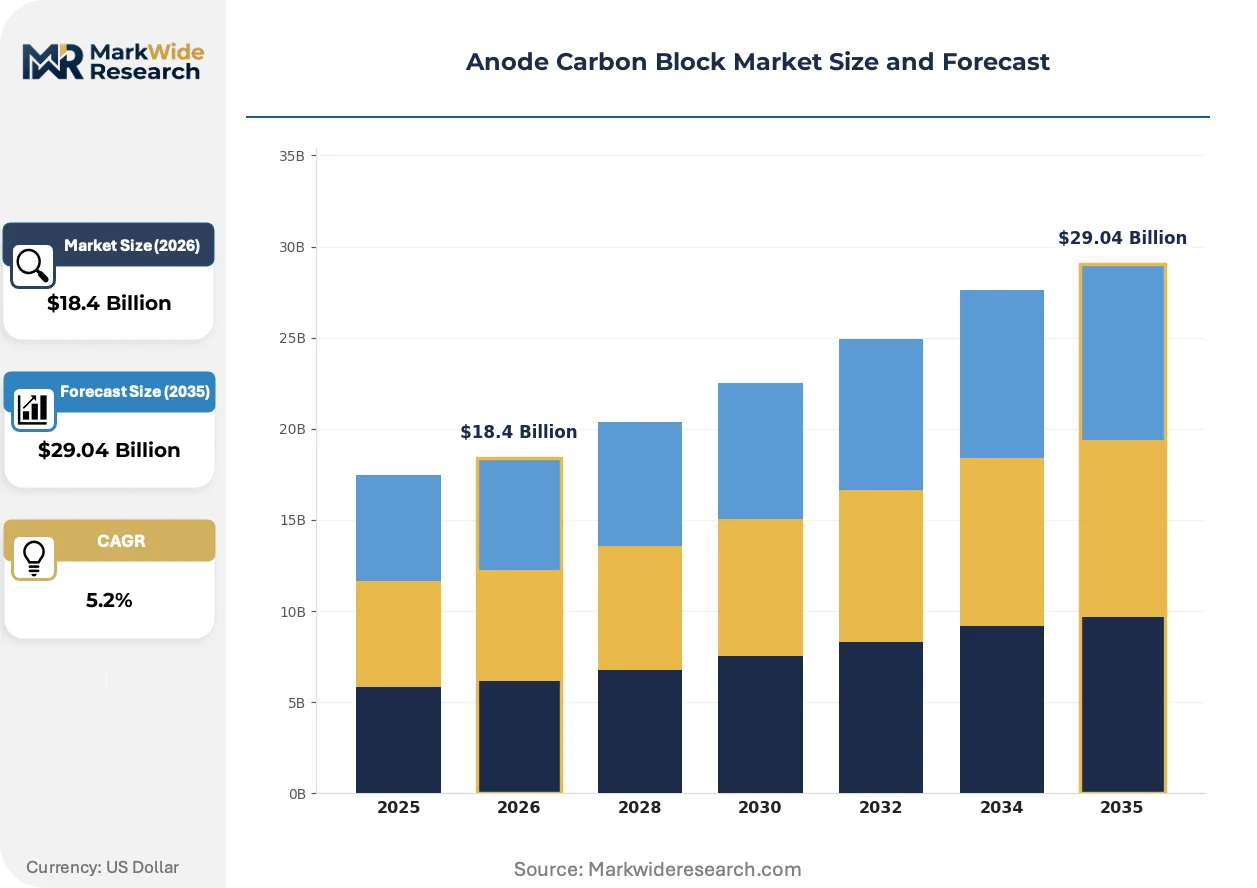
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $29.04 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphite Carbon Block, Carbon Composite, Resin Bonded Carbon, Silicon Impregnated Carbon, Phenolic Impregnated Carbon Technology: Isostatic Pressing, Vibro-Pressing, Extrusion, Compression Molding, Pouring Application: Electrolytic Production, Aluminum Smelting, Electric Arc Furnaces, Lubrication, Chemical Processing End User: Metal Manufacturing, Glass Fabrication, Foundries, Power Generation, Aerospace |
| Companies Covered | SGL Carbon, Tokai Carbon, Mersen, Graphtek, Schunk, TOYO TANSO, Nippon Carbon, Jining Carbon, Fangrui, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anode Carbon Block Market Trends and Innovations
Active transformation in anode carbon block manufacturing centers on densification technologies, regulatory chemistry reformulation, and procurement model restructuring. These intersecting developments are compressing legacy supply relationships and elevating technical performance requirements.
Isostatic pressing technology is displacing conventional vibro-pressing in premium aluminum smelting applications. Smelters in the Middle East and China specify these blocks for their uniform density distribution and superior dimensional stability under thermal cycling. The shift is compressing margins for extrusion-based producers serving cost-sensitive foundry segments.
REACH framework restrictions on polycyclic aromatic hydrocarbon content in coal tar pitch binders are forcing reformulation across European supply chains. ECHA enforcement has eliminated certain conventional binder chemistries, compelling suppliers to qualify alternative formulations without compromising electrical resistivity below 55 μΩ·m. German and French smelters now require supplier certification under updated PAH limits before contract renewal.
Long-term offtake agreements with embedded performance guarantees are displacing spot-market purchasing among major primary aluminum producers. Smelters in the GCC region contract directly with integrated carbon suppliers for multi-year supply security. This behavioral shift concentrates volume with vertically integrated players capable of needle coke captive supply.
Anode Carbon Block Market Segmentation
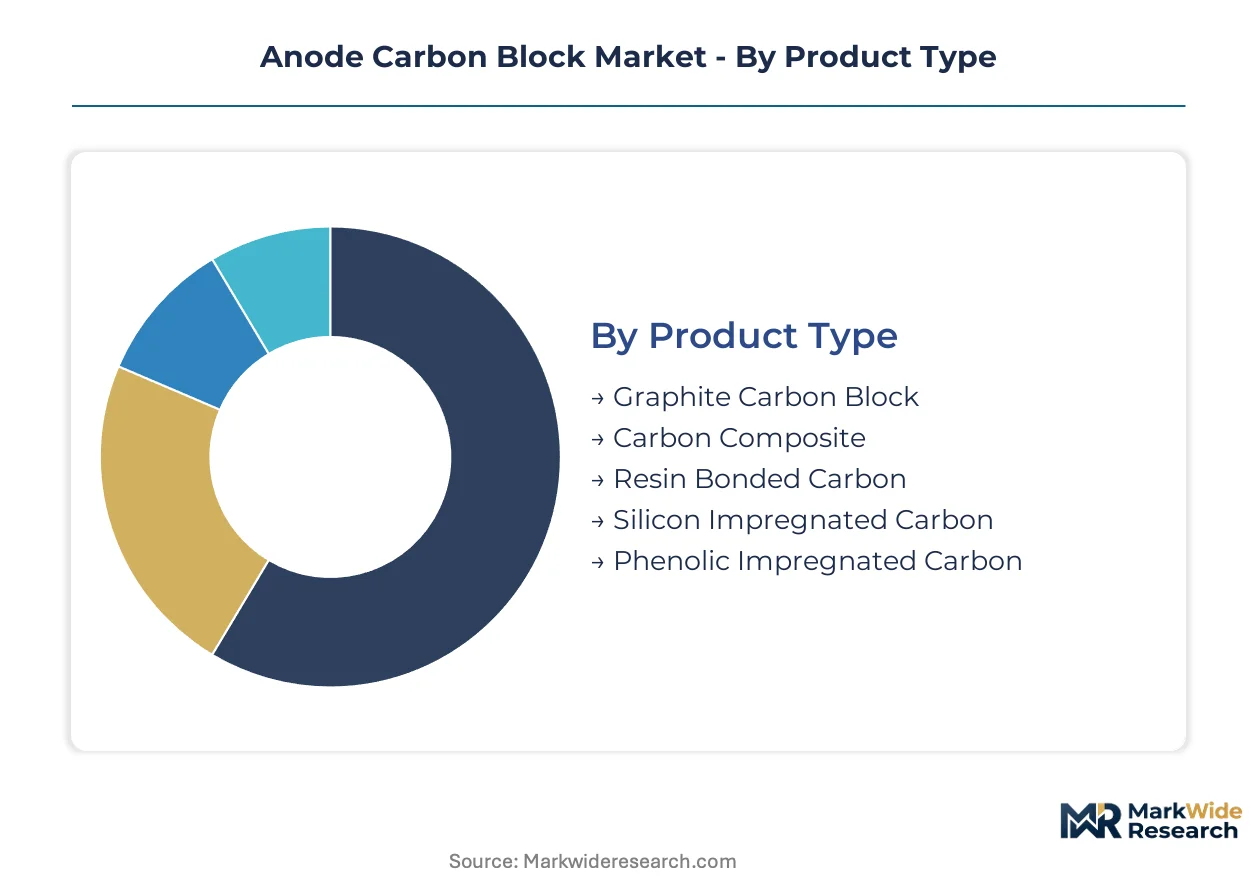
Anode carbon block procurement patterns diverge sharply across product grades and forming technologies, with regulatory thresholds on emission intensity and thermal performance dictating specification choices. Smelters now segment suppliers by their ability to certify electrical resistivity and dimensional stability under electrolytic cell operating conditions.
Product Type:
REACH restrictions on polycyclic aromatic hydrocarbon content in coal tar pitch binders create divergent compliance pathways across material formulations, favoring segments with alternative impregnation chemistries.
- Graphite Carbon Block:Manufactured from calcined petroleum coke with coal tar pitch binder, these blocks achieve electrical resistivity below 55 μΩ·m and dimensional stability under thermal cycling. Primary aluminum smelters in Saudi Arabia and the UAE specify these grades for new potline investments, with MEE emission benchmarks in China accelerating replacement cycles for legacy installations.
- Carbon Composite:Hybrid structures combining carbonaceous matrices with reinforcing phases deliver enhanced thermal shock resistance for extended pot lining life. Demand concentrates in European smelter networks where ECHA enforcement of updated PAH limits has eliminated certain conventional binder qualifications.
- Resin Bonded Carbon:Synthetic resin binders replace coal tar pitch for applications requiring reduced volatile organic compound emissions during baking.
- Silicon Impregnated Carbon:Liquid silicon infiltration creates ceramic-carbon composites with superior oxidation resistance for specialty chemical processing environments.
- Phenolic Impregnated Carbon:Thermoset phenolic resins provide carbon yield and structural integrity without aromatic hydrocarbon content concerns.
Graphite carbon blocks handle the majority of throughput; carbon composite is expanding most quickly on share as thermal performance requirements tighten.
Technology:
Capital intensity and lead times for production equipment create stark cost tier differentiation between premium forming methods and conventional alternatives.
- Isostatic Pressing:Uniform density distribution through omnidirectional pressure application yields premium-grade blocks with consistent electrical properties. Middle Eastern smelter investments specify these products exclusively, with equipment lead times exceeding 18 months constraining supply expansion.
- Vibro-Pressing:Directional vibration compaction achieves adequate density for standard aluminum smelting grades at lower capital cost. Chinese smelters facing MEE emission intensity targets increasingly specify higher-density vibro-pressed products as intermediate compliance solutions.
- Extrusion:Continuous forming suits cost-sensitive foundry applications where dimensional tolerances are less critical.
- Compression Molding:Batch processing for specialty geometries and small-series chemical processing components.
- Pouring:Cast carbon techniques for complex shapes unsuited to mechanical forming methods.
Isostatic pressing commands the margin premium; vibro-pressing delivers the volume base across installed smelter capacity.
Application:
End-use thermal and electrical performance requirements segment demand by operational severity and replacement frequency.
- Electrolytic Production:Hall-Héroult cell anodes require precise electrical resistivity and consumption rates to maintain metal purity and energy efficiency. China's dual carbon goals enforced by MEE are forcing specification upgrades across existing potlines.
- Aluminum Smelting:Prebaked anode systems dominate primary metal production, with pot lining protection driving demand for dimensional stability under thermal cycling.
- Electric Arc Furnaces:High-temperature electrode applications in steel recycling operations.
- Lubrication:Solid lubricant formulations exploiting carbon's low friction coefficient.
- Chemical Processing:Thermal shock resistance for reactor linings and heat exchanger components.
Electrolytic production absorbs the dominant share of premium-grade output; aluminum smelting maintains the broadest supplier base.
End User:
Customer concentration and procurement scale differentiate segments by contract structure and supply security requirements.
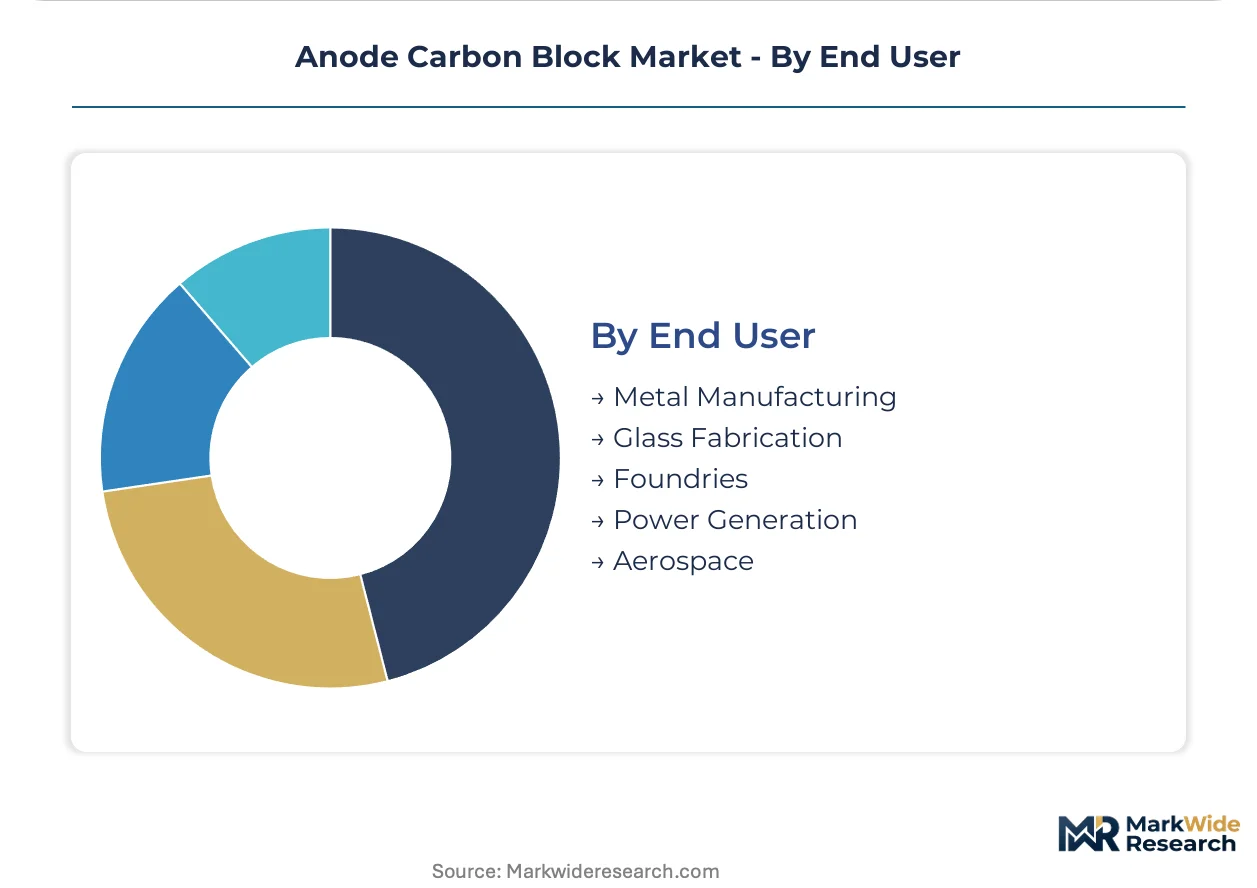
- Metal Manufacturing:Integrated primary aluminum producers consolidate procurement around long-term offtake agreements with needle coke-integrated suppliers. GCC region smelters in Saudi Arabia and the UAE anchor this segment through multi-year supply security contracts.
- Foundries:Secondary aluminum and specialty alloy operations purchase on shorter cycles with greater spot-market participation.
- Glass Fabrication:Melting furnace electrode applications with distinct thermal profile requirements.
- Power Generation:Carbon brush and current collector applications in rotating equipment.
- Aerospace:Specialty carbon-carbon composites for thermal protection systems.
Metal manufacturing concentrates procurement volume; foundries provide the most fragmented demand profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Needle coke refining clusters in China, Japan, and South Korea supply the feedstock backbone for anode carbon block manufacturing, while primary aluminum smelting demand concentrates in China, the Middle East, and select European nodes.
China
MEE emission intensity benchmarks are forcing electrolytic aluminum smelters to specify higher-density anode blocks that reduce per-tonne CO2 output. The dual carbon goals framework tightens compliance deadlines annually. Shandong and Henan provinces host the densest concentrations of carbon block fabricators serving domestic potline upgrades.
Saudi Arabia
New smelter investments in Ras Al-Khair Industrial City require premium anode grades with superior thermal shock resistance for extended pot lining life. Saudi Aramco's downstream integration supports captive needle coke supply security for integrated carbon manufacturers. The Eastern Province anchors Gulf aluminum production capacity expansion through 2030.
United Arab Emirates
Emirates Global Aluminium and Dubal Holding specify isostatic-pressed products exclusively for new potline investments at Jebel Ali and Al Taweelah. MOHAP environmental standards align with EU-equivalent emission disclosure requirements for smelter inputs. Abu Dhabi Industrial City concentrates carbon block procurement coordination for GCC smelter networks.
Germany
ECHA enforcement of updated PAH limits in coal tar pitch binders has eliminated certain conventional formulations, compelling suppliers to qualify alternatives without compromising electrical resistivity. The EU Green Deal carbon border adjustment mechanism incentivizes Scope 3 documentation for anode inputs. North Rhine-Westphalia hosts the densest cluster of specialty carbon engineering talent and pilot production facilities.
Japan
METI industrial decarbonization roadmaps push aluminum smelters toward higher-grade anode specifications that improve energy efficiency per tonne of primary metal. JIS standards for carbon materials maintain stringent dimensional stability requirements under thermal cycling. Osaka and Nagoya industrial corridors concentrate needle coke refining and carbon block export capacity.
Anode Carbon Block Market Competitive Landscape
Concentration sits with integrated carbon suppliers possessing captive needle coke refining capabilities and long-term smelter offtake relationships. The vendor base separates into three tiers: vertically integrated multinationals controlling upstream feedstock, regional specialists with dedicated portside blending infrastructure, and technology-focused players competing on thermal performance specifications. Dominant competitive moves include backward integration into needle coke production and multi-year supply security contracting with primary aluminum producers.
Among German-integrated specialists, SGL Carbon exemplifies the captive refining archetype through controlled needle coke supply streams. Tokai Carbon anchors Japanese supply chain positioning with dedicated infrastructure serving domestic smelter networks. Mersen occupies specialty positioning where thermal shock resistance commands premium tier placement in European chemical processing applications.
| Leading Market Players |
|---|
| SGL Carbon |
| Tokai Carbon |
| Mersen |
| Graphtek |
| Schunk |
| TOYO TANSO |
| Nippon Carbon |
| Jining Carbon |
| Fangrui |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon border adjustment mechanisms gate both supply qualification and price differentiation simultaneously, compelling anode block suppliers to document embedded Scope 3 emissions before smelters will execute premium-tier contracts. Smelters in Germany and the UAE now require verified carbon accounting as a threshold condition for volume allocation, compressing margins for non-compliant producers while elevating pricing power for integrated manufacturers with captive needle coke refining.
Pricing Analysis
REACH restrictions on polycyclic aromatic hydrocarbon content dictate the pricing tier structure across European supply chains, forcing reformulation costs that separate certified premium grades from standard offerings. Three-tier pricing structure across premium, standard, and economy levels reflects electrical resistivity certification, with isostatic-pressed blocks commanding substantial premiums over vibro-pressed alternatives. Cost compression in standard grades is intensifying because Chinese smelters facing MEE emission benchmarks are upgrading specifications faster than supply can adapt. Foundries purchasing extrusion-formed products on spot markets exhibit highest price sensitivity, while GCC smelters contracting multi-year offtake agreements demonstrate lowest sensitivity due to supply security prioritization.
Supply Chain Analysis
Eighteen-month equipment lead times for isostatic presses constrain inventory responsiveness, creating order-book backlogs that extend through smelter procurement cycles. Manufacturing concentrates in China, Japan, and Germany, with needle coke refining anchored in Asian petrochemical corridors. Raw material streams draw from calcined petroleum coke, coal tar pitch binders, and synthetic resin alternatives. Single-source vulnerability sits with Asian needle coke refiners dominating high-quality output. Distribution runs through dedicated portside blending facilities serving regional smelter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anode carbon block market represents high-growth disruption as inert anode technologies threaten demand destruction while regulatory carbon accounting creates premium positioning for compliant suppliers. China's MEE dual carbon goals and EU CBAM implementation together accelerate specification upgrades that favor integrated manufacturers with transparent supply chains.
For Market Incumbents: Consolidate backward integration into needle coke refining to secure feedstock streams against Asian refiner concentration, while expanding isostatic press capacity in the Middle East to capture GCC smelter procurement. Inert anode substitution risk demands accelerated R&D in carbon composite formulations that extend pot lining life and delay technology displacement. For New Entrants and Emerging Players: Green aluminum certification fast-tracks offer entry pathways into European smelter networks where ESG-linked procurement mandates create qualification shortcuts for verified low-carbon suppliers. Target resin-bonded carbon segments where REACH PAH restrictions have eliminated incumbent formulations, leveraging synthetic binder expertise to bypass reformulation barriers that constrain established players. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed carbon specialists possessing European portside infrastructure but lacking captive needle coke supply. Five-to-ten year viability hinges on successful backward integration execution and CBAM compliance system deployment. Watch for MEE enforcement acceleration in Shandong and Henan provinces as the signal indicating Chinese specification upgrade velocity and replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Needle Coke Refining | Captive feedstock supply secures margin protection against Asian refiner price volatility. |
| Isostatic Press Capacity Expansion | Premium-grade output captures GCC smelter demand concentrated in Saudi Arabia and UAE. |
| REACH-Compliant Binder Reformulation | Alternative chemistry qualifications unlock contract renewals across German and French smelter networks. |
| Long-Term Offtake Agreements with Performance Guarantees | Outcome-based contracts linking block quality to potline metrics displace spot-market purchasing. |
| Scope 3 Carbon Accounting System Deployment | Embedded emission documentation satisfies EU CBAM requirements for premium-tier positioning. |
Research Methodology
A spread of perspectives from primary aluminum smelter procurement directors, carbon block plant managers, needle coke refinery technical leads, and ESG compliance officers converged on the working assumptions shaping this analysis. Primary field engagement combined with secondary validation from customs trade data, SEC filings of listed carbon manufacturers, MEE enforcement bulletins, and ECHA regulatory updates. Bottom-up volume builds from smelter capacity and replacement frequency triangulated against top-down market value estimates derived from contract pricing disclosures.
Segmentation dimensions modeled span product grade, forming technology, end-use application, and regional regulatory framework across the analysis window. CAGRs were computed from historical trajectory analysis and forward-looking capacity-expansion schedules. Forecast inputs incorporate MEE emission intensity benchmark tightening schedules, GCC smelter investment pipelines, and REACH PAH limit enforcement timelines.
Underlying assumptions cover sustained aluminum demand growth, continued Hall-Héroult process dominance, and regulatory enforcement consistency, with deviation risk concentrated in inert anode technology commercialization acceleration and needle coke supply disruption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Stainless Steel Cable Ties Market
Industrial Materials
Global Medical Plastics Extrusion Market
Industrial Materials
Wood Protein Market
Industrial Materials
Global Industrial Chain Market
Industrial Materials
Silica Fume Market
Industrial Materials
Industrial Continuous Furnaces Market
Industrial Materials
Pultrusion Products Market
Industrial Materials
Global Cenospheres Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
Wire Hoods Market
Industrial Materials
UHP Graphite Electrode Market
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
Natural Industrial Absorbents Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
Global Cast Acrylic Sheet Market
Industrial Materials
Polymer Bearing Market