
 North America Industrial Fasteners Market | 2026-2036
North America Industrial Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Fasteners Market Analytics
A widening capital-intensity gap between integrated manufacturers and distributors is redrawing competitive boundaries in the North America industrial fasteners landscape. Fastenal Company leverages its branch-based inventory network to sustain same-day fulfillment dominance across construction and maintenance channels. Illinois Tool Works Inc. anchors its position through proprietary engineered fastening systems that command specification control at OEM design stages.
Industrial fasteners are mechanical joining devices—typically threaded bolts, nuts, screws, and washers manufactured to precise tensile strength, shear resistance, and corrosion specifications—that create clamping force between discrete components in assembled products and structures. Steel-grade fasteners dominate volume throughput due to cost efficiency in automotive and construction applications, though aluminum variants are gaining specification share in aerospace weight-reduction programs. The permanent installation category captures the deepest margin pools through safety-critical applications where failure carries catastrophic liability, while removable fasteners compete primarily on logistics velocity and inventory turnover metrics.
The Federal Aviation Administration enforces material certification and lot traceability standards that elevate qualification barriers for aerospace fastener suppliers, while OSHA construction safety regulations mandate specified torque ratings and inspection protocols that shape procurement specifications across commercial building projects. The EPA's evolving restrictions on hexavalent chromium plating processes are accelerating supplier transitions to zinc-nickel and other alternative corrosion-protection coatings. Stakeholders must monitor how NHTSA vehicle lightweighting mandates and evolving crashworthiness standards redirect fastener material specifications toward high-strength aluminum and titanium alloys in automotive platforms.
Market Dynamics
Aerospace OEMs in the US and Canada are accelerating fastener procurement for next-generation airframe programs, while the FAA tightens material traceability mandates that reshape supplier qualification requirements across the North American supply base.
Growth Catalysts
- Aerospace OEM expansion:Boeing and Airbus suppliers in Washington state and Quebec are scaling titanium fastener orders for single-aisle and widebody production ramps. Airframers specify lot-traceable material for every critical joint.
- OSHA construction mandates:Commercial building codes in Texas and Florida now require torque-verified structural fasteners with documented inspection protocols. General contractors face liability exposure from fastener failure in high-rise projects.
- Gulf Coast petrochemical investment:Louisiana and Texas are attracting over $15 billion in refinery and LNG export capacity expansion. Corrosion-resistant alloy fasteners for pressure vessels and piping systems command specification priority in these builds.
Market Restraints
- Steel scrap volatility:Cold-heading quality wire rod prices fluctuate with electric arc furnace input costs. Fastener manufacturers in the Midwest lack long-term hedging instruments for their primary feedstock.
- Canadian supply concentration:Quebec hosts three specialized aerospace fastener forges supplying 60% of North American titanium airframe hardware. Any disruption to these facilities propagates through Boeing and Airbus final assembly lines.
- Hexavalent chromium phase-out:EPA restrictions on cadmium and hex-chrome plating force coating line conversions. Zinc-nickel alternatives require salt-spray requalification cycles that delay customer approvals.
Strategic Opportunities
- Mexican nearshoring corridors:Queretaro and Nuevo Leon are attracting Tier-2 automotive fastener plants serving US assembly operations. Labor arbitrage and USMCA tariff advantages support 15-20% landed cost reductions versus Asian imports.
- EV battery enclosure standards:NHTSA crashworthiness rules for electric vehicles specify high-strength aluminum fasteners in battery tray assemblies. This application category was negligible five years ago.
- Additive manufacturing qualification:Laser powder bed fusion is producing titanium aerospace brackets with integral fastener features. FAA certification pathways for printed structural hardware are clarifying through AM-specific advisory circulars.
Industry Challenges
- Heat treat technician shortage:Aerospace fastener suppliers in California and Arizona cannot staff vacuum furnace operations. Specialized metallurgical expertise for titanium solution treating has aged out of the workforce without pipeline replacement.
- AS9100D audit backlogs:Certification body capacity constraints delay supplier requalification timelines. OEMs cannot onboard new fastener sources without current aerospace quality system credentials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Fasteners Market |
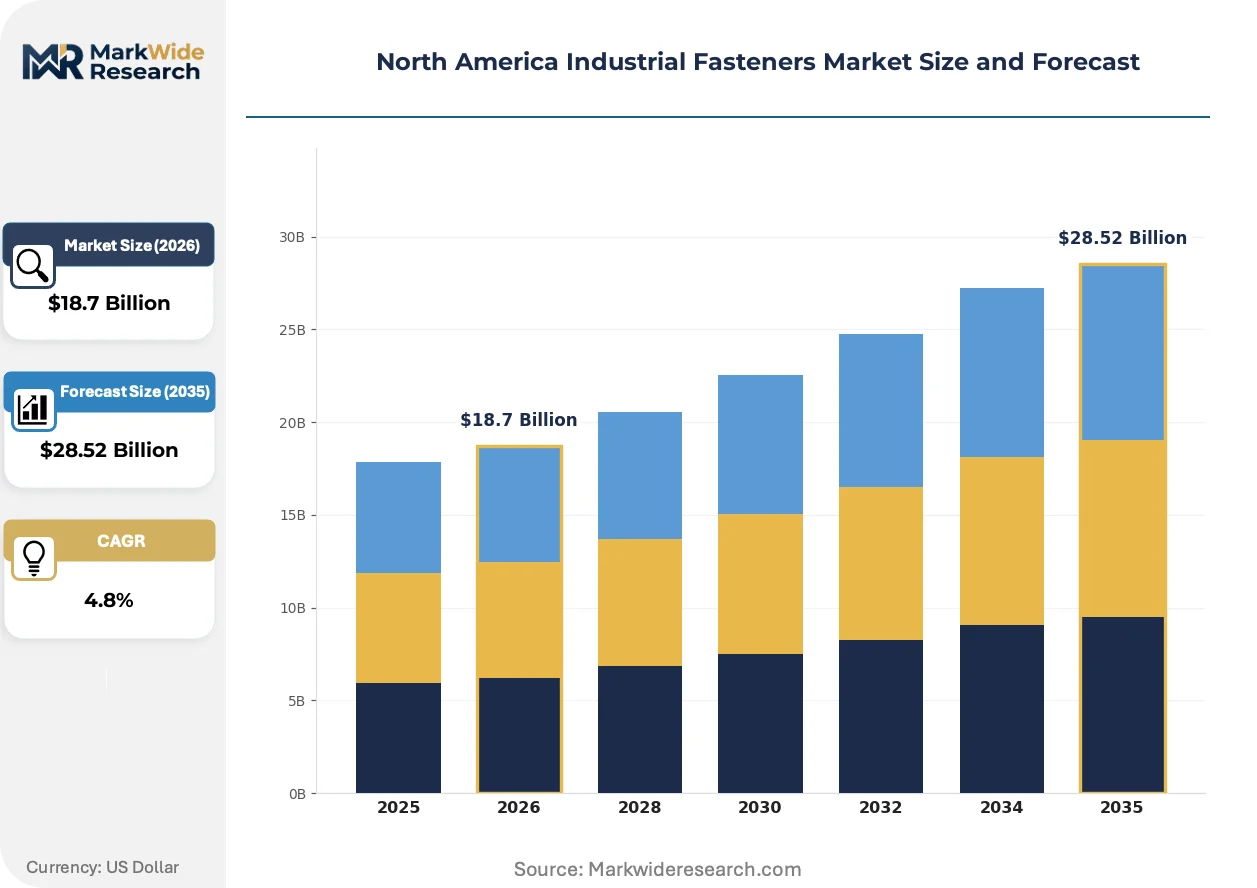
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bolts, Nuts, Screws, Washers Material: Steel, Aluminum, Brass, Plastic Application: Aerospace, Automotive, Construction, Electronics Installation Type: Permanent, Removable, Semi-permanent, Through-hole |
| Companies Covered | Fastenal Company, Acument Global Technologies, Inc., Illinois Tool Works Inc., SFS Group AG, LISI Group, Stanley Black and Decker, Inc., Howmet Aerospace Inc., Bulten AB, Würth Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Fasteners Market Evolving Landscape
Digital thread technologies and advanced coating chemistries are restructuring how North American fastener suppliers demonstrate compliance, while procurement organizations demand real-time material genealogy rather than batch certificates.
Smart fastener systems embedding RFID tags and strain sensors are fragmenting traditional hardware categories. Boeing 787 and Airbus A350 maintenance programs now specify intelligent joints for critical wing-to-fuselage attachments. These devices enable continuous structural health monitoring, compressing the addressable market for conventional inspection-dependent hardware in safety-critical applications.
EPA enforcement of hexavalent chromium restrictions under the Clean Air Act is forcing coating line conversions across Ohio and Indiana fastener plants. Zinc-nickel and trivalent chrome alternatives require 1,000-hour salt-spray requalification. Aerospace suppliers in Connecticut and Kansas are most affected, as military specifications lag commercial aviation in accepting substitute finishes.
Consolidation among US automotive OEMs is compressing fastener supplier bases from hundreds to dozens of approved sources. Stellantis and Ford now mandate single-source accountability for entire vehicle platform fastener kits. Tier-1 distributors in Michigan and Ontario are responding by acquiring regional bolt manufacturers to secure captive forging capacity and maintain procurement access.
North America Industrial Fasteners Market Segmentation
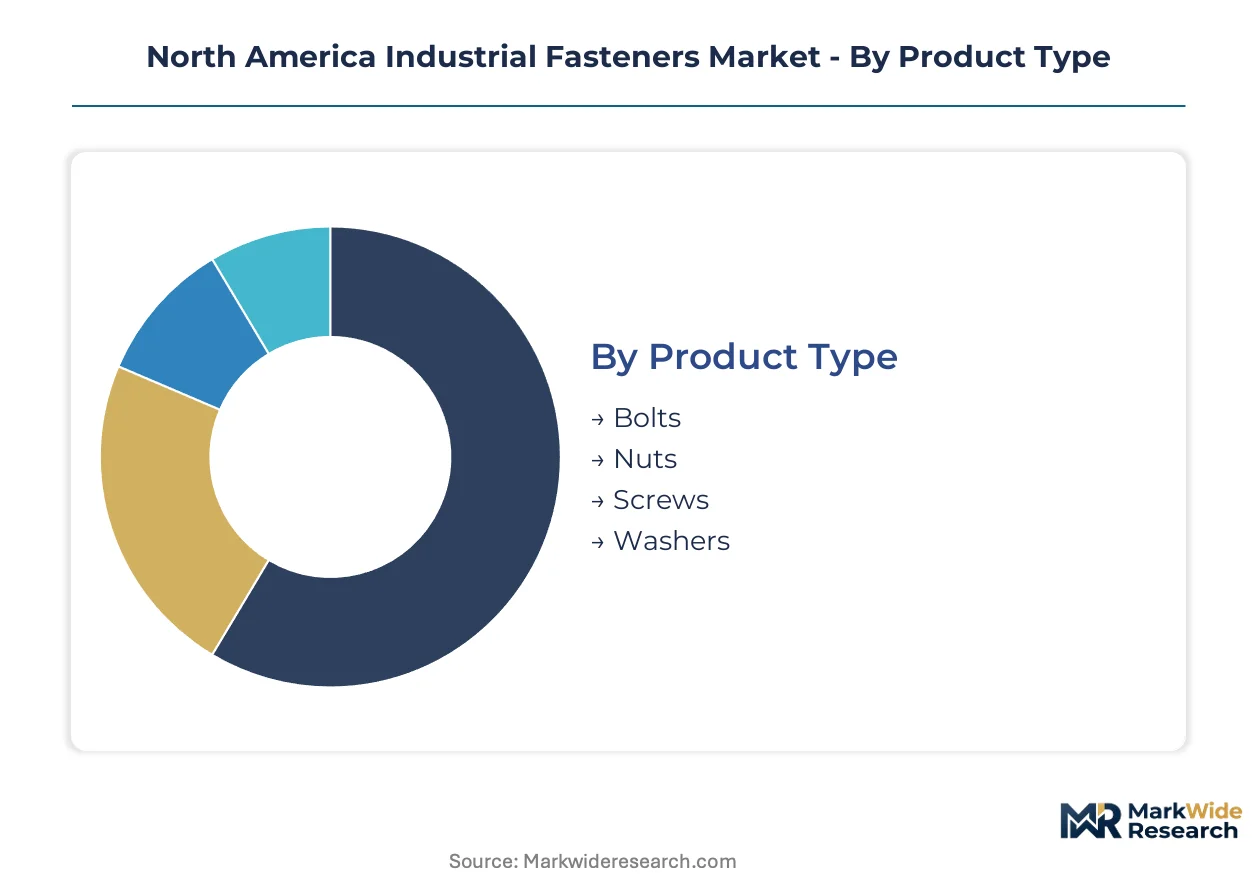
Industrial fastener procurement in North America splits across four structural dimensions that determine channel economics. Product geometry and material specification dictate whether orders flow through distributor stock programs or direct OEM supply agreements.
Product Type:
Bolts and screws move through divergent fulfillment channels based on specification complexity and lot-size economics.
- Bolts:Hex-head and socket-head configurations rated to ASTM A325 and A490 standards dominate structural steel construction. Demand concentrates in Texas and Louisiana petrochemical builds where torque-controlled tensioning is mandatory for pressure-boundary joints.
- Screws:Thread-forming and thread-cutting variants span machine, wood, and self-drilling categories. Electronics assembly in Mexico's Baja California and Guanajuato corridors is absorbing precision miniature screws for device enclosure fastening.
- Nuts:Hex nuts, lock nuts, and flange nuts provide clamping force mating surfaces across all assembly categories.
- Washers:Flat, lock, and structural washers distribute bolt load and prevent loosening under vibration.
Bolts dominate installed base tonnage. Screws are where expansion concentrates in precision assembly applications.
Material:
Raw material selection determines corrosion performance, weight targets, and qualification burden across end-use specifications.
- Steel:Cold-heading quality grades 1018 through 1541 deliver tensile strengths from 60,000 to 150,000 psi at lowest unit cost. Automotive chassis and commercial construction in the US Midwest and Ontario consume volume through mill-direct and distributor-stocked programs.
- Aluminum:2024-T4 and 7075-T6 aerospace grades offer strength-to-weight ratios critical for Boeing and Airbus single-aisle programs. FAA material traceability mandates require lot-controlled sourcing from Quebec and California forges.
- Brass:Copper-zinc alloys provide corrosion resistance and electrical conductivity for marine and electrical applications.
- Plastic:Nylon 6/6 and PEEK polymers serve electronics and chemical processing where galvanic isolation or chemical inertness is required.
Steel commands volume throughput. Aluminum is climbing the fastest on aerospace specification share gains.
Application:
End-use sector requirements fragment procurement patterns across safety-critical, cost-optimized, and logistics-velocity channels.
- Aerospace:Titanium and superalloy fasteners for wing-to-fuselage and engine pylon attachments carry AS9100D quality system mandates. Boeing suppliers in Washington state and Airbus partners in Quebec maintain dedicated fastener inventories with full material genealogy documentation.
- Automotive:High-volume stamped and rolled fasteners for body-in-white and powertrain assembly compete on hundredths-of-a-cent piece pricing. Stellantis and Ford platform consolidation is compressing approved supplier lists to single-source kit providers.
- Construction:Structural bolting for commercial and infrastructure projects follows AISC and RCSC specifications with torque-verified installation protocols.
- Electronics:Miniature precision fasteners for PCB mounting and enclosure assembly serve consumer device and industrial control markets.
Construction anchors installed base value. Aerospace is where margin expansion concentrates through specification control.
Installation Type:
Joint permanence determines aftermarket serviceability and liability exposure in procurement specifications.
- Permanent:Rivets, lockbolts, and swaged collars create joints requiring drilling for disassembly. Gulf Coast refinery and LNG construction specifies these for pressure-vessel applications where fastener loosening carries catastrophic failure risk.
- Removable:Standard threaded fasteners enable maintenance access and component replacement. Fleet vehicle service operations in Michigan and Ohio demand removable hardware with documented torque specifications for warranty compliance.
- Semi-permanent:Thread-locking adhesives and prevailing torque nuts resist loosening while permitting intentional removal.
- Through-hole:Fasteners passing completely through joined members with nut retention on the opposite side.
Removable hardware dominates unit volume. Permanent installation is where specification premiums concentrate in safety-critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the US Gulf Coast corridor where petrochemical construction absorbs premium alloy fasteners, while Canadian aerospace suppliers command specification premiums through Boeing and Airbus qualification locks.
United States
Texas and Louisiana host $15 billion in refinery and LNG export capacity expansion, driving demand for corrosion-resistant alloy fasteners in pressure-vessel applications. OSHA mandates torque-verified structural fasteners with documented inspection protocols for high-rise commercial projects in Florida and California. Washington state aerospace clusters supply Boeing with titanium lot-traceable hardware under FAA material genealogy requirements.
Canada
Quebec hosts three specialized aerospace fastener forges supplying 60% of North American titanium airframe hardware for single-aisle and widebody programs. Transport Canada aligns with FAA airworthiness directives on material traceability, tightening supplier qualification barriers. Ontario automotive stamping operations in Windsor and Oshawa consume high-volume steel fasteners for Stellantis and Ford platform assembly.
Mexico
Queretaro and Nuevo Leon attract Tier-2 automotive fastener plants serving US assembly operations through USMCA tariff advantages. The Secretariat of Economy's manufacturing promotion programs accelerate precision component investment in Baja California electronics corridors. Guanajuato's industrial parks absorb miniature screw demand from consumer device enclosure assembly.
North America Industrial Fasteners Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American industrial fasteners landscape. Integrated manufacturers with captive forging and heat-treat capabilities capture specification control at OEM design stages, while branch-network distributors compete on logistics velocity and same-day fulfillment density. The market structure tilts toward tiered consolidation with three strategic archetypes: specification-locked aerospace specialists, scale-driven automotive suppliers, and inventory-intensive maintenance distributors. Dominant competitive moves include M&A to secure captive forging capacity and strategic partnerships to bypass AS9100D audit backlogs.
Among US-based distributors, Fastenal Company exemplifies the branch-network archetype with construction and maintenance channel dominance. Illinois Tool Works Inc. anchors the engineered systems tier through proprietary fastening specifications at OEM design stages. Howmet Aerospace Inc. occupies a position within the aerospace specialist cluster serving Boeing and Airbus qualification requirements.
| Leading Market Players |
|---|
| Fastenal Company |
| Acument Global Technologies, Inc. |
| Illinois Tool Works Inc. |
| SFS Group AG |
| LISI Group |
| Stanley Black and Decker, Inc. |
| Howmet Aerospace Inc. |
| Bulten AB |
| Würth Group |
| Others |
Value Network & Pricing Analysis
Ninety-day lead times for lot-traceable titanium aerospace fasteners concentrate pricing power with Quebec and Washington state forges, while standard-grade construction bolts compete on logistics velocity through distributor branch networks. This supply-chain geometry elevates specification-controlled premiums in safety-critical applications while compressing margins in commodity construction channels.
Pricing Analysis
Configured-to-order aerospace fasteners command 3-5x premiums over standard catalog equivalents, with Boeing and Airbus qualification locks sustaining price insulation. Price differentiation rests on AS9100D certification tier and material genealogy documentation depth. Cost compression in automotive stamped fasteners is intensifying because Stellantis and Ford platform consolidation squeezes hundredths-of-a-cent piece economics. Fleet maintenance buyers exhibit highest price sensitivity; aerospace OEM procurement teams prioritize failure-risk mitigation over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive and electronics assembly, while Gulf Coast petrochemical construction demands strategic stockpiles of corrosion-resistant alloy fasteners. Supply concentrates in the United States, Canada, and Mexico through USMCA-integrated manufacturing corridors. Raw material dependencies center on cold-heading quality wire rod, titanium sponge, and zinc-nickel plating chemistries. Single-source vulnerability pervades Quebec aerospace forges supplying 60% of North American titanium airframe hardware. Distribution runs through three-tier structures: mill-direct for high-volume automotive, branch-network distributors for construction maintenance, and dedicated OEM supply agreements for aerospace.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against additive manufacturing and smart fastener systems that displace conventional hardware in structural health monitoring applications.
For Market Incumbents: Fortify specification control at OEM design stages through proprietary engineered fastening systems that embed switching costs. Secure captive forging capacity in Mexican nearshoring corridors to defend automotive platform access against Asian import competition. Prioritize AS9100D certification maintenance to bypass audit backlog bottlenecks that delay competitor qualification.
For New Entrants and Emerging Players: Anchor in EV battery enclosure fastening where NHTSA crashworthiness rules specify high-strength aluminum hardware absent entrenched supplier relationships. Target Queretaro and Nuevo Leon automotive corridors for Tier-2 plant establishment with USMCA tariff positioning. Pursue zinc-nickel coating specialization to capture EPA-driven hexavalent chromium replacement demand.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because aerospace qualification locks and automotive platform consolidation favor scale-driven survivors over fragmented regional suppliers. Target mid-cap distributors with captive forging capacity and established OEM procurement access. Watch FAA additive manufacturing certification pathways as inflection signal for printed structural hardware displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging Capacity | Captive heat-treat operations secure titanium solution treating expertise aging out of California and Arizona workforce pools. |
| Mexican Manufacturing Footprint Expansion | Queretaro and Nuevo Leon plants exploit USMCA tariff advantages for 15-20% landed cost reductions versus Asian imports. |
| Alternative Coating Chemistry Transition | Zinc-nickel plating line conversions address EPA hexavalent chromium restrictions while awaiting military specification acceptance. |
| AS9100D Certification Fast-Track | Bypassing audit backlogs accelerates supplier onboarding for Boeing and Airbus next-generation airframe programs. |
| Smart Fastener Technology Partnership | RFID-embedded and strain-sensor systems capture Boeing 787 and Airbus A350 maintenance program specifications. |
Research Methodology
Desk research of aerospace material certification databases, customs trade flow records, and SEC supplier filing disclosures preceded structured interviews with fastener procurement managers at Tier-1 automotive suppliers, aerospace quality directors, construction general contractors, and distributor branch operations heads. Primary fieldwork captured specification control dynamics, inventory velocity benchmarks, and qualification timeline constraints. Secondary validation drew from FAA airworthiness directive archives, OSHA construction safety enforcement data, and EPA plating process restriction notices. Bottom-up segment sizing triangulated against top-down end-use consumption estimates.
Variance decomposition across product type, material specification, application sector, and installation permanence shaped volume and value outputs over the projection horizon. CAGRs derived from elasticity-adjusted demand modeling against petrochemical construction capex cycles, aerospace production ramp schedules, and automotive platform consolidation trajectories. Industry-specific inputs included electric vehicle battery enclosure fastener content per vehicle, titanium fastener intensity per airframe, and corrosion-resistant alloy specification share in Gulf Coast pressure-vessel applications.
Decision-makers should treat outputs as directional under assumptions of sustained USMCA trade integration, continued FAA material traceability enforcement, and stable electric vehicle penetration trajectories; material deviation would warrant model refresh. Revision becomes warranted when additive manufacturing certification pathways accelerate or Quebec aerospace forge disruption propagates through Boeing and Airbus final assembly lines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Plastic Molds Market
Industrial Materials
Portable Magnetizer Market
Industrial Materials
Stainless Steel Cable Ties Market
Industrial Materials
Industrial Absorbents Market
Industrial Materials
Metal Based Safety Gratings Market
Industrial Materials
Global Melamine Faced Chipboard (MFC) Market
Industrial Materials
Conveyor Belt Materials Market
Industrial Materials
Global Medical Plastics Extrusion Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
United States Engineering Plastics Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
GCC Welding Consumables Market
Industrial Materials
Encapsulated Gaskets/Seals Market
Industrial Materials
Heat-Insulation Boards for Industrial Equipment Market
Industrial Materials
Diamond Wire Market