
 Paper Coating Binders Market | 2026-2036
Paper Coating Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Coating Binders Market Outlook
The EU Green Deal is rebalancing procurement criteria across European paper mills toward low-VOC coating systems. BASF SE leverages its integrated acrylic acid chain to supply water-based styrene-acrylic binders at scale. Dow anchors its position through direct partnerships with North American coated paper manufacturers. Kemira Oyj specializes in bio-based alternatives that align with Nordic pulp industry sustainability targets.
Paper coating binders are film-forming polymers, typically acrylic or styrene-acrylic emulsions with particle sizes of 100-300 nanometers, applied to paper substrates to improve surface strength, printability, and gloss. These binders function by filling interstices between pigment particles and anchoring them to the cellulose fiber matrix. Styrene-acrylic formulations command the largest volume share due to their cost-performance balance in high-speed coating operations. Water-based systems are displacing solvent alternatives as mills retrofit drying infrastructure to comply with emissions rules. Polyurethane binders occupy the premium tier where extreme durability or specialized barrier properties justify higher raw material costs.
EPA regulations on hazardous air pollutants from coating operations constrain solvent-based formulation sales in the United States. ECHA's REACH restrictions on styrene monomer residuals are forcing reformulation investments across European supply chains. China's MEE standards on industrial wastewater are pushing domestic mills toward cleaner binder chemistries. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation assets and misaligned R&D spending.
Market Dynamics
The paper coating binders sector faces a structural pivot as water-based acrylic systems displace solvent formulations under tightening emissions regimes across major manufacturing jurisdictions.
Growth Catalysts
- REACH reformulation mandates:ECHA's restrictions on styrene residuals are compelling European mills to accelerate water-based binder adoption, creating sustained demand for compliant acrylic emulsions.
- Packaging sector pull:Brand owners in food and beverage applications are specifying recyclable paperboard substrates that require high-performance coating binders for print durability.
- China's MEE wastewater standards:Domestic paper mills are retrofitting coating lines to meet stricter effluent limits, directly stimulating cleaner binder chemistry procurement.
Market Restraints
- Acrylic acid feedstock volatility:Propylene price swings transmit directly to styrene-acrylic binder production costs, compressing formulation margins.
- Specialized polyurethane supply concentration:Premium barrier-grade binders depend on concentrated isocyanate suppliers in Germany and the United States, exposing buyers to allocation risk.
- Drying infrastructure retrofit costs:Mills running solvent-based lines face capital-intensive oven modifications to handle water-based systems' higher thermal energy requirements.
Strategic Opportunities
- India's underpenetrated coated paper segment:Domestic packaging growth and BIS quality standards are creating first-mover openings for water-based binder suppliers establishing local technical service.
- Bio-based binder convergence:Kemira's bio-acrylic development path demonstrates viable routes to combine renewable feedstocks with existing emulsion polymerization infrastructure.
- EU Green Deal procurement criteria:European public sector paper purchasing is weighting lifecycle emissions, advantaging low-VOC coating systems in tender evaluations.
Industry Challenges
- Emulsion polymerization expertise scarcity:Formulation chemists with particle size control and stability optimization skills are concentrated at established suppliers, constraining new entrant scale-up.
- Multi-jurisdiction compliance synchronization:Divergent EPA, ECHA, and MEE timelines for residual monomer limits force parallel formulation tracks and duplicated testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Coating Binders Market |
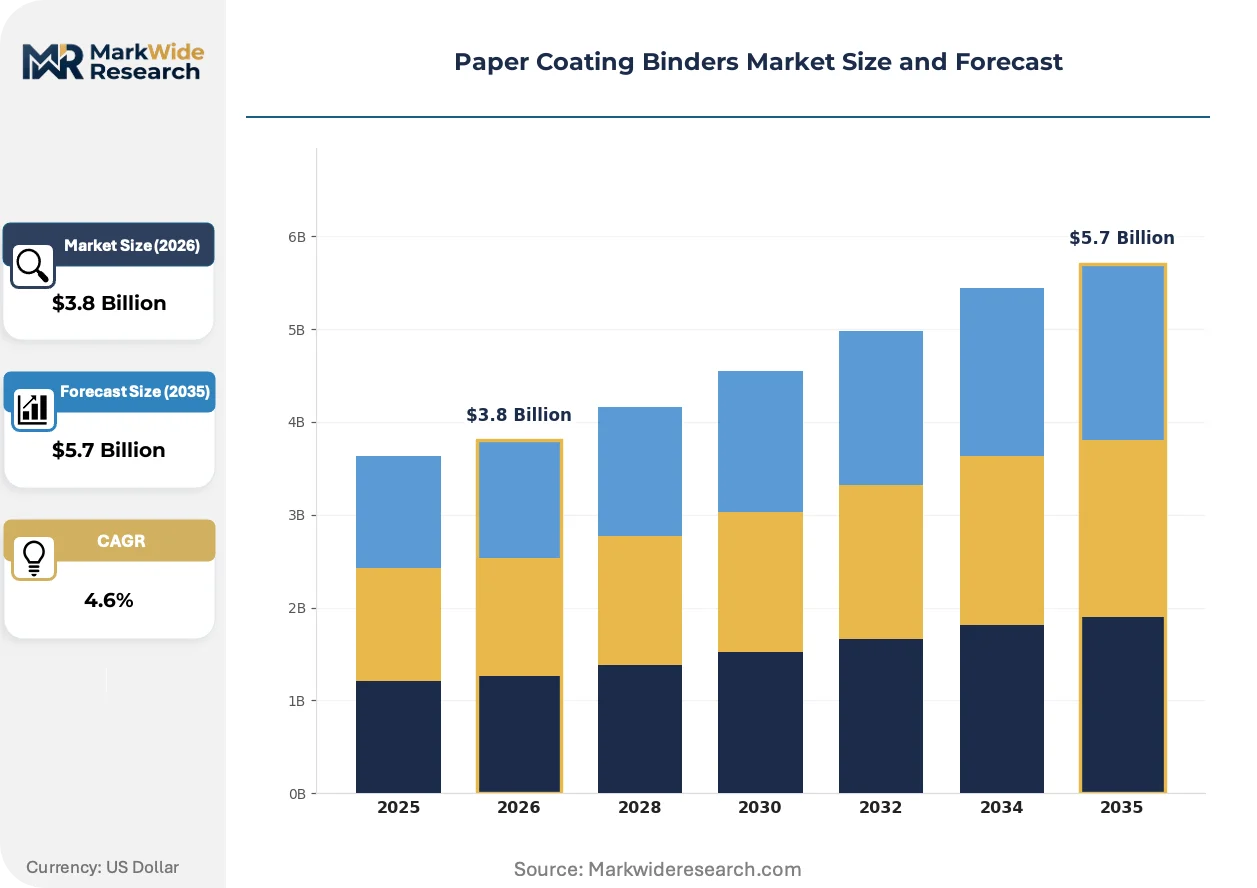
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Styrene-Acrylic, Polyvinyl Acetate, Polyurethane End Use Industry: Printing, Packaging, Stationery, Labeling Formulation Type: Water-Based, Solvent-Based, Hot-Melt, Powder Functionality: Adhesive, Coating Agent, Binder, Emulsifier |
| Companies Covered | Wacker Chemie, Trinseo, BASF SE, DIC Corporation, Arkema, Dow, Celanese Corporation, Kemira Oyj, Synthomer Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Coating Binders Market Strategic Shifts
Reformulation pressures and substrate diversification are compressing product development cycles while expanding performance specifications beyond traditional printability metrics.
Hybrid acrylic-styrene emulsions with engineered particle morphology are unifying gloss control and binding strength in single-binder architectures. Food-contact board manufacturers are adopting these systems to reduce coating weight while maintaining heat-seal integrity. This unification is compressing the traditional trade-off between surface aesthetics and fiber anchoring that previously required multi-binder blends.
EPA hazardous air pollutant rules for coating operations are forcing solvent-based capacity closures in the United States. Paper mills in Wisconsin and the Carolinas are accelerating water-based line conversions to avoid enforcement exposure. The flexographic and gravure packaging segments are absorbing the highest compliance costs as they migrate drying infrastructure.
Brand-owner sustainability scorecards are embedding coating chemistry disclosure requirements into supplier qualification. Major consumer goods companies are auditing paper packaging vendors for VOC content and renewable feedstock share. This behavioral shift is most pronounced in European and North American fast-moving consumer goods supply chains where packaging represents visible ESG commitment.
Paper Coating Binders Market Segmentation
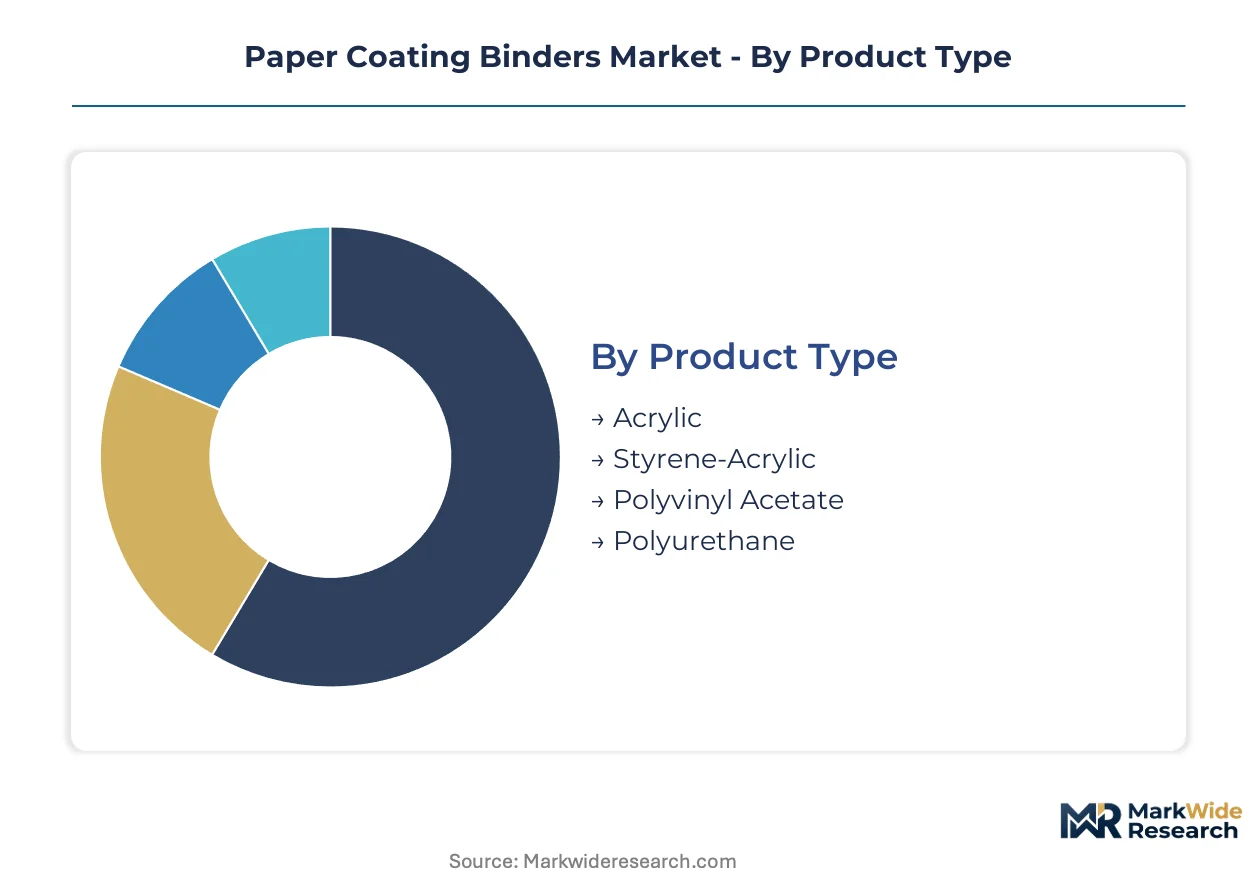
Paper coating binders segment across polymer chemistry, application requirements, and regulatory compliance profiles. Each axis shapes procurement decisions, formulation investments, and supplier positioning in distinct ways.
Product Type:
Polymer architecture determines film-forming characteristics, thermal stability, and compatibility with coating line speeds.
- Styrene-Acrylic:Cost-optimized copolymers balance gloss development with fiber anchoring at high coating speeds. European mills favor these formulations for magazine and catalog papers under ECHA REACH compliance timelines. Styrene residuals now capped at stricter thresholds drive reformulation toward lower monomer content grades.
- Acrylic:Pure acrylic emulsions deliver superior UV resistance and clarity for premium coated papers. Water-based acrylic systems dominate new line installations in China's packaging corridor as MEE wastewater standards tighten. These binders command price premiums where optical properties outweigh raw material cost sensitivity.
- Polyvinyl Acetate:Vinyl acetate homopolymers and copolymers serve lower-speed coating operations and specialty laminating adhesives.
- Polyurethane:Aliphatic polyurethane dispersions provide extreme durability and barrier properties for food-contact board and synthetic paper substrates.
Styrene-acrylic leads on scale; acrylic leads on momentum as water-based conversion accelerates.
End Use Industry:
Application-specific performance requirements dictate binder selection across print durability, heat-seal integrity, and food-contact compliance.
- Packaging:Recyclable paperboard specifications from major consumer brands are pulling high-performance binders into folding carton and corrugated liner applications. Water-based styrene-acrylic systems dominate this segment where print scuff resistance and heat-seal strength must coexist.
- Printing:Publication gravure and offset lithography demand binders with controlled ink receptivity and blister resistance. Magazine and commercial print mills in Germany and the United States specify particle size distributions optimized for high-speed calendering.
- Labeling:Pressure-sensitive and wet-glue label stocks require tack-modified binder systems with specific peel adhesion profiles.
- Stationery:Fine paper and envelope applications prioritize stiffness retention and writability over gloss maximization.
Packaging leads on scale; labeling leads on momentum as e-commerce logistics expand adhesive label consumption.
Formulation Type:
Carrier chemistry determines emissions profile, drying energy requirements, and capital investment thresholds for coating line retrofits.
- Water-Based:Acrylic and styrene-acrylic emulsions with 40-50% solids content are displacing solvent alternatives under EPA hazardous air pollutant rules. Mills in Wisconsin and the Carolinas are converting legacy solvent lines to water-based systems to avoid enforcement exposure. These formulations require higher drying temperatures but eliminate VOC emissions at the point of application.
- Solvent-Based:Hydrocarbon and ester solvent carriers persist in specialty applications where rapid drying or substrate compatibility constraints resist aqueous conversion.
- Hot-Melt:Thermoplastic block copolymer systems serve extrusion coating and laminating operations where immediate green strength is critical.
- Powder:Dry polymer powders enable curtain coating and specific specialty applications where liquid carrier elimination provides processing advantages.
Water-based leads on scale; hot-melt leads on momentum in packaging laminating applications.
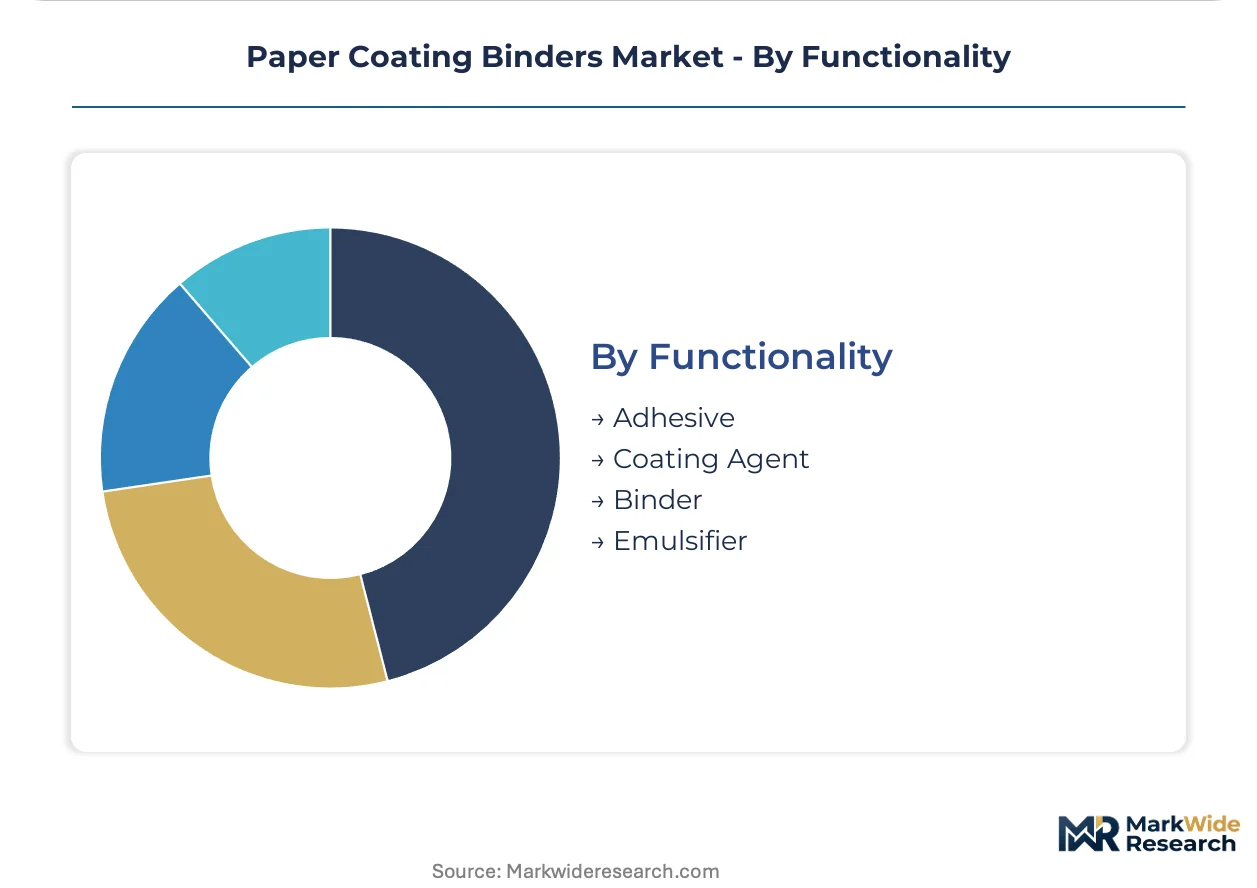
Functionality:
Primary mechanical role in the coating structure determines binder loading levels and interaction with pigment particles.
- Binder:Film-forming polymers anchor pigment to cellulose fibers and provide inter-particle cohesion. This core function consumes the majority of coating formulation volume and determines final sheet strength properties.
- Coating Agent:Surface-modifying additives control gloss, smoothness, and print receptivity through specific particle size and glass transition temperature engineering.
- Adhesive:Tack-providing formulations serve laminating, sizing, and specialty bonding applications beyond pigment binding.
- Emulsifier:Surfactant-stabilized systems enable dispersion of hydrophobic components in aqueous coating formulations.
Binder leads on scale; coating agent leads on momentum as single-binder architectures unify multiple functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized emulsion polymerization chemists concentrate in Germany's Rhine-Ruhr corridor and China's Yangtze River Delta, anchoring formulation expertise for water-based binder scale-up.
United States
Packaging converters in Wisconsin and the Carolinas drive water-based line conversions as EPA hazardous air pollutant enforcement intensifies. The agency's residual solvent limits for coating operations are accelerating capital deployment toward compliant acrylic systems. Milwaukee-area paper mills are retrofitting legacy solvent infrastructure to handle higher thermal drying loads.
Germany
Publication gravure houses in Baden-Württemberg specify particle-engineered styrene-acrylic binders for high-speed calendering operations. ECHA REACH restrictions on styrene monomer residuals are forcing reformulation investments across European supply chains. Ludwigshafen's integrated chemical complexes supply captive acrylic acid feedstock for binder production.
China
Domestic packaging growth in Guangdong and Zhejiang provinces is absorbing expanded water-based acrylic capacity. MEE wastewater discharge standards for industrial effluent are pushing mills toward cleaner binder chemistries. The Yangtze River Delta corridor concentrates coating line retrofit activity as state-owned paper groups modernize.
India
BIS quality standards for coated paper are tightening specifications for folding carton applications in Maharashtra and Gujarat. Domestic packaging growth is creating first-mover openings for technical service-intensive binder suppliers. Mumbai-Pune industrial belt mills are evaluating water-based system conversions.
Japan
Specialty synthetic paper manufacturers in the Chubu region require aliphatic polyurethane dispersions for extreme durability applications. METI industrial standards on chemical emissions are aligning domestic procurement with low-VOC coating systems. Nagoya-area technical paper producers are qualifying next-generation barrier-grade binders.
Paper Coating Binders Market Competitive Environment
Capital-heavy producers compete with asset-light designers as integrated chemical majors face specialized emulsion polymerization houses. The market structure tiers between multinational resin suppliers with captive feedstock and regional formulation specialists with technical service depth. Three archetypes dominate: integrated acrylic acid producers, emulsion polymerization specialists, and bio-based alternative developers. Capacity expansion and backward integration into propylene derivatives represent the primary competitive vectors.
Within the integrated chemical tier, BASF SE and Dow exemplify scale-driven positioning through captive acrylic acid supply chains. Kemira Oyj occupies a distinct specialization anchor in bio-based binder development aligned with Nordic pulp industry sustainability requirements. Arkema represents the premium-performance vector where aliphatic polyurethane dispersions serve specialized barrier applications.
| Leading Market Players |
|---|
| Wacker Chemie |
| Trinseo |
| BASF SE |
| DIC Corporation |
| Arkema |
| Dow |
| Celanese Corporation |
| Kemira Oyj |
| Synthomer Plc |
| Others |
Value Chain & Pricing Dynamics
Propylene cost volatility transmits directly through styrene-acrylic binder production, compressing margins at formulation houses while integrated producers with captive acrylic acid supply chains maintain pricing power across premium and standard tiers.
Pricing Analysis
Bundled technical service contracts dominate premium polyurethane binder sales, while unbundled commodity emulsion transactions prevail in high-volume styrene-acrylic segments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Pricing pressure stems from acrylic acid feedstock swings, with margins tightening most acutely at non-integrated formulators. Brand-owner packaging converters show highest price sensitivity, whereas food-contact board manufacturers prioritize barrier performance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for coating line retrofit equipment and spent solvent recovery systems are emerging as secondary material channels in Germany and the United States. Supply concentrates in Germany, China, and the United States for both acrylic acid feedstock and specialized emulsion polymerization capacity. Production draws from propylene derivatives, styrene monomer, and isocyanate precursors. Single-source vulnerability around German and US isocyanate suppliers exposes premium binder buyers to allocation risk. Distribution runs through direct mill partnerships for large coating operations and regional chemical distributors for mid-tier converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The paper coating binders market functions as a stable compounder, with regulatory-mandated water-based conversion providing durable demand visibility across the analysis window.
For Market Incumbents: Lock in backward integration into propylene derivatives to defend against acrylic acid margin compression. Secure long-term offtake agreements with packaging converters in China's Yangtze River Delta corridor. Invest in bio-acrylic R&D to preempt Nordic pulp industry sustainability procurement shifts.
For New Entrants and Emerging Players: Digital-channel technical service platforms offer low-capital routes to penetrate India's underpenetrated coated paper segment. Target Maharashtra and Gujarat folding carton mills with water-based system conversion support. Lead with BIS compliance consulting bundled with binder supply.
For Investors and Strategic Acquirers: Consolidation pressure builds where emulsion polymerization expertise scarcity constrains new entrant scale-up. Five-to-ten-year viability favors acquiring regional formulation specialists with technical service depth in packaging corridors. Monitor EPA enforcement intensity in Wisconsin and the Carolinas as inflection signal for water-based conversion acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive acrylic acid supply insulates BASF and Dow from propylene volatility. |
| Green Manufacturing Transition | Kemira's bio-acrylic path aligns with EU Green Deal procurement criteria. |
| Long-term Supply Agreement | Dow's direct partnerships with North American mills secure volume commitments. |
| Joint Venture | Local technical service JVs unlock India's packaging growth corridor. |
| Capacity Expansion | China's MEE standards drive Yangtze River Delta coating line retrofit demand. |
Study Parameters
Direct dialogue with coating line engineers, procurement leads at packaging converters, emulsion polymerization chemists, and technical R&D directors at integrated chemical majors grounded qualitative insights. Secondary validation drew from EPA enforcement records, ECHA REACH substance restrictions, China MEE wastewater discharge data, and SEC 10-K filings of listed chemical producers. Bottom-up and top-down triangulation cross-checked volume estimates against customs trade flows and mill capacity announcements.
Bottom-up modeling aggregated individual coating line conversion timelines and binder procurement volumes across the projection horizon. Segmentation dimensions included polymer chemistry, end-use industry, formulation type, and regional regulatory cluster. CAGRs derived from regression analysis of historical capacity deployment correlated with emissions rule implementation schedules. Forecast inputs incorporated propylene price trajectory assumptions and packaging sector growth elasticities.
The model assumes a particular technology adoption path; alternative pathways for solvent-based binder retention would alter the outlook. Forecasts reflect assumptions about REACH timeline adherence and MEE enforcement intensity. Practitioners should monitor EPA inspection frequency in Wisconsin and the Carolinas, ECHA styrene residual limit revisions, and China state-owned paper group modernization announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
United Arab Emirates Protective Coatings Market
Coatings
Cladding Coatings Market
Coatings
Global Inorganic Antimicrobial Coatings Market
Coatings
South Africa Automotive OEM Coatings Market
Coatings
High Performance Epoxy Coating Market
Coatings
Global Anti-Corrosion Coating Market
Coatings
Canada Floor Coatings Market
Coatings
Saudi Arabia Industrial Coatings Market
Coatings
Polyurethane Powder Coatings Market
Coatings
Global Sputter Coatings Market
Coatings
Marine Deck Coatings Market
Coatings
Russia Architectural Coatings Market
Coatings
Qatar Protective Coatings Market
Coatings
Sol-Gel Coatings Market
Coatings
Tablet and Pellet Coating Systems Market
Coatings
North America Polyimide Coating Market