
 Lip Seals Market | 2026-2036
Lip Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Lip Seals Market Analytics
Advanced fluoroelastomer compounding is reconfiguring seal performance benchmarks for electrified powertrains. SKF Group leverages integrated bearing-seal architectures to dominate thermal management applications in EV axle assemblies. Freudenberg Sealing Technologies anchors European supply through captive polymer synthesis and in-house compounding of perfluoroelastomer grades. Parker Hannifin Corporation competes across aerospace and industrial hydraulics with broad material certification portfolios.
A lip seal is an annular sealing device featuring a flexible elastomeric or thermoplastic lip that maintains dynamic contact against a rotating or reciprocating shaft surface, typically operating at pressures from vacuum to 10 bar and temperatures spanning -40°C to 200°C depending on material selection; its primary function is to retain lubricants and exclude contaminants from bearing chambers, gearboxes, and hydraulic systems. Rotary seals command the largest volume share due to ubiquity in automotive transmissions and electric motor shafts, though PTFE-based variants are gaining fastest penetration in chemical processing where aggressive media degrade conventional elastomers. Polyurethane hydraulic seals occupy a mature, price-competitive segment serving construction and agricultural machinery rebuild markets.
EPA emissions enforcement and NHTSA fuel economy mandates in the United States compel seal suppliers to demonstrate extended service life and reduced friction coefficients. REACH substance restrictions and the EU Green Deal's fluoropolymer phase-down timelines force European manufacturers to qualify hydrogenated nitrile and thermoplastic elastomer alternatives. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance strategies viable in North America may face material disqualification under European chemical frameworks.
Market Dynamics
Automotive electrification is compressing traditional seal design cycles while forcing material qualification for higher thermal loads and dielectric compatibility in electric drivetrain architectures.
Growth Catalysts
- EV Thermal Management:Electric axle assemblies require precision lip seals capable of operating at elevated temperatures and rotational speeds, expanding specification requirements across automotive OEM supply chains.
- REACH Fluoropolymer Phase-Down:European chemical restrictions are accelerating supplier investment in hydrogenated nitrile and thermoplastic elastomer alternatives, creating first-mover advantages for qualified compounders.
- German Industrial Clustering:Precision seal manufacturing concentrates in Germany's industrial corridor, where captive polymer synthesis and integrated bearing-seal architectures serve Tier 1 automotive and chemical processing demand.
Market Restraints
- Fluoroelastomer Feedstock Volatility:Perfluorinated compound supply constraints and precursor chemical availability create input cost instability for high-performance seal formulations.
- European Supply Concentration:Captive polymer synthesis capabilities cluster among three major compounders, creating bottleneck risk for specialized perfluoroelastomer grades.
- Material Substitution Ceiling:Hydrogenated nitrile and thermoplastic elastomers face performance gaps in extreme chemical exposure applications, limiting displacement of fluoroelastomer architectures.
Strategic Opportunities
- PTFE-Based Chemical Processing:Aggressive media degradation in European chemical plants creates white space for PTFE-laminated lip seals with extended service intervals.
- Integrated Bearing-Seal Systems:Convergence of seal and bearing functions enables value capture through thermal management module supply to EV powertrain integrators.
- NHTSA Fuel Economy Mandates:Extended service life and reduced friction coefficient requirements create specification pull for advanced compound formulations in US automotive applications.
Industry Challenges
- Material Qualification Timelines:New elastomer formulations require 18-24 month validation cycles against OEM thermal cycling and chemical resistance protocols.
- Compounding Talent Scarcity:Fluoroelastomer and perfluoroelastomer formulation expertise concentrates among retiring chemist cohorts, constraining R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lip Seals Market |
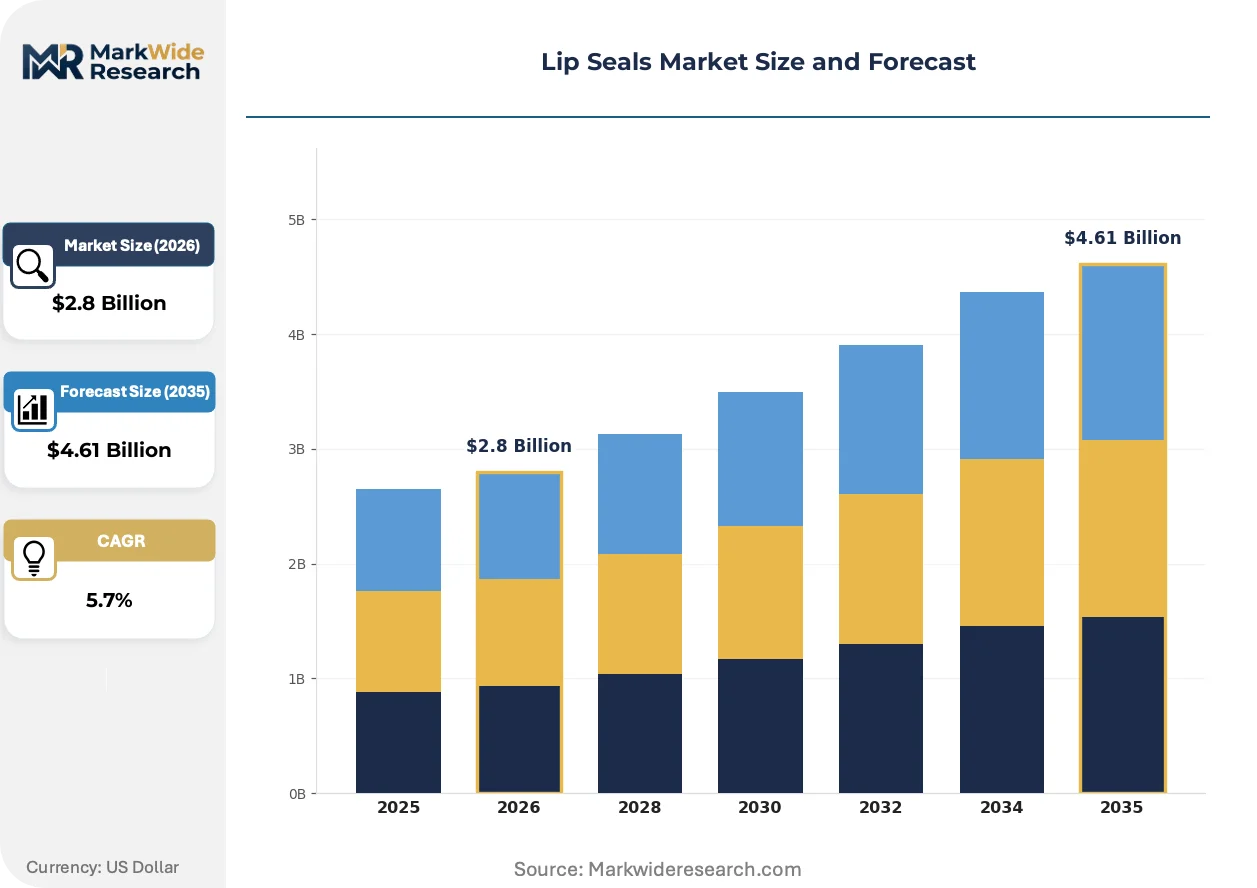
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Seals, Pneumatic Seals, Hydraulic Seals, Mechanical Seals Material: Rubber, PTFE, Metal, Polyurethane End User: Automotive, Aerospace, Industrial Equipment, Marine Application: Oil & Gas, Food Processing, Chemical Industry, Pharmaceuticals |
| Companies Covered | SKF Group, Freudenberg Sealing Technologies, Parker Hannifin Corporation, Trelleborg AB, Dana Inc., Bal Seal Engineering, NOK Corporation, James Walker & Co., Greene Tweed & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lip Seals Market Evolving Landscape
Digital integration of seal performance monitoring, regulatory chemistry restrictions, and compressed automotive development cycles are reconfiguring how suppliers qualify materials and capture value.
Smart seal architectures incorporating embedded temperature and wear sensors are digitizing predictive maintenance workflows for critical rotating equipment. Wind turbine operators and chemical processing facilities in Northern Europe are piloting these systems to eliminate unplanned downtime. The technology is digitizing service contract structures toward performance-guarantee models rather than component replacement revenue.
REACH restrictions on perfluorinated compounds are forcing European suppliers to rebuild material portfolios around hydrogenated nitrile and thermoplastic elastomer alternatives. Compounders must requalify entire product lines against OEM thermal and chemical specifications previously met by fluoroelastomer grades. German automotive seal manufacturers face the steepest compliance burden given their concentration of high-temperature EV powertrain contracts.
Automotive OEMs are consolidating seal procurement around thermal management module suppliers rather than discrete component vendors. Tier 1 integrators now specify seal performance as subsystem requirements, compressing direct supplier relationships. This pattern concentrates most visibly in German and US electric drivetrain supply chains where axle assembly integration dominates sourcing decisions.
Lip Seals Market Segmentation
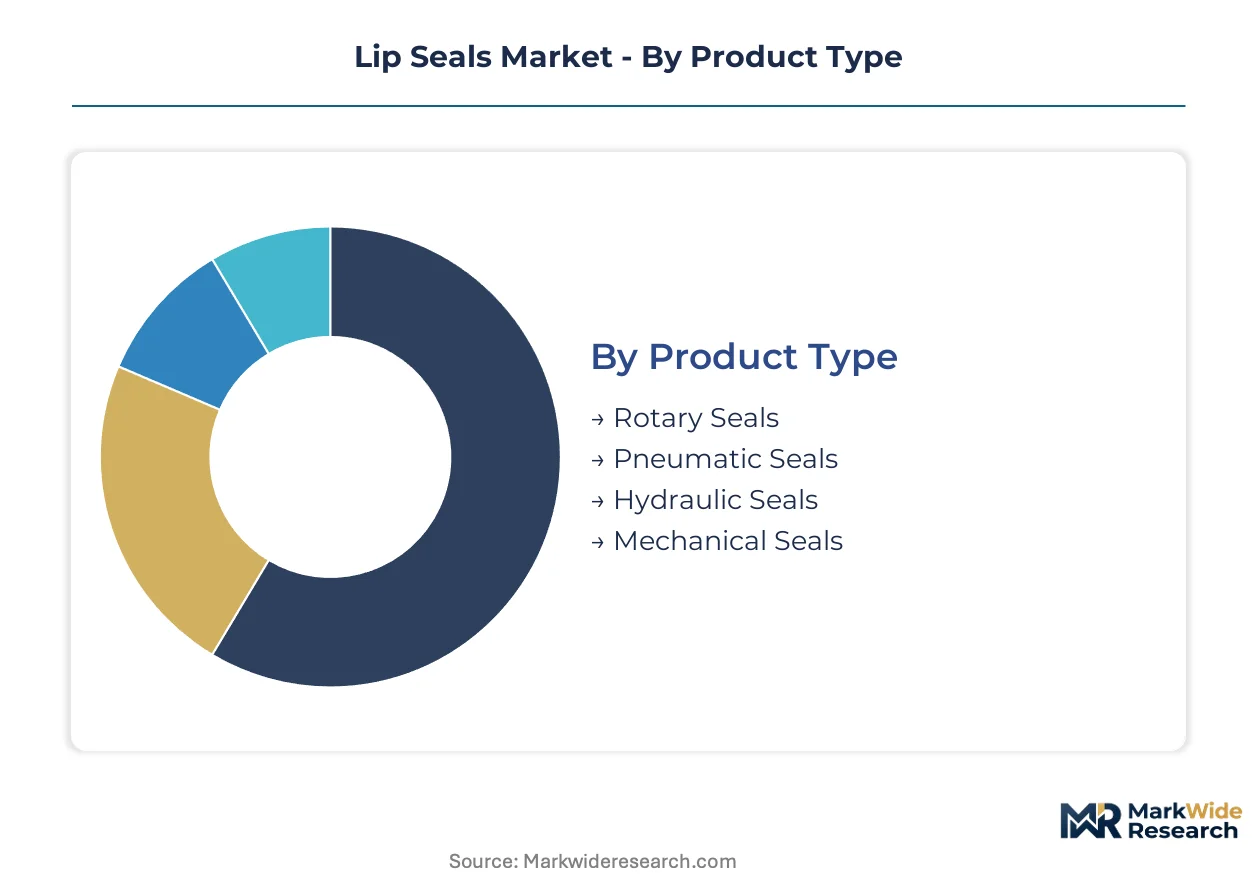
Segmentation in lip seals reveals divergent replacement cycles and specification intensities across product architectures. Rotary seals turn over fastest in automotive drivetrains, while material selection locks in decade-long supply relationships in chemical processing. Understanding these temporal patterns enables suppliers to align R&D investment with revenue predictability.
Product Type:
Replacement cycles vary dramatically across seal architectures, with some segments requiring annual rebuild schedules while others operate across equipment lifecycles.
- Rotary Seals:Annular elastomeric lips maintain dynamic contact against rotating shafts in transmissions and electric motor assemblies. Automotive OEMs in Germany specify these for EV thermal management modules where elevated operating temperatures accelerate wear cycles.
- Hydraulic Seals:Polyurethane and rubber formulations contain pressurized fluid in construction equipment and agricultural machinery cylinders. Rebuild markets in North America drive steady aftermarket demand as equipment owners extend asset lifecycles.
- Pneumatic Seals:Low-friction designs seal compressed air systems in factory automation equipment.
- Mechanical Seals:Multi-component face seal assemblies protect pumps and compressors in chemical processing plants.
Rotary seals anchor the volume base while hydraulic seals gain share at the steepest rate.
Material:
Cost tiers stratify sharply between commodity elastomers and fluoropolymer grades, with qualification barriers determining supplier switching economics.
- Rubber:Nitrile and hydrogenated nitrile compounds dominate automotive and general industrial applications at the standard-performance tier. REACH restrictions on perfluorinated compounds are accelerating European qualification of advanced nitrile formulations for elevated temperature service.
- PTFE:Polytetrafluoroethylene laminates and composites withstand aggressive chemical media that degrade conventional elastomers. Chemical processing facilities in Germany specify these for extended service intervals in corrosive environments.
- Metal:Stainless steel and alloy housings provide structural rigidity and thermal dissipation in high-speed rotating equipment.
- Polyurethane:Abrasion-resistant formulations serve hydraulic cylinder applications in construction and mining equipment.
Rubber formulations command the broadest installed base while PTFE expands most quickly in chemical-resistant specifications.
End User:
Customer concentration patterns diverge between fragmented aftermarket channels and consolidated OEM direct procurement.
- Automotive:Tier 1 axle assembly integrators specify seal performance as subsystem requirements, compressing direct supplier relationships. Electric drivetrain thermal management modules in Germany and the United States concentrate procurement among integrated bearing-seal suppliers.
- Aerospace:FAA certification requirements and material traceability mandates create steep qualification barriers for new entrants. Extended validation timelines favor incumbent suppliers with established airframe manufacturer relationships.
- Industrial Equipment:Diverse machinery OEMs and maintenance departments drive fragmented demand across factory automation and process industries.
- Marine:Classification society approvals and saltwater corrosion resistance specifications govern propulsion system applications.
Automotive anchors procurement volume while aerospace commands the highest specification premiums.
Application:
Regulatory chemistry restrictions and process safety requirements create divergent material qualification burdens across industrial sectors.
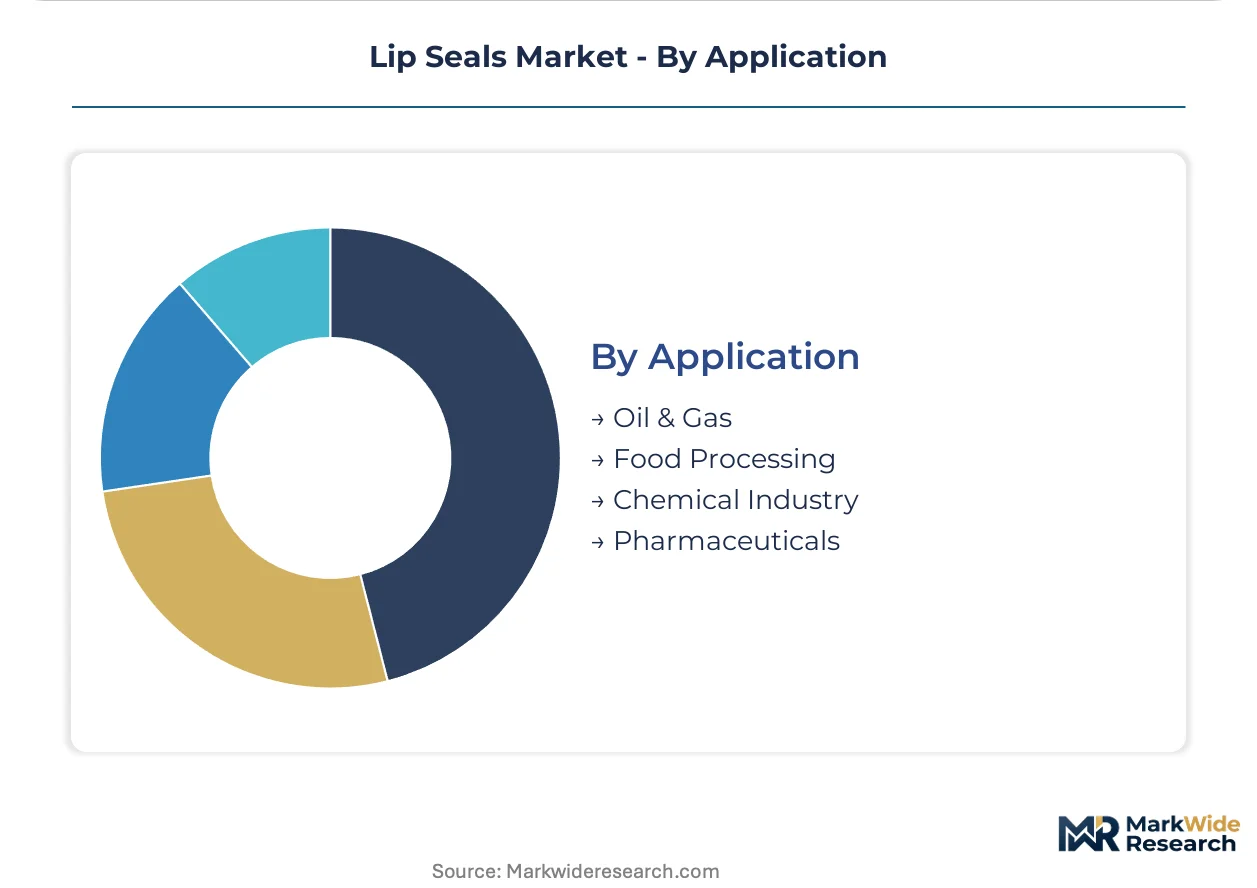
- Chemical Industry:Aggressive acids, solvents, and high-temperature process streams demand fluoroelastomer or PTFE-based seal architectures. ECHA restrictions on perfluorinated compounds are forcing European processors to revalidate entire product lines with alternative materials.
- Oil & Gas:Downhole pressure ratings and sour gas compatibility specifications govern subsea and wellhead equipment sealing. API certification requirements and NORSOK standards in North Sea operations create regional qualification barriers.
- Food Processing:FDA compliance and hygienic design requirements limit material selection to approved elastomer grades with full batch traceability.
- Pharmaceuticals:USP Class VI biocompatibility and sterile processing validation govern equipment sealing in aseptic manufacturing environments.
Chemical industry applications drive the most intensive material innovation cycles while food processing presents the most standardized procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in lip seals reveal Germany as a net exporter of precision fluoroelastomer grades while the United States maintains import dependence for specialized perfluoroelastomer formulations. Asian manufacturing centers in China and Japan supply volume-tier nitrile and polyurethane variants to North American aftermarket channels. Regional regulatory divergence on perfluorinated compounds is fragmenting material qualification pathways across jurisdictions.
Germany
Automotive OEM procurement for EV thermal management modules drives specification intensity in Stuttgart and Munich industrial corridors. REACH restrictions on perfluorinated compounds force compounders in Baden-Württemberg to rebuild material portfolios around hydrogenated nitrile alternatives. Freudenberg Sealing Technologies anchors supply through captive polymer synthesis in Weinheim.
United States
NHTSA fuel economy mandates and EPA emissions enforcement compel seal suppliers to demonstrate extended service life in Detroit and Tennessee automotive clusters. The country maintains import dependence for specialized perfluoroelastomer grades from European compounders. Parker Hannifin Corporation exemplifies the diversified industrial-aerospace positioning prevalent among domestic suppliers.
China
Electric vehicle production concentration in Shanghai and Shenzhen generates volume demand for rotary seals in motor and axle assemblies. MIIT industrial standards govern material certification for domestic automotive supply chains. Local compounders supply nitrile and polyurethane tiers while importing fluoroelastomer precursor chemicals.
Japan
Precision manufacturing in Aichi and Kanagawa prefectures sustains demand for high-performance rotary seals in hybrid and electric drivetrains. METI technology roadmaps prioritize thermal management component localization. NOK Corporation represents the integrated material-to-component supply model characteristic of domestic players.
India
Automotive manufacturing expansion in Maharashtra and Tamil Nadu creates aftermarket and OEM demand for hydraulic and rotary seal replacements. BIS standards govern elastomer material certification for domestic industrial applications. Import dependence persists for fluoroelastomer grades serving chemical processing installations in Gujarat.
Lip Seals Market Competitive Landscape
On the supply side, the industry is tiered between integrated polymer-to-seal manufacturers and specialized fabricators dependent on external compound supply. Three strategic archetypes dominate: European compounders with captive synthesis capabilities, diversified industrial conglomerates spanning aerospace and automotive verticals, and Asian volume manufacturers serving replacement markets. Competitive moves concentrate on material qualification speed for regulatory-compliant alternatives and thermal management module integration partnerships with EV powertrain integrators.
Within the integrated European tier, SKF Group and Freudenberg Sealing Technologies exemplify the polymer synthesis-to-seal manufacturing model that dominates high-specification automotive procurement. Parker Hannifin Corporation occupies a diversified position across industrial hydraulics and aerospace certification portfolios. These three anchors represent distinct strategic postures: bearing-seal integration, captive material science, and broad regulatory certification coverage.
| Leading Market Players |
|---|
| SKF Group |
| Freudenberg Sealing Technologies |
| Parker Hannifin Corporation |
| Trelleborg AB |
| Dana Inc. |
| Bal Seal Engineering |
| NOK Corporation |
| James Walker & Co. |
| Greene Tweed & Co. |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's volatile container rates compress margins for fluoroelastomer compounders shipping from German industrial clusters to North American automotive plants, concentrating pricing power among integrated suppliers with captive polymer synthesis while forcing tier-two fabricators toward hydrogenated nitrile formulations at lower price points.
Pricing Analysis
Next-generation perfluoroelastomer grades command substantial premiums over hydrogenated nitrile and standard fluoroelastomer tiers due to REACH-driven material scarcity. Three-tier pricing structure across premium perfluoroelastomer, standard fluoroelastomer, and economy nitrile levels reflects certification grade and thermal performance specifications. Cost compression in the nitrile tier is intensifying because Asian volume manufacturers are expanding European distribution. Aftermarket rebuild channels exhibit the highest price sensitivity, while EV thermal management module integrators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Extended payment terms from Tier 1 automotive integrators are forcing compounders to utilize supply-chain finance facilities, extending cash conversion cycles for specialized seal fabricators. Feedstock dependence draws from Germany, Japan, and the United States for fluoroelastomer precursor chemicals and captive polymer synthesis. Supply chain risk centers on single-source vulnerability for perfluoroelastomer grades amid ECHA phase-down timelines. Distribution runs through authorized distributor networks serving industrial maintenance channels and direct OEM contracts for thermal management modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around REACH-compliant material qualifications creates steep switching costs for automotive OEMs locked into validated supply relationships.
For Market Incumbents: Entrench position by accelerating hydrogenated nitrile qualification programs ahead of ECHA enforcement timelines, securing first-mover certification advantages against substitute material threats. Deepen backward integration into captive polymer synthesis to defend margin position amid feedstock volatility. Target capacity expansion in Baden-Württemberg to anchor German automotive cluster procurement. For New Entrants and Emerging Players: PTFE-laminated rotary seals for European chemical processing facilities represent the most penetrable entry point, given aggressive media degradation and extended service interval requirements that favor new material architectures. Mid-volume hydraulic seal rebuild markets in North American agricultural machinery offer secondary white-space opportunity. Pursue qualification partnerships with regional distributor networks rather than direct OEM penetration. For Investors and Strategic Acquirers: European compounders with integrated polymer synthesis and established REACH-compliant formulation libraries present the highest-value acquisition archetype for long-term positioning across the five-to-ten year regulatory transition window. Monitor ECHA enforcement acceleration as the critical inflection signal for material substitution velocity and stranded asset risk in legacy fluoroelastomer capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | Captive fluoroelastomer production insulates SKF and Freudenberg from precursor chemical volatility. |
| REACH-Compliant Material Qualification | Hydrogenated nitrile validation programs secure automotive OEM thermal management contracts ahead of competitors. |
| Integrated Bearing-Seal System Development | Thermal management module convergence captures value from EV axle assembly integrators in Germany. |
| Smart Seal Sensor Integration | Embedded temperature monitoring digitizes predictive maintenance contracts for Northern European wind turbine operators. |
| Regional Distribution Network Expansion | Authorized distributor relationships in North American aftermarket channels defend against Asian volume competitors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and ECHA regulatory submissions, combining structured interviews with seal procurement managers at Tier 1 automotive suppliers, compounder R&D directors, and aftermarket distribution channel heads with bottom-up and top-down triangulation across product and geographic segments.
Forecast inputs include vehicle production databases, IHS Markit registration data, and OEM thermal management module sourcing disclosures across the projection horizon. Segmentation dimensions modeled encompass material grade tier, end-use industry, seal architecture type, and regional production cluster. CAGRs derive from elasticity analysis against automotive electrification penetration rates and chemical processing capacity expansion.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, polymer feedstock pricing, or ECHA enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timelines and material substitution curves; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Isostatic Pressing Market
Industrial Materials
North America Phenolic Insulation Market
Industrial Materials
GCC Welding Consumables Market
Industrial Materials
Metal Molds Market
Industrial Materials
Global Graphite Electrode Rod Market
Industrial Materials
North America Non-Structural Stainless Steel Fasteners Market
Industrial Materials
Industrial Kiln Market
Industrial Materials
Vinyl Extrusion Equipment Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
Global Polycarbonate Sheets Market
Industrial Materials
Air Classifiers Market
Industrial Materials
Tooling Board Market
Industrial Materials
Static Mixer Market
Industrial Materials
Ribbed Smoke Sheet Market
Industrial Materials
Flat Enameled Wires Market