
 Global Friction Materials Market | 2026-2036
Global Friction Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Friction Materials Market Foresight
ECE R90 certification is bifurcating the competitive landscape into qualified suppliers and excluded challengers. Nisshinbo Holdings Inc. leverages its sintered metal expertise to dominate Japanese OEM supply chains. Tenneco Inc. sustains aftermarket scale through broad distribution across North American and European channels. Brembo differentiates via motorsport-derived ceramic formulations that command premium positioning in performance vehicle segments.
Friction materials are engineered composites—typically comprising phenolic resin binders, reinforcing fibers, and metallic or ceramic fillers—that convert kinetic energy into thermal energy through controlled wear during braking or power transmission operations. Manufacturing employs hot pressing, sintering, or wet mixing processes to achieve coefficient-of-friction stability across temperature ranges exceeding 350°C. Ceramic formulations within the material type segment lead in thermal performance and are capturing share from organic variants in heavy-duty applications. Brake pads as a product form occupy the largest margin pool due to high replacement frequency, while clutch facings face structural pressure from electrification trends in passenger vehicle powertrains.
The U.S. EPA regulates copper content in brake formulations under stormwater runoff provisions, compelling reformulation toward non-copper alternatives. The EU's REACH framework restricts specific friction-modifying chemicals, forcing European suppliers to recertify material compositions. Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces JIS D 4411 standards that govern noise and wear performance thresholds. Stakeholders must monitor how dual carbon targets in China and the EU's F-Gas Regulation on process emissions will cascade into raw material sourcing constraints and qualification timelines.
Market Dynamics
Automotive electrification is fragmenting traditional friction material demand, as regenerative braking systems in battery-electric vehicles reduce mechanical brake pad wear cycles by 50-70% compared to internal combustion powertrains. This structural dislocation forces suppliers to pivot toward heavy-duty commercial segments and emerging markets where conventional braking architectures persist.
Growth Catalysts
- MIIT emission mandates:China's Ministry of Industry and Information Technology enforces stricter particulate limits on brake wear emissions, compelling domestic OEMs to qualify advanced low-metallic and ceramic formulations.
- Commercial vehicle drum brake replacement cycles:Heavy-duty trucking fleets in India and Brazil generate sustained aftermarket pull as loaded axle weights and mountainous terrain accelerate lining consumption.
- Sintered copper-free formulations:Powder metallurgy processes enable brake pad architectures that satisfy California's SB 346 copper reduction timeline while maintaining thermal stability under 400°C operating conditions.
Market Restraints
- Phenolic resin cost volatility:Petrochemical feedstock price swings compress formulation margins, particularly for mid-tier suppliers lacking long-term benzene derivative contracts.
- Aramid fiber supply concentration:Dupont and Teijin control 70%+ of para-aramid global capacity, creating single-source vulnerability for friction material binders.
- REACH chemical restrictions:ECHA's expanding SVHC candidate list forces European formulators to retire established friction modifiers, triggering 18-24 month recertification timelines.
Strategic Opportunities
- India passenger vehicle aftermarket:Domestic production scaling by Maruti Suzuki and Hyundai Motor India concentrates vehicle parc growth, concentrating replacement demand in Delhi-Mumbai-Chennai corridors.
- Railway friction segments:High-speed rail expansion across Southeast Asia creates demand for sintered brake pads capable of 300+ km/h deceleration cycles.
- EU F-Gas Regulation process incentives:Manufacturers investing in non-fluorinated curing agents gain preferential qualification status under the EU Green Deal industrial transition framework.
Industry Challenges
- ECE R90 certification backlog:Testing laboratory capacity constraints in Germany and Italy extend type-approval timelines to 14-18 months, freezing new product launches.
- Tribology simulation talent scarcity:Finite element modeling expertise for brake thermal fade prediction concentrates in Stuttgart, Turin, and Nagoya engineering clusters.
- Legacy press equipment retrofit costs:Converting hydraulic hot presses for ceramic preform compatibility requires $2-4 million per production line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Friction Materials Market |
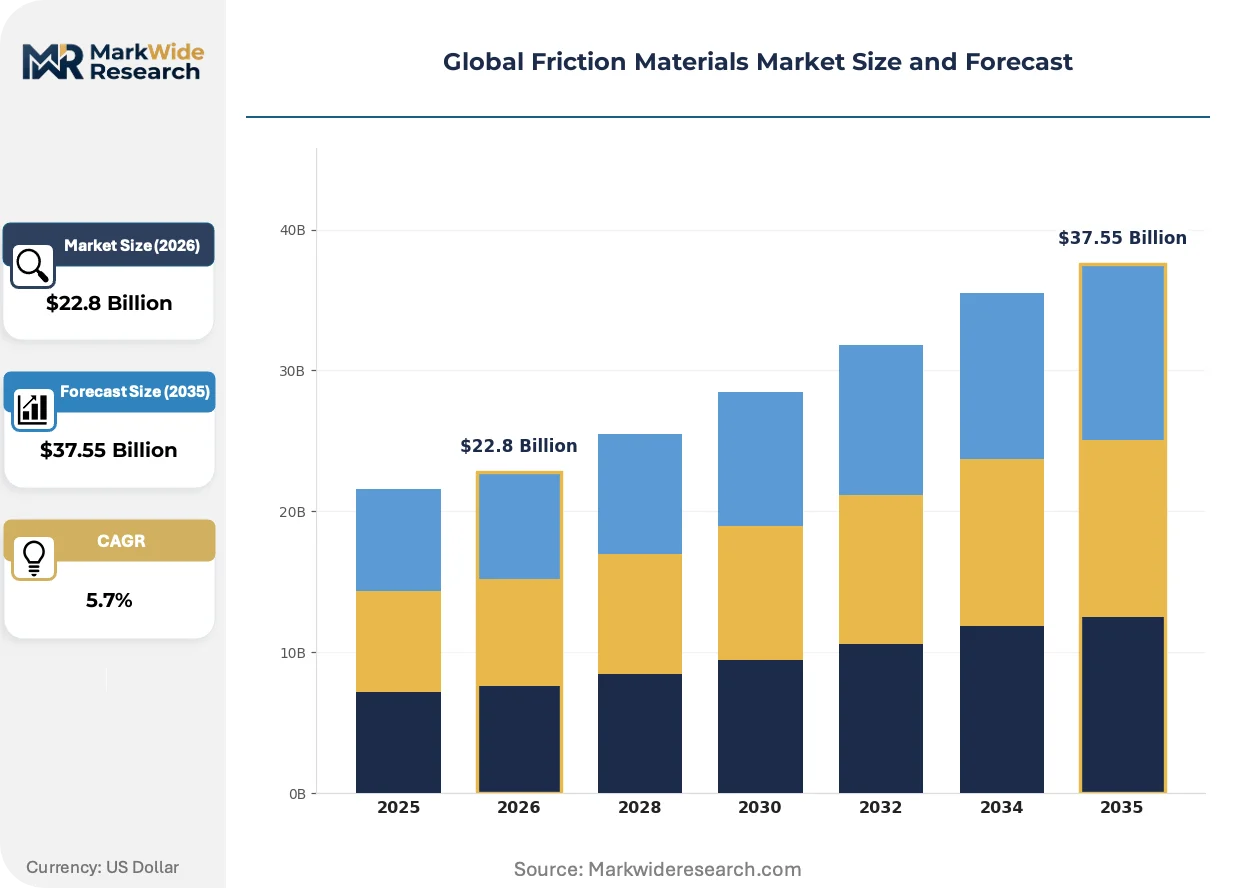
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $37.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Sintered, Organic, Metallic, Ceramic, Composite Application: Passenger Vehicles, Commercial Vehicles, Industrial Machinery, Construction Equipment, Two-Wheelers Product Form: Brake Pads, Brake Shoes, Clutch Facings, Disc Pads, Lining Sheets End User: Vehicle Manufacturers, Aftermarket Suppliers, Equipment Manufacturers, OEMs |
| Companies Covered | Nisshinbo Holdings Inc., Tenneco Inc., Akebono Brake Industry Co. Ltd., Miba AG, Brembo, Fras-le, Carlisle Brake & Friction, ABS Friction, Aisin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Friction Materials Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are converging to accelerate formulation turnover, compressing product lifecycles while opening premium positioning for certified suppliers. Three developments dominate this transition.
Ceramic matrix composite brake pads are decomposing the traditional organic-metallic hierarchy in heavy-duty applications. Mining truck OEMs in Western Australia and Chilean copper belts specify these formulations for 50,000+ hour service intervals. The technology is decomposing aftermarket revenue predictability as extended replacement cycles compress addressable event frequency.
REACH Annex XVII restrictions on copper and heavy metal content are forcing European formulators toward glass, rubber, and mineral fiber alternatives. The regulation eliminates legacy low-cost competitors unable to fund composition redevelopment. Aftermarket suppliers serving Poland, Hungary, and Romania face the steepest compliance cost gradients.
Digital fleet management platforms are consolidating brake wear monitoring into predictive maintenance contracts. Logistics operators in Germany and the Netherlands now specify outcome-based brake performance agreements rather than component procurement. Tier-1 suppliers capturing this data stream gain direct influence over replacement timing and specification lock-in.
Global Friction Materials Market Segmentation
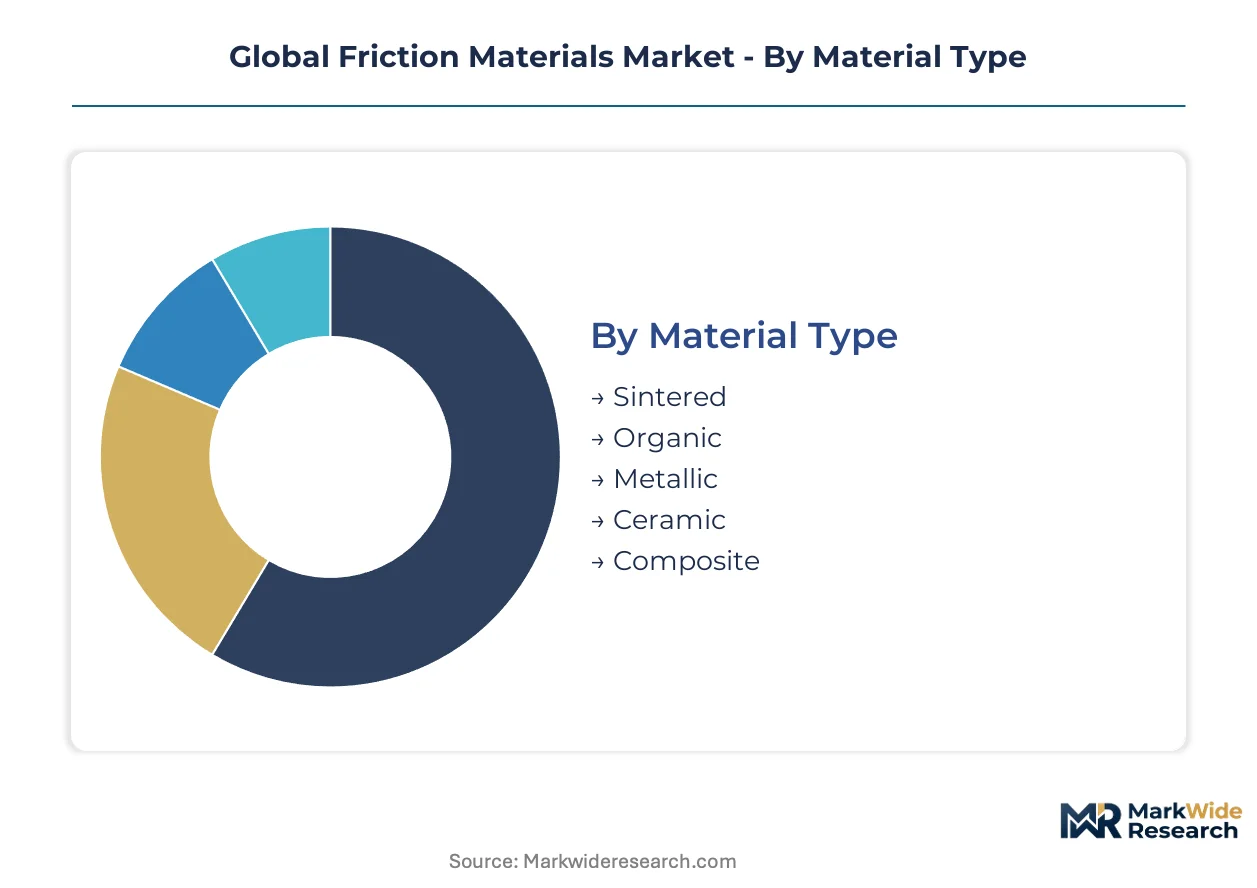
Friction material specifications diverge sharply across automotive, industrial, and heavy-duty applications, with formulation chemistry and thermal thresholds determining supplier qualification tiers. Segment boundaries are hardening as ECE R90 certification and regional emission mandates filter out undifferentiated competitors.
Material Type:
Sintered formulations concentrate in export-heavy supply chains serving Australian mining and Chilean copper operations, while organic variants dominate domestic aftermarket channels in India and Brazil due to cost sensitivity.
- Sintered:Powder metallurgy processes fuse copper, bronze, and iron particles under high pressure and temperature, producing pads that withstand 400°C+ operating conditions in mining haul trucks and high-speed rail. Demand concentrates in Western Australia's Pilbara region and Chile's Antofagasta Province, where loaded vehicle weights exceed 400 tonnes and replacement cycles extend past 50,000 hours.
- Ceramic:Non-asbestos organic matrices reinforced with ceramic fibers and fillers deliver superior thermal stability and reduced brake dust emissions. German and Japanese OEM procurement is accelerating for premium passenger vehicle fitments, driven by China's MIIT particulate mandates and California's SB 346 copper reduction requirements.
- Organic:Phenolic resin binders with aramid, glass, or mineral fiber reinforcement occupy economy-tier aftermarket segments in price-sensitive markets.
- Metallic:Steel and iron-based formulations persist in heavy commercial drum brake applications where abrasive wear tolerance outweighs noise considerations.
- Composite:Hybrid architectures combining ceramic thermal performance with metallic structural integrity target emerging electrified vehicle platforms requiring blended braking strategies.
Ceramic formulations hold the largest share; momentum sits with sintered grades in heavy-duty export markets.
Application:
Passenger vehicle demand fragments between electrified platforms with regenerative braking and conventional architectures in emerging economies, while commercial vehicle procurement concentrates in fleet replacement cycles.
- Passenger Vehicles:Battery-electric powertrains with regenerative braking reduce mechanical pad wear by 50-70%, compressing aftermarket event frequency in German, Japanese, and U.S. parcs. Conventional internal combustion vehicles in India and Southeast Asia sustain organic and low-metallic formulation demand through 2035.
- Commercial Vehicles:Heavy-duty trucking fleets in India and Brazil generate sustained aftermarket pull as loaded axle weights and mountainous terrain accelerate lining consumption. Drum brake architectures dominate trailer and bus applications, with replacement cycles tightening under digital fleet management monitoring.
- Industrial Machinery:Mining excavators, conveyors, and winch systems specify sintered brake pads for continuous-duty thermal loads in Western Australia and Chile.
- Construction Equipment:Loader and grader applications in India's infrastructure build-out favor organic formulations with compressed replacement economics.
- Two-Wheelers:Motorcycle and scooter brake pad demand concentrates in India's domestic aftermarket and Southeast Asian manufacturing hubs.
Commercial vehicles command the deepest aftermarket penetration; two-wheelers are climbing the fastest on production scaling in India.
Product Form:
Brake pads generate recurring revenue through high replacement frequency, while clutch facings face structural displacement from electrification trends eliminating manual transmissions.
- Brake Pads:Disc brake architectures dominate passenger vehicle fitments, with formulation differentiation spanning ceramic premium tiers, low-metallic mid-range, and organic economy grades. Aftermarket channel stocking in Germany, Italy, and the United States requires ECE R90 certification, bifurcating qualified suppliers from excluded challengers.
- Clutch Facings:Phenolic resin-impregnated woven or molded friction materials transmit torque in manual transmission powertrains. Demand is concentrating in commercial vehicle and two-wheeler segments where automated manual transmissions and conventional architectures persist, while passenger vehicle electrification eliminates this component category.
- Brake Shoes:Drum brake actuation components persist in heavy commercial rear axle and trailer applications.
- Disc Pads:Performance-oriented formulations with motorsport-derived thermal characteristics command premium positioning in German and Italian sports vehicle segments.
- Lining Sheets:Raw friction material rolls enable in-house cutting and bonding by aftermarket brake rebuilders in India and Brazil.
Brake pads anchor revenue stability; disc pads are gaining share fastest on performance vehicle specification.
End User:
Vehicle manufacturer procurement demands full material traceability and REACH-compliant chemistry documentation, while aftermarket suppliers compete on inventory velocity and channel coverage.
- Vehicle Manufacturers:OEM brake system integration requires collaborative engineering with Tier-1 suppliers such as Brembo, Nisshinbo, and Tenneco. Procurement specifications mandate JIS D 4411 noise thresholds in Japan, ECE R90 type-approval in Europe, and EPA copper content compliance in the United States.
- Aftermarket Suppliers:Independent distributors and service chains in India, Germany, and the United States compete on brand recognition, availability, and installer training programs. Digital fleet management platforms in the Netherlands and Germany are consolidating brake wear monitoring into predictive maintenance contracts with outcome-based performance agreements.
- Equipment Manufacturers:Mining and construction OEMs in Australia and Chile specify sintered brake architectures with 50,000+ hour service intervals.
- OEMs:Original equipment service channels leverage warranty capture and specification lock-in to defend replacement demand against independent aftermarket competitors.
Aftermarket suppliers capture the broadest geographic footprint; equipment manufacturers are expanding most quickly on mining capital expenditure cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT emission mandates and the EU's REACH chemical restrictions are reshaping qualification requirements across manufacturing hubs. Procurement patterns are diverging between electrified vehicle parcs in Germany and Japan versus conventional architectures persisting in India and Brazil.
United States
California's SB 346 copper reduction timeline is compelling reformulation toward non-copper alternatives. The EPA regulates brake formulation copper content under stormwater runoff provisions. Detroit-area OEMs and aftermarket distributors in the Midwest are qualifying sintered copper-free architectures for heavy-duty commercial fitments.
Germany
ECE R90 certification bifurcates qualified suppliers from excluded challengers in European aftermarket channels. The EU's REACH framework restricts specific friction-modifying chemicals, forcing recertification of material compositions. Stuttgart engineering clusters concentrate finite element modeling expertise for brake thermal fade prediction.
China
Domestic OEMs are accelerating procurement of ceramic composite brake pads to satisfy MIIT particulate limits on brake wear emissions. The Ministry of Industry and Information Technology enforces stricter emission mandates. Manufacturing capacity concentrates in Yangtze River Delta hubs supplying both domestic vehicle production and export markets.
India
Passenger vehicle aftermarket demand is concentrating as Maruti Suzuki and Hyundai Motor India scale domestic production. The country's emission norms align with global standards while preserving cost-sensitive segments. Replacement demand clusters in Delhi-Mumbai-Chennai corridors where vehicle parc expansion outpaces electrification penetration.
Japan
JIS D 4411 standards govern noise and wear performance thresholds for domestic OEM supply chains. The Ministry of Land, Infrastructure, Transport and Tourism enforces certification requirements. Nagoya engineering clusters anchor sintered metal expertise serving premium passenger vehicle and motorsport-derived applications.
Global Friction Materials Market Competitive Landscape
Player mix skews toward diversified automotive suppliers with captive brake system integration capabilities. The vendor base concentrates around three strategic tiers: premium ceramic formulators serving German and Japanese OEMs, scale-driven aftermarket distributors with broad channel coverage, and heavy-duty specialists dominating mining and rail applications. Competitive moves center on ECE R90 certification acquisition and sintered formulation capacity expansion.
Among Japanese fabricators, Nisshinbo Holdings Inc. and Akebono Brake Industry Co. Ltd. occupy positions within the premium-tier OEM supply chain, exemplifying metallurgical expertise integration. Tenneco Inc. represents the scale-driven aftermarket archetype with broad North American and European distribution architecture. Brembo anchors the performance-specialist segment through motorsport-derived positioning.
| Leading Market Players |
|---|
| Nisshinbo Holdings Inc. |
| Tenneco Inc. |
| Akebono Brake Industry Co. Ltd. |
| Miba AG |
| Brembo |
| Fras-le |
| Carlisle Brake & Friction |
| ABS Friction |
| Aisin Corporation |
| Others |
Supply & Pricing Matrix
Fourteen-to-eighteen-month ECE R90 certification lead times concentrate pricing power with qualified German and Italian suppliers while excluding challengers from premium aftermarket channels. This inventory compression cascades into raw material pre-positioning strategies, with phenolic resin and para-aramid fiber stockpiles anchoring cost structures for formulation houses serving European OEM procurement.
Pricing Analysis
Certification level creates the primary spread across the friction materials landscape, with ECE R90-qualified formulations commanding substantial premiums over uncertified alternatives in German and Italian aftermarket channels. Three-tier pricing structure across premium ceramic, standard low-metallic, and economy organic grades tracks thermal performance thresholds and wear emission compliance. Cost compression in mid-tier segments is intensifying because phenolic resin feedstock volatility squeezes margins for suppliers lacking long-term benzene derivative contracts. Fleet operators and mining OEMs exhibit lowest price sensitivity due to outcome-based performance agreements, while independent aftermarket distributors in India and Brazil face acute margin pressure from cost-conscious vehicle owners.
Supply Chain Analysis
Strait of Malacca transit underwrites phenolic resin and specialty chemical flows to Yangtze River Delta friction material manufacturing hubs, creating logistics vulnerability for European and North American formulators. Raw material procurement draws from China for processed ceramic fibers, the United States for high-purity copper powders, and Japan for para-aramid binders controlled by Teijin and DuPont. Single-source vulnerability concentrates in aramid fiber supply, with the two dominant producers controlling seventy percent-plus of global para-aramid capacity. Distribution runs through captive OEM supply chains for German and Japanese vehicle manufacturers, while independent aftermarket channels in India and Brazil rely on regional distributors with localized blending and cutting operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contracts and digital brake wear monitoring represent the fastest-expanding revenue layer, with outcome-based performance agreements displacing traditional component procurement among German and Dutch logistics operators.
For Market Incumbents: Shield aftermarket position by securing ECE R90 certification capacity expansion in German testing laboratories before fourteen-to-eighteen-month backlogs freeze new product launches. Deepen backward integration into phenolic resin supply through long-term benzene derivative contracts, insulating formulation margins from petrochemical feedstock volatility that compresses mid-tier competitors. For New Entrants and Emerging Players: Anchor in India's passenger vehicle aftermarket corridor between Delhi, Mumbai, and Chennai, where Maruti Suzuki and Hyundai Motor India production scaling concentrates replacement demand ahead of electrification penetration. Target sintered brake pad qualification for Australian mining OEMs specifying fifty-thousand-hour service intervals, leveraging powder metallurgy expertise gaps among incumbent suppliers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because REACH chemical restrictions and MIIT emission mandates are eliminating legacy low-cost European and Chinese competitors unable to fund composition redevelopment. Acquisition candidates include mid-tier formulators with ECE R90 testing relationships and sintered capacity serving Western Australian mining operations. Monitor California SB 346 copper reduction compliance timelines as the inflection signal for non-copper formulation technology premiums.| Strategic Initiative | Industry Significance |
|---|---|
| ECE R90 Certification Acquisition | Testing laboratory partnerships in Germany and Italy unlock premium aftermarket channel access. |
| Sintered Capacity Expansion | Powder metallurgy investments satisfy Australian mining OEM fifty-thousand-hour service specifications. |
| Non-Copper Formulation Development | California SB 346 compliance enables continued supply to Detroit-area commercial vehicle fitments. |
| Predictive Maintenance Platform Integration | Digital brake wear monitoring captures replacement timing influence from German fleet operators. |
| Backward Integration into Resin Supply | Captive phenolic production insulates margins from benzene derivative contract volatility. |
Research Methodology
Cross-validation between regulatory filing analysis and trade data anchors the qualitative findings on material qualification timelines and regional procurement patterns. Primary interviews with Tier-1 brake system procurement managers, aftermarket distribution channel heads, mining equipment maintenance directors, and formulation R&D directors combined with secondary validation from EPA stormwater runoff provisions, ECHA SVHC candidate list updates, MIIT emission mandate documentation, and customs trade statistics. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers across automotive production and mining capital expenditure cycles.
Sensitivity analysis on phenolic resin feedstock pricing, para-aramid fiber supply disruption scenarios, and ECE R90 certification timeline extensions shapes the projection framework across the analysis window. Segmentation dimensions span material type, application, product form, and end user, with vehicle class and propulsion architecture cross-cutting automotive demand. CAGRs derive from installed base wear-rate modeling, replacement cycle compression from regenerative braking penetration, and regional production scaling trajectories. Mining haul truck utilization rates and high-speed rail expansion capex in Southeast Asia feed industrial segment forecasts.
Material uncertainties — REACH Annex XVII expansion scope, MIIT brake wear emission stringency acceleration, copper powder supply constraints from Chilean mining disruptions — sit outside the modeled envelope. Forecasts reflect assumptions on electrification penetration rates and aftermarket channel certification enforcement intensity. Practitioners should keep alternative scenarios live as dual carbon targets in China and the EU F-Gas Regulation on process emissions cascade into raw material sourcing constraints and qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Crimped Wire Brushes Market
Industrial Materials
Precipitated Silica Market
Industrial Materials
Industrial Pails and Drums Market
Industrial Materials
GCC Welding Consumables Market
Industrial Materials
Investment Casting Market
Industrial Materials
Grouting Materials Market
Industrial Materials
Global Plastic Fasteners Market
Industrial Materials
Fiberglass Tanks Market
Industrial Materials
Polyurethane Insulation Board Market
Industrial Materials
High Purity Quartz Market
Industrial Materials
2-in-1 Material Rack Correction Machine Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
Tablet Press Tooling Market
Industrial Materials
Isotropic Graphite Market
Industrial Materials
Wire Drawing Dies Market