
 Air Classifiers Market | 2026-2036
Air Classifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Air Classifiers Market Analytics
EU Green Deal industrial emissions benchmarks are consolidating demand for precision particle separation across European cement and minerals processing. Bühler AG leverages its Swiss engineering heritage to dominate food-grade air classification systems. Hosokawa Micron sustains technology leadership in ultrafine powder processing through intensive R&D spending. ALPA Powder Technology anchors supply to China's battery minerals sector with localized manufacturing scale.
Air classifiers are mechanical separation devices that sort particulate solids by size, density, and shape using controlled airflow velocities, typically achieving cut points between 1 and 150 microns depending on rotor speed and air volume. They serve primary industrial purposes in closed-circuit grinding, product de-dusting, and narrow particle-size distribution control for downstream process compatibility. Dry classifiers command the largest installed base in cement and mining applications where moisture-sensitive feedstocks predominate, while air jet classifiers represent the fastest-expanding technology segment as pharmaceutical and battery-material producers demand sub-10-micron precision with minimal contamination risk. Wet classifiers retain defensive positions in mineral sands and iron ore beneficiation where water-based density separation remains cost-optimal.
EPA NESHAP standards for Portland cement manufacturing mandate particulate matter controls that directly specify classifier efficiency thresholds, while REACH chemical safety protocols in Europe restrict dust exposure classifications that shape equipment sealing and exhaust designs. China's MEE enforces ultra-low emissions targets for non-ferrous metals smelters that cascade into classifier procurement specifications. Stakeholders must monitor how tightening PM2.5 regulations across multiple jurisdictions will redefine the trade-off between capital cost and separation precision in greenfield plant design.
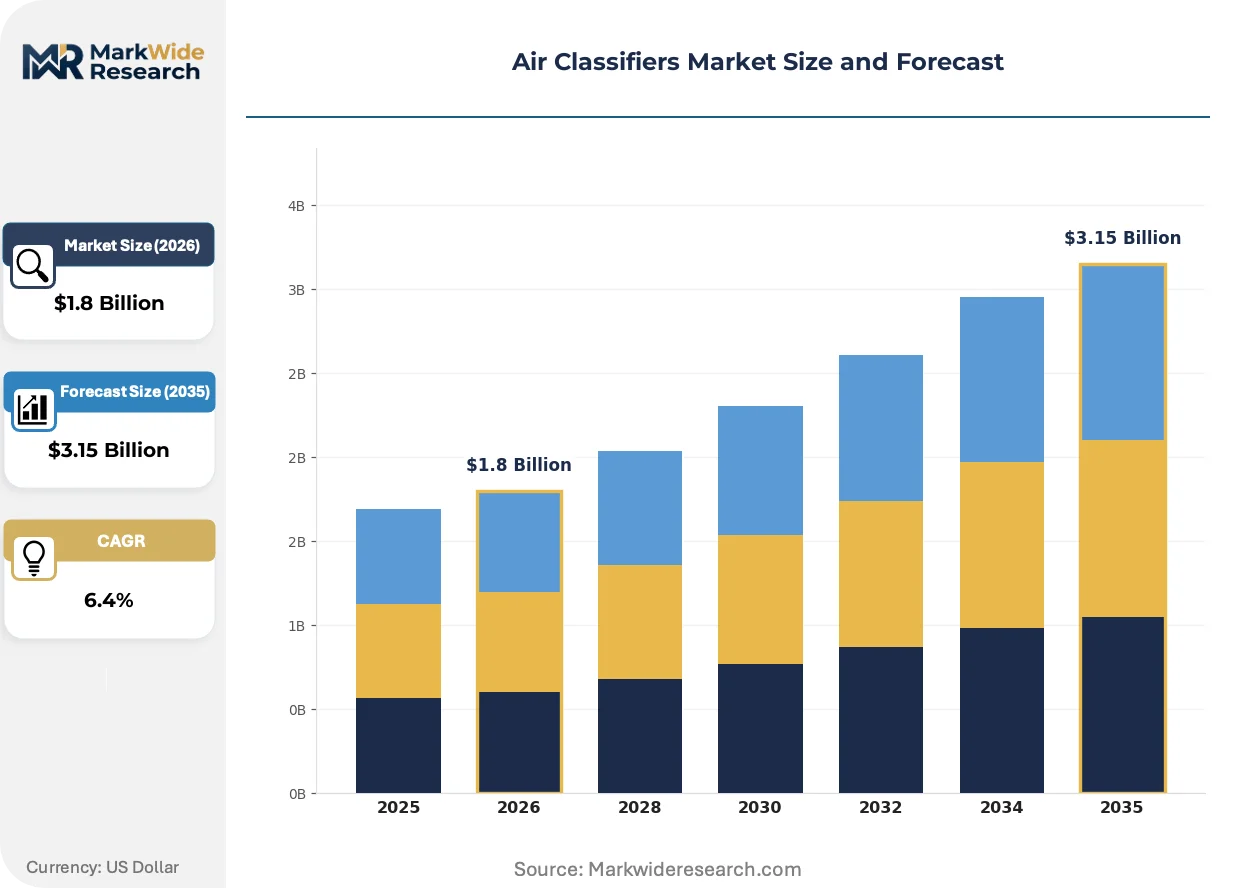
Market Dynamics
Tighter emissions thresholds across cement and battery minerals processing are forcing capital equipment upgrades, with dry classification systems capturing preference over wet alternatives in moisture-sensitive feedstock corridors.
Growth Catalysts
- EU Green Deal industrial emissions benchmarks:Precision particle separation mandates in European cement and minerals processing are accelerating classifier replacement cycles.
- East Asian mining corridors:Declining ore grades in China and India are elevating fines recovery economics, concentrating dry classifier demand in these extraction zones.
- Battery-grade powder specifications:Cathode material producers require sub-10-micron cut point consistency, pulling air jet classifier adoption in lithium-ion supply chains.
Market Restraints
- Rotor and classifier wheel alloys:Nickel and cobalt price volatility in specialty steel inputs compresses equipment margin structures unpredictably.
- German precision component suppliers:Concentration of high-speed bearing and drive assembly manufacturing in Central Europe creates single-source vulnerability.
- Wet classifier incumbency:Mineral sands and iron ore beneficiation operations resist dry system conversion where water-based density separation maintains cost superiority.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Domestic battery material production incentives are opening greenfield classifier procurement windows.
- Pharmaceutical continuous manufacturing:FDA Process Analytical Technology frameworks favor integrated classification-milling systems over batch processing.
- Digital twin integration:Real-time rotor speed and airflow optimization via IoT sensors is creating aftermarket service revenue pools.
Industry Challenges
- Computational fluid dynamics expertise:Shortage of simulation specialists capable of modeling turbulent particle-laden flows delays custom classifier design cycles.
- EPA NESHAP compliance documentation:Portland cement producers face extended certification timelines for particulate matter control verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Classifiers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Wet Classifiers, Dry Classifiers, Air Separators, Sieving Machines Application: Cement Industry, Mineral Processing, Chemical Manufacturing, Food Processing End User: Construction, Chemicals, Pharmaceuticals, Mining Technology: Cyclone Classifiers, Spiral Classifiers, Air Jet Classifiers, Gravitational Classifiers |
| Companies Covered | Bühler AG, Prater Industries, Hosokawa Micron, Kason Corporation, Sturtevant Inc., Metso Outotec, GEA Group, ALPA Powder Technology, NETZSCH Grinding & Dispersing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Classifiers Market Evolving Landscape
Active classification control systems are displacing fixed-speed mechanical designs, with sensor feedback loops enabling real-time cut point adjustment that responds to feedstock variability without manual intervention.
Multi-wheel air jet classifier architectures are overtaking single-rotor designs in battery material processing. Cathode precursor manufacturers in South Korea and Japan are adopting these systems to achieve sub-5-micron precision with reduced contamination risk. This architecture is overtaking conventional centrifugal designs in premium powder applications where narrow particle distribution directly determines electrochemical performance.
China's MEE ultra-low emissions targets for non-ferrous metals smelters are cascading into classifier procurement specifications that exceed historical efficiency thresholds. Equipment vendors must now document PM2.5 capture rates above 99.9% to qualify for state-owned enterprise tenders. Battery minerals and rare earth processing facilities in Jiangxi and Inner Mongolia are retrofitting exhaust systems to meet these tightened benchmarks.
Service contract unbundling is fragmenting traditional bundled maintenance agreements. Cement producers in Germany and Poland are separating spare parts procurement from technical support, driving aftermarket specialists to compete on component availability rather than field service coverage. This pattern is most visible in Central European brownfield installations where in-house maintenance capabilities have matured.
Air Classifiers Market Segmentation
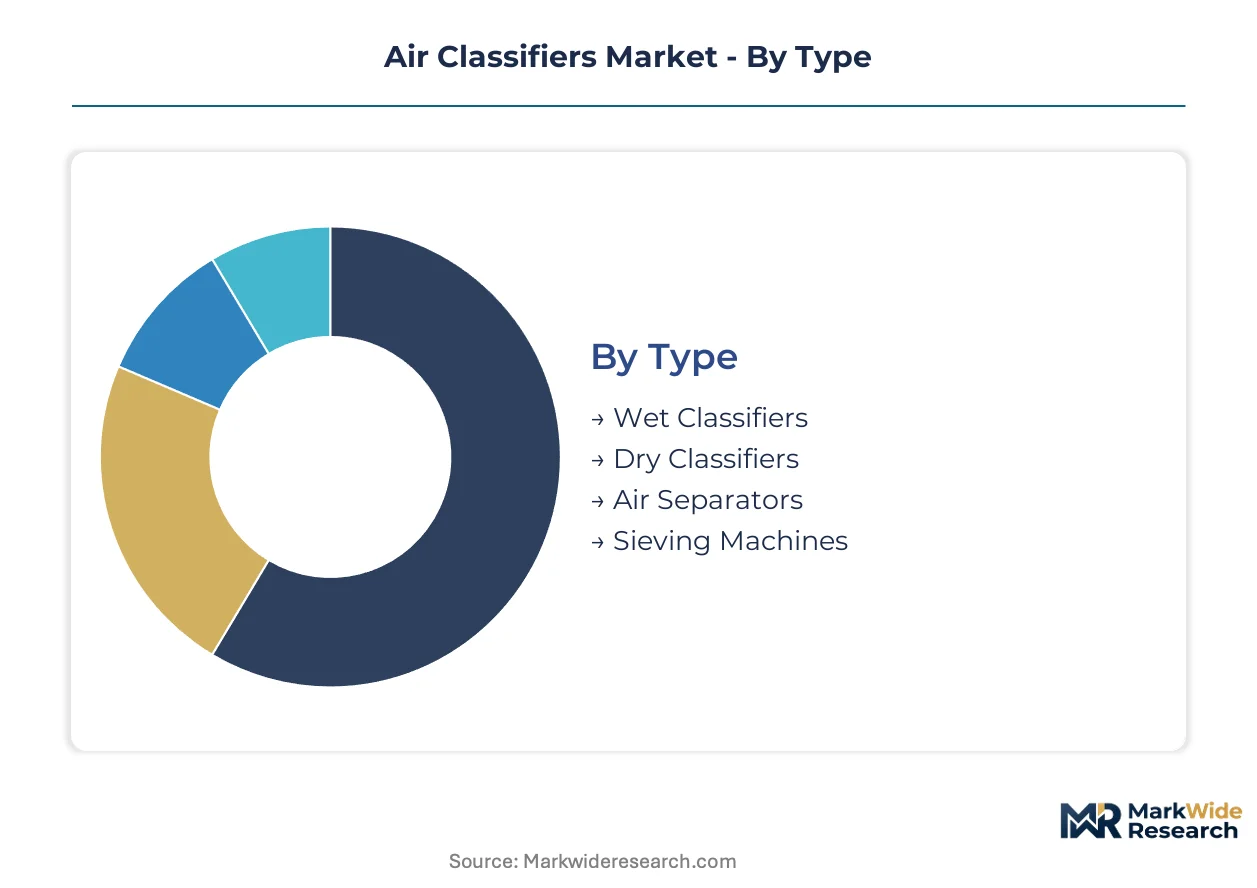
Equipment specification and end-use process requirements fragment the air classifiers landscape into distinct procurement categories. Each segmentation axis reveals different competitive dynamics, with technology type and application vertical driving the largest pricing spreads across supplier portfolios.
Type:
Supply concentration in dry classification systems reflects their dominance in moisture-sensitive feedstock corridors across India and China.
- Dry Classifiers:Mechanical separation devices utilizing controlled airflow velocities without liquid media, achieving cut points between 1 and 150 microns. Cement producers in India and China specify these systems under tightened MEE and EPA emissions rules where water contamination risks exclude wet alternatives.
- Air Separators:Precision airflow-based units designed for closed-circuit grinding applications with integrated fan systems. Battery material processors in South Korea and Japan demand sub-10-micron cut point consistency from these units for cathode precursor manufacturing.
- Wet Classifiers:Density-based separation systems employing water slurries for mineral sands and iron ore beneficiation where water-based economics retain cost superiority.
- Sieving Machines:Mechanical screening equipment for coarse particle ranges above 150 microns in food processing and construction aggregate applications.
Today's leader: Dry Classifiers. Tomorrow's challenger: Air Separators.
Application:
Cost tier differentiation separates premium precision applications from bulk commodity processing in this segmentation axis.
- Cement Industry:High-volume particulate control systems for Portland cement manufacturing requiring EPA NESHAP compliance documentation. German and Polish producers are unbundling service contracts for brownfield classifier retrofits.
- Mineral Processing:Fines recovery systems for declining ore grades in East Asian mining corridors where economics now justify sophisticated separation investments.
- Chemical Manufacturing:Contamination-resistant designs for specialty chemical production with REACH-compliant sealing and exhaust configurations.
- Food Processing:Hygienic air classification meeting EU food safety protocols, with Swiss engineering heritage commanding premium positioning.
Cement Industry anchors current procurement volumes. Battery-grade powder specifications in chemical manufacturing are climbing the fastest.
End User:
Customer type maturity determines specification complexity, with pharmaceutical and battery material producers demanding the most intensive technical validation.
- Mining:Large-scale dry classification installations across Chinese and Indian extraction zones where declining ore grades elevate fines recovery economics.
- Construction:Cement industry procurement driven by capacity expansion under tightening emissions benchmarks in India and China.
- Chemicals:Specialty material processors requiring REACH-compliant equipment designs with documented PM2.5 capture thresholds.
- Pharmaceuticals:FDA Process Analytical Technology frameworks favor integrated classification-milling systems for continuous manufacturing transitions.
Mining dominates installed base. Pharmaceuticals represents the steepest expansion trajectory.
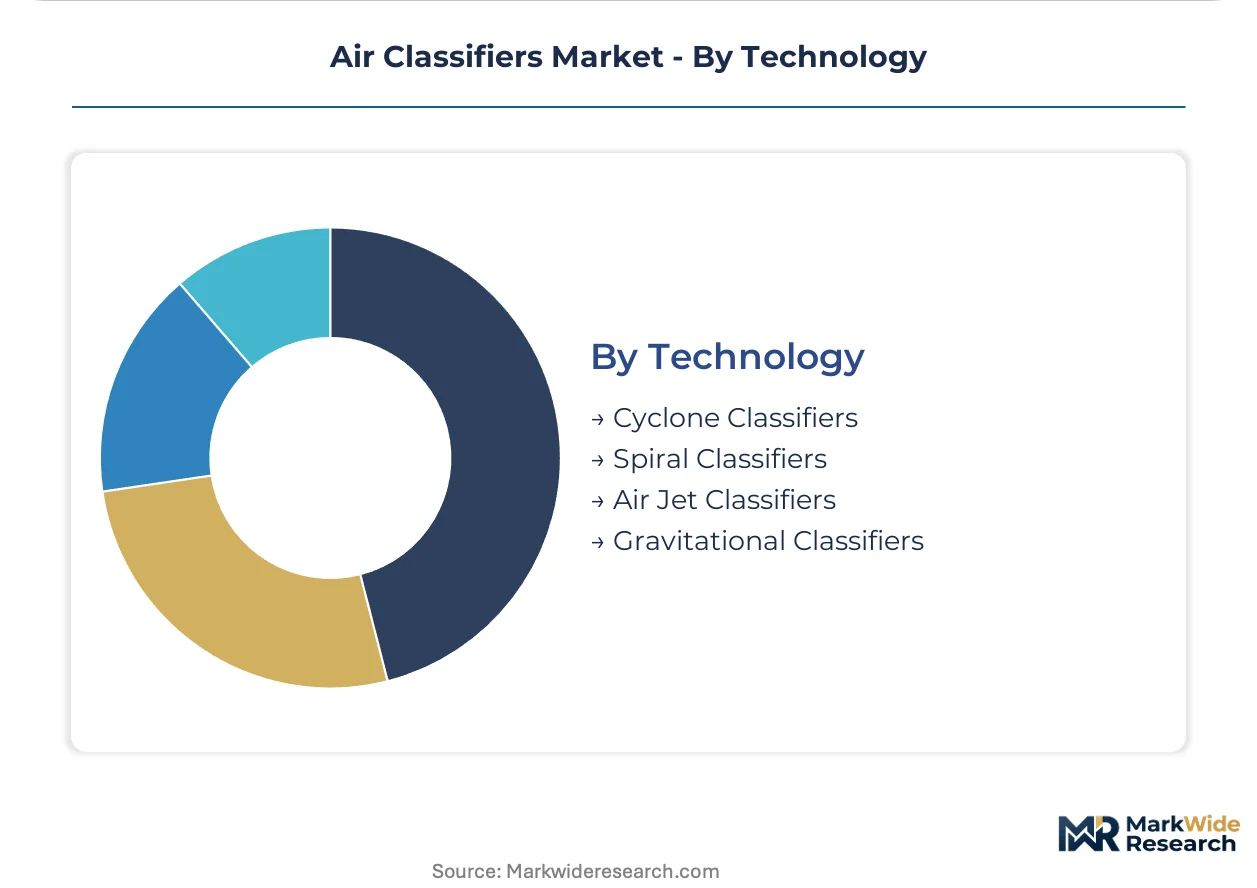
Technology:
Volume concentration in cyclone and spiral designs contrasts with margin concentration in precision air jet architectures.
- Air Jet Classifiers:Multi-wheel architectures achieving sub-5-micron precision through opposed jet milling principles. Cathode material producers in South Korea and Japan adopt these for electrochemical performance-critical applications.
- Cyclone Classifiers:Inertial separation devices using centrifugal force in vortex airflow patterns for coarse to medium cut points in cement and mining bulk processing.
- Spiral Classifiers:Gravity-settling equipment with rotating helical blades for mineral sands beneficiation where water-based density separation maintains incumbent positions.
- Gravitational Classifiers:Settling chamber designs for coarse particle separation in construction aggregate and preliminary screening applications.
Cyclone Classifiers hold the largest installed footprint. Air Jet Classifiers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Air classifier technology traces its industrial lineage to German and Swiss precision engineering of the early twentieth century, with centrifugal separation principles refined for cement and minerals processing across Central Europe before diffusion to East Asian manufacturing corridors.
Germany
Cement producers in North Rhine-Westphalia drive brownfield classifier retrofits under EU Green Deal emissions benchmarks. The country's national industrial emissions regulator mandates PM2.5 capture documentation that extends equipment certification timelines. Precision component fabricators in Baden-Württemberg supply high-speed bearing assemblies for multi-wheel air jet architectures.
China
Battery minerals processors in Jiangxi and Inner Mongolia expand fines recovery capacity as declining ore grades elevate separation economics. MEE ultra-low emissions targets for non-ferrous metals smelters cascade into classifier procurement specifications exceeding 99.9% capture thresholds. Cathode material producers in the Yangtze River Delta adopt opposed jet milling systems for sub-5-micron precision.
India
Cement manufacturers in Maharashtra and Gujarat expand kiln capacity under tightening particulate matter controls. The country's production-linked incentive scheme for advanced chemistry cell manufacturing opens greenfield procurement windows for battery-grade powder systems. Mining operations in Odisha's iron ore belts concentrate dry classifier demand where moisture-sensitive feedstocks predominate.
United States
Portland cement producers in Texas and California face EPA NESHAP compliance documentation requirements for particulate matter controls. The national environmental regulator specifies classifier efficiency thresholds that directly shape equipment replacement cycles. Pharmaceutical continuous manufacturing transitions in the Northeast Corridor favor integrated classification-milling systems under FDA Process Analytical Technology frameworks.
Japan
Cathode precursor manufacturers in the Kansai region adopt multi-wheel air jet architectures for electrochemical performance-critical applications. The country's ministry of economy, trade and industry supports precision powder processing R&D that sustains technology leadership in ultrafine separation. Industrial clusters around Osaka and Nagoya concentrate demand for sub-10-micron cut point consistency in lithium-ion supply chains.
Air Classifiers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology precision tiers, with Swiss and German engineering heritage commanding pricing power in food-grade and pharmaceutical applications while Asian fabricators compete on manufacturing scale in bulk minerals processing. The vendor base organizes into three strategic archetypes: precision specialists leveraging intensive R&D spending, diversified industrial conglomerates with integrated process portfolios, and regional scale players anchoring supply to localized mining corridors. Competitive moves concentrate on geographic expansion through distribution partnerships and backward integration into specialty alloy component manufacturing.
Among Swiss and German precision engineering houses, Bühler AG and Hosokawa Micron exemplify the premium-tier archetype built on century-old separation technology lineages. ALPA Powder Technology occupies a position within the China-based scale tier, anchoring supply to domestic battery minerals processing corridors. These three entities represent divergent competitive vectors: heritage-driven precision positioning, R&D-intensive ultrafine specialization, and manufacturing-scale responsiveness to state-backed industrial expansion programs.
| Leading Market Players |
|---|
| Bühler AG |
| Prater Industries |
| Hosokawa Micron |
| Kason Corporation |
| Sturtevant Inc. |
| Metso Outotec |
| GEA Group |
| ALPA Powder Technology |
| NETZSCH Grinding & Dispersing |
| Others |
Value Network & Pricing Analysis
Multi-wheel air jet classifier architectures are reshaping cost economics and supply concentration simultaneously, as cathode material producers in South Korea and Japan demand sub-5-micron precision that only specialized rotor assemblies from Baden-Württemberg fabricators can deliver. This technology transition concentrates margin capture among precision component suppliers while forcing equipment OEMs to absorb alloy price volatility in nickel and cobalt specialty steels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates food-grade Swiss-engineered systems from bulk cement classifiers and commodity mining units. Price differentiation rests on certification grade for EPA NESHAP and MEE compliance, plus after-sales service bundling that German producers are now unbundling. Cost compression in standard-tier dry classifiers is intensifying because Indian and Chinese fabricators are scaling manufacturing capacity. Mining operators in Odisha exhibit highest price sensitivity, while pharmaceutical continuous manufacturing adopters in the Northeast Corridor show lowest.
Supply Chain Analysis
Dual-sourcing requirements for high-speed bearing assemblies are forcing OEMs to qualify secondary suppliers beyond German precision component houses. Geographic supply concentration centers on Germany, China, and Switzerland for finished equipment, with specialty steel inputs drawing from Austrian and Japanese metallurgical sources. Raw material dependencies include nickel-cobalt superalloys, ceramic rotor coatings, and precision-machined drive housings. Single-source vulnerability in Central European bearing manufacturing creates supply chain risk. Distribution runs through direct OEM sales for large cement and mining installations, with aftermarket parts flowing via regional service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage value between EU Green Deal compliance costs in Germany and PLI-subsidized manufacturing scale in India, where battery mineral processing incentives are compressing effective equipment costs for cathode material producers.
For Market Incumbents: Acquire computational fluid dynamics simulation capabilities to shorten custom classifier design cycles threatened by specialist talent shortages. Cement producers unbundling service contracts in Poland and Germany erode recurring revenue; defend by backward integration into ceramic rotor coating production and captive supply of wear components. Capacity addition in Maharashtra and Gujarat anchors position in India's kiln expansion wave. For New Entrants and Emerging Players: Aftermarket specialists separating spare parts from technical support represent the most penetrable channel entry point. Target pharmaceutical continuous manufacturing transitions in the Northeast Corridor where FDA Process Analytical Technology frameworks favor integrated classification-milling systems over batch incumbents. White-space exists in digital twin integration for real-time rotor optimization, with IoT sensor deployment creating service revenue pools independent of equipment sales. For Investors and Strategic Acquirers: Valuations sit cheapest among regional scale players anchoring supply to Jiangxi and Inner Mongolia battery minerals corridors, where MEE ultra-low emissions mandates are forcing retrofit demand. Long-term viability across the analysis window favors precision specialists with demonstrated sub-10-micron cut point consistency in lithium-ion supply chains. The signal to watch is EPA NESHAP enforcement intensity in Texas and California cement corridors, which would accelerate replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Production | Captive supply of nickel-cobalt rotor materials insulates margins from commodity volatility in steel inputs. |
| Digital Twin Integration for Predictive Maintenance | Real-time airflow optimization via IoT sensors creates aftermarket revenue pools beyond equipment sales. |
| Joint Venture with Battery Minerals Processors | Co-development with Jiangxi cathode producers aligns R&D to sub-5-micron precision requirements. |
| Geographic Manufacturing Footprint Expansion | Localized assembly in Maharashtra captures PLI scheme benefits for advanced chemistry cell manufacturing. |
| REACH-Compliant Sealing System Certification | Documented PM2.5 capture above 99.9% qualifies vendors for EU Green Deal industrial emissions tenders. |
Research Methodology
Multiple input streams — technical interviews with plant engineers and maintenance directors, procurement discussions with cement and battery material producers, and regulatory filings with EPA and MEE — were reconciled against secondary validation from customs trade data, SEC equipment supplier disclosures, and EU emissions compliance databases. Bottom-up triangulation across installation counts and top-down cross-check against capital expenditure patterns in cement and mining verticals anchored volume estimates. Primary fieldwork concentrated on brownfield retrofit corridors in North Rhine-Westphalia and greenfield battery mineral processing zones in Jiangxi and Inner Mongolia.
Historical capacity expansion patterns were cross-referenced against expert panel inputs from OEM technical directors and aftermarket service heads to model replacement cycle timing. Segmentation dimensions included technology type, application vertical, end-user maturity tier, and regional regulatory cluster. CAGRs were derived from slope analysis of equipment procurement trajectories across the projection horizon, with specific weighting for battery-grade powder specification tightening in lithium-ion supply chains and EPA NESHAP compliance documentation burdens in Portland cement manufacturing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nickel and cobalt price volatility in specialty steel inputs and to computational fluid dynamics specialist availability for custom design cycles. Deviation in MEE enforcement intensity for non-ferrous metals smelters or in FDA Process Analytical Technology adoption timelines for pharmaceutical continuous manufacturing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Anode Carbon Block Market
Industrial Materials
Industrial Silica Sand Market
Industrial Materials
Metal Molds Market
Industrial Materials
Solid Surface Materials Market
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
Industrial Gaskets Market
Industrial Materials
Magnet Rings Market
Industrial Materials
High Purity Quartz Market
Industrial Materials
Flat Scroll Spring Market
Industrial Materials
Global Industrial Dust Collector Market
Industrial Materials
Modified Wood Market
Industrial Materials
Global Cast Acrylic Sheet Market
Industrial Materials
Diamond Wire Market
Industrial Materials
Tooling Board Market
Industrial Materials
Wood Fiber Insulation Market
Industrial Materials
Fiberglass Tanks Market