
 GCC Welding Consumables Market | 2026-2036
GCC Welding Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Welding Consumables Market Intelligence
Contractors serving megaproject construction is bifurcating from traditional maintenance-provider demand across the GCC welding consumables landscape. Lincoln Electric Holdings Inc. anchors its regional position through extensive distributor networks covering Saudi Arabia and the UAE. ESAB Corporation differentiates via specialized filler wire formulations engineered for high-temperature petrochemical applications. voestalpine Böhler Welding competes on premium electrode portfolios tailored to offshore fabrication standards in Abu Dhabi and Qatar.
Welding consumables encompass electrode coatings, solid and flux-cored filler wires, granular fluxes, and shielding gases formulated with precise chemical compositions to ensure metallurgical integrity under thermal stress. These materials function as the consumable interface in arc welding processes, depositing molten metal to form permanent joints in structural steel, pressure vessels, and process piping. Filler wire commands the dominant value share as infrastructure scale-up drives bulk procurement of copper-coated solid wires and metal-cored alternatives. MIG Welding technology leads volume deployment in automated fabrication yards, while TIG Welding retains premium positioning for precision aerospace repair work and critical root-pass applications.
The Saudi Standards, Metrology and Quality Organization (SASO) enforces conformity assessment protocols that filter non-certified electrode imports from entering Kingdom projects. The UAE's Ministry of Industry and Advanced Technology aligns industrial material specifications with Gulf Standardization Organization harmonized benchmarks, creating a unified compliance threshold across member states. Stakeholders must monitor how Qatar's expanding North Field gas expansion timelines and Kuwait's refinery upgrade cycles reshape procurement concentration among contractor tiers.
Market Dynamics
SASO conformity assessment protocols are compressing import windows for uncertified electrodes while megaproject bundling consolidates purchasing power among tier-one EPC contractors across the Arabian Peninsula.
Growth Catalysts
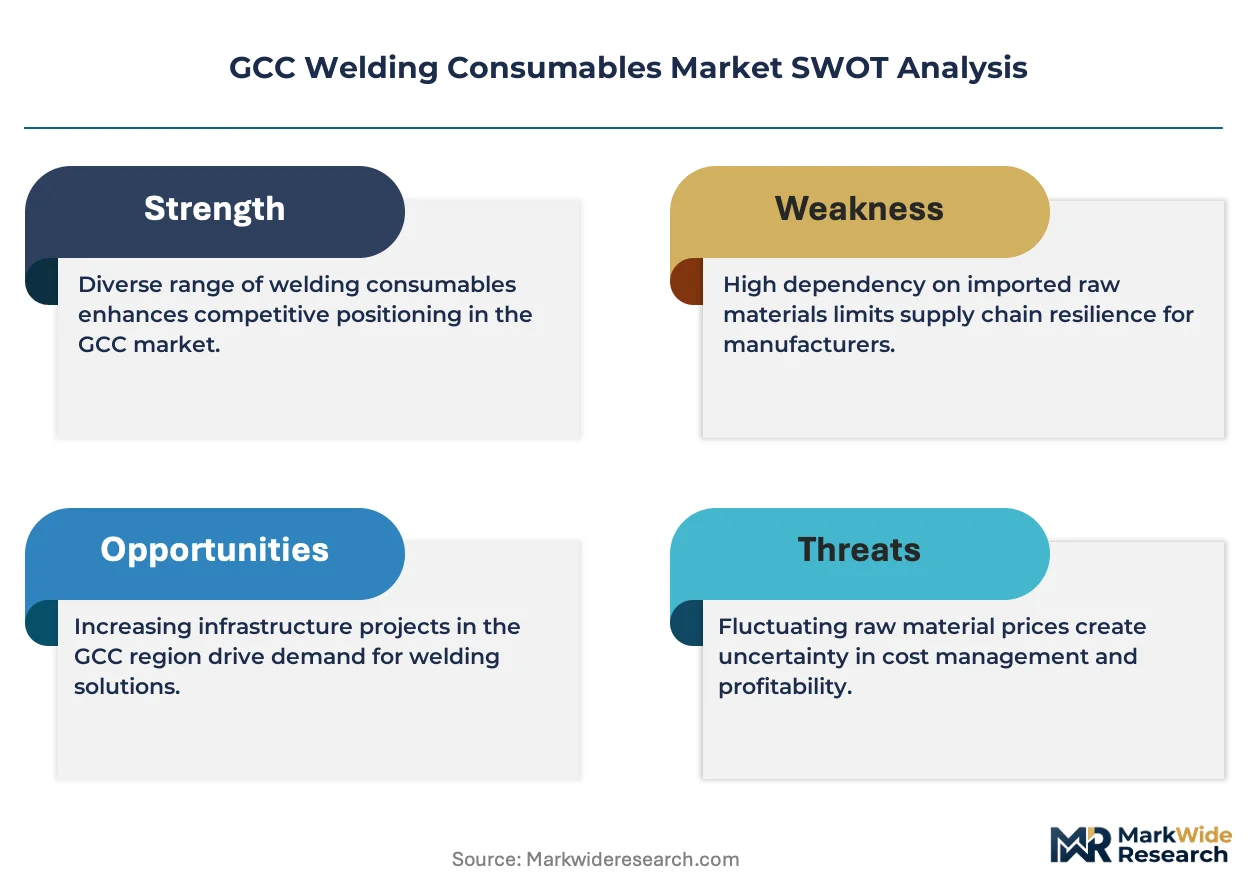
- North Field Expansion Timelines:Qatar's gas infrastructure buildout is accelerating bulk procurement of high-temperature filler wires for pressure vessel fabrication.
- SABIC Compliance Mandates:Saudi Arabia's industrial material certification requirements are filtering substandard imports and elevating certified supplier relationships.
- Flux-Cored Wire Adoption:Automated fabrication yards in Dubai Industrial City are displacing stick electrode workflows with metal-cored alternatives for structural steel deposition.
Market Restraints
- Alloy Input Volatility:Nickel and molybdenum price swings are compressing margin visibility for specialty electrode formulations.
- Supply Concentration Risk:Copper-coated solid wire production clusters in East Asian manufacturing hubs expose GCC distributors to shipping corridor disruptions.
- Shielding Gas Infrastructure Gaps:Limited argon and CO2 distribution networks in Oman's interior regions constrain TIG and MIG process adoption outside coastal zones.
Strategic Opportunities
- Kuwait Refinery Upgrade Cycles:Planned maintenance turnarounds at Al-Zour and Mina Abdullah facilities will concentrate demand for chrome-molybdenum repair electrodes.
- GSO Harmonized Benchmarks:UAE Ministry of Industry alignment with Gulf Standardization Organization protocols is creating unified certification pathways across Bahrain, Oman, and Qatar.
- Robotic Welding Convergence:Integration of collaborative robot arms with pulsed MIG power sources is opening automated repair contracts in Abu Dhabi offshore fabrication yards.
Industry Challenges
- Certified Welder Shortages:Pipeline construction contractors face 6-12 month lead times for ASME Section IX qualified welders in Saudi Arabia's Eastern Province.
- Multi-Tier Compliance Timelines:Navigating SASO technical regulations alongside project-specific Aramco engineering standards extends product qualification cycles for new electrode entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Welding Consumables Market |
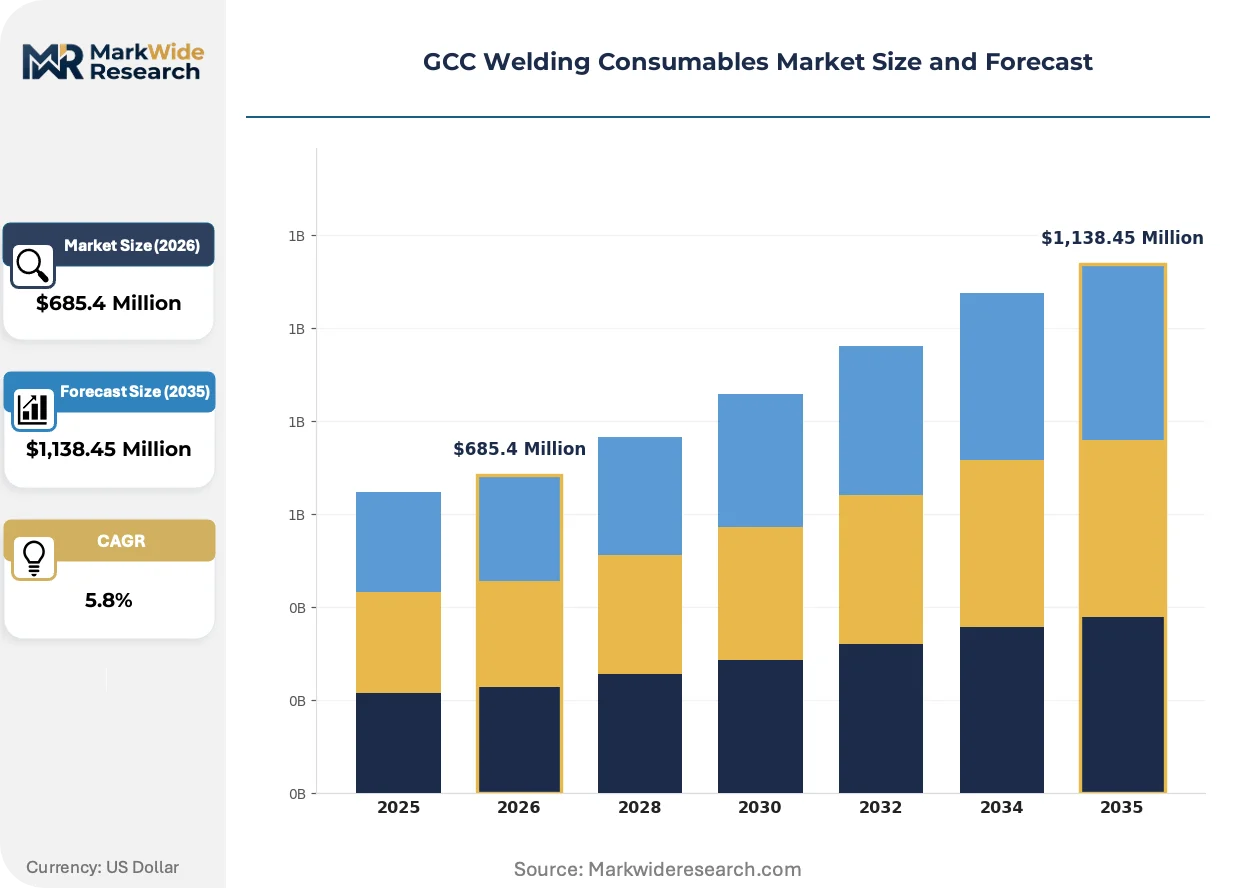
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrode, Filler Wire, Welding Flux, Shielding Gas Application: Automotive Manufacturing, Construction, Shipbuilding, Aerospace Repair Technology: MIG Welding, TIG Welding, Stick Welding, Submerged Arc Welding End User: Manufacturers, Contractors, Maintenance Providers, Educational Institutions |
| Companies Covered | voestalpine Böhler Welding, Illinois Tool Works Inc., Lincoln Electric Holdings Inc., Panasonic Corporation, Air Liquide, ESAB Corporation, Kobe Steel Ltd., Fronius International GmbH, Hyundai Welding Co., Ltd., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Welding Consumables Market Strategic Shifts & Innovations
Automation adoption and regulatory harmonization are compressing traditional procurement cycles while elevating metallurgical performance specifications across GCC fabrication sectors.
Metal-cored filler wire is bifurcating the consumables landscape by separating high-volume automated yards from manual maintenance operations. Shipbuilders in Dubai Maritime City are adopting copper-coated solid wires with enhanced arc stability for robotic positioners. This technology is bifurcating supplier relationships toward technical-service partnerships and away from commodity spot purchasing.
SASO technical regulations now mandate third-party conformity assessment for all structural welding electrodes entering Kingdom projects. Industrial material specifications align with GSO harmonized benchmarks, reducing duplicate testing burdens across UAE, Bahrain, and Oman. Fabrication contractors in Jubail Industrial City are consolidating supplier panels to pre-certified portfolios that satisfy both national and project-specific requirements.
Integrated supply contracts are displacing spot-market purchasing as EPC contractors bundle consumables into lump-sum construction agreements. Tier-one contractors in Qatar's North Field expansion are locking in multi-year electrode supply commitments with volume-price mechanisms. This concentration is most visible in Ras Laffan Industrial City, where Bechtel and McDermott fabrication yards are consolidating procurement through single-source distributor arrangements.
GCC Welding Consumables Market Segmentation
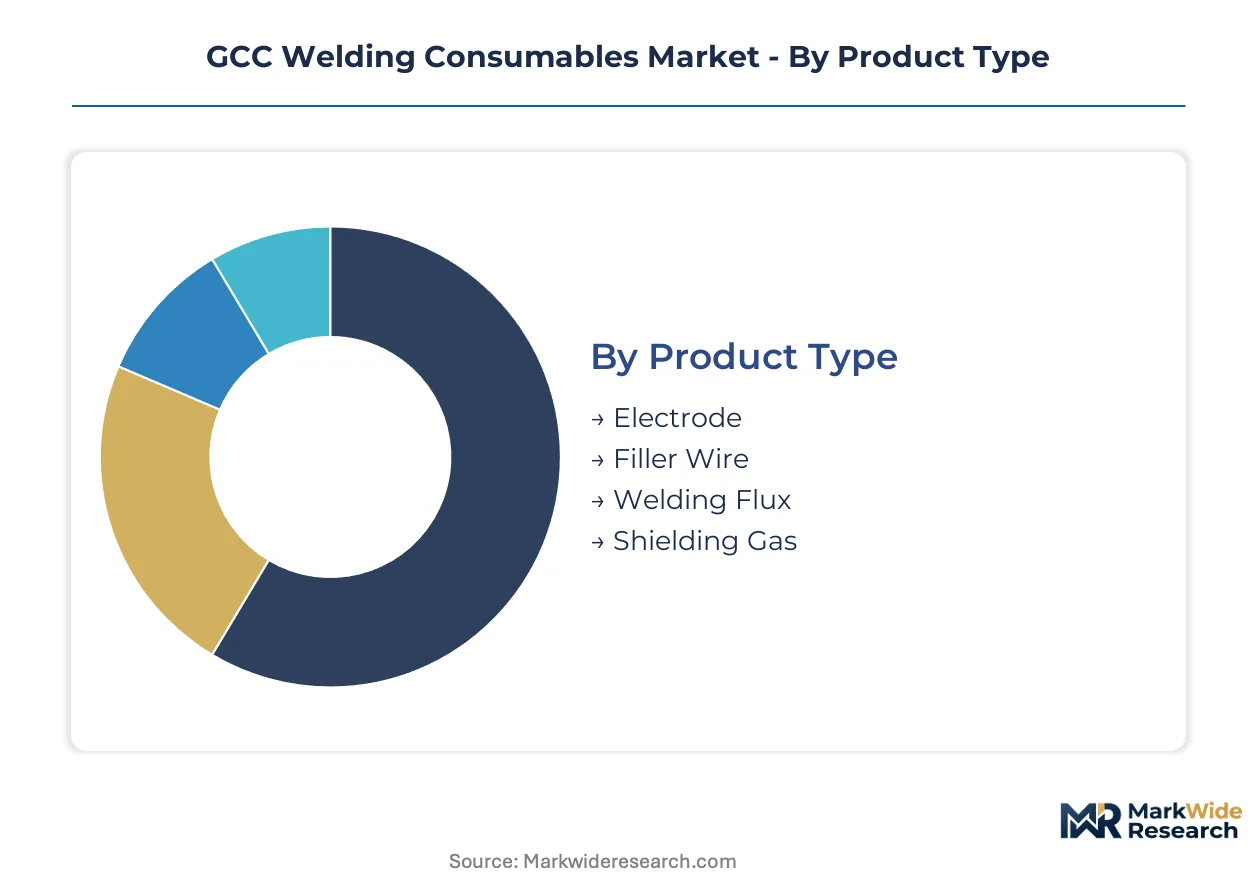
Welding consumables segmentation in the GCC reveals distinct procurement patterns between megaproject construction and maintenance operations. Product type and technology choices diverge sharply across Saudi Arabia's industrial corridors versus UAE fabrication clusters.
Product Type:
Domestic demand concentrates in Saudi Arabia and the UAE, while export-oriented supply flows through Dubai's re-export hubs toward Bahrain and Oman.
- Filler Wire:Copper-coated solid wires and metal-cored alternatives dominate automated fabrication yards. Dubai Industrial City shipbuilders are displacing stick electrode workflows with these materials for structural steel deposition at scale.
- Electrode:Specialty formulations with nickel and chrome-molybdenum alloys serve offshore platform maintenance and pressure vessel repair. SASO conformity protocols now mandate third-party certification for all structural electrodes entering Kingdom projects.
- Welding Flux:Granular fluxes support submerged arc welding in heavy plate fabrication for Qatar's North Field expansion infrastructure.
- Shielding Gas:Argon and CO2 mixtures enable MIG and TIG processes, though distribution network gaps in Oman's interior constrain adoption outside coastal zones.
Filler wire holds the largest share; momentum sits with metal-cored alternatives.
Application:
Cost tier separation distinguishes premium-specification aerospace work from high-volume construction procurement.
- Construction:Megaproject bundling consolidates electrode purchasing among tier-one EPC contractors across Jubail and Ras Al-Khair industrial zones. Integrated supply contracts displace spot-market purchasing as Bechtel and McDermott lock in multi-year commitments.
- Shipbuilding:Dubai Maritime City yards specify copper-coated solid wires with enhanced arc stability for robotic positioners. Technical-service partnerships are replacing commodity spot purchasing in this segment.
- Automotive Manufacturing:Limited regional vehicle production constrains consumables demand to aftermarket repair and component fabrication.
- Aerospace Repair:Precision TIG applications for critical root-pass work command premium positioning, though certified welder shortages extend project timelines.
Construction commands volume leadership; shipbuilding exhibits the steepest expansion trajectory.
Technology:
Customer type bifurcation separates automated yard operators from manual maintenance providers.
- MIG Welding:Pulsed power sources integrated with collaborative robot arms are opening automated repair contracts in Abu Dhabi offshore fabrication yards. Metal transfer efficiency drives adoption in high-deposition structural work.
- TIG Welding:Precision control retains premium positioning for aerospace repair and critical piping root passes. ASME Section IX qualified welder scarcity in Saudi Arabia's Eastern Province constrains deployment.
- Stick Welding:Manual electrode processes persist in maintenance operations and field repair where shielding gas logistics prove impractical.
- Submerged Arc Welding:Heavy plate fabrication for pressure vessels and storage tanks leverages high-deposition rates with granular flux systems.
MIG Welding leads automated deployment; TIG Welding maintains premium-margin positioning.
End User:
Supply concentration varies between consolidated contractor panels and fragmented maintenance procurement.
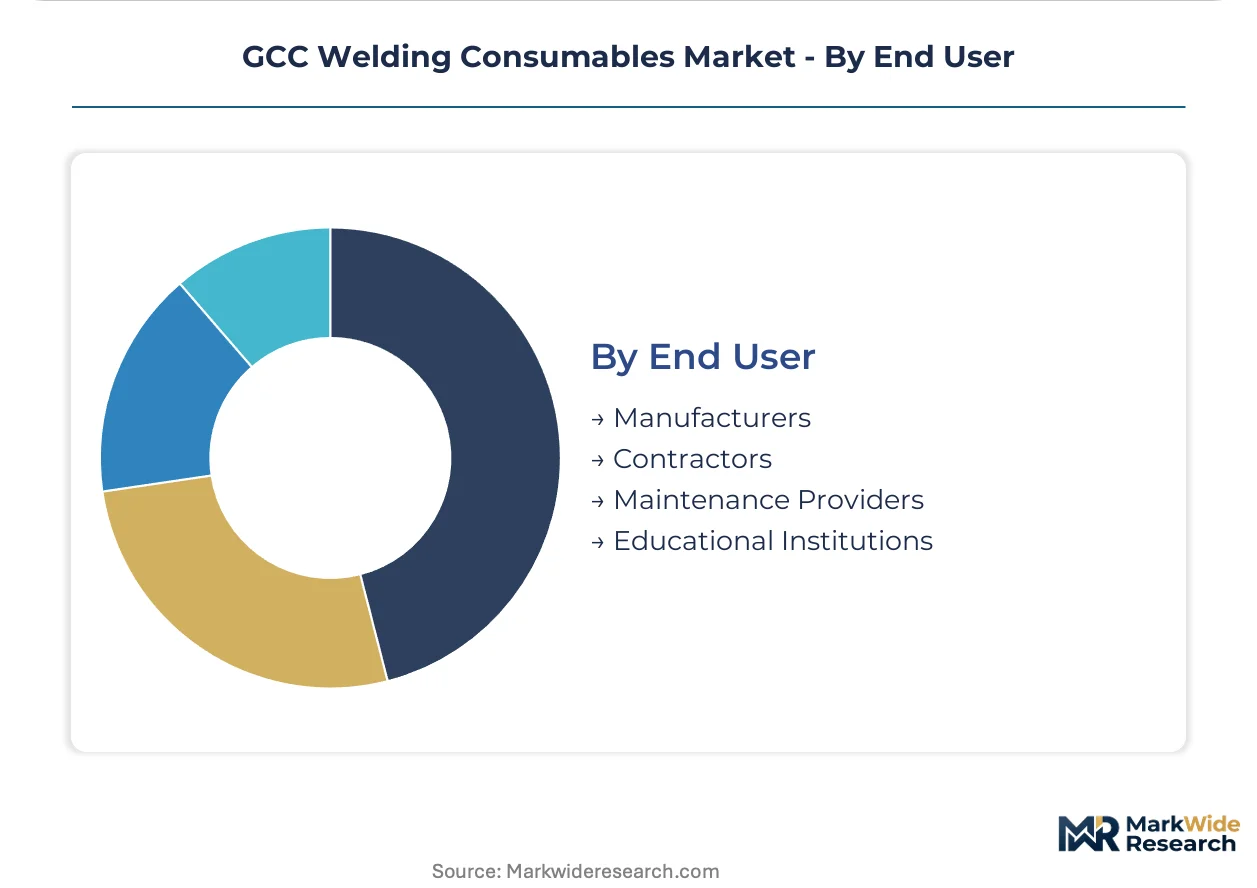
- Contractors:Tier-one EPC firms serving Qatar's North Field expansion and Saudi megaprojects are consolidating supplier relationships through single-source distributor arrangements with volume-price mechanisms.
- Maintenance Providers:Traditional procurement patterns persist for refinery turnarounds at Kuwait's Al-Zour and Mina Abdullah facilities, where chrome-molybdenum repair electrodes concentrate demand.
- Manufacturers:Industrial fabricators in Dubai Industrial City cluster purchasing power through shipyard and heavy fabrication contracts.
- Educational Institutions:Welding training centers support workforce development, though certified welder pipeline gaps persist across the region.
Contractors represent the dominant procurement volume; maintenance providers show expanding replacement-cycle activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's North Field expansion pipeline infrastructure anchors regional demand for high-temperature welding consumables across the GCC fabrication corridor.
Saudi Arabia
Jubail Industrial City and Ras Al-Khair fabrication yards drive electrode procurement for petrochemical infrastructure. SASO conformity assessment protocols now mandate third-party certification for all structural welding materials entering Kingdom projects. Eastern Province contractors face certified welder shortages extending project timelines for ASME Section IX qualified personnel.
United Arab Emirates
Dubai Industrial City shipbuilders displace stick electrode workflows with metal-cored filler wires for automated structural steel deposition. The Ministry of Industry and Advanced Technology aligns material specifications with Gulf Standardization Organization harmonized benchmarks. Abu Dhabi offshore fabrication yards integrate collaborative robot arms with pulsed MIG power sources for automated repair contracts.
Qatar
North Field gas expansion timelines accelerate bulk procurement of chrome-molybdenum filler wires for pressure vessel fabrication. Ras Laffan Industrial City concentrates demand as Bechtel and McDermott yards consolidate procurement through single-source distributor arrangements with multi-year volume-price mechanisms.
Kuwait
Planned maintenance turnarounds at Al-Zour and Mina Abdullah refineries concentrate demand for specialty repair electrodes. The country's national industrial regulator enforces material certification requirements filtering substandard imports from supply chains. Domestic fabrication capacity remains limited, directing procurement toward established distributor relationships with GCC-based suppliers.
GCC Welding Consumables Market Key Industry Players
Listed leaders compete with private specialists across certification depth and technical service capabilities in the GCC welding consumables sector. The supplier base organizes around three strategic archetypes: integrated multinational manufacturers with regional distribution networks, specialized electrode formulators targeting offshore standards, and Asian producers supplying copper-coated solid wires through Dubai re-export channels. Dominant competitive moves include distributor network expansion into Saudi Arabia's Eastern Province and portfolio diversification toward automated welding consumables.
Within the integrated multinational tier, Lincoln Electric Holdings Inc. and voestalpine Böhler Welding occupy positions defined by regional coverage breadth versus premium specification depth. ESAB Corporation exemplifies the specialized formulator archetype through its positioning in high-temperature petrochemical applications. These three companies represent the competitive spectrum from volume-driven construction supply to precision-engineered offshore fabrication materials.
| Leading Market Players |
|---|
| voestalpine Böhler Welding |
| Illinois Tool Works Inc. |
| Lincoln Electric Holdings Inc. |
| Panasonic Corporation |
| Air Liquide |
| ESAB Corporation |
| Kobe Steel Ltd. |
| Fronius International GmbH |
| Hyundai Welding Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Multi-year lump-sum construction agreements with volume-price mechanisms lock in electrode supply access while compressing margin visibility for distributors serving Qatar's North Field expansion and Saudi megaprojects. These bundled contracts concentrate purchasing power among tier-one EPC contractors and filter out spot-market suppliers unable to meet SASO certification timelines.
Pricing Analysis
Three-tier pricing structure across premium certified, standard industrial, and economy import levels separates suppliers by conformity assessment depth. Premium tier pricing rests on SABIC compliance mandates and third-party SASO certification, while economy tiers face compression from nickel and molybdenum alloy input volatility. Price differentiation intensifies as megaproject bundling forces volume discounts on distributors. Maintenance providers in Kuwait's refinery sector exhibit highest price sensitivity due to fragmented procurement, whereas offshore fabricators in Abu Dhabi accept premium positioning for technical-service partnerships.
Supply Chain Analysis
Container availability constraints on Asia-Gulf trade lanes elevate inbound logistics costs for copper-coated solid wire shipments originating from East Asian manufacturing hubs. Production clusters in China, South Korea, and Japan feed GCC demand through Dubai's re-export channels. Raw material dependencies on nickel, molybdenum, and copper coatings expose formulators to commodity price swings. Single-source vulnerability concentrates in East Asian wire coating capacity. Distribution runs through consolidated distributor networks anchored by Lincoln Electric and voestalpine Böhler Welding regional partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from metal-cored wire automation displacing stick electrode workflows across Dubai Industrial City and Jubail fabrication yards. Defense requires locking in technical-service relationships before robotic welding convergence accelerates.
For Market Incumbents: Secure pre-certified electrode portfolios that satisfy both SASO technical regulations and project-specific Aramco engineering standards simultaneously. Deepen technical-service partnerships with automated fabrication yards in Abu Dhabi and Dubai Maritime City before robotic welding convergence accelerates displacement of manual processes. Vertical integration into copper-coated wire production mitigates East Asian supply concentration risk. For New Entrants and Emerging Players: Lead with specialized chrome-molybdenum repair electrode formulations targeting Kuwait's Al-Zour and Mina Abdullah refinery turnaround cycles where incumbent presence remains thin. Concentrate go-to-market efforts on maintenance providers rather than consolidated EPC contractor panels. Exploit shielding gas infrastructure gaps in Oman's interior by packaging electrode-gas bundled solutions for coastal fabricators expanding inland. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap electrode formulators with established SASO certification pathways and existing distributor relationships in Saudi Arabia's Eastern Province. Long-term viability hinges on automation-readiness and regulatory compliance depth rather than commodity volume scale. Monitor robotic welding adoption rates in Abu Dhabi offshore yards as the inflection signal for metal-cored wire demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Wire Production | Captive supply of nickel and molybdenum inputs insulates margins from commodity volatility. |
| SASO Certification Fast-Track Investment | Accelerated conformity assessment timelines unlock Kingdom megaproject procurement panels. |
| Robotic Welding Technical Partnership | Collaborative robot arm integration with pulsed MIG sources secures automated yard contracts. |
| Shielding Gas Distribution Expansion | Argon and CO2 network buildout in Oman's interior enables TIG and MIG process adoption. |
| Refinery Turnaround Service Contracting | Long-term maintenance agreements at Kuwait's Al-Zour facility concentrate chrome-molybdenum demand. |
Research Approach
A standing panel of welding consumables procurement managers at tier-one EPC contractors, distributor network heads, and plant engineers at Jubail and Ras Laffan fabrication yards provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders against secondary validation through SASO technical regulation filings, Gulf Standardization Organization harmonized benchmark documentation, customs import records for electrode categories, and SEC 10-K disclosures from listed manufacturers. Bottom-up demand modeling from end-use applications triangulated against top-down market sizing from trade flow analysis.
Consistency checks validated volume and value outputs against external benchmarks including industrial construction spend data from GCC national statistics offices and petrochemical capacity expansion timelines. Segmentation modeling spanned product type, application, technology, and end-user categories across the projection horizon. CAGRs derived from regression analysis of historical procurement patterns against announced megaproject capital expenditure cycles. Forecast inputs incorporated certified welder pipeline constraints and robotic welding adoption curves specific to regional fabrication yards.
The analysis sits within stated boundaries; outcomes outside sustained oil and gas capital expenditure levels, SASO regulatory enforcement consistency, or East Asian supply chain stability would require recalibration. Forecasts reflect documented assumptions regarding megaproject execution timelines and alloy input price trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Continuous Mesh Belt Furnaces Market
Industrial Materials
Silica Fume Market
Industrial Materials
Food Grade Nylon Market
Industrial Materials
Wire Hoods Market
Industrial Materials
Metal Molds Market
Industrial Materials
Industrial Pails and Drums Market
Industrial Materials
Industrial Gaskets Market
Industrial Materials
Wood Fiber Insulation Market
Industrial Materials
Compression Gas Spring Market
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
Anode Carbon Block Market
Industrial Materials
Global Metal Anodizing Market
Industrial Materials
Steel Bar Magnet Market
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
Static Mixer Market
Industrial Materials
Stainless Steel Cable Ties Market