
 Nitrogen Gas Springs Market | 2026-2036
Nitrogen Gas Springs Market Size, Share, and Industry Trends Forecast 2026-2036
Nitrogen Gas Springs Market Outlook
Germany is rewriting capacity dynamics across European nitrogen gas spring supply as tool-and-die manufacturers expand localized forging and finishing operations. Stabilus GmbH leverages its heritage in precision motion control to sustain premium positioning among German automotive stampers. DADCO anchors North American aftermarket and OEM channels through dedicated die component distribution networks. Suspa GmbH competes on integrated damper-spring systems for machinery builders seeking combined vibration and force management.
Nitrogen gas springs are sealed, self-contained cylinders charged with high-pressure nitrogen gas that exert controlled force through a piston rod, typically operating at pressures between 20 and 180 bar depending on bore diameter and stroke length; they replace mechanical coil springs in metal forming, injection molding, and automation equipment where consistent force delivery and space constraints matter. Compression gas springs dominate installed base volumes across automotive press shops and aerospace fixture applications where standard stroke lengths and high cycle counts define procurement specifications. Adjustable variants capture expanding margin pools in custom tooling and prototype environments where die designers reconfigure force profiles without hardware swaps. Compact designs penetrate machinery OEM builds where envelope dimensions restrict conventional cylinder placement.
German KBA safety requirements for press force limitation, EU Machinery Directive 2006/42/EC conformity assessments, and ISO 10218 robotic integration standards collectively shape product certification burdens and specification rigor for nitrogen gas spring suppliers. REACH chemical compliance and RoHS substance restrictions further constrain seal elastomer and lubricant selections in European supply chains. Stakeholders must monitor how evolving EU Green Deal manufacturing benchmarks and potential carbon border adjustments reshape sourcing decisions for nitrogen gas spring forgings and nitrogen gas supply.
Market Dynamics
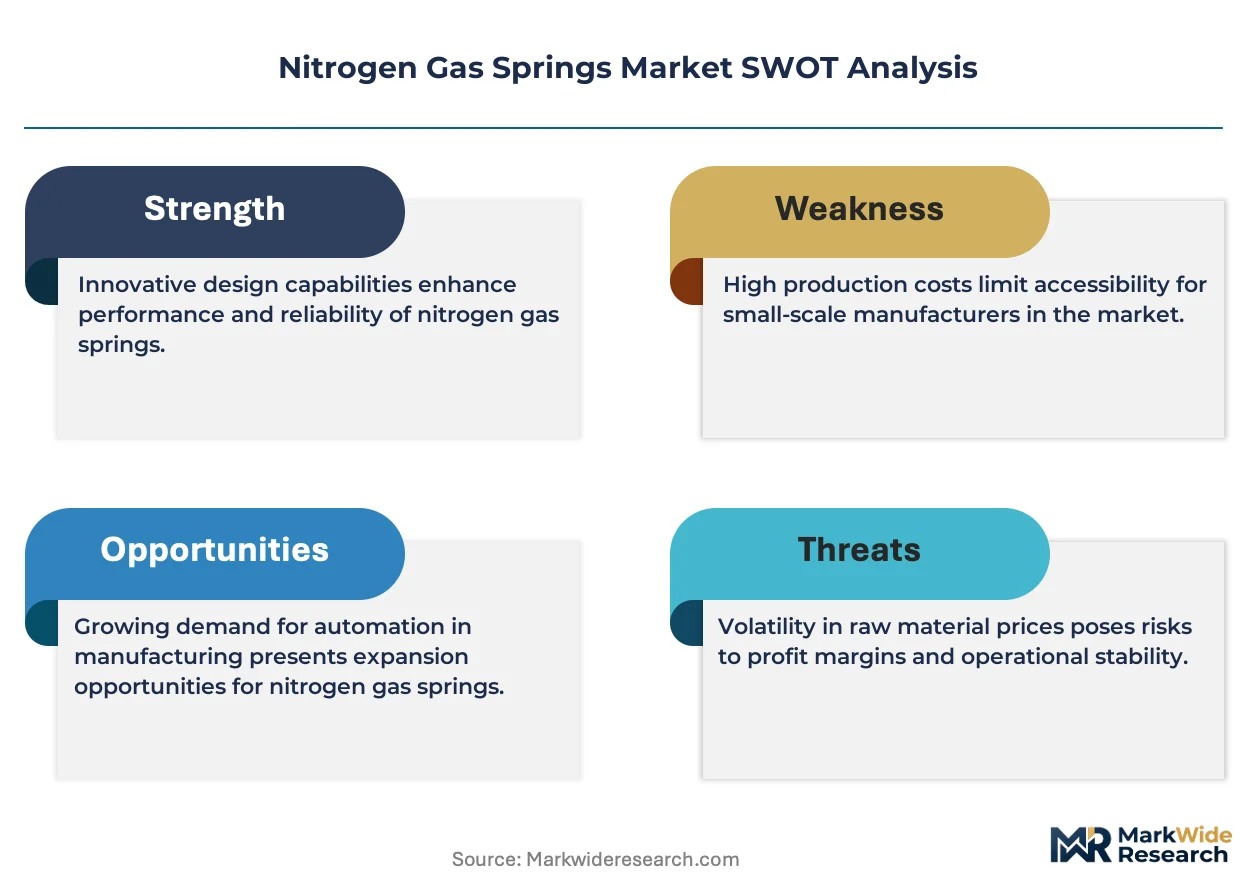
EU Machinery Directive 2006/42/EC conformity assessments are forcing nitrogen gas spring suppliers to redesign seal systems and recertify force-limitation mechanisms, compressing product development timelines and raising barriers for non-integrated competitors.
Growth Catalysts
- Automotive stamping automation:German OEMs expand servo-press retrofits requiring compact adjustable gas springs for programmable force profiles across multiple part geometries.
- REACH chemical compliance:Seal elastomer reformulation mandates in Europe are accelerating adoption of perfluorinated-free compounds that extend service intervals in high-cycle press applications.
- Tool-and-die cluster localization:Stuttgart and Munich industrial corridors concentrate demand for precision-forged gas spring housings serving premium automotive supply chains.
Market Restraints
- Nitrogen gas supply volatility:Industrial gas production concentration in German Ruhr Valley creates input cost exposure for spring charging operations.
- Mechanical coil spring substitution:Low-force fixture applications in cost-sensitive machinery segments retain legacy spring technology.
- ISO 10218 robotic integration standards:Extended certification timelines for force-controlled press tools delay new equipment commissioning.
Strategic Opportunities
- Underpenetrated French aerospace tooling:Toulouse and Bordeaux manufacturing clusters lack localized gas spring finishing capacity for composite forming fixtures.
- Smart sensor convergence:Integration of IoT pressure monitors with adjustable gas springs enables predictive maintenance contracts for automotive stampers.
- EU Green Deal manufacturing benchmarks:Carbon border adjustment mechanisms favor forged components from low-emission European foundries.
Industry Challenges
- Precision machining skill scarcity:Honed cylinder bore finishing requires specialized tool-and-die craftsmanship concentrated in aging German workforce cohorts.
- Legacy press retrofit integration:Mechanical stamping lines built before 2010 lack standardized mounting interfaces for modern compact gas spring designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitrogen Gas Springs Market |
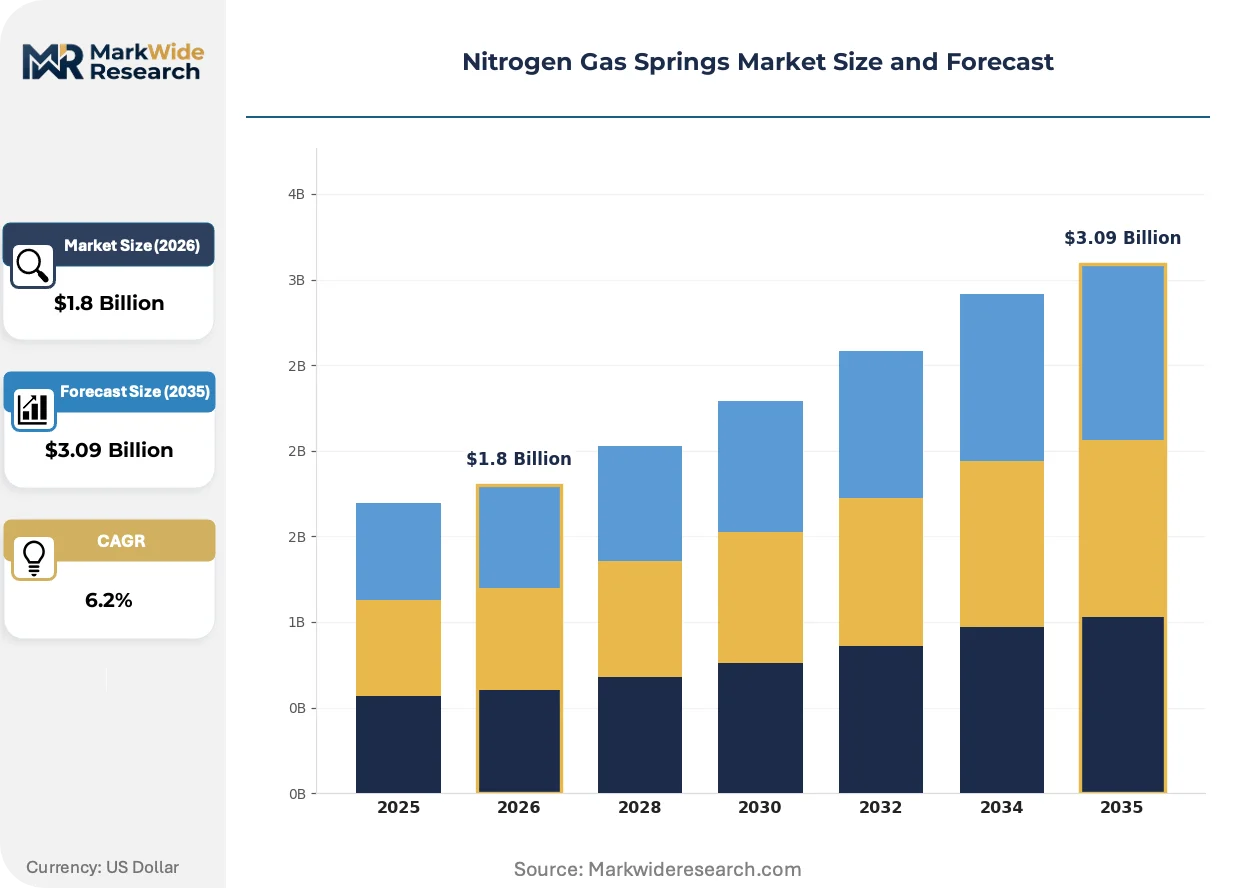
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.09 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression, Tension, Adjustable, Compact Application: Automotive, Aerospace, Machinery, Tooling End User: Manufacturers, OEMs, Maintenance Providers, Assemblers Installation: Standard, Customized, Built-in, Removable |
| Companies Covered | Stabilus GmbH, DADCO, Barnes Group, Suspa GmbH, FIBRO GmbH, ACE Controls Inc., Changzhou Longxiang Gas Spring Co., Ltd., Special Springs, Pascal Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitrogen Gas Springs Market Strategic Shifts
Active materials and regulatory frameworks are compressing traditional product lifecycles while digital integration creates new service revenue models across European tooling supply chains.
Composite piston rod coatings incorporating diamond-like carbon and ceramic matrix layers are hybridizing durability benchmarks in high-velocity stamping environments. Tier-1 automotive suppliers in Germany and Italy specify these surfaces for 10-million-cycle warranties. The technology is hybridizing procurement specifications by merging traditional wear-resistance metrics with predictive sensor compatibility requirements.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon-based lubricants previously used in extreme-temperature gas spring applications. Seal manufacturers reformulate fluoroelastomer compounds to maintain low-temperature flexibility without restricted substances. Aerospace fixture builders in France face the steepest compliance timeline, accelerating qualification of alternative lubricant chemistries.
Tooling procurement teams consolidate vendor relationships around integrated die-component suppliers offering gas springs alongside guides, retainers, and sensors. Traditional specialized spring distributors lose specification influence at major German automotive stampers. This concentration is most visible in Bavaria, where OEM engineering teams reduce approved supplier lists from twelve to four qualified die-component integrators.
Nitrogen Gas Springs Market Segmentation
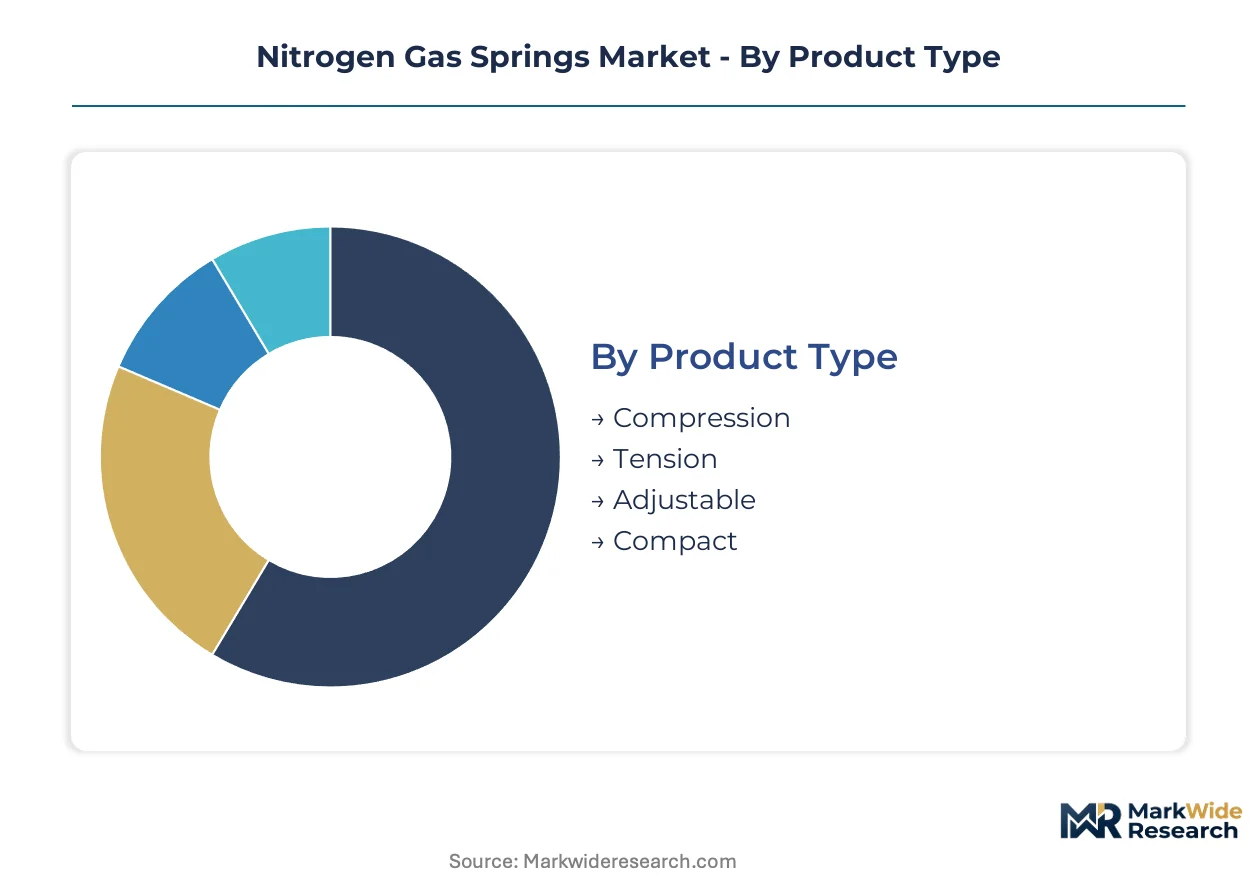
Nitrogen gas spring procurement splits across four distinct axes that reshape supplier strategy and margin capture. Product type determines technical specification rigor, while application and end-user concentration dictate geographic sales deployment and certification burdens.
Product Type:
Mature compression variants anchor installed base volumes across established automotive press shops, while adjustable and compact designs emerge as growth vectors in servo-press retrofits and space-constrained machinery builds.
- Compression:Sealed cylinders with fixed force output dominate high-cycle automotive stamping lines in Germany and Italy where standardized stroke lengths simplify die maintenance protocols. Stuttgart tool-and-die clusters specify these for 10-million-cycle warranties on servo-press retrofits.
- Adjustable:Variable force profiles enable die designers to reconfigure press parameters without hardware swaps, capturing expanding specification share at prototype shops and custom tooling houses in Munich industrial corridors where batch sizes shrink and part geometries diversify.
- Tension:Pull-type actuation serves specialized fixture and clamping applications in aerospace composite forming where rod retraction force must exceed extension resistance.
- Compact:Reduced envelope dimensions penetrate machinery OEM builds where mounting clearances restrict conventional cylinder placement, particularly in robotic press-tending cells governed by ISO 10218 integration standards.
Compression handles the majority of throughput; adjustable is expanding most quickly on specification share as automotive stampers pursue flexible manufacturing.
Application:
Cost tier stratification separates premium aerospace qualification requirements from volume-driven automotive procurement, with machinery and tooling occupying intermediate positions on specification rigor and price sensitivity.
- Automotive:Metal forming operations in German, French, and Italian OEM supply chains drive bulk demand for high-cycle gas springs with predictive sensor compatibility. EU Machinery Directive 2006/42/EC conformity assessments tighten force-control specifications for press tools.
- Aerospace:Composite forming fixtures in Toulouse and Bordeaux manufacturing clusters require precision force control for carbon fiber layup operations, with EU F-Gas Regulation phase-down schedules accelerating alternative lubricant qualifications.
- Machinery:General automation equipment builders specify nitrogen gas springs for consistent force delivery in packaging, assembly, and material handling systems where space constraints displace mechanical coil alternatives.
- Tooling:Die and mold manufacturers integrate gas springs alongside guides, retainers, and sensors, consolidating vendor relationships around qualified component integrators in Bavaria where approved supplier lists contract from twelve to four.
Automotive commands the largest volume commitment; aerospace is climbing the fastest on margin contribution per unit.
End User:
Customer type determines service model intensity, with OEMs demanding predictive maintenance integration and maintenance providers prioritizing interchangeability and aftermarket availability.
- Manufacturers:In-house tool-and-die operations at automotive stampers and aerospace tier-1s specify integrated die-component packages with IoT pressure monitoring for predictive maintenance contracts.
- OEMs:Original equipment manufacturers building new press lines and automation cells drive specification authority, embedding gas spring requirements into machinery procurement standards.
- Maintenance Providers:Aftermarket service operations prioritize standardized mounting interfaces and rapid interchangeability to minimize press downtime during scheduled maintenance windows.
- Assemblers:Contract manufacturing and final assembly operations specify gas springs for fixture and workstation applications where ergonomic force assistance improves operator productivity.
Manufacturers absorb the greatest specification influence; maintenance providers are gaining share fastest as installed base ages and retrofit activity accelerates.
Installation:
Supply concentration in precision machining capabilities favors built-in and customized variants where honed cylinder bore finishing requires specialized German tool-and-die craftsmanship.
- Standard:Off-the-shelf mounting configurations serve replacement demand and new equipment builds where die designers accept conventional envelope dimensions.
- Customized:Tailored stroke lengths, force curves, and port configurations address legacy press retrofits and specialized aerospace fixtures where standardized interfaces prove incompatible.
- Built-in:Permanent integration into die sets and machinery frames requires precision machining during initial tool build, concentrating demand among Stuttgart and Munich industrial corridors with captive finishing capacity.
- Removable:Quick-change mounting systems enable rapid gas spring replacement without die disassembly, prioritizing aftermarket service efficiency and maintenance provider procurement.
Built-in captures the dominant share of initial equipment specification; removable is expanding most quickly as maintenance cost reduction becomes a procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central European nitrogen gas spring logistics, connecting precision machining clusters to North Sea and Mediterranean ports for forged component distribution.
Germany
Stuttgart tool-and-die manufacturers drive specification authority for servo-press retrofits requiring adjustable force profiles. KBA safety mandates for press force limitation compress certification timelines for seal system redesigns. Bavaria's industrial corridor concentrates captive finishing capacity where OEM engineering teams consolidate approved supplier lists from twelve to four qualified integrators.
France
Toulouse and Bordeaux aerospace clusters generate precision demand for composite forming fixtures with carbon fiber layup operations. EU F-Gas Regulation phase-down schedules accelerate alternative lubricant qualifications for extreme-temperature applications. The Auvergne-Rhône-Alpes manufacturing belt lacks localized gas spring finishing capacity, creating supply chain gaps for tier-1 aerospace suppliers.
Italy
Emilia-Romagna automotive stampers expand purchases of compact gas springs for multi-part geometry production lines. EU Machinery Directive 2006/42/EC conformity assessments tighten force-control specifications across press tool procurement. Turin-Piedmont industrial districts anchor high-cycle compression spring demand for legacy mechanical press maintenance.
United States
Detroit automotive OEMs and tier-1 suppliers drive aftermarket demand for standardized mounting interfaces in legacy press retrofits. OSHA machinery safety standards shape force-limitation requirements for automated stamping operations. The Great Lakes manufacturing belt concentrates die component distribution networks serving North American maintenance providers.
Japan
Kansai region machinery builders specify nitrogen gas springs for robotic press-tending cells governed by ISO 10218 integration standards. METI industrial automation incentives accelerate servo-press adoption requiring programmable force profiles. Chubu manufacturing corridors concentrate precision motion control expertise for high-velocity stamping environments.
Nitrogen Gas Springs Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in forging, finishing, and seal manufacturing. The supplier base organizes around three strategic archetypes: diversified motion control conglomerates with heritage precision engineering, dedicated die component distributors with captive North American channels, and specialized damper-spring integrators serving machinery OEMs. Competitive moves concentrate on vendor list consolidation by automotive stampers and geographic expansion of precision machining capacity into underpenetrated aerospace clusters.
Within the heritage precision engineering tier, Stabilus GmbH and Suspa GmbH represent the German Mittelstand archetype of family-rooted motion control specialists. DADCO anchors the dedicated distribution archetype through its North American die component channel focus. These three exemplify how European suppliers leverage proximity to Stuttgart and Munich industrial corridors against emerging competition from Changzhou Longxiang Gas Spring Co., Ltd., which occupies a position among Chinese fabricators serving cost-sensitive machinery segments.
| Leading Market Players |
|---|
| Stabilus GmbH |
| DADCO |
| Barnes Group |
| Suspa GmbH |
| FIBRO GmbH |
| ACE Controls Inc. |
| Changzhou Longxiang Gas Spring Co., Ltd. |
| Special Springs |
| Pascal Engineering |
| Others |
Value Chain & Pricing Dynamics
Nitrogen gas supply volatility in the German Ruhr Valley determines both pricing tier spreads across automotive and aerospace segments and supply chain configuration toward captive charging operations and regional forging clusters. This input cost exposure compresses margins at volume-tier suppliers while rewarding precision machining specialists with long-term contract structures.
Pricing Analysis
Volume-discount tiering structures separate premium-forged adjustable springs from standard compression variants and economy-grade imports. Pricing stratifies across premium, standard, and economy tiers based on certification grade (EU Machinery Directive 2006/42/EC conformity) and bore finishing precision. Cost compression in the standard tier is intensifying because mechanical coil spring substitution retains share in low-force fixture applications. Maintenance providers exhibit highest price sensitivity due to interchangeable part procurement, while aerospace tier-1s prioritize qualification-grade premiums over unit cost.
Supply Chain Analysis
Tariff exposure between Chinese fabricators and European OEMs dominates supply chain risk assessment for cost-sensitive machinery segments. Forged housings concentrate in Germany, Italy, and China; seal elastomers draw from specialized fluoroelastomer compounders in Germany and Japan. The supply chain rests on nitrogen gas charging infrastructure, precision-honed cylinder finishing capacity, and REACH-compliant lubricant formulations. Single-source vulnerability concentrates in Ruhr Valley industrial gas production. Distribution runs through die-component integrators in Bavaria and dedicated aftermarket channels in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against mechanical coil spring retention in cost-sensitive machinery segments, where legacy technology threatens volume-tier nitrogen gas spring displacement.
For Market Incumbents: Pre-empt coil spring substitution by embedding IoT pressure monitoring into adjustable product lines, converting hardware sales into predictive maintenance contracts. Secure captive nitrogen gas charging capacity in Stuttgart and Munich corridors to insulate against Ruhr Valley supply volatility. Consolidate specification influence through die-component integration as Bavarian OEM engineering teams reduce approved supplier lists. For New Entrants and Emerging Players: Build out precision finishing capacity in the Auvergne-Rhône-Alpes manufacturing belt, where French aerospace clusters lack localized gas spring supply. Target composite forming fixture applications in Toulouse and Bordeaux with EU F-Gas Regulation-compliant lubricant qualifications. Penetrate through specialized distributor partnerships rather than direct OEM specification contests. For Investors and Strategic Acquirers: EU Machinery Directive 2006/42/EC recertification timelines reshape the acquisition landscape toward seal system redesign capabilities and force-limitation mechanism expertise. Long-term viability hinges on servo-press retrofit exposure and smart sensor convergence potential. Target precision machining specialists with aging German workforce craftsmanship. Monitor REACH chemical compliance acceleration as the inflection signal for compound reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Seal System Redesign Investment | EU Machinery Directive 2006/42/EC recertification compresses development timelines for compliant force-limitation mechanisms. |
| Smart Sensor Integration | IoT pressure monitoring enables predictive maintenance contracts with German automotive stampers and tier-1 suppliers. |
| Regional Forging Capacity Expansion | Carbon border adjustment mechanisms under EU Green Deal favor low-emission European foundries over import dependency. |
| Alternative Lubricant Qualification | EU F-Gas Regulation phase-down schedules accelerate compound reformulation for extreme-temperature aerospace applications. |
| Die-Component Integration | Consolidated vendor relationships in Bavaria reduce specification influence of traditional specialized spring distributors. |
Study Parameters
A standing panel of tool-and-die procurement managers, maintenance directors at automotive stampers, aerospace fixture engineers, seal compound technical leads, and industrial gas supply specialists provided ongoing calibration. Primary interview insights combined with secondary validation from customs trade data, KBA safety filing records, EU Machinery Directive conformity assessment databases, and SEC filings from listed motion control conglomerates. Bottom-up segment sizing triangulated against top-down industry production estimates.
Scenario-bracketing framed analytical approach across the analysis window, modeling baseline, accelerated servo-press retrofit, and coil spring substitution risk cases. Segmentation dimensions included product type (compression, adjustable, tension, compact), application (automotive, aerospace, machinery, tooling), end-user archetype (manufacturer, OEM, maintenance provider, assembler), and installation configuration (standard, customized, built-in, removable). CAGRs derived from production volume trajectories, equipment replacement cycles, and regulatory compliance investment curves.
Stress conditions across nitrogen gas input cost volatility, REACH chemical compliance acceleration, and precision machining labor scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal manufacturing benchmark evolution and carbon border adjustment implementation scope. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Neon Gas for Laser Market
Industrial Gases
Krypton Gas Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
Welding Shielding Gas Market
Industrial Gases
Gas Purifiers Market
Industrial Gases
Noble Gas Market
Industrial Gases
Argon Gas Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
Commercial Hydrogen Market
Industrial Gases
Sulfur Recovery Tail Gas Analyzer Market
Industrial Gases
Metal Cutting Gas Market
Industrial Gases
Global Industrial Nitrogen Generator Market
Industrial Gases
Syngas Market
Industrial Gases
US Industrial Gas Regulator Market
Industrial Gases
Gas Sampling Line Market