
 Global Graphite Electrodes Market | 2026-2036
Global Graphite Electrodes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Graphite Electrodes Market Foresight
Direct supply contracts between electrode producers and integrated steel mills are reshaping procurement patterns in the graphite electrodes trade. GrafTech International leverages captive needle coke supply to sustain margin stability across volatile raw material cycles. HEG Limited anchors its position through deep vertical integration into carbon precursor refining. Tokai Carbon Co., Ltd. competes on ultra high power product specialization for large-diameter EAF operations.
Graphite electrodes are cylindrical conductive components manufactured from petroleum needle coke and coal tar pitch, baked to temperatures exceeding 2,400°C to achieve electrical resistivity below 5.5 μΩ·m for ultra high power grades. These electrodes transmit massive electrical currents to melt scrap steel in electric arc furnaces, the dominant route for recycled steel production. Ultra high power electrodes command premium positioning due to their superior thermal shock resistance and lower consumption rates per ton of steel output. Needle coke technology leads the feedstock hierarchy because its crystalline structure delivers the mechanical strength required for electrodes exceeding 600 mm diameter. Steel producers represent the concentrated end user pool, with foundries occupying a narrower niche in specialty alloy melting.
The EPA enforces Maximum Achievable Control Technology standards for electrode manufacturing emissions in the United States. REACH and the EU Green Deal impose carbon footprint disclosure requirements on European steel supply chains, indirectly elevating demand for EAF-compatible electrodes. China's MEE operates dual carbon goals that restrict new blast furnace approvals while encouraging electric arc furnace substitution. Stakeholders must monitor how carbon border adjustment mechanisms redefine competitive access across regional steel markets.
Market Dynamics
The steel industry's decarbonization imperative is compressing blast furnace capacity while accelerating electric arc furnace deployments, concentrating electrode demand around ultra high power grades capable of sustaining 700 mm diameter operations at current densities exceeding 25 A/cm².
Growth Catalysts
- EAF Steelmaking Mandates:China's MEE dual carbon goals restrict new blast furnace approvals while subsidizing scrap-based electric arc furnace substitution, redirecting electrode procurement toward domestic Chinese mills.
- REACH Carbon Disclosure:European steel supply chains must document embodied carbon under EU Green Deal frameworks, elevating demand for EAF-compatible electrodes that enable Scope 3 emissions reductions.
- Needle Coke Refining Advances:Petroleum needle coke producers are expanding calcination capacity to supply 600 mm plus diameter electrodes for large-scale EAF operations in India.
Market Restraints
- Needle Coke Supply Concentration:Four petroleum refiners control over 70 percent of premium needle coke output, creating feedstock bottlenecks during steel demand surges.
- Energy Cost Volatility:Graphitization furnaces consume 3,500-4,500 kWh per ton of electrode, exposing producers to natural gas and electricity price spikes in Germany and the United States.
- Silicon Carbide Substitution:Submerged arc furnace operators in ferroalloy production are testing silicon carbide electrodes for lower-amperage applications, threatening niche graphite demand.
Strategic Opportunities
- India EAF Capacity Scaling:Domestic steelmakers are adding 15 million tons of electric arc furnace capacity by 2030, creating concentrated electrode demand in a market with limited local production.
- Carbon Border Adjustment Alignment:European CBAM implementation rewards low-carbon steel imports, incentivizing Middle Eastern and Southeast Asian mills to adopt EAF routes requiring premium electrodes.
- Recycled Needle Coke Recovery:Pyrolysis technologies are emerging to reclaim carbon from spent electrodes, potentially reducing virgin needle coke dependence by 15-20 percent for secondary-grade products.
Industry Challenges
- Graphitization Engineer Scarcity:The specialized workforce required to operate 2,400°C Acheson furnaces is aging, with fewer than 200 qualified engineers available globally for new facility commissioning.
- ISO 9001 Certification Timelines:Steel mill qualification processes for new electrode suppliers require 18-24 months of continuous production trials, delaying market entry for emerging producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Graphite Electrodes Market |
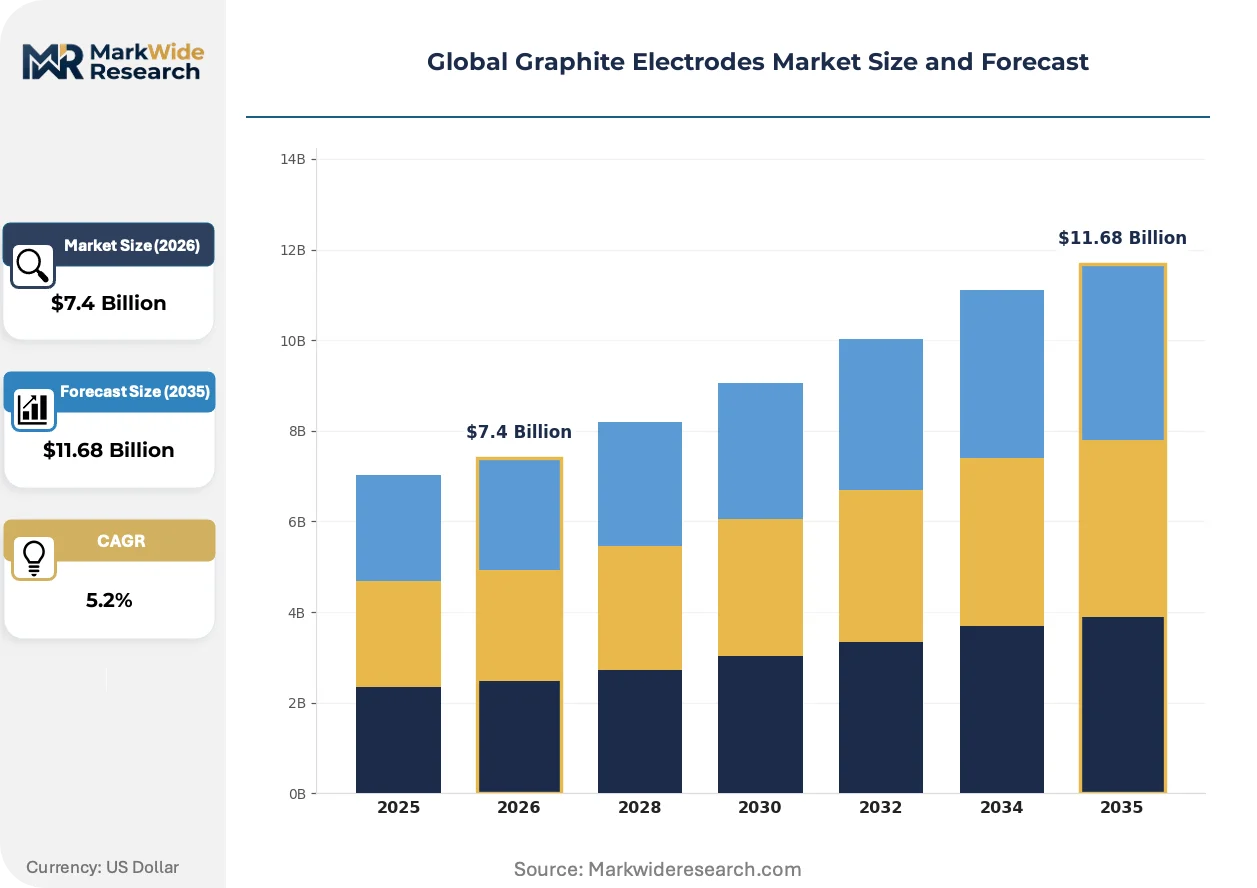
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $11.68 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultra High Power, High Power, Regular Power, Super High Power Technology: Needle Coke, Petroleum Coke, Pitch Coke, Mesophase Coke Application: Electric Arc Furnace, Ladle Furnace, Induction Furnace, Steel Melting Shop End User: Steel Producers, Foundries, Refractory Manufacturers, Carbon Product Suppliers |
| Companies Covered | HEG Limited, Resonac Holdings Corporation, GrafTech International, SGL Carbon, Showa Denko, Tokai Carbon Co., Ltd., Graphite India Limited, SEC Carbon, Ltd., Fangda Carbon New Material, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Graphite Electrodes Market Shifts & Advancements
Electrode manufacturing is pivoting toward predictive quality control and alternative binder chemistries as producers seek to decouple performance from petroleum needle coke supply constraints.
Impregnated pitch technology is rendering obsolete conventional baked electrodes in ultra high power applications. Japanese EAF operators at Tokyo Steel and JFE Steel are adopting impregnated grades for 600 mm plus diameter operations. The technology is rendering obsolete older baking methods that cannot achieve the density required for 30 A/cm² current loads.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons are forcing reformulation of coal tar pitch binders. European electrode producers must certify pitch impregnants below 0.005 percent benzo(a)pyrene content by 2027. German and Austrian mills are accelerating supplier audits to ensure compliance ahead of enforcement deadlines.
Steelmakers are consolidating electrode procurement through multi-year direct supply agreements, bypassing traditional distributor networks. Large integrated mills in India and South Korea are negotiating 36-month contracts with fixed volume floors. This concentration is most visible in India's western steel corridor, where JSW Steel and Tata Steel have shifted 80 percent of electrode purchases to direct producer relationships.
Global Graphite Electrodes Market Segmentation
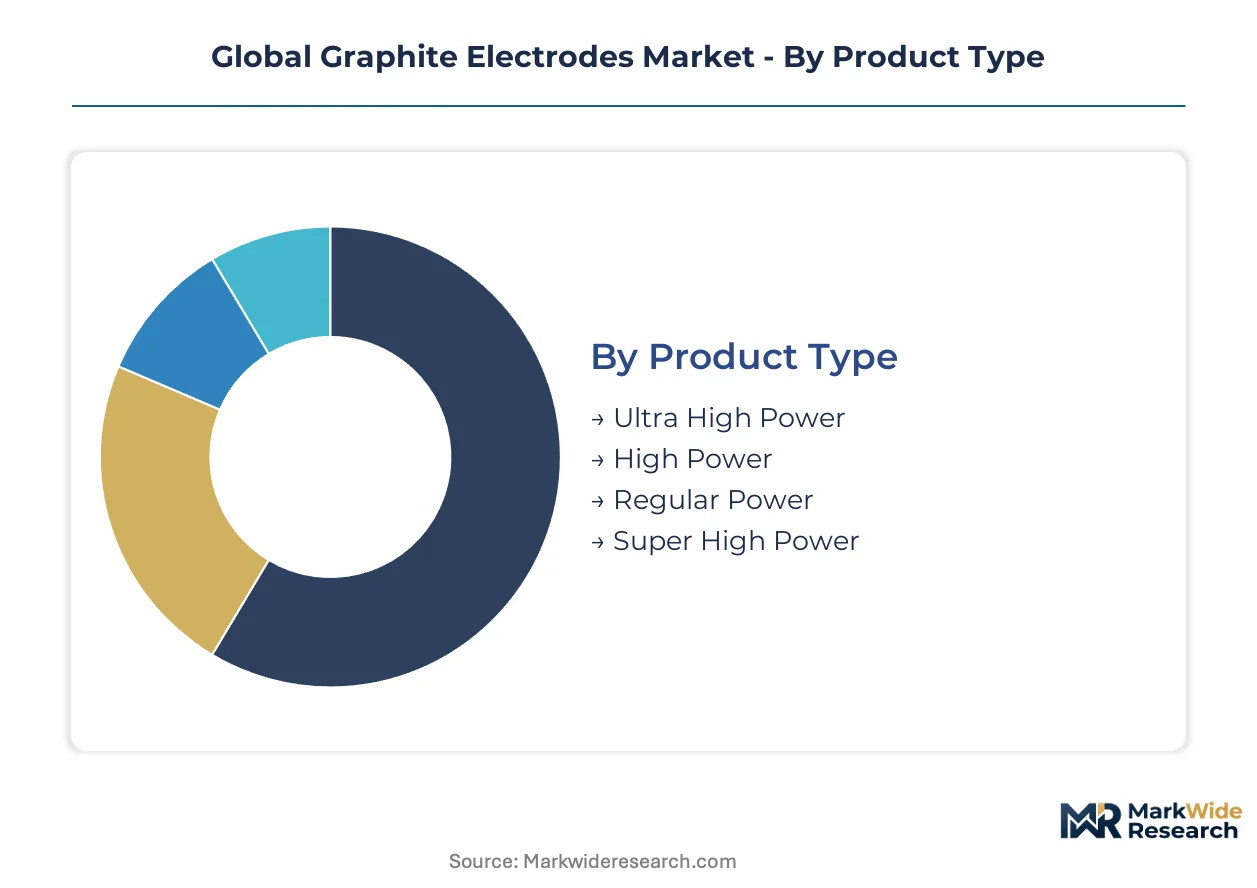
Graphite electrode procurement patterns diverge sharply across product grades and feedstock technologies. Steelmakers calibrate electrode specifications against furnace amperage, scrap quality, and operating cost targets.
Product Type:
Mature ultra high power grades dominate large-diameter furnace operations, while emerging super high power variants target next-generation EAF designs.
- Ultra High Power:Electrodes in this class achieve electrical resistivity below 5.5 μΩ·m through premium needle coke formulations and extended graphitization cycles. Demand concentrates in India where JSW Steel and Tata Steel operate 600 mm plus diameter furnaces requiring 25-30 A/cm² current densities. Indian EAF capacity additions through 2030 are redirecting procurement volumes toward domestic mills.
- Super High Power:These electrodes incorporate enhanced pitch impregnation to sustain current densities exceeding 30 A/cm² in next-generation EAF designs. Japanese operators at Tokyo Steel and JFE Steel are piloting 700 mm diameter installations that stress conventional ultra high power thermal limits. The segment climbs fastest as furnace builders push amperage boundaries.
- High Power:Mid-tier electrodes serve smaller EAF operations and ladle refining stations with moderate current requirements.
- Regular Power:Standard grades address foundry applications and induction furnaces where thermal shock demands are less severe.
Ultra high power electrodes handle the majority of throughput; super high power is expanding most quickly on share.
Technology:
Feedstock hierarchy stratifies by crystalline structure quality and supply security, with cost tiers separating premium needle coke from alternative precursors.
- Needle Coke:Petroleum-derived needle coke delivers the anisotropic crystalline structure required for electrodes exceeding 600 mm diameter. Four refiners control over 70 percent of premium output, creating bottlenecks during steel demand surges. GrafTech International and HEG Limited maintain captive needle coke supply to buffer margin volatility.
- Petroleum Coke:Sponge and shot coke variants serve lower-power electrode grades where mechanical strength requirements relax. Chinese producers blend petroleum coke with needle coke to manage raw material costs amid MEE environmental compliance pressures.
- Pitch Coke:Coal tar pitch derivatives provide binder matrix material and limited anode-grade applications.
- Mesophase Coke:Synthetic mesophase variants target specialty carbon products with controlled thermal expansion properties.
Needle coke anchors volume; mesophase variants show steepest expansion trajectory in niche applications.
Application:
Customer type determines specification rigor, with integrated steel mills driving premium grade demand against foundry tolerance for standard products.
- Electric Arc Furnace:EAF operations consume 70-80 percent of graphite electrode output globally. India's western steel corridor is consolidating procurement through 36-month direct supply agreements, bypassing traditional distributor networks. JSW Steel and Tata Steel have shifted 80 percent of purchases to producer relationships.
- Ladle Furnace:Secondary refining stations require smaller-diameter electrodes for temperature adjustment and chemistry control.
- Induction Furnace:Medium-frequency induction melting in foundry applications employs lower-specification electrodes.
- Steel Melting Shop:Integrated SMS operations combine multiple furnace types with differentiated electrode requirements.
Electric arc furnace applications command the majority of volume; ladle furnace demand is climbing fastest on steel quality standards.
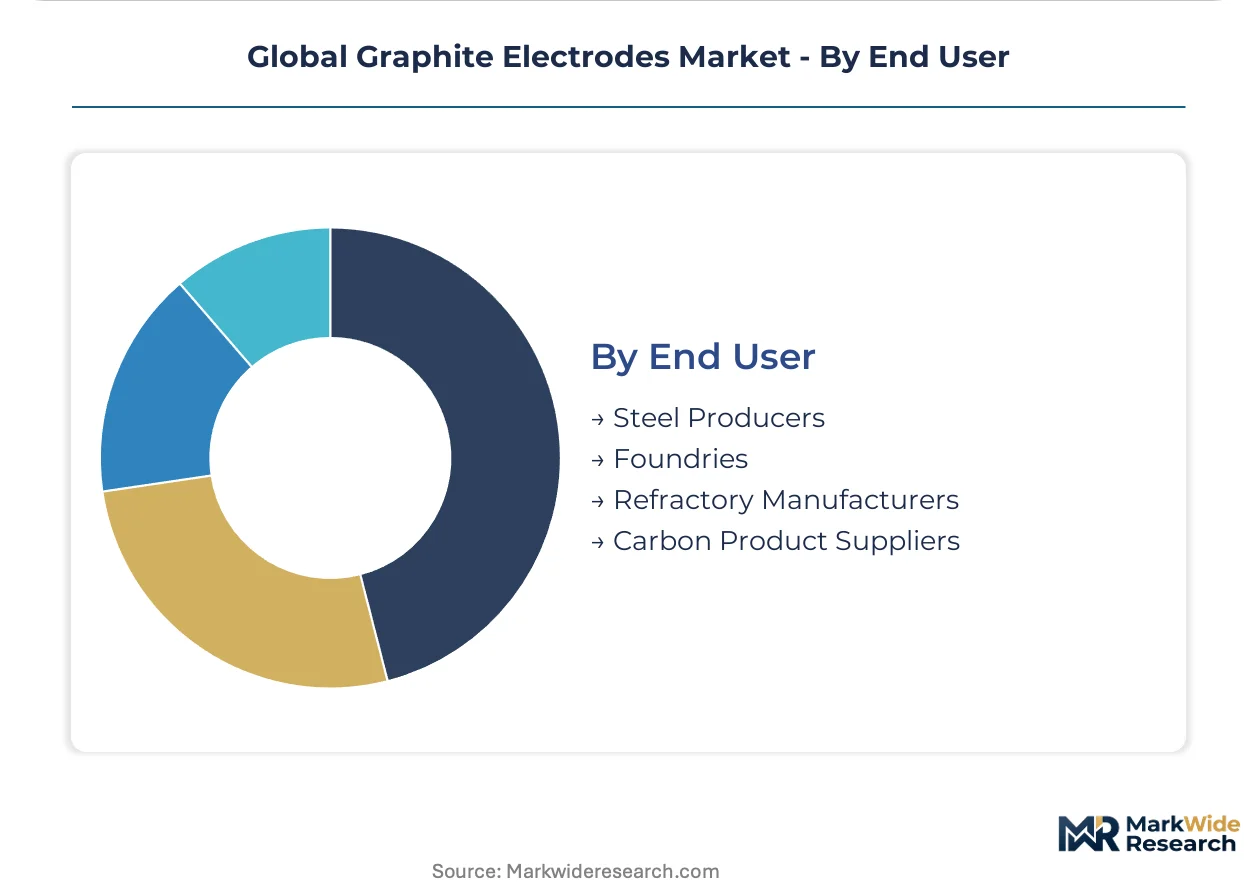
End User:
Volume concentration separates commodity steel producers from specialty alloy and carbon product manufacturers with fragmented procurement patterns.
- Steel Producers:Integrated mills and minimills represent the concentrated demand pool, with procurement shifting toward multi-year direct contracts. European CBAM implementation rewards low-carbon steel imports, incentivizing Middle Eastern and Southeast Asian mills to adopt EAF routes requiring premium electrodes.
- Foundries:Specialty alloy and gray iron foundries occupy a narrower niche with tolerance for regular power grades.
- Refractory Manufacturers:Carbon-containing refractory products consume electrode-grade materials in lower purity specifications.
- Carbon Product Suppliers:Downstream carbon fabricators source electrode materials for machined components and specialty shapes.
Steel producers handle the majority of throughput; carbon product suppliers are gaining share fastest on industrial graphite demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward Indian electrode buyers as domestic EAF capacity scales, while Chinese producers absorb margin compression from MEE environmental compliance costs. German mills face electricity-driven cost premiums that widen spreads against Asian supply.
China
Blast furnace restrictions under MEE dual carbon goals redirect steel investment toward scrap-based EAF routes. The regulator's emissions intensity benchmarks disqualify new basic oxygen furnace approvals in Hebei and Jiangsu provinces. Tangshan steel clusters pivot electrode procurement toward domestic needle coke-integrated suppliers.
India
JSW Steel and Tata Steel drive 15 million tons of announced EAF capacity through 2030. The Ministry of Steel's scrap recycling policy incentivizes electric melting with input tax credits on shredded scrap imports. Gujarat's western steel corridor concentrates direct supply negotiations with electrode producers.
United States
EPA Maximum Achievable Control Technology standards elevate compliance costs for electrode manufacturing emissions. Section 45Q carbon capture credits reward EAF steelmaking investments in Ohio and Pennsylvania. Great Lakes regional mills consolidate procurement through multi-year volume commitments.
Germany
EU Green Deal carbon border adjustment mechanisms penalize imported blast furnace steel. REACH Annex XVII polycyclic aromatic hydrocarbon limits force binder chemistry reformulation by 2027. North Rhine-Westphalia's Ruhr industrial zone hosts qualification trials for low-PAH electrode grades.
Japan
METI supports 700 mm diameter EAF pilot programs at Tokyo Steel and JFE Steel facilities. JIS standards for ultra high power electrodes mandate thermal shock resistance testing above 30 A/cm². Chubu region carbon producers advance pitch impregnation technology for next-generation furnace designs.
Global Graphite Electrodes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream where needle coke supply determines margin stability. Four petroleum refiners control premium needle coke output, creating upstream bottlenecks that downstream electrode fabricators cannot easily circumvent. The competitive terrain stratifies into captive feedstock operators, pure-play electrode manufacturers, and diversified carbon material conglomerates. Capacity expansion and backward integration into needle coke refining represent the dominant competitive moves.
Among needle coke-integrated producers, HEG Limited and GrafTech International exemplify the captive supply archetype that buffers raw material volatility. Tokai Carbon Co., Ltd. occupies a position within the ultra high power specialization tier. These three anchors illustrate how feedstock control and product grade focus separate margin-stable operators from price-takers in cyclical demand periods.
| Leading Market Players |
|---|
| HEG Limited |
| Resonac Holdings Corporation |
| GrafTech International |
| SGL Carbon |
| Showa Denko |
| Tokai Carbon Co., Ltd. |
| Graphite India Limited |
| SEC Carbon, Ltd. |
| Fangda Carbon New Material |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese electrode manufacturing is compressing spot pricing while Indian buyers leverage domestic EAF expansion to negotiate long-term contract discounts. Utilization rates below 70 percent across Hebei and Jiangsu production clusters are forcing exporters to absorb MEE environmental compliance costs rather than pass through to customers.
Pricing Analysis
Configured-to-order pricing for 600 mm plus diameter electrodes commands a 25-35 percent premium over standard catalog grades due to furnace-specific thermal profiling and extended graphitization cycles. Price differentiation rests on needle coke purity tiers and ISO 9001 certification status, with uncertified Chinese imports facing rejection at JSW Steel and Tata Steel qualification gates. Cost compression in regular power grades is intensifying because petroleum coke blending substitutes erode performance guarantees. Small foundry operators exhibit highest price sensitivity, while integrated mills prioritize thermal shock resistance over unit economics.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk planning as New Delhi's DGFT reviews anti-dumping duties on electrode imports. Geographic supply concentration centers on China, India, and Japan, with needle coke feedstock drawing from four petroleum refiners controlling premium output. Raw material dependencies anchor on petroleum needle coke, coal tar pitch binders, and synthetic graphite scrap for secondary-grade blending. Single-source vulnerability persists in large-diameter needle coke where calcination capacity expansion lags EAF deployment timelines. Distribution runs through direct mill-producer contracts that displace traditional distributor networks across India's western steel corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrode procurement fragmentation is accelerating as steelmakers diversify supplier bases beyond incumbent needle coke-integrated majors. India's scrap recycling policy and CBAM-aligned European demand are creating specialized niches for regional producers with captive pitch impregnation capabilities.
For Market Incumbents: Harden margin stability through backward integration into petroleum needle coke refining or binding long-term offtake with calcination operators. Silicon carbide electrode pilots in ferroalloy submerged arc furnaces threaten niche graphite demand, requiring thermal performance differentiation through enhanced pitch impregnation R&D. Capacity addition in Gujarat's western steel corridor secures proximity to JSW Steel and Tata Steel direct contract negotiations. For New Entrants and Emerging Players: Pursue white-space opportunities in recycled needle coke recovery technologies that reduce virgin feedstock dependence for secondary-grade electrode production. India's 15 million ton EAF capacity expansion through 2030 represents the most penetrable geography, with limited local manufacturing creating procurement gaps. Go-to-market positioning should anchor on 18-24 month ISO 9001 qualification support bundled with furnace-specific thermal modeling services. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across super high power electrode sub-segments as 700 mm diameter furnace designs require extended graphitization cycles and specialized Acheson furnace engineering. Long-term viability over the next decade favors producers with captive needle coke supply or exclusive pitch impregnation licensing. Acquisition targets should screen for qualified graphitization engineering talent pools and existing steel mill qualification relationships. The signal to watch is Indian Ministry of Steel scrap policy enforcement tightening that accelerates EAF conversion timelines beyond current capacity announcements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Needle Coke | GrafTech International's captive supply buffers margin volatility during steel demand surges. |
| Pitch Impregnation Technology Licensing | Tokai Carbon Co., Ltd. leverages Japanese EAF operator partnerships for 700 mm diameter validation. |
| Direct Supply Agreement Consolidation | JSW Steel and Tata Steel shifted 80 percent of electrode purchases to producer relationships in Gujarat. |
| Recycled Needle Coke Recovery Scale-Up | Pyrolysis technologies emerging from European REACH compliance investments reduce virgin feedstock exposure. |
| Graphitization Engineer Training Programs | Fewer than 200 qualified Acheson furnace engineers globally constrains new facility commissioning timelines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with electrode procurement managers at integrated steel mills, needle coke refinery operations directors, and carbon materials R&D heads; and secondary validation through customs trade databases, SEC 10-K filings of listed electrode producers, and MEE environmental compliance disclosures. Bottom-up triangulation against top-down market sizing cross-referenced EAF capacity announcements with electrode consumption coefficients per ton of steel output.
Forecast inputs considered product grade segmentation across ultra high power, super high power, high power, and regular power tiers; feedstock technology splits between needle coke, petroleum coke, pitch coke, and mesophase variants; and application dimensions spanning electric arc furnace, ladle furnace, induction furnace, and steel melting shop operations. CAGRs were derived through regression analysis of historical electrode pricing against steel production volumes and EAF penetration rates, incorporating needle coke supply elasticity parameters and energy cost volatility assumptions across Germany and the United States.
Sensitivities concentrate around MEE dual carbon goal enforcement intensity, Indian scrap recycling policy implementation pace, and REACH Annex XVII benzo(a)pyrene limit compliance timelines. Forecasts reflect documented assumptions regarding EAF capacity conversion rates and needle coke calcination expansion schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Flat Enameled Wires Market
Industrial Materials
Saudi Arabia Industrial Insulation Market
Industrial Materials
Thermal Spray Guns Market
Industrial Materials
Silica Fume Market
Industrial Materials
Shrink Tanks Market
Industrial Materials
Extruders and Compounding Machines Market
Industrial Materials
Wood Fiber Insulation Market
Industrial Materials
Industrial Films Market
Industrial Materials
North America Phenolic Insulation Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Mesh Nozzle Plates Market
Industrial Materials
Metal Based Safety Gratings Market
Industrial Materials
Steel Wire Rope and Plastic Rope Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
HV Glass Insulator Market