
 Tension Spring Market | 2026-2036
Tension Spring Market Size, Share, and Industry Trends Forecast 2026-2036
Tension Spring Market Insights
Tool-and-die craftsperson availability is collapsing across Midwestern US manufacturing corridors, forcing tension spring producers to automate coiling and heat-treat lines or relocate near technical colleges. Associated Spring sustains its position through captive wire drawing and in-house shot peening across multiple North American plants. Lee Spring Company competes via an extensive catalog of stock extension springs with same-day shipping from its Brooklyn facility. Peterson Spring anchors automotive programs through direct OEM qualification at Detroit-area assembly plants.
A tension spring is a helical spring designed to store mechanical energy and resist axial pulling forces, typically manufactured from cold-drawn carbon steel or stainless steel wire between 0.005 and 0.625 inches in diameter, with hooks or loops formed at each end for load attachment. Extension springs dominate machinery and automotive applications where controlled return force governs mechanism reliability. Stainless steel variants command premium positioning in medical devices and food-processing equipment due to corrosion resistance requirements under FDA and EU MDR frameworks. Music wire springs occupy a specialized niche in precision instruments where high elastic limit and fatigue life outweigh raw material cost.
US NHTSA crashworthiness standards and EPA material restrictions shape automotive spring specifications, while EU REACH chemical regulations limit hexavalent chromium coatings and drive substitution to zinc-aluminum flake systems. ISO 10243 and JIS B5014 define dimensional tolerances and load-testing protocols that govern cross-border component acceptance. Stakeholders must monitor evolving alloy surcharge mechanisms and dual-carbon regulatory timelines to time capacity investments and material qualification cycles.
Market Dynamics
Automotive lightweighting mandates and electrification timelines are compressing traditional steel spring specifications while pulling advanced alloy and composite alternatives into volume production qualification cycles.
Growth Catalysts
- EU REACH chemical restrictions:Hexavalent chromium coating bans are accelerating zinc-aluminum flake system adoption across European automotive supply chains, creating replacement demand for compliant tension spring inventories.
- Medical device corrosion standards:FDA and EU MDR frameworks for implantable and surgical instruments are expanding stainless steel and titanium spring specifications in precision healthcare equipment.
- Stuttgart-Munich component cluster:German precision manufacturing concentration around tier-one automotive suppliers sustains specialized high-volume demand for fatigue-rated extension springs.
Market Restraints
- Tool-and-die craftsperson scarcity:Midwestern US manufacturing corridors face collapsing availability of skilled coil winding and heat-treat technicians, forcing automation capital deployment or geographic relocation.
- Carbon steel wire price volatility:Alloy surcharge mechanisms tied to scrap and energy indices create margin unpredictability for commodity-grade spring producers.
- Composite leaf spring substitution:Glass-reinforced polymer suspension components in heavy trucking are displacing multi-leaf steel assemblies in specific load-bearing applications.
Strategic Opportunities
- India automotive localization:PLI scheme incentives and BIS certification harmonization are opening domestic supply opportunities for tension spring producers serving Maruti Suzuki and Tata Motors assembly networks.
- Renewable energy maintenance:Wind turbine blade pitch control and solar tracking mechanisms are emerging as high-cycle fatigue applications requiring corrosion-resistant extension spring designs.
- ISO 10243-JIS B5014 convergence:Unified dimensional tolerance standards are reducing cross-border qualification friction for suppliers targeting both European and Japanese automotive OEMs.
Industry Challenges
- Shot peening parameter certification:Automotive OEM direct qualification requirements for residual stress profiles demand capital-intensive process validation and documentation systems.
- Legacy ERP integration:Automated coiling and inline inspection equipment deployment creates data architecture friction with decades-old shop floor management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tension Spring Market |
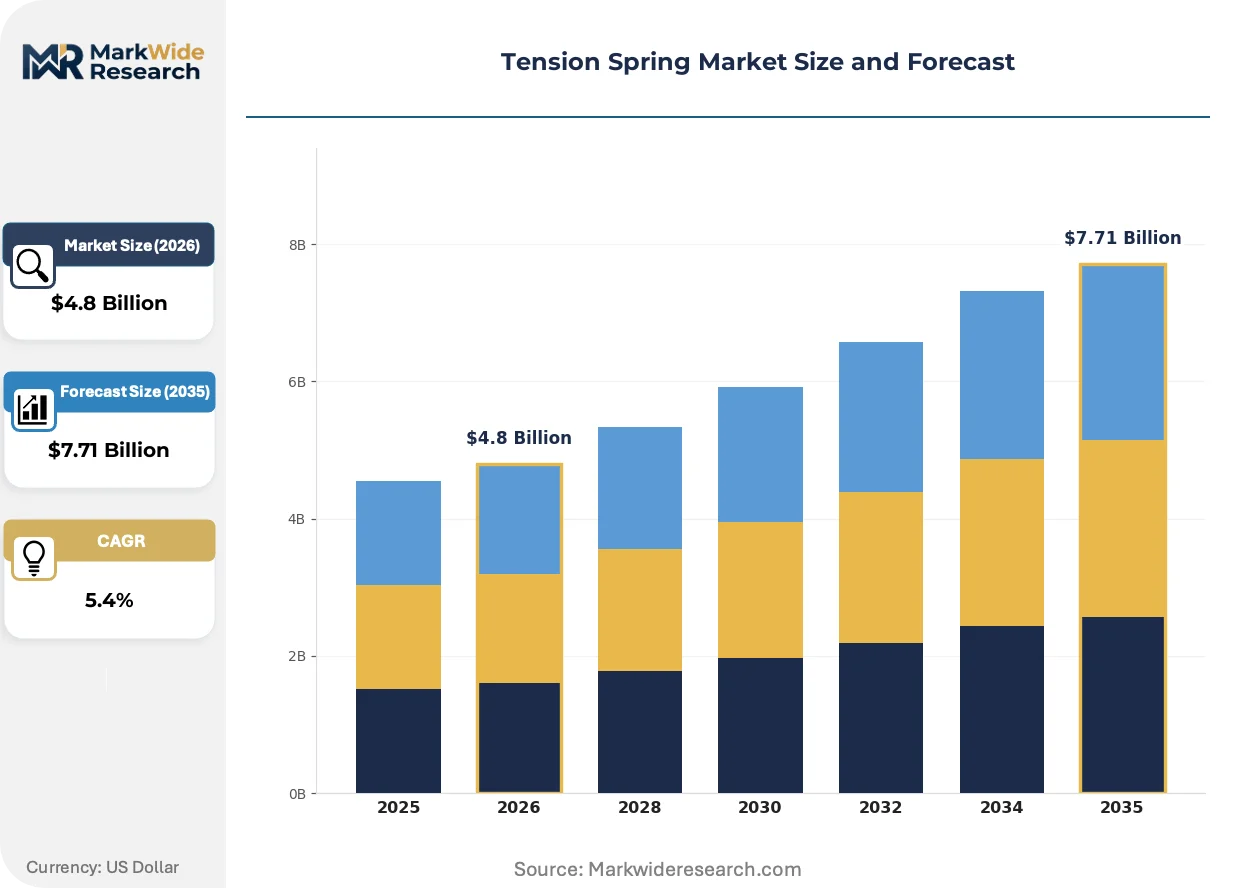
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extension Springs, Compression Springs, Flat Springs, Music Wire Springs Material: Steel, Stainless Steel, Zinc-Plated Steel, Others End User: Automotive, Aerospace, Consumer Electronics, Industrial Equipment Application: Machinery, Furniture, Medical Devices, Sports Equipment |
| Companies Covered | Associated Spring, Spiros Industries, The D.R. Templeman Co., Coiling Technologies, Inc., Fennell Spring Company, Lee Spring Company, Peterson Spring, Spring Dynamics, Lesjofors Springs America, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tension Spring Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are simultaneously enabling higher-performance spring designs while eliminating legacy coating and alloy systems from qualified supplier lists.
High-elastic-limit precipitation-hardened stainless alloys are supplanting traditional music wire in precision instrumentation and medical device applications where magnetic permeability and corrosion resistance outweigh raw material cost premiums. Swiss and German surgical instrument manufacturers are accelerating qualification timelines for these alloys. This substitution is compressing the addressable market for carbon steel precision springs in high-reliability segments.
EU F-Gas Regulation phase-down schedules and REACH authorization requirements for chromium trioxide are forcing coating line conversions to trivalent chromium and zinc-flake systems before 2027 sunset dates. Surface treatment suppliers in Germany and Poland are consolidating qualification batch testing capabilities to serve fragmented spring producer demand. Automotive chassis component suppliers face the steepest compliance timelines and are pre-qualifying dual-source coating arrangements.
Direct OEM technical purchasing is consolidating tier-two spring procurement previously dispersed through distributor channels, with NHTSA crashworthiness documentation requirements driving preference for suppliers with captive testing and finite element analysis capabilities. Detroit-area automotive engineering centers are shortening approved vendor lists to single-digit counts per component category. This concentration is most visible in North American electric vehicle platform launches where spring fatigue life predictions feed directly into vehicle simulation models.
Tension Spring Market Segmentation
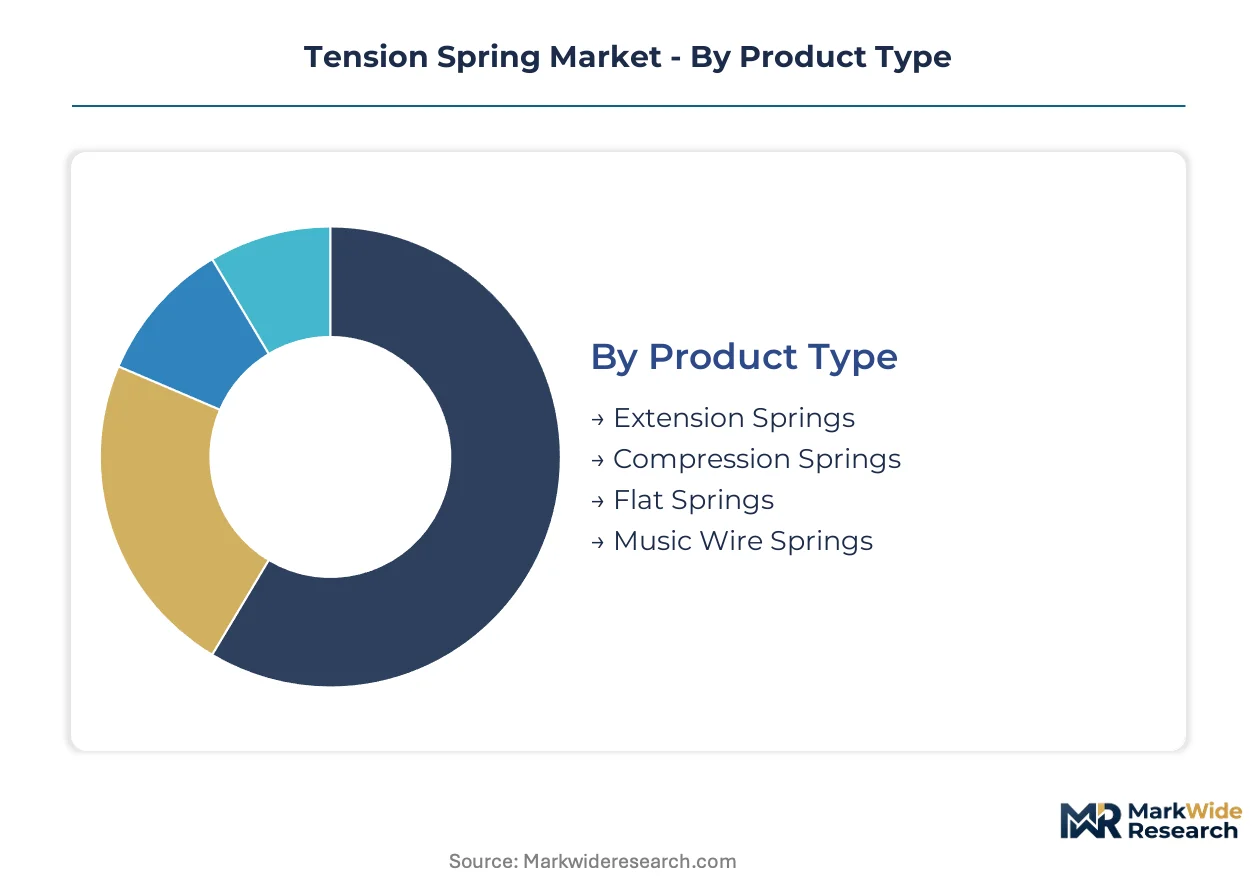
Precision component suppliers configure production lines around spring geometry and load specifications rather than end-use markets. Segmentation reveals how material selection and manufacturing complexity map to channel economics and customer qualification requirements.
Product Type:
Extension springs flow through distributor catalogs and OEM direct channels in roughly equal volume, while flat and music wire variants concentrate in specialized technical procurement.
- Extension Springs:Helical designs with formed end loops resist axial tension across 0.005 to 0.625 inch wire diameters. Demand clusters in German automotive chassis programs around Stuttgart and Munich where tier-one suppliers specify fatigue-rated batches for suspension return mechanisms.
- Compression Springs:Coils wound to resist compressive loads occupy machinery and industrial equipment procurement channels. US Midwest tool-and-die shops source standard catalog sizes through Associated Spring and Lee Spring distributor networks, while automotive programs require direct OEM qualification.
- Flat Springs:Stamped or formed strip configurations serve limited-travel applications in consumer electronics and appliance latches.
- Music Wire Springs:High-carbon steel precision coils command premium positioning in surgical instruments and measurement devices where elastic limit governs performance.
By volume, Extension Springs leads. By growth pace, Music Wire Springs is ahead.
Material:
Cost tier stratification separates commodity carbon steel from corrosion-resistant alloys, with coating systems creating intermediate pricing bands for automotive compliance.
- Steel:Cold-drawn carbon grades dominate high-volume automotive and machinery applications where raw material cost sensitivity outweighs corrosion exposure. Alloy surcharge mechanisms tied to scrap indices create margin volatility for producers serving Detroit-area assembly plants.
- Stainless Steel:Austenitic and precipitation-hardened grades command medical device and food-processing specifications under FDA and EU MDR frameworks. Swiss surgical instrument manufacturers accelerate qualification of nickel-free variants for magnetic resonance compatibility.
- Zinc-Plated Steel:Trivalent chromium and zinc-aluminum flake coatings substitute for banned hexavalent systems under EU REACH phase-down schedules.
- Others:Titanium and Inconel variants occupy aerospace and implantable medical niches requiring extreme corrosion resistance.
Steel commands the volume base. Stainless Steel captures the steepest expansion trajectory.
End User:
Application maturity determines whether procurement flows through consolidated OEM technical purchasing or fragmented maintenance-repair channels.
- Automotive:Chassis, suspension, and powertrain return mechanisms anchor volume demand. NHTSA crashworthiness documentation requirements concentrate procurement among suppliers with captive testing and finite element analysis capabilities.
- Aerospace:Landing gear and control surface applications specify high-cycle fatigue ratings with full material traceability.
- Consumer Electronics:Miniature spring requirements in smartphones and wearables favor Asian contract manufacturers with automated micro-coiling capacity.
- Industrial Equipment:Machinery OEMs and aftermarket distributors source standard catalog configurations with shorter qualification cycles.
Automotive generates the revenue concentration. Aerospace delivers the highest specification premiums.
Application:
Geography and regulatory exposure shape material and coating requirements across machinery, furniture, medical, and sports end-uses.
- Machinery:Industrial automation and agricultural equipment specify carbon steel extension springs with phosphate or oil coatings for moderate corrosion protection.
- Furniture:Reclining mechanisms and office seating components source through Asian contract manufacturers serving global retail chains.
- Medical Devices:Implantable and surgical instrument specifications require stainless steel or titanium with full FDA and EU MDR documentation.
- Sports Equipment:Archery, firearms, and fitness equipment applications span carbon steel economy grades to music wire precision configurations.
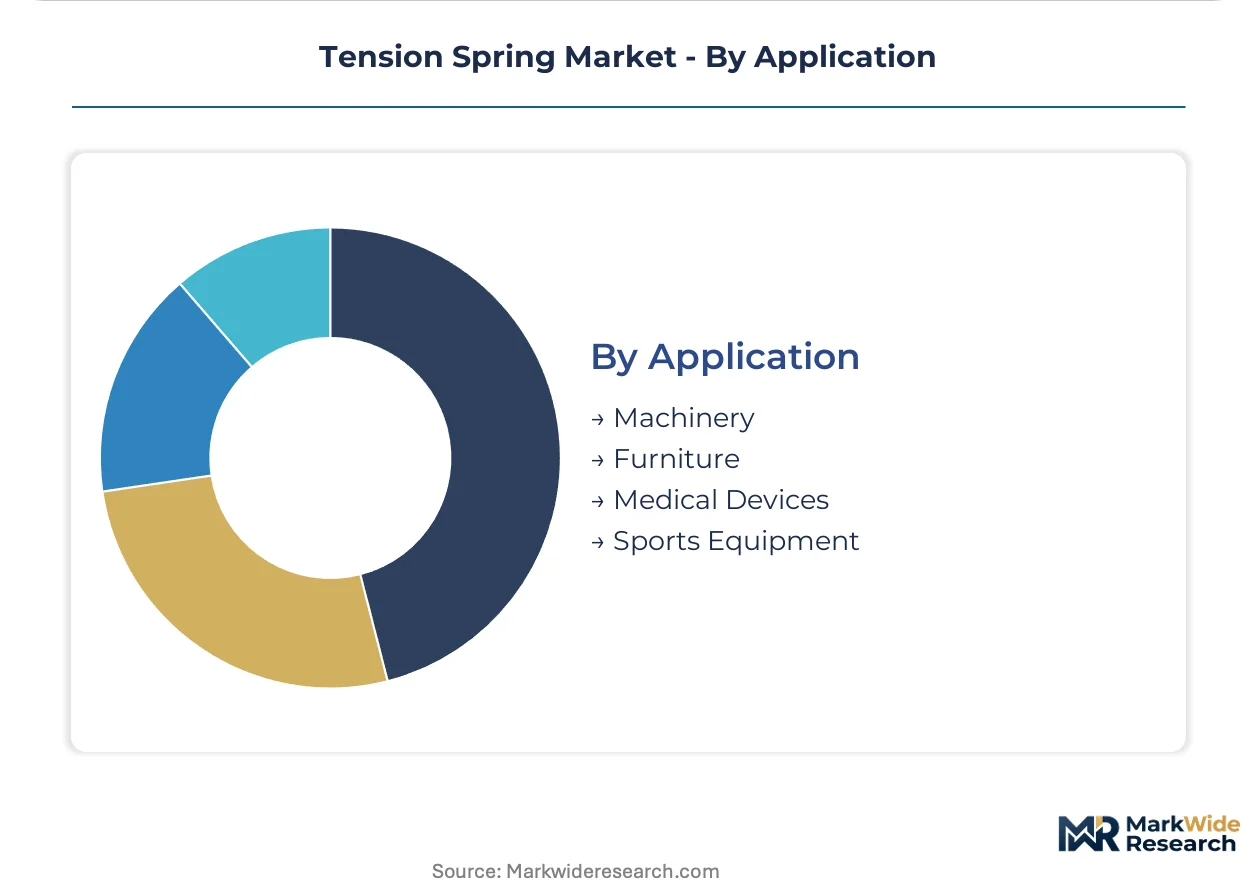
Machinery maintains the shipment volume. Medical Devices expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German precision manufacturing clusters while cost-competitive volume production migrates to Indian and Chinese automotive supply bases. This asymmetry reshapes investment allocation across tension spring supply chains. Regional regulatory divergence on chemical coatings and carbon intensity timelines accelerates geographic specialization.
United States
Automotive lightweighting mandates from NHTSA and EPA material restrictions compress steel spring specifications toward advanced alloys. Tool-and-die craftsperson scarcity across Midwestern manufacturing corridors forces automation capital deployment or relocation near technical colleges. Detroit-area assembly plants anchor direct OEM qualification requirements for chassis and suspension components.
Germany
EU REACH hexavalent chromium bans and F-Gas Regulation phase-down schedules accelerate coating line conversions to zinc-aluminum flake systems. Stuttgart and Munich precision component clusters sustain specialized high-volume demand for fatigue-rated extension springs serving tier-one automotive suppliers. Surface treatment suppliers consolidate qualification batch testing capabilities across Germany and Poland.
China
Dual carbon goals and MIIT industrial efficiency standards reshape material selection toward lower-alloy alternatives in domestic automotive production. Yangtze River Delta manufacturing bases supply miniature spring requirements for consumer electronics contract manufacturers. GB standards harmonization with ISO 10243 reduces export qualification friction for automotive component suppliers.
India
PLI scheme incentives and BIS certification harmonization open domestic supply opportunities for Maruti Suzuki and Tata Motors assembly networks. Maharashtra and Gujarat automotive corridors attract tension spring producers seeking localization partnerships. Central government push for manufacturing self-reliance redirects procurement from imports to domestic qualified suppliers.
Japan
METI carbon neutrality roadmaps and JIS B5014 dimensional tolerance standards govern precision spring acceptance in automotive and industrial equipment channels. Kanto and Kansai manufacturing belts maintain high-cycle fatigue specifications for robotics and automation equipment. Japanese automotive OEMs consolidate approved vendor lists to single-digit counts per component category.
Tension Spring Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the tension spring market. Vertically integrated manufacturers with captive wire drawing and heat-treat capabilities occupy premium positions in automotive direct procurement, while catalog distributors compete on fulfillment speed and standard specification coverage. Three archetypes dominate: precision specialists with OEM qualification depth, volume producers serving aftermarket channels, and regional fabricators leveraging geographic proximity. Consolidation moves center on coating line asset acquisitions for REACH compliance and automated coiling equipment deployment to offset skilled labor scarcity.
Among North American integrated manufacturers, Associated Spring exemplifies the captive-capability archetype through in-house shot peening across multiple plants, while Lee Spring Company occupies the catalog-distribution position with same-day shipping infrastructure. Peterson Spring anchors the direct-OEM-qualification tier through Detroit-area automotive program presence. These three represent distinct competitive vectors rather than overlapping market contestation.
| Leading Market Players |
|---|
| Associated Spring |
| Spiros Industries |
| The D.R. Templeman Co. |
| Coiling Technologies, Inc. |
| Fennell Spring Company |
| Lee Spring Company |
| Peterson Spring |
| Spring Dynamics |
| Lesjofors Springs America, Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive shot peening and in-house wire drawing capacity at scale anchors pricing power among automotive-qualified producers, compressing margin floors for distributors lacking backward integration into heat-treat operations. Scale concentration around Stuttgart-Munich precision clusters and Detroit-area OEM engineering centers creates geographic rent extraction for fatigue-rated batch suppliers while commoditizing standard catalog configurations.
Pricing Analysis
Configured-to-order pricing for direct-OEM-qualified extension springs commands substantial premiums over standard catalog equivalents. Three-tier pricing structure across premium fatigue-rated, standard industrial-grade, and economy catalog tiers separates automotive chassis programs from machinery maintenance channels. Cost compression in commodity carbon steel segments is intensifying due to alloy surcharge volatility tied to scrap indices. Aftermarket distributors and MRO procurement teams exhibit the highest price sensitivity, while automotive platform engineers prioritize fatigue-life documentation over unit cost.
Supply Chain Analysis
Germany, China, and the United States anchor tension spring manufacturing through distinct capability specializations. Raw material flows draw from cold-drawn carbon steel wire mills in the US Midwest, austenitic stainless producers in Germany, and alloy processing centers in China's Yangtze River Delta. Single-source vulnerability concentrates in European surface treatment suppliers consolidating REACH-compliant zinc-aluminum flake coating capacity. Distribution runs through tier-one automotive direct procurement, industrial distributor catalogs, and Asian contract manufacturer networks serving consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collapse of tool-and-die craftsperson availability across Midwestern manufacturing corridors has converted skilled coil winding and heat-treat technician retention into a structural chokepoint. Producers and buyers must now compete for automation-capable talent pools rather than traditional apprenticeship pipelines.
For Market Incumbents: Shield automotive program positions through captive residual stress testing documentation and finite element analysis capabilities that satisfy NHTSA crashworthiness requirements. Accelerate coating line conversions to trivalent chromium and zinc-aluminum flake systems ahead of EU REACH sunset enforcement. Vertical integration into automated coiling equipment offsets skilled labor scarcity while raising barriers for unqualified competitors.
For New Entrants and Emerging Players: Aftermarket wind turbine blade pitch control and solar tracking mechanism specifications represent underserved high-cycle fatigue applications where corrosion-resistant designs command premium positioning. Target renewable energy maintenance channels with extension spring designs qualified for offshore and desert exposure conditions. Partner with surface treatment specialists in Poland and Germany to bypass capital-intensive coating line investments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision specialists with OEM qualification depth over volume producers exposed to commodity carbon steel margin compression. Long-term viability rests on coating line assets with REACH compliance validation and automated micro-coiling capacity for medical device specifications. Monitor EU F-Gas Regulation phase-down schedules and dual-carbon regulatory timelines as inflection indicators for material substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Coating Line Conversion | REACH-compliant zinc-aluminum flake systems secure European automotive supply chain access ahead of regulatory deadlines. |
| Automated Coiling Deployment | Robotic winding and inline inspection offset Midwestern tool-and-die craftsperson scarcity while improving batch consistency. |
| Captive Testing Investment | In-house shot peening parameter certification satisfies direct OEM qualification requirements for NHTSA crashworthiness documentation. |
| Medical Device Qualification | FDA and EU MDR framework compliance opens stainless steel and titanium spring specifications in surgical instrument markets. |
| Renewable Energy Channel Development | Wind turbine pitch control and solar tracking mechanism designs capture high-cycle fatigue demand outside traditional automotive procurement. |
Research Methodology
Operator-level perspectives from coil winding technicians, heat-treat process engineers, tier-one automotive procurement managers, and surface treatment specialists anchored the qualitative base. Secondary validation drew from SEC filings of precision component manufacturers, NHTSA crashworthiness documentation databases, EU REACH authorization registries, and ISO 10243 certification records. Bottom-up volume estimates triangulated against top-down automotive production and industrial machinery shipment data.
Sensitivity analysis tested forecast outputs against alternative scenarios for alloy surcharge volatility, REACH compliance timeline acceleration, and composite substitution rates in heavy trucking suspension. Segmentation modeling spanned product geometry, material grade tier, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from slope-intercept fitting across the analysis window, with automotive lightweighting mandates and medical device corrosion standards as primary demand elasticity inputs.
Underlying assumptions cover sustained OEM direct procurement consolidation, stable alloy surcharge mechanisms, and REACH enforcement timelines, with deviation risk concentrated in carbon steel price volatility and composite leaf spring substitution acceleration. Recalibration cycles align with material shifts in EU chemical authorization schedules and dual-carbon regulatory milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
US Industrial Fasteners Market
Industrial Materials
Industrial Anti-Fatigue Mat Market
Industrial Materials
Wood Fiber Insulation Market
Industrial Materials
Asia-Pacific Wood Based Panel Market
Industrial Materials
Global Metal Anodizing Market
Industrial Materials
Modified Wood Market
Industrial Materials
Weatherstrip Seal Market
Industrial Materials
Bamboo Products Market
Industrial Materials
Global Cenospheres Market
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
Global Graphite Electrodes Market
Industrial Materials
Pultrusion Products Market
Industrial Materials
Paint Knife Market
Industrial Materials
Atomizing Metal Powder Market
Industrial Materials
Chalk Reel and Line Chalk Market
Industrial Materials
United States Ceramic Roller Bearings Market