
 Technical Coil Coatings Market | 2026-2036
Technical Coil Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Technical Coil Coatings Market Outlook
Modular specification bundles combining primer, topcoat, and backing coat into single-source supply agreements is recalibrating procurement behavior across building envelope projects. Akzo Nobel N.V. leverages its integrated color matching laboratories to anchor specification relationships with European cladding fabricators. PPG Industries Inc. competes through backward integration into resin synthesis, sustaining margin control across volatile petrochemical cycles. Beckers Group differentiates via specialized fluoropolymer topcoats for extreme-UV geographies, occupying premium niches in Middle Eastern and Australian construction markets.
Technical coil coatings are factory-applied liquid or powder systems cured onto continuous metal strips—typically aluminum or galvanized steel—at line speeds exceeding 150 meters per minute, delivering controlled film thicknesses of 15–25 micrometers for corrosion resistance, color retention, and formability in downstream stamping or roll-forming operations. Polyester formulations dominate volume shipments to roofing and siding applications where cost efficiency outweighs extreme durability requirements, while polyurethane segments command margin premiums in automotive exterior trim and high-end appliance panels demanding superior scratch resistance and chemical tolerance. Powder coating technology is displacing conventional solvent-borne lines in regulatory-sensitive European and North American facilities, though roller application retains scale advantages in emerging-market steel mills with lower capital replacement budgets.
EPA VOC regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based coating formulations across US coil coating facilities, while REACH registration requirements and the EU Green Deal's embodied carbon tracking reshape raw material qualification protocols for suppliers serving European OEMs. China's MEE enforces progressively stricter emissions limits on coating operations in the Yangtze and Pearl River Delta manufacturing belts, compelling local producers to retrofit curing ovens or migrate toward waterborne and powder systems. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments in one geography may not transfer to emerging standards elsewhere, fragmenting equipment and formulation strategies across multinational coating portfolios.
Market Dynamics
Factory-applied coating systems are consolidating procurement decisions around integrated primer-topcoat-backcoat bundles, compressing supplier rosters and elevating technical service capabilities as the primary competitive differentiator over standalone formulation pricing.
Growth Catalysts
- India's western industrial corridor concentration:New steel processing clusters in Gujarat and Maharashtra serve domestic appliance and construction OEMs, creating localized demand density that reduces logistics costs for coating suppliers.
- China's dual carbon goals and MEE emissions standards:Tightening VOC limits in the Yangtze and Pearl River Delta manufacturing belts accelerate solvent-free coating transitions, expanding addressable market for waterborne and powder system providers.
- Architectural cladding specification expansion:Pre-coated metal substrates gain share in building envelope projects as fabricators prioritize controlled film thickness and corrosion resistance over field-applied alternatives.
Market Restraints
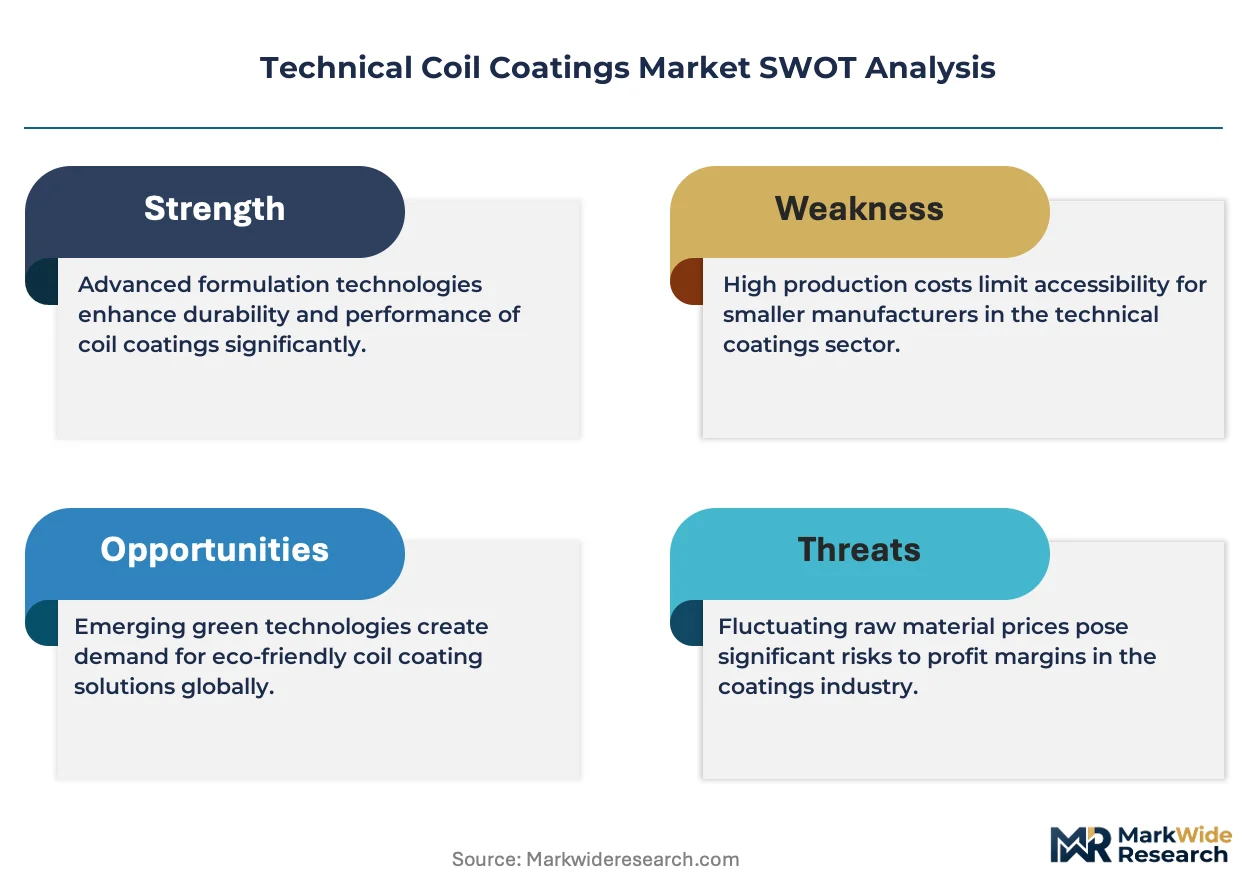
- Petrochemical input volatility:Resin and pigment feedstock costs fluctuate with crude oil and natural gas derivatives, compressing margins for coating formulators lacking backward integration into resin synthesis.
- European supply concentration:REACH registration requirements and EU Green Deal embodied carbon tracking fragment raw material qualification protocols, creating compliance asymmetries between multinational and regional suppliers.
- Line speed limitations:Curing oven thermal profiles constrain maximum coating throughput to approximately 150 meters per minute, capping unit economics for high-volume commodity applications.
Strategic Opportunities
- Extreme-UV geography specialization:Fluoropolymer topcoat demand in Middle Eastern and Australian construction markets commands premium pricing for color retention in high-radiation environments.
- Powder coating retrofit wave:Regulatory-sensitive European and North American facilities face capital replacement cycles that favor solvent-free line conversions over incremental solvent-borne upgrades.
- Automotive exterior trim expansion:Polyurethane segments in high-end appliance and automotive panels leverage superior scratch resistance to penetrate specification hierarchies historically dominated by polyester formulations.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in fluoropolymer and polyurethane resin compatibility commands salary premiums that strain mid-tier coating producers.
- Multi-jurisdictional compliance divergence:EPA NESHAP standards, REACH protocols, and China's GB emissions limits require non-transferable equipment investments that fragment multinational coating portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Technical Coil Coatings Market |
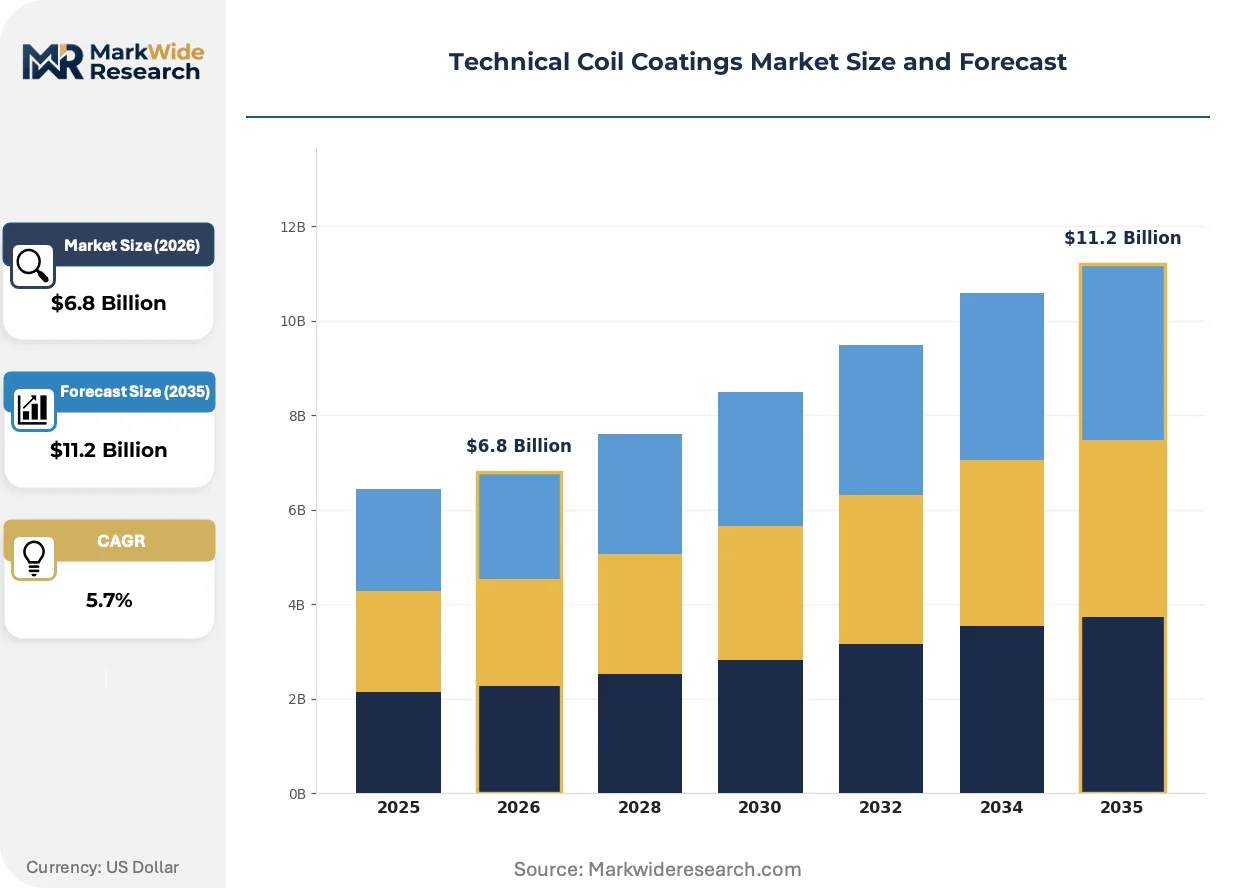
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polyurethane, Acrylic, Epoxy Application: Building & Construction, Automotive, Appliance, Electrical End User: Manufacturers, Contractors, Distributors, Retailers Technology: Electrostatic Spray, Roller Application, Dip Coating, Powder Coating |
| Companies Covered | The Sherwin-Williams Company, Beckers Group, PPG Industries Inc., DuPont, Kansai Paint Co., Ltd., Akzo Nobel N.V., Axalta Coating Systems Ltd., Nippon Paint Holdings Co., Ltd., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Technical Coil Coatings Market Strategic Shifts
Powder coating technology is absorbing capital allocation across regulatory-sensitive jurisdictions while digital color matching and modular specification bundles reconfigure buyer-supplier relationships. These shifts compress traditional competitive advantages rooted in standalone formulation expertise.
UV-curable powder systems are absorbing line integration complexity at European and North American coil coating facilities seeking to eliminate solvent handling entirely. Automotive exterior trim manufacturers and high-end appliance panel fabricators adopt these systems fastest, driven by combined EPA and REACH compliance deadlines. The technology is absorbing curing energy requirements by 40-60% versus thermal powder, compressing operational expenditure structures for early adopters.
REACH registration requirements and the EU Green Deal's embodied carbon tracking are reshaping raw material qualification protocols for suppliers serving European OEMs. ECHA substance evaluation timelines extend raw material approval cycles, forcing coating formulators to maintain dual-qualified supply chains. Architectural cladding fabricators in Germany and the Netherlands face the most acute compliance pressure, accelerating specification shifts toward pre-certified coating bundles.
Modular specification bundles combining primer, topcoat, and backing coat into single-source agreements are displacing component-level procurement in building envelope projects. European cladding fabricators consolidate supplier rosters to three or fewer integrated providers, compressing market access for standalone primer or backing coat specialists. Gujarat-based steel processors in India exhibit similar consolidation patterns, though emerging-market mills retain more fragmented purchasing due to lower capital replacement budgets.
Technical Coil Coatings Market Segmentation
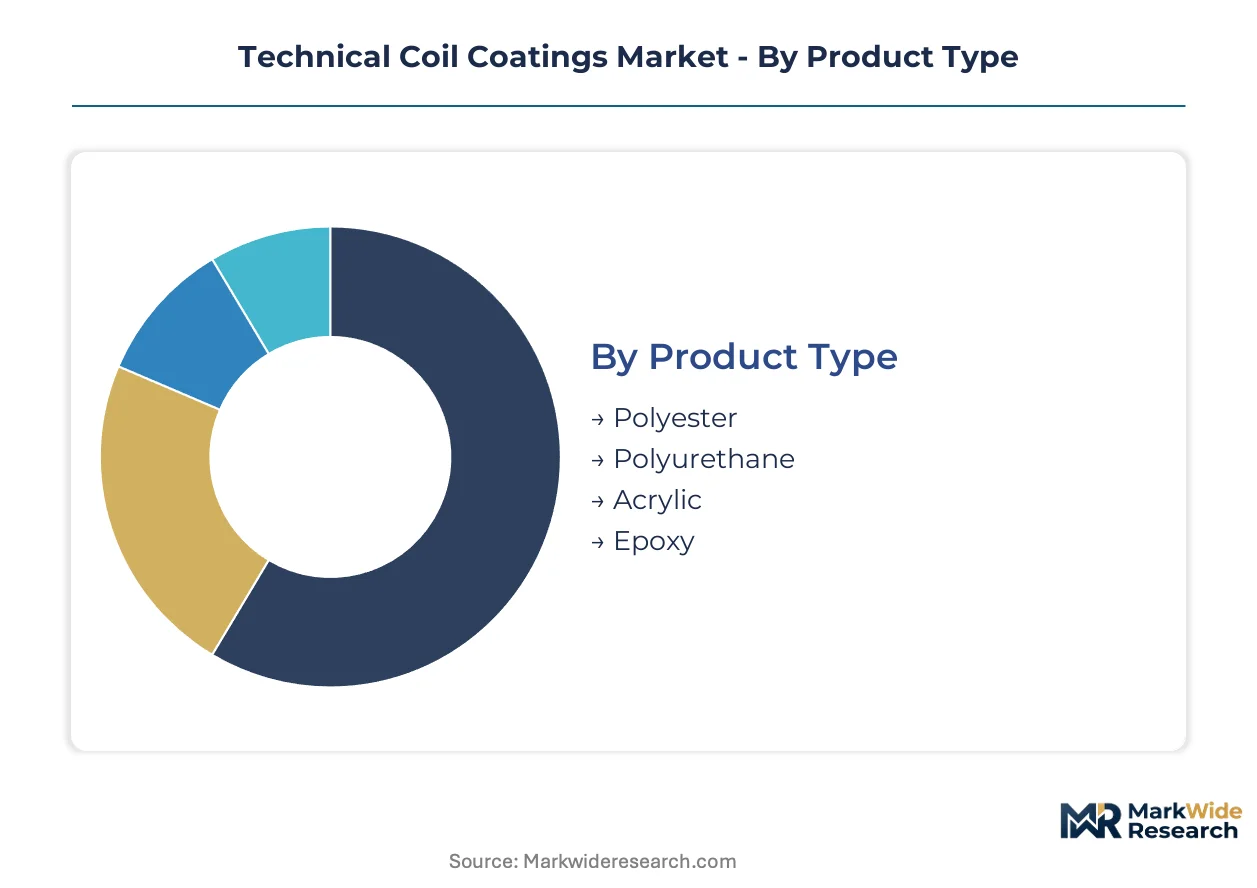
Technical coil coatings demand fragments across resin chemistries, application methods, and end-use specifications that each impose distinct performance requirements. Procurement behavior varies sharply between volume-driven construction segments and specification-intensive automotive and appliance markets.
Product Type:
Resin formulation supply concentrates around polyester capacity in Asian steel mill corridors, while polyurethane and fluoropolymer production clusters near European and North American OEM specification centers.
- Polyester:Saturated and unsaturated polyester resins deliver cost-efficient color retention and flexibility for roofing and siding substrates. Demand clusters in India's western industrial corridor around Gujarat and Maharashtra steel processing facilities serving domestic construction OEMs, constrained by margin pressure from petrochemical feedstock volatility.
- Polyurethane:Aliphatic polyurethane systems provide superior scratch resistance and chemical tolerance for automotive exterior trim and premium appliance panels. Specification relationships with European cladding fabricators and North American automotive Tier 1s command margin premiums, though formulation chemist scarcity strains mid-tier producers seeking entry.
- Acrylic:Thermoplastic acrylic formulations offer rapid cure response and exterior durability for architectural applications in moderate UV environments.
- Epoxy:Epoxy-based systems deliver exceptional adhesion and corrosion resistance for backing coat applications and electrical steel insulation.
Polyester absorbs the bulk of installed capacity; polyurethane is expanding most quickly.
Application:
End-use demand concentrates in building envelope fabrication where pre-coated metal substrates displace field-applied alternatives, while automotive and appliance segments drive technology upgrading cycles.
- Building & Construction:Architectural cladding, roofing, and siding applications specify controlled film thickness of 15–25 micrometers for corrosion resistance and formability. China's MEE emissions standards in the Yangtze and Pearl River Delta accelerate solvent-free coating transitions, expanding specification of pre-coated substrates over field-applied systems.
- Automotive:Exterior trim panels and interior metal components demand superior scratch resistance and color matching precision. EPA NESHAP compliance deadlines and REACH registration requirements force capital replacement cycles favoring UV-curable powder systems that reduce curing energy consumption versus thermal alternatives.
- Appliance:Refrigerator, washing machine, and HVAC panel applications balance aesthetic finish with chemical tolerance from household cleaners.
- Electrical:Transformer and motor lamination coatings require dielectric insulation properties and thermal stability under electrical stress.
Building and construction maintains volume leadership; automotive exhibits the steepest expansion trajectory as exterior trim metalization accelerates.
End User:
Procurement authority is consolidating around integrated primer-topcoat-backcoat bundles, compressing supplier rosters and elevating technical service capabilities as the primary competitive differentiator.
- Manufacturers:Steel mills, aluminum processors, and metal fabricators specify coating systems for continuous coil lines operating at speeds exceeding 150 meters per minute. European cladding fabricators consolidate supplier relationships to three or fewer integrated providers, while Gujarat-based processors in India retain more fragmented purchasing due to lower capital replacement budgets.
- Contractors:Installation and fabrication contractors influence specification through field performance feedback and warranty claim exposure.
- Distributors:Metal service centers and coating intermediaries manage inventory and logistics for regional construction markets.
- Retailers:Big-box building material retailers and specialty metal distributors serve renovation and repair demand segments.
Manufacturers control specification authority; distributors are gaining procurement influence as just-in-time delivery requirements tighten.
Technology:
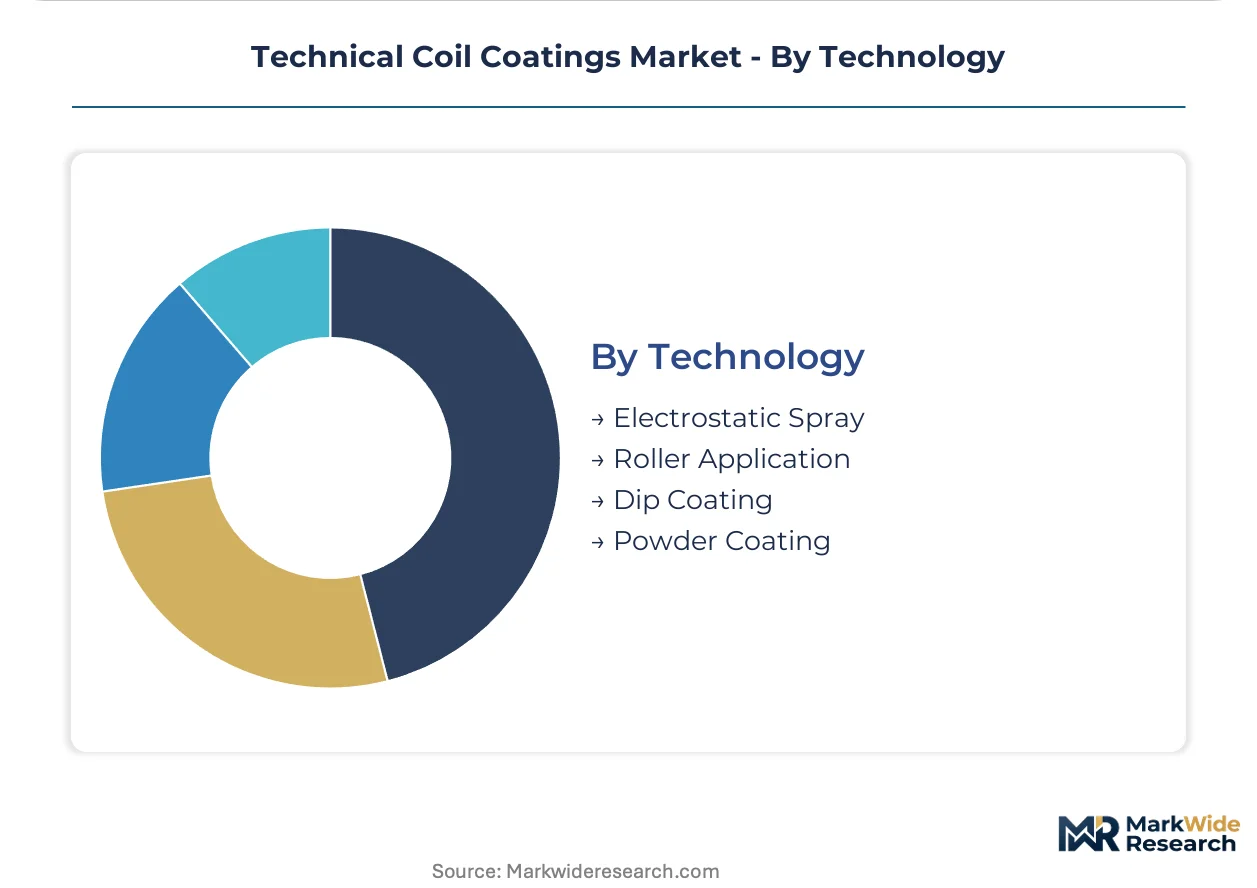
Application method selection hinges on capital replacement budgets, regulatory jurisdiction, and line speed requirements that constrain unit economics for commodity versus specialty production.
- Powder Coating:Solvent-free electrostatic application and thermal or UV curing eliminates VOC handling and reduces curing energy by 40–60% versus conventional systems. Regulatory-sensitive European and North American facilities face capital replacement cycles favoring powder line conversions, though roller application retains scale advantages in emerging-market steel mills.
- Roller Application:Direct roll coating delivers controlled film thickness at line speeds exceeding 150 meters per minute with lower capital intensity. Chinese and Indian steel processors favor this method for volume roofing and siding production where cost efficiency outweighs extreme durability requirements.
- Electrostatic Spray:Liquid spray systems accommodate complex geometries and color change flexibility for specialty batch production.
- Dip Coating:Immersion application provides uniform edge coverage for small-diameter wire and narrow strip products.
Roller application commands the largest installed base; powder coating is climbing the fastest on regulatory-driven retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Asian steel corridors while consumption concentrates in construction and automotive fabrication centers across multiple continents. This geographic split creates distinct supply chain configurations for coating formulators. Regulatory divergence between jurisdictions fragments equipment investment strategies.
China
Steel processing volumes in the Yangtze and Pearl River Delta manufacturing belts drive solvent-free coating transitions. The MEE enforces progressively stricter VOC emissions limits on coating operations, compelling local producers to retrofit curing ovens. Shanghai and Jiangsu province steel mills are migrating toward waterborne and powder systems at scale.
United States
Automotive exterior trim manufacturers and architectural cladding fabricators anchor demand in the Midwest and Southeast manufacturing corridors. EPA NESHAP standards constrain solvent-based formulations across coil coating facilities, accelerating capital replacement cycles. Michigan and Ohio-based steel processors favor UV-curable powder conversions to meet combined federal and state compliance deadlines.
Germany
REACH registration requirements and EU Green Deal embodied carbon tracking reshape raw material qualification protocols for suppliers serving European OEMs. ECHA substance evaluation timelines extend approval cycles, forcing dual-qualified supply chain maintenance. North Rhine-Westphalia and Bavaria-based cladding fabricators consolidate supplier rosters to three or fewer integrated providers.
India
New steel processing clusters in Gujarat and Maharashtra serve domestic appliance and construction OEMs, creating localized demand density. BIS standards and state-level pollution control mandates tighten formulation requirements for imported resin systems. The western industrial corridor around Ahmedabad and Pune reduces logistics costs for coating suppliers through cluster proximity.
Japan
High-end appliance panel and automotive exterior specifications demand superior scratch resistance and color matching precision. METI energy efficiency guidelines and JIS standards influence curing oven thermal profile investments. Kansai and Chubu region metal fabricators prioritize polyurethane segments for premium applications over cost-driven polyester alternatives.
Technical Coil Coatings Market Competitive Environment
The competitive structure tilts toward integrated resin-to-coating specialists with captive supply chains. Market access concentrates around firms controlling backward integration into resin synthesis, insulating margin positions from petrochemical feedstock volatility. Three archetypes dominate: multinational chemical conglomerates with diversified coating portfolios, regional specialists in fluoropolymer or polyurethane formulations, and steel mill-integrated coating operations. Capacity expansion and technology licensing represent the primary competitive moves, with modular specification bundles displacing component-level procurement.
Among Netherlands-based chemical conglomerates, Akzo Nobel N.V. anchors the integrated color matching laboratory archetype for European specification relationships. PPG Industries Inc. exemplifies the backward-integrated resin synthesis model, sustaining margin control across volatile cycles. Beckers Group occupies the specialized fluoropolymer topcoat position for extreme-UV geographies. These three firms represent distinct strategic postures without implying specific market share claims.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| Beckers Group |
| PPG Industries Inc. |
| DuPont |
| Kansai Paint Co., Ltd. |
| Akzo Nobel N.V. |
| Axalta Coating Systems Ltd. |
| Nippon Paint Holdings Co., Ltd. |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
European cladding fabricators consolidating supplier rosters to three or fewer integrated providers have compressed procurement leverage toward contract-based long-term offtake agreements, anchoring pricing power with resin-synthesis-integrated coating formulators.
Pricing Analysis
Margin tightening in polyester formulations reflects petrochemical feedstock volatility and Asian steel mill overcapacity. Three-tier pricing structure across premium fluoropolymer, standard polyurethane, and economy polyester levels separates specification relationships from commodity volume plays. Cost-down pressure on mid-tier producers accelerates because REACH registration requirements and dual-qualified supply chain maintenance drain working capital. Automotive exterior trim specifications exhibit least price sensitivity due to scratch resistance and color matching precision requirements.
Supply Chain Analysis
Dual-sourcing mandates from German and Dutch architectural fabricators force coating formulators to maintain parallel resin qualification across Asian and European supply bases. Raw material concentration centers on China, Germany, and India for polyester resin, aliphatic isocyanates, and fluoropolymer dispersions respectively. Formulation draws from titanium dioxide pigments, epoxy curing agents, and specialty acrylic monomers. Single-source vulnerability persists in fluoropolymer resin supply. Distribution runs through steel mill-integrated coating operations and regional metal service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where backward integration into resin synthesis separates margin-sustainable players from feedstock-exposed competitors.
For Market Incumbents: Anticipate powder coating retrofit cycles in European and North American facilities by securing UV-curable system capacity ahead of EPA NESHAP and REACH compliance deadlines. Deepen captive supply of aliphatic polyurethane resins to defend formulation margins against petrochemical volatility. Consolidate specification relationships with Gujarat and Maharashtra steel processors before emerging-market capital replacement budgets shift toward integrated providers. For New Entrants and Emerging Players: Waterborne system technology-first wedges open procurement doors at Chinese Yangtze River Delta steel mills facing MEE emissions enforcement. Target India's western industrial corridor appliance panel segment where polyurethane specification relationships remain underpenetrated versus European markets. Pursue technical service partnerships with regional metal fabricators lacking in-house color matching laboratories. For Investors and Strategic Acquirers: The window for entry favors mid-tier coating specialists with fluoropolymer formulation expertise and established Middle Eastern or Australian construction market access. Long-term viability hinges on regulatory-driven solvent-free transition completion rather than commodity polyester volume scale. Watch for MEE enforcement intensity in Pearl River Delta manufacturing belts as inflection indicator for Chinese market restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive supply of aliphatic polyurethane resins insulates margin positions from petrochemical feedstock cycles. |
| UV-Curable Powder System Capacity Expansion | European and North American facilities face capital replacement cycles favoring solvent-free line conversions. |
| Fluoropolymer Topcoat Specialization | Premium positioning in Middle Eastern and Australian extreme-UV construction markets commands pricing power. |
| Modular Specification Bundle Development | Integrated primer-topcoat-backcoat agreements displace component-level procurement in building envelope projects. |
| Regional Laboratory Network Buildout | Color matching capabilities anchor specification relationships with European cladding fabricators and automotive Tier 1s. |
Study Parameters
Document review covered customs and trade data, SEC 10-K filings, and industry association reports from ACC and Cefic, complemented by interviews with plant managers at coil coating facilities, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors. Bottom-up volume modeling triangulated against top-down market sizing from secondary validation.
Cross-referencing historical capacity utilization patterns against panel input from industry stakeholders anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include resin chemistry tier, end-use application, application technology, and regional production hub. CAGRs derived from trend extrapolation adjusted for regulatory enforcement timelines and capital replacement cycle phasing.
Several conditions sit outside the modeled scope, including unannounced MEE enforcement intensity shifts, abrupt petrochemical feedstock price dislocations, and trade policy revisions affecting resin import flows. Deviation in dual carbon policy implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Germany Protective Coatings Market
Coatings
High Performance Coatings Market
Coatings
Physical Vapor Deposition (PVD) Coatings Market
Coatings
Asia-Pacific Anti-Friction Coatings Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
BRIC Performance Coatings Market
Coatings
US Industrial Coatings Market
Coatings
Japan Protective Coatings Market
Coatings
Architectural Metal Coatings Market
Coatings
Global Fireproofing Coatings for Wood Market
Coatings
PACVD-Based Coatings Market
Coatings
Electronic Protection Device (EPD) Coatings Market
Coatings
Fillers and Coating Market
Coatings
Coating Agents for Synthetic Leather Market
Coatings
Germany Automotive OEM Coatings Market
Coatings
Carpet Back Coatings Market