
 Industrial Brushes Market | 2026-2036
Industrial Brushes Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Brushes Market Analysis
Automation in abrasive finishing is tilting procurement toward precision-engineered brush systems with embedded sensors and predictive wear tracking. Osborn GmbH anchors European deburring and surface conditioning through its engineered brush portfolio for automated production lines. Gordon Brush Mfg. Co. Inc. specializes in custom-configured industrial brushes for aerospace and defense specifications, leveraging domestic manufacturing scale to sustain rapid turnaround on specialized orders. Tanis Brush Inc. competes across material handling and conveyor cleaning segments with modular brush designs that reduce changeover downtime.
Industrial brushes are mechanical implements constructed from filaments of metal wire, synthetic polymers, or natural fibers secured within a rigid block, handle, or rotating core, engineered to operate at defined rotational speeds and contact pressures for material removal, surface finishing, or debris control. Wire brushes dominate heavy-duty applications where aggressive material removal tolerates surface scoring, while synthetic fiber variants capture expanding demand in precision polishing where substrate damage must be minimized. Among end users, automotive manufacturing commands the largest installed base of automated brush systems, whereas aerospace represents the fastest-growing segment as tighter surface-integrity specifications propagate through supply chains.
OSHA workplace safety standards and EPA hazardous waste regulations shape brush material selection and disposal protocols in US manufacturing facilities, while REACH and RoHS compliance in Europe restricts certain metal alloys and chemical treatments in brush construction. The EU Green Deal's circular-economy mandates are pressuring suppliers to develop recyclable filament materials and closed-loop manufacturing processes. Stakeholders must monitor how evolving carbon-border adjustments and material traceability requirements will reshape supplier qualification criteria and sourcing geography decisions.
Market Dynamics
Automotive surface-finishing automation is compressing brush replacement cycles while demanding embedded sensor integration, forcing suppliers to reengineer product architectures around predictive wear analytics rather than commodity filament bundles.
Growth Catalysts
- REACH compliance deadlines:European manufacturers are accelerating brush system upgrades to meet ECHA material composition rules for industrial consumables, pulling forward replacement demand across German automotive supplier networks.
- Precision deburring robotics:Automated production lines in aerospace manufacturing require engineered brush systems with calibrated filament density and rotational speed control.
- Stuttgart-Wolfsburg supplier belt concentration:Dense clustering of automotive OEMs and Tier-1 suppliers in southern Germany creates localized demand pull for just-in-time brush replenishment programs.
Market Restraints
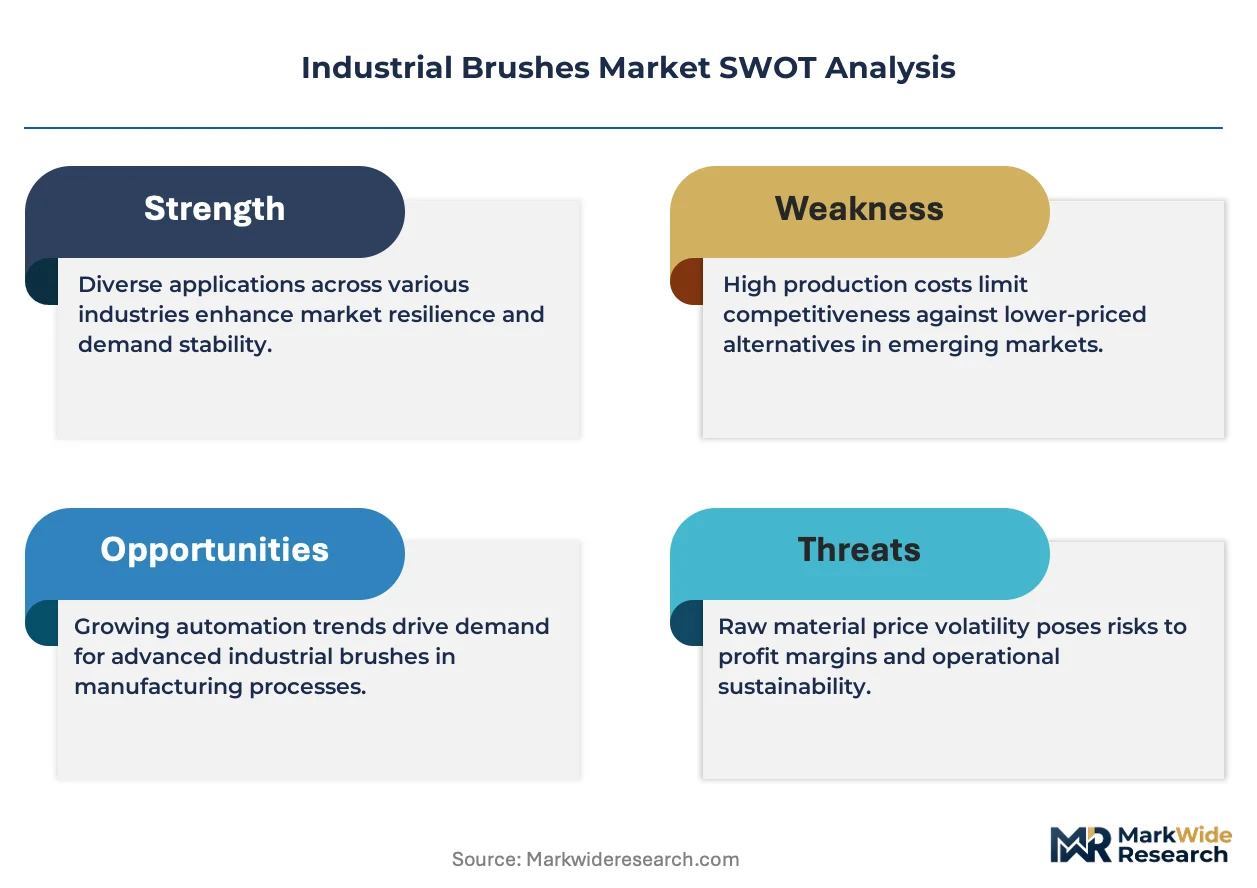
- Steel wire price volatility:Fluctuations in ferrous metal input costs squeeze margin structures for heavy-duty wire brush manufacturers serving metal fabrication end-uses.
- Specialty polymer supply concentration:Nylon 6.12 and PBT filament producers cluster in East Asian chemical manufacturing hubs, exposing European brush makers to shipping cost spikes and currency risk.
- Surface scoring limitations:Wire brush aggression thresholds prevent penetration into precision electronics polishing where substrate damage tolerances approach zero.
Strategic Opportunities
- EU Green Deal circular-economy mandates:Regulatory pressure for recyclable filament materials and closed-loop manufacturing processes creates first-mover advantage for suppliers developing bio-based polymer alternatives.
- Carbon-border adjustment mechanism:Impending EU carbon tariffs on imported industrial goods incentivize nearshoring of brush production to qualify for preferential supplier status.
- Sensor-embedded smart brushes:Convergence of IoT connectivity with mechanical wear components enables predictive maintenance contracts and recurring revenue streams from data services.
Industry Challenges
- Tribology engineering talent scarcity:Specialized knowledge of filament-substrate interaction mechanics remains concentrated among aging technical specialists, constraining R&D velocity for next-generation surface conditioning products.
- REACH registration timelines:Extended chemical substance authorization procedures delay commercialization of novel polymer formulations, compressing effective patent windows.
- Legacy CNC integration complexity:Retrofitting predictive brush wear systems into existing automated finishing cells requires custom mechanical and software interfaces, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Brushes Market |
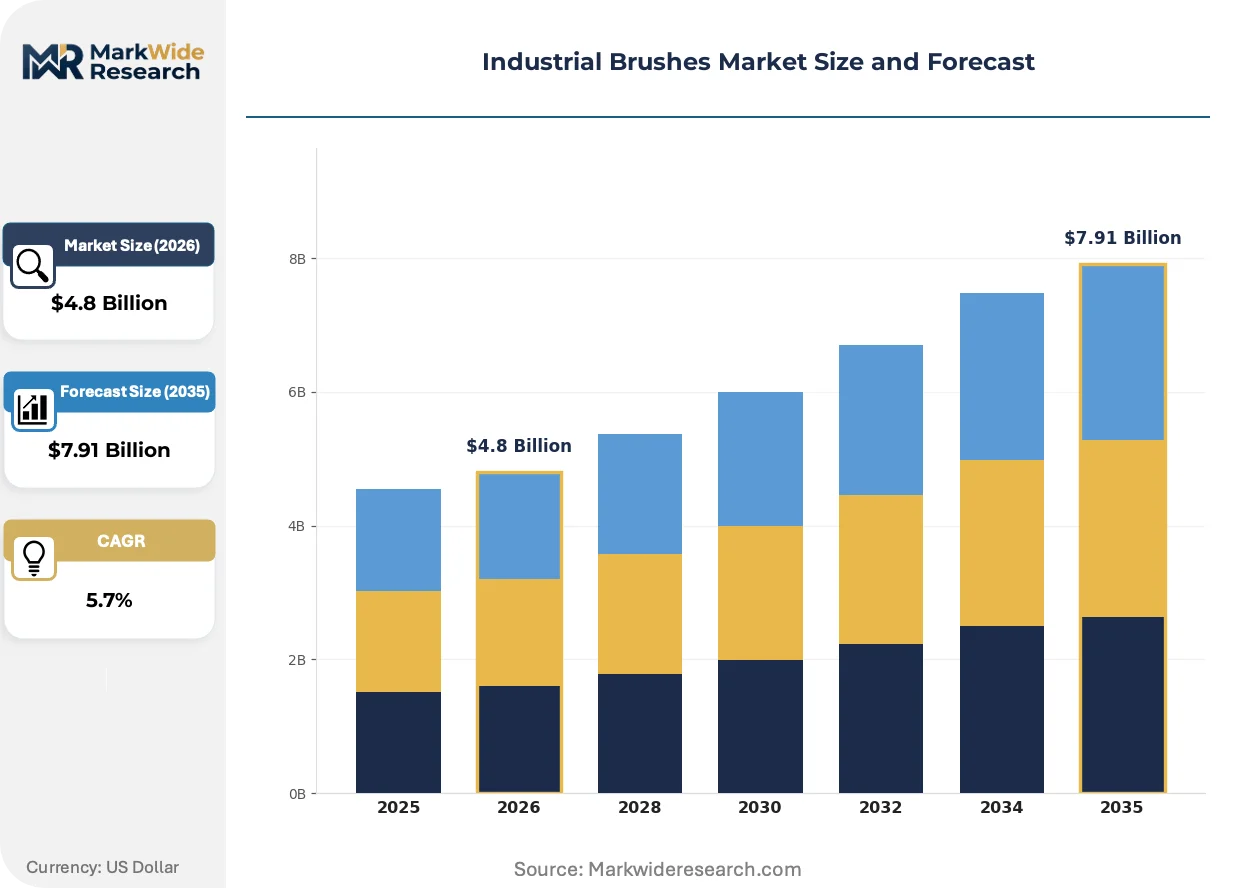
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Brushes, Nylon Brushes, Wire Brushes, Duster Brushes End User: Manufacturing, Cleaning Services, Automotive, Aerospace Application: Surface Preparation, Paint Removal, Deburring, Polishing Material: Brass, Stainless Steel, Synthetic Fibers, Natural Fibers |
| Companies Covered | Gordon Brush Mfg. Co. Inc., Tanis Brush Inc., 3M Co., Carolina Brush, Schaefer Brush, Osborn GmbH, Spiral Brushes Inc., Fuller Industries LLC, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Brushes Market Emerging Trajectories
Brush system architecture is bifurcating between commodity consumables and intelligent, connected finishing tools that generate operational data. This divergence is reshaping supplier business models and buyer procurement criteria simultaneously.
Carbon-fiber-reinforced polymer brush cores are collapsing the weight-performance tradeoff that previously constrained high-speed rotational applications. Aerospace finishing operations in Germany and France are adopting these cores for automated deburring cells running at elevated RPM. The technology is collapsing the historical gap between metal-core durability and polymer-core flexibility, enabling single-platform designs across multiple surface conditioning tasks.
EU Green Deal circular-economy mandates are forcing filament chemistry redesigns ahead of 2030 material traceability requirements. ECHA substance restrictions are propagating through brush supply chains, disqualifying certain chrome-plated wire grades and solvent-based fiber treatments. German automotive suppliers are responding by qualifying alternative surface coatings and demanding supplier documentation of closed-loop recycling capabilities.
Buyer consolidation among automotive Tier-1 suppliers is compressing vendor qualification lists and extending contract durations. Procurement teams at major German transmission and engine component manufacturers are unbundling brush supply from broader MRO agreements, creating dedicated category management functions. This pattern concentrates volume with engineered brush specialists capable of technical collaboration on custom specifications rather than catalog distributors.
Industrial Brushes Market Segmentation
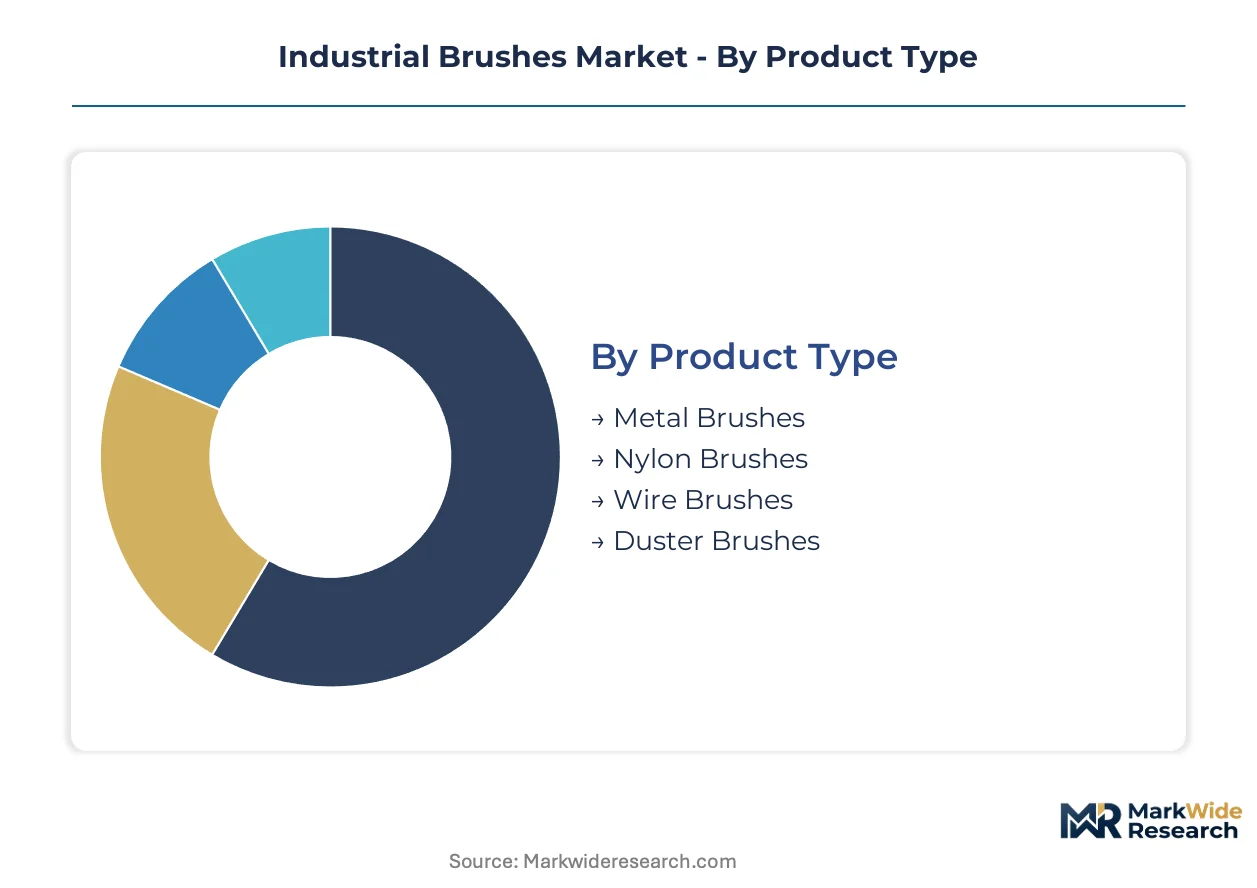
Industrial brush procurement decisions pivot on filament-substrate compatibility, rotational speed requirements, and regulatory compliance profiles. Segmentation reveals how suppliers architect differentiated product lines across performance tiers and end-use specifications.
Product Type:
Mature metal and wire formats anchor heavy-duty material removal, while synthetic variants capture precision-finishing demand.
- Metal Brushes:Engineered from brass, carbon steel, or stainless steel filaments secured in rigid metal cores, designed for aggressive stock removal at high contact pressures. German automotive supplier networks around Stuttgart consume the bulk of European volume as ECHA substance restrictions force qualification of chrome-free wire grades.
- Nylon Brushes:Abrasive-impregnated polymer filaments enable controlled surface conditioning without substrate scoring. Aerospace finishing operations in France and Germany are accelerating adoption for automated deburring cells where dimensional tolerances are tight.
- Wire Brushes:Crimped or twisted steel wire configurations dominate weld cleaning and rust removal in metal fabrication. Ferrous input cost volatility squeezes margin structures for manufacturers serving construction equipment OEMs.
- Duster Brushes:Soft-bristle configurations for particulate removal in electronics assembly and cleanroom environments.
Wire brushes handle the majority of throughput; nylon brushes are gaining share fastest as precision automation expands.
End User:
Customer concentration patterns split between high-volume manufacturing procurement and specialized technical specifications.
- Manufacturing:General industrial fabrication, metalworking, and assembly operations requiring standardized brush consumables for equipment maintenance and surface preparation.
- Cleaning Services:Commercial and industrial facility maintenance contractors sourcing durable sweepers and scrubber brushes for floor care equipment.
- Automotive:OEM and Tier-1 supplier networks operating automated surface-finishing lines with just-in-time replenishment requirements. Stuttgart-Wolfsburg supplier belt concentration creates localized demand pull for engineered brush systems with predictive wear tracking.
- Aerospace:Airframe and engine component manufacturers enforcing stringent surface-integrity specifications through supply chains. This segment climbs fastest as tighter FAA and EASA certification standards propagate finishing requirements to subcontractors.
Automotive procurement dominates installed base; aerospace qualification programs are expanding most quickly.
Application:
Process-stage requirements determine filament selection, with aggressive removal at one pole and cosmetic finishing at the other.
- Surface Preparation:Roughening substrates to specified anchor profiles prior to coating adhesion. German wind turbine manufacturers specify calibrated brush systems for tower section pretreatment.
- Paint Removal:Stripping coatings from metal substrates without base material damage. Automotive refurbishment operations in France favor nylon abrasive configurations for controlled layer removal.
- Deburring:Edge finishing of machined components to remove sharp projections and ensure assembly fit. Automated robotics integration in Italian precision manufacturing demands brushes with calibrated filament density.
- Polishing:Final-stage cosmetic finishing to specified surface roughness parameters. This application expands steepest as consumer electronics and medical device manufacturers adopt automated buffing cells.
Surface preparation commands the largest equipment footprint; polishing is climbing fastest on precision automation demand.
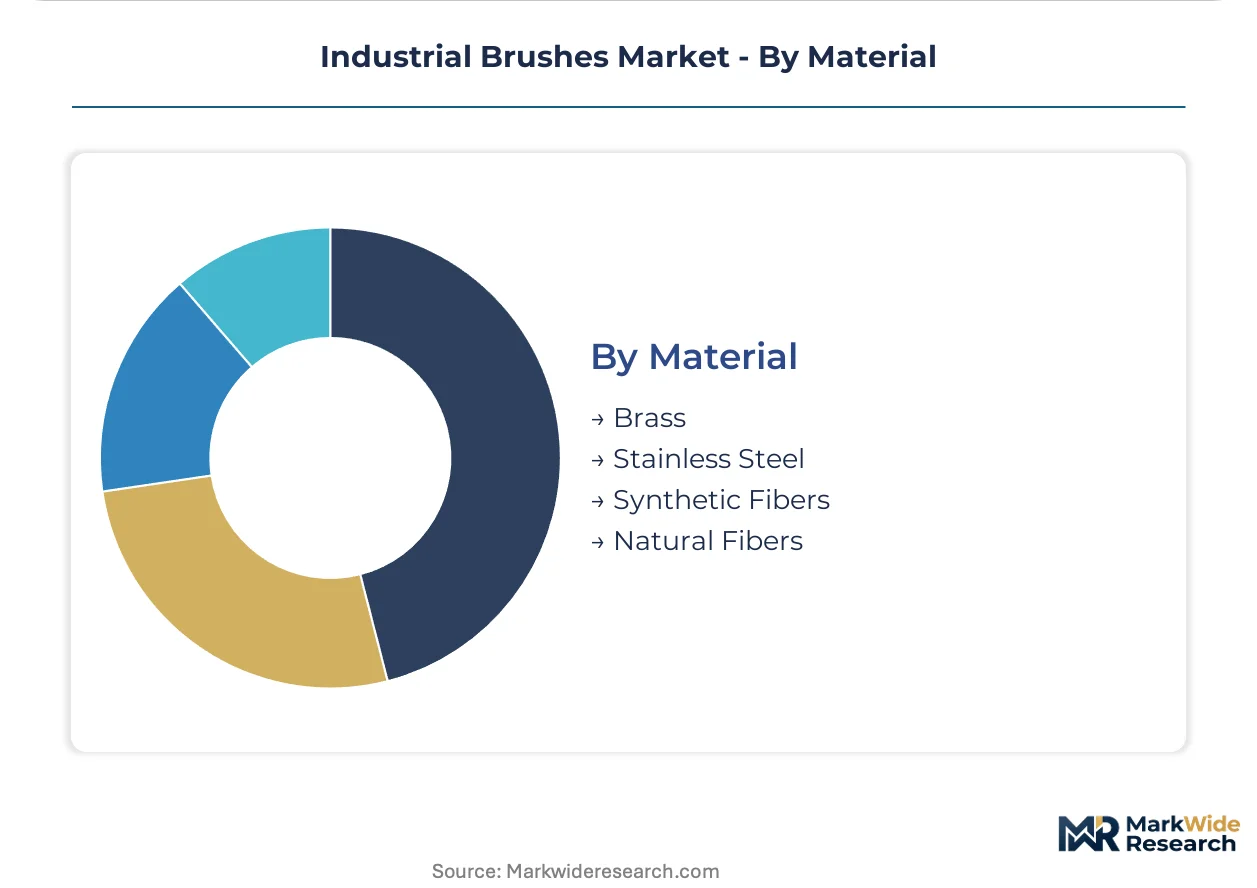
Material:
Raw material chemistry faces regulatory pressure as ECHA substance restrictions and EU Green Deal circular-economy mandates reshape formulation options.
- Brass:Non-sparking copper-zinc alloy filaments for hazardous environment applications. Oil and gas maintenance operations in Norway specify brass configurations for refinery turnaround work.
- Stainless Steel:Corrosion-resistant grades for food processing, pharmaceutical, and marine applications where contamination control is critical.
- Synthetic Fibers:Nylon, polyester, and abrasive-impregnated polymers enabling controlled cutting action with minimal substrate damage. REACH registration timelines delay commercialization of novel bio-based alternatives.
- Natural Fibers:Tampico, palmyra, and horsehair for specialty applications requiring chemical compatibility or static dissipation properties.
Stainless steel and synthetic fibers handle the majority of volume; bio-based synthetic formulations are advancing fastest on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement teams and aerospace quality engineers concentrate brush demand in manufacturing belts where surface-finishing automation runs at highest intensity. Supplier qualification programs favor vendors with REACH documentation and just-in-time logistics capabilities.
Germany
ECHA substance restrictions are forcing Stuttgart-Wolfsburg automotive suppliers to requalify chrome-free wire grades ahead of compliance deadlines. The KBA maintains strict documentation requirements for production equipment consumables used in vehicle assembly. Dense clustering of transmission and engine component manufacturers around Stuttgart creates localized demand for engineered brush systems with predictive wear tracking.
United States
OSHA workplace safety standards and EPA hazardous waste protocols shape material selection for metal fabrication and aerospace finishing operations. The FAA propagates surface-integrity specifications through domestic airframe supply chains. California and Washington State host precision electronics manufacturers adopting automated polishing cells with minimal substrate damage tolerances.
France
Aerospace OEMs in Toulouse and engine component suppliers enforce EASA-aligned finishing specifications through subcontractor networks. ANSM oversight of medical device manufacturing extends to surface preparation equipment validation. Auvergne-Rhône-Alpes precision manufacturing clusters are integrating automated deburring robotics with calibrated filament density controls.
China
MIIT industrial upgrading guidelines promote automation in metalworking and electronics assembly operations. GB standards govern filament material specifications for food processing and pharmaceutical equipment. Yangtze River Delta manufacturing hubs concentrate demand for synthetic fiber brushes in consumer electronics polishing applications.
Japan
METI carbon-neutrality roadmaps pressure suppliers to develop recyclable filament materials for industrial consumables. JIS standards define performance parameters for precision surface conditioning in automotive and semiconductor manufacturing. Nagoya-area automotive suppliers operate dense networks of automated finishing lines with just-in-time replenishment requirements.
Industrial Brushes Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered procurement categories. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive brush divisions, dedicated brush engineering specialists with custom fabrication capabilities, and catalog distributors serving maintenance-repair-operations procurement. Consolidation pressure concentrates volume with suppliers capable of technical collaboration on embedded sensor integration and REACH-compliant material documentation.
Among German-engineered brush specialists, Osborn GmbH exemplifies the precision-engineering archetype with automated production line focus. Gordon Brush Mfg. Co. Inc. and Tanis Brush Inc. represent North American fabricators occupying positions across custom-configured and modular brush design segments. These three anchors illustrate how geographic manufacturing scale and application specialization stratify competitive positioning.
| Leading Market Players |
|---|
| Gordon Brush Mfg. Co. Inc. |
| Tanis Brush Inc. |
| 3M Co. |
| Carolina Brush |
| Schaefer Brush |
| Osborn GmbH |
| Spiral Brushes Inc. |
| Fuller Industries LLC |
| Robert Bosch GmbH |
| Others |
Supply Flow & Price Mechanics
Overcapacity in East Asian polymer filament production is compressing margin structures for European brush manufacturers while simultaneously enabling aggressive pricing postures among synthetic fiber suppliers. This utilization imbalance forces buyers to navigate volatile spot markets for nylon 6.12 and PBT inputs while long-term contract holders capture stability premiums.
Pricing Analysis
Cost-plus contracts indexed to ferrous metal benchmarks dominate wire brush procurement, with steel wire price volatility passing directly through to automotive Tier-1 suppliers. Three-tier pricing structure across premium, standard, and economy levels separates sensor-embedded smart brushes with predictive analytics from commodity filament bundles and unbranded catalog alternatives. Pricing pressure stems from REACH compliance-driven material requalification costs, with German automotive suppliers least price-sensitive due to just-in-time replenishment penalties and MRO procurement teams most sensitive due to unbundled category management mandates.
Supply Chain Analysis
Contract manufacturing concentration in Chinese Yangtze River Delta hubs and South Korean chemical corridors controls specialty polymer filament capacity for precision brush applications. Raw material dependencies rest on brass and stainless steel wire from German and Italian metalworking centers, synthetic polymers from East Asian petrochemical complexes, and natural fibers from Mexican and Southeast Asian agricultural processors. Single-source vulnerability concentrates in abrasive-impregnated nylon formulations, with distribution running through dedicated industrial distributors serving German automotive supplier belts and catalog networks covering fragmented MRO procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial brushes market faces high-growth disruption as EU Green Deal circular-economy mandates force filament chemistry redesigns ahead of 2030 traceability requirements. This regulatory inflection compresses commercialization windows for bio-based alternatives while rewarding first movers with qualified supplier status.
For Market Incumbents: Insulate margin structures by backward integration into chrome-free wire coating capabilities and captive recycling streams for polymer filaments. Defensive consolidation around REACH documentation expertise protects vendor qualification status as German automotive buyers compress supplier lists. Capacity addition in Czech and Polish manufacturing corridors captures carbon-border adjustment advantages for EU market access.
For New Entrants and Emerging Players: Build out bio-based polymer formulation capabilities targeting aerospace polishing applications where substrate damage tolerances approach zero and qualification premiums persist. The most penetrable white space sits in sensor-embedded brush systems for predictive maintenance contracts, with go-to-market traction through robotics integrators serving automated deburring cells in French and Italian precision manufacturing clusters.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among engineered brush specialists with predictive wear tracking capabilities and just-in-time replenishment contracts. Long-term viability over the next decade favors suppliers with demonstrated ECHA substance registration expertise and closed-loop manufacturing certifications. The signal to watch is buyer consolidation among German transmission and engine component manufacturers unbundling brush supply from broader MRO agreements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filament Production | Captures margin from steel wire and polymer inputs while securing REACH-compliant material traceability for German automotive buyers. |
| Sensor-Embedded Smart Brush Development | Enables predictive maintenance contracts with Stuttgart-Wolfsburg supplier networks and recurring data-service revenue streams. |
| Bio-Based Polymer Formulation Investment | Addresses EU Green Deal mandates ahead of 2030 deadlines, creating first-mover advantage in recyclable filament categories. |
| Regional Manufacturing Footprint Expansion | Positions suppliers to qualify for carbon-border adjustment preferences as EU tariffs on imported industrial goods take effect. |
| Technical Collaboration Partnerships | Secures vendor qualification with consolidating automotive Tier-1 suppliers demanding custom specification development capabilities. |
Methodological Framework
The analysis maps metal brush, nylon brush, wire brush, and duster brush sub-sectors, each validated through plant engineers at automotive OEMs, procurement leads at aerospace Tier-1 suppliers, aftermarket service heads at industrial distributors, and technical R&D directors at filament manufacturers. Primary interview insights triangulate against customs and trade data, ECHA substance registration databases, SEC 10-K filings from diversified industrial conglomerates, and production statistics from German automotive supplier associations. Bottom-up demand modeling from end-use application volumes converges with top-down market sizing from supplier revenue aggregation.
The forecast framework holds macroeconomic conditions, regulatory enforcement intensity, and technology adoption curves stable across the projection horizon while varying raw material cost trajectories and buyer consolidation scenarios. Segmentation dimensions include product type, end-user industry, application stage, and material chemistry, with CAGRs derived from elasticity-adjusted volume projections and value-per-unit trends. Industry-specific inputs incorporate REACH registration timelines for novel polymer formulations and automation penetration rates in surface-finishing operations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese polymer producers or unexpected ECHA substance bans would shift outcomes beyond modeled ranges. Quarterly review of German automotive production schedules, ferrous metal price indices, and ECHA authorization updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Magnetic Separator Market
Industrial Materials
US Industrial Fasteners Market
Industrial Materials
Industrial Mixers Market
Industrial Materials
Petrochemical Fasteners Market
Industrial Materials
Wood Fiber Insulation Market
Industrial Materials
Saudi Arabia Industrial Insulation Market
Industrial Materials
Japan Engineering Plastics Market
Industrial Materials
North America Activated Carbon Market
Industrial Materials
Food Grade Nylon Market
Industrial Materials
Flat Scroll Spring Market
Industrial Materials
Global Metal Anodizing Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
Ribbed Smoke Sheet Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Industrial Standoff and Spacer Market
Industrial Materials
Gravity Die Casting Market