
 Hybrid Paint Cans Market | 2026-2036
Hybrid Paint Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Paint Cans Market Outlook
Lightweight composite shell technology is reconfiguring how hybrid paint cans balance structural integrity against material cost. Mauser Packaging Solutions leverages its industrial scale to dominate bulk supply contracts for coating manufacturers across North America. Crown Holdings anchors its position through deep metal-forming expertise that it extends into hybrid laminate designs for premium architectural coatings.
Hybrid paint cans are engineered containers combining metal rims or shells with plastic, composite, or glass bodies, typically rated for 0.5 to 5 liter capacities and designed to resist corrosion from solvent-based or waterborne coatings while enabling resealability and stackability. Their primary purpose is to reduce shipping weight and material cost versus all-metal alternatives without sacrificing chemical compatibility or shelf stability. Spray cans within the product type dimension occupy the mature volume base, while specialty cans capture disproportionate margin due to custom lining requirements for epoxy and polyurethane formulations. Composite material grades represent the fastest-growing structural pocket as manufacturers navigate metal price volatility and EU circular-economy mandates.
EPA regulations on volatile organic compound emissions shape can lining specifications and closure integrity standards for products entering the US market, while REACH compliance in Europe forces material disclosure and substitution protocols across the supply chain. BIS certification requirements in India add a layer of product testing for imported hybrid containers used in decorative and industrial coatings. Buyers and manufacturers must monitor how fragmented national packaging recovery schemes alter total cost of ownership calculations for multi-material designs.
Market Dynamics
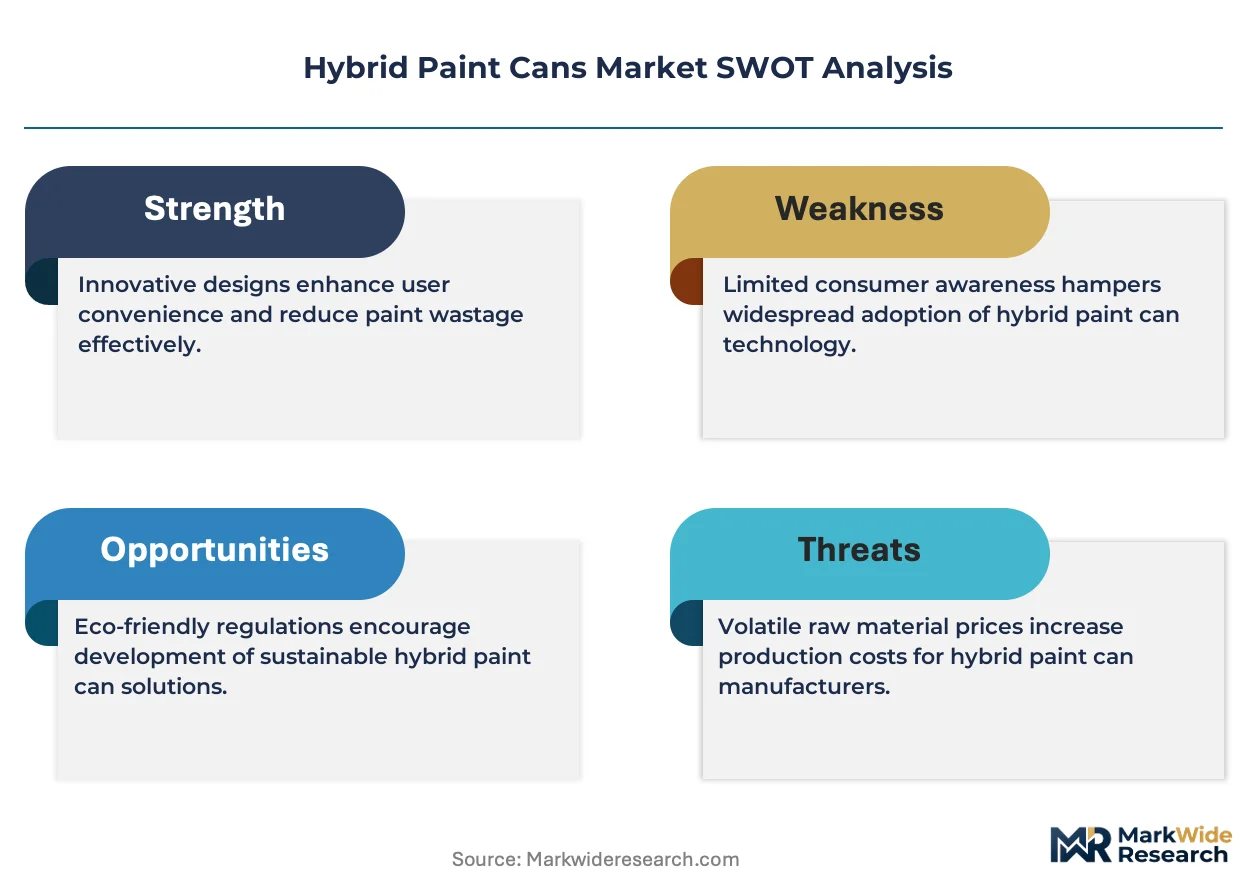
REACH and RoHS compliance in Europe is forcing manufacturers toward composite material formulations that eliminate volatile compound migration from hybrid paint can linings. This regulatory compression is accelerating R&D spend on barrier coatings while reshaping supplier qualification criteria across coating formulators.
Growth Catalysts
- Residential renovation intensity:Home improvement spending in Germany and France is pulling demand for reusable 2.5-5 liter hybrid formats that withstand multiple open-close cycles without seal degradation.
- ECHA substitution mandates:REACH Article 33 disclosure protocols are compelling coating manufacturers to specify cans with verified low-migration composite shells for solvent-based epoxy formulations.
- Lightweighting technology maturation:Glass-reinforced polypropylene shell production is achieving price parity with tinplate at volumes above 50,000 units, eroding the cost barrier to hybrid adoption.
Market Restraints
- Steel price volatility:Tinplate and cold-rolled steel input costs swing 15-40% annually, compressing margin on metal-rimmed hybrid designs and forcing hedging costs onto converters.
- Recycling infrastructure fragmentation:Germany's Duales System Deutschland achieves 90%+ recovery rates while neighboring markets lack multi-material separation capabilities, creating compliance cost asymmetry.
- Polypropylene supply concentration:European resin production clusters in Belgium and the Netherlands expose can manufacturers to single-point disruption risk from refinery maintenance cycles.
Strategic Opportunities
- India decorative coatings expansion:BIS certification requirements for imported hybrid containers create first-mover advantage for converters establishing local testing partnerships with Mumbai and Chennai laboratories.
- Waterborne polyurethane compatibility:Advanced fluoropolymer lining chemistries enable hybrid cans to capture share from steel pails in automotive refinish segments previously blocked by hydrolysis risk.
- EU Green Deal packaging mandates:The Packaging and Packaging Waste Regulation's 2030 recycled content targets position composite-shell hybrids ahead of all-metal alternatives on lifecycle scoring.
Industry Challenges
- Multi-material welding certification:Operators must qualify to ISO 15614-11 for plastic-metal joint integrity, extending technician training timelines by 4-6 months versus single-material can production.
- Legacy ERP integration:Coating manufacturers running SAP R/3 systems require custom middleware to track hybrid can batch numbers through REACH Article 33 supply chain disclosure workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Paint Cans Market |
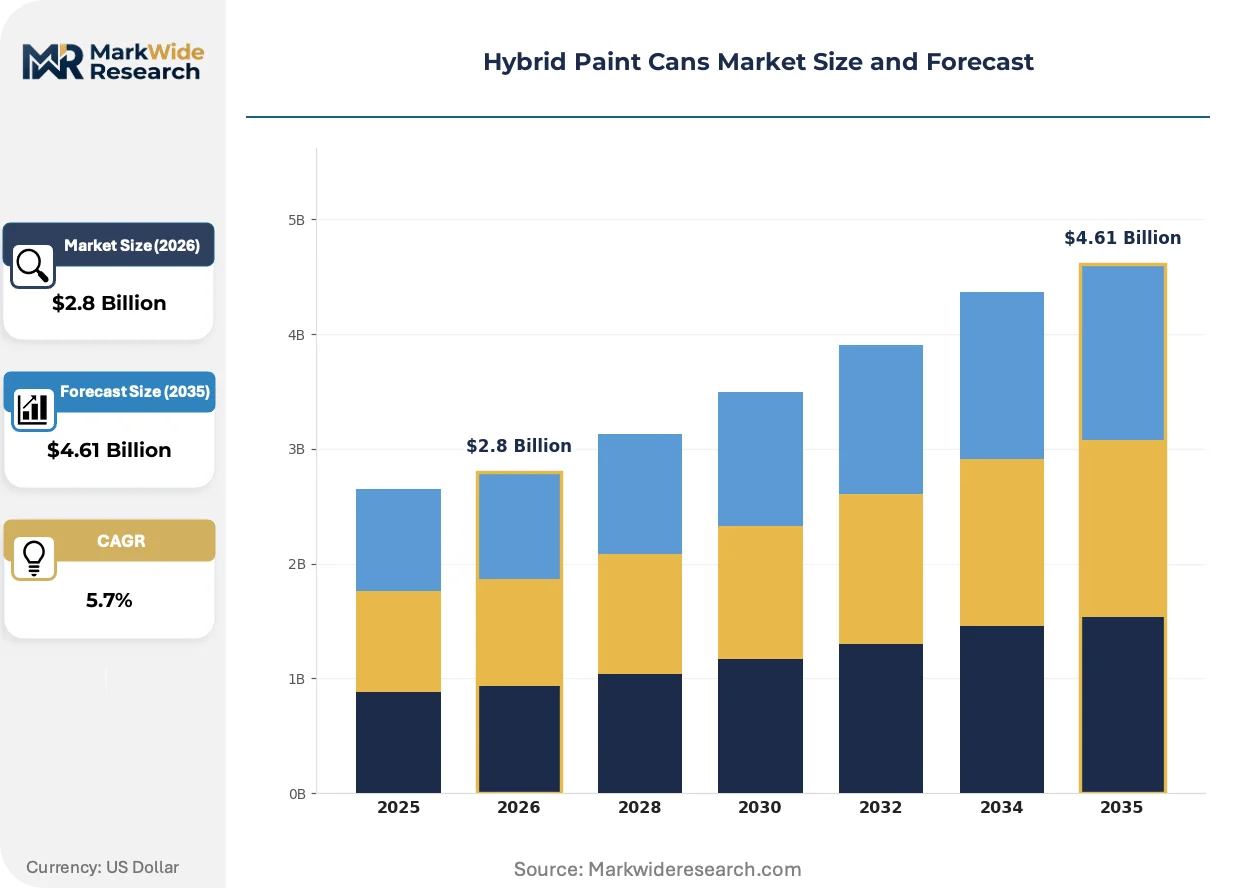
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray Cans, Disposable Cans, Reusable Cans, Specialty Cans Material: Plastic, Metal, Glass, Composite Application: Residential, Commercial, Industrial, Artistic Sales Channel: Retail, Wholesale, E-Commerce, Direct Sales |
| Companies Covered | Mauser Packaging Solutions, Ball Corporation, The Cary Company, Crown Holdings, Ardagh Group, Berlin Packaging, KW Container, Silgan Holdings, BWAY Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Paint Cans Market Strategic Shifts
Active barrier coating chemistry is displacing passive liner technologies across premium architectural and industrial coating segments. These innovations target the interface between shell material and aggressive solvent formulations.
Fluoropolymer-ceramic hybrid lining deposition is rendering obsolete conventional epoxy-phenolic spray coatings for polyurethane and epoxy formulations. Specialty coating manufacturers in Germany and Italy are specifying these linings for 5-liter hybrid cans intended for two-component industrial finishes. The technology is rendering obsolete the 12-18 month shelf-life limitation that previously constrained hybrid can penetration in high-performance segments.
REACH Annex XIV authorization requirements are tightening scrutiny on bisphenol-A derivatives in can lining formulations. Coating manufacturers serving the French and Dutch markets are accelerating qualification of alternative epoxy curing agents to maintain market access. The industrial maintenance coatings segment is absorbing the highest compliance burden, with reformulation timelines compressing from 36 months to 18 months.
Coating formulators are consolidating supplier panels from 8-12 hybrid can vendors to 3-4 strategic partners with integrated design and testing capabilities. This concentration is displacing spot-buy relationships in the German automotive refinish channel. The shift is most visible among mid-sized coating manufacturers seeking to outsource lining compatibility testing rather than maintaining in-house polymer laboratories.
Hybrid Paint Cans Market Segmentation
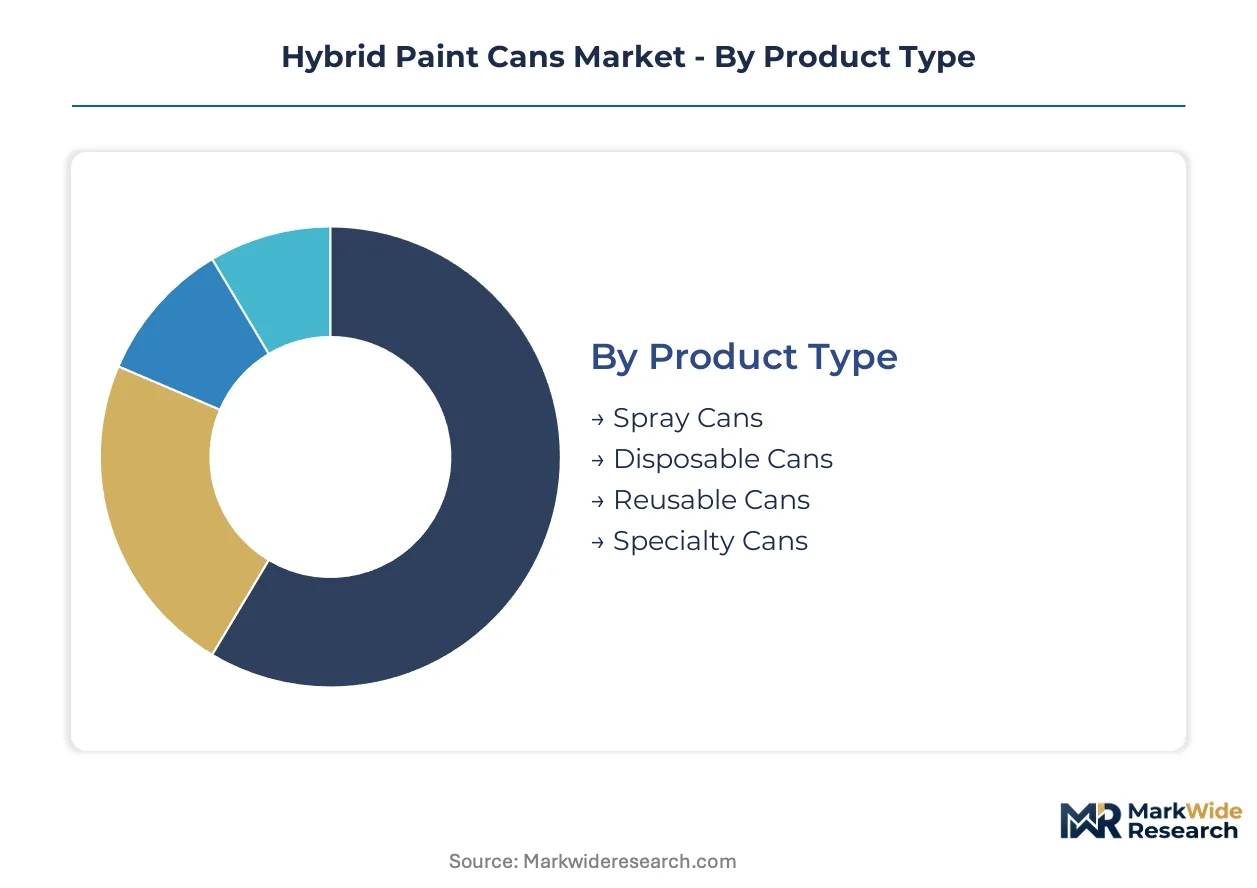
Segmentation in hybrid paint cans reveals how container specifications align with coating chemistry, handling intensity, and recovery economics. Each dimension carries distinct margin profiles and regulatory exposure that reshape supplier priorities across end-use channels.
Product Type:
Spray cans turn inventory fastest through mass-market retail, while specialty formats sit longest in specification and qualification cycles.
- Spray Cans:Pressurized metal or hybrid shells with integrated valve systems deliver pre-mixed coatings for consumer and light industrial touch-up. Demand clusters in North American big-box retail where one-time-use convenience outweighs unit economics for small-scale projects.
- Specialty Cans:Custom-engineered containers with fluoropolymer or ceramic-composite linings handle aggressive epoxy and polyurethane formulations. German automotive refinish shops and Italian industrial maintenance contractors specify these for solvent-based two-component systems requiring extended shelf stability and repeated resealability.
- Reusable Cans:Glass-reinforced polypropylene shells with metal rims withstand 15-20 open-close cycles for professional painters. France and Germany drive specification through packaging recovery mandates that reward durable formats.
- Disposable Cans:Thin-walled hybrid laminates designed for single-use residential applications balance cost against basic chemical resistance. These dominate volume in emerging markets where recovery infrastructure remains underdeveloped.
Spray cans dominate installed base. Specialty cans are where expansion concentrates.
Material:
Cost tier separates commodity inputs from engineered composites commanding qualification premiums.
- Composite:Glass-reinforced polypropylene or thermoplastic shell structures with metal rim integration achieve weight reductions of 30-40% versus all-metal alternatives. REACH Article 33 disclosure protocols and EU Green Deal packaging targets accelerate specification among coating formulators seeking lifecycle scoring advantages.
- Metal:Tinplate or cold-rolled steel rims and shells deliver maximum structural integrity for solvent-rich formulations. Steel price volatility and hedging costs compress converter margins, pushing specification toward hybrid alternatives in cost-sensitive segments.
- Plastic:Monopolymer polypropylene or polyethylene cans serve waterborne decorative coatings with limited solvent exposure. These capture share in residential renovation channels where chemical compatibility requirements remain modest.
- Glass:Borosilicate or soda-lime bodies with polymer sealing interfaces target premium artistic and specialty industrial segments requiring absolute chemical inertness. Belgium's chemical cluster and Dutch coating research facilities specify these for experimental formulations.
Metal dominates installed base. Composite is where expansion concentrates.
Application:
Volume concentration runs inverse to margin capture across end-use intensity levels.
- Industrial:High-volume coating operations for automotive, aerospace, and heavy equipment manufacturing specify 5-liter hybrid cans with advanced barrier linings. ECHA substitution mandates and REACH Annex XIV scrutiny on bisphenol-A derivatives drive reformulation and container requalification timelines.
- Residential:Home improvement and renovation activity in Germany and France pulls demand for 2.5-5 liter reusable formats. These applications prioritize ergonomic handling and multiple reseal cycles over maximum chemical resistance.
- Commercial:Property maintenance, construction finishing, and facility management operations balance cost against performance across mid-tier hybrid specifications. Procurement consolidation among facility services firms is narrowing supplier panels.
- Artistic:Fine art, craft, and specialty coating applications demand small-format containers with precise pouring control and contamination prevention. These segments absorb premium pricing for glass-bodied or specialized composite designs.
Industrial dominates installed base. Residential is where expansion concentrates.
Sales Channel:
Customer type determines service intensity and technical support requirements.
- Wholesale:Distributors serving professional painting contractors and industrial coating applicators demand batch traceability and REACH compliance documentation. These relationships carry 12-18 month contract cycles with technical service obligations.
- Direct Sales:Strategic accounts among multinational coating manufacturers negotiate integrated design and testing partnerships. Consolidation from 8-12 vendor panels to 3-4 strategic suppliers is most visible in this channel.
- Retail:Big-box and specialty hardware stores serve DIY consumers with standardized spray and disposable formats. Inventory velocity requirements favor established SKUs with predictable demand patterns.
- E-Commerce:Online channels capture growing share in specialty and hard-to-find formats, though hazardous material shipping regulations constrain expansion for solvent-based product offerings.
Wholesale dominates installed base. Direct sales is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports hybrid paint can systems to French and Italian coating formulators, establishing a north-south trade corridor that concentrates specification influence in Bavaria and Baden-Württemberg.
Germany
Industrial coatings output in North Rhine-Westphalia and Bavaria drives specification for 5-liter reusable formats with fluoropolymer linings. Duales System Deutschland mandates 90%+ packaging recovery rates, forcing converters toward composite-shell designs that score favorably on lifecycle assessments. Stuttgart's automotive refinish cluster demands advanced barrier coatings for two-component polyurethane systems.
France
Residential renovation intensity in Île-de-France and Auvergne-Rhône-Alpes pulls demand for 2.5-5 liter formats that withstand repeated open-close cycles. ANSM enforces strict migration limits on can lining materials for solvent-based decorative coatings. Lille's industrial maintenance sector specifies hybrid containers with ceramic-composite linings for epoxy formulations.
United States
EPA volatile organic compound regulations shape can lining specifications for architectural coatings entering California and Northeast markets. Big-box retail channels in Texas and Florida standardize on disposable spray formats for DIY consumers. Ohio's manufacturing belt sources bulk hybrid cans from distributors serving professional painting contractors.
India
BIS certification requirements for imported hybrid containers create qualification barriers for decorative coatings manufacturers in Maharashtra and Gujarat. Mumbai and Chennai laboratories handle compliance testing for multi-material can designs. Karnataka's emerging industrial coatings sector seeks local converter partnerships to bypass import lead times.
Italy
Specialty coating formulators in Lombardy and Emilia-Romagna specify custom-lined hybrid cans for solvent-based industrial finishes. REACH Article 33 disclosure protocols compel material substitution in can shell formulations. Milan's automotive refinish channel consolidates supplier panels to integrated design partners capable of lining compatibility testing.
Hybrid Paint Cans Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. The vendor base clusters around three strategic archetypes: industrial-scale converters with bulk supply contracts, metal-forming specialists extending into hybrid laminates, and regional fabricators serving spot-buy relationships. Dominant competitive moves include supplier panel consolidation among coating manufacturers and backward integration into lining chemistry capabilities.
Among North American industrial-scale players, Mauser Packaging Solutions and Crown Holdings occupy positions that exemplify divergent strategic anchors. Mauser leverages its industrial scale across bulk supply contracts for coating manufacturers. Crown extends deep metal-forming expertise into hybrid laminate designs for premium architectural coatings. Ball Corporation represents the diversified packaging conglomerate archetype with cross-segment technology transfer capabilities.
| Leading Market Players |
|---|
| Mauser Packaging Solutions |
| Ball Corporation |
| The Cary Company |
| Crown Holdings |
| Ardagh Group |
| Berlin Packaging |
| KW Container |
| Silgan Holdings |
| BWAY Corporation |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Antwerp freight corridor drives cost dynamics across hybrid paint can supply chains, with its barge-rail intermodal rates compressing margins for Belgian resin suppliers while enabling price differentiation between bulk contract buyers and spot-market purchasers in the German coatings belt.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange tinplate pricing dominate procurement between European converters and coating manufacturers. Price differentiation separates fluoropolymer-lined specialty formats from standard epoxy-phenolic alternatives, with certification tier and volume scale as secondary drivers. Cost compression in disposable laminates is intensifying because polypropylene resin volatility outpaces metal hedging instruments. DIY retail channels exhibit highest price sensitivity, while automotive refinish contractors absorb premium pricing for proven barrier performance.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supply-chain finance facilities offered by resin distributors to mid-tier can converters. Geographic concentration centers on Belgium and the Netherlands for polypropylene feedstock, Germany for metal forming, and Italy for specialty lining deposition. Raw material dependencies include tinplate, glass-reinforced polypropylene, and fluoropolymer resins. Single-source vulnerability from refinery maintenance cycles in the Port of Rotterdam complex threatens resin availability. Distribution runs through coatings distributors serving professional contractors, with direct sales capturing multinational formulator accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid paint cans are approaching a platform-economics inflection as REACH Article 33 disclosure protocols force interoperability between can batch tracking systems and coating manufacturer ERP platforms.
For Market Incumbents: Pre-empt supplier panel consolidation by acquiring lining chemistry capabilities or forming exclusive testing partnerships with Mumbai and Chennai laboratories. Backward integration into fluoropolymer-ceramic deposition technology defends margin position against emerging composite-shell specialists from South Korea. For New Entrants and Emerging Players: Establish a beachhead in India's BIS-certified decorative coatings segment before local converter partnerships solidify. Karnataka's emerging industrial coatings sector offers the most penetrable entry point, with certification advisory services as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with integrated design-and-test capabilities over pure manufacturing plays. The five-to-ten year viability window rewards acquisition targets possessing REACH compliance documentation infrastructure and established automotive refinish channel relationships. Watch for ECHA substitution mandate acceleration as the inflection signal triggering premium valuations for low-migration lining specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lining Chemistry | Captures margin from fluoropolymer-ceramic deposition currently outsourced to German and Italian specialists. |
| REACH Compliance Documentation Infrastructure | Enables supplier panel consolidation among coating manufacturers seeking outsourced Article 33 disclosure workflows. |
| Joint Venture with Indian Testing Laboratories | Bypasses BIS certification lead times for imported hybrid containers serving Maharashtra and Gujarat coatings manufacturers. |
| Capacity Expansion in Glass-Reinforced Polypropylene | Achieves price parity with tinplate at volumes above 50,000 units, eroding cost barriers to hybrid adoption. |
| Long-term Supply Agreement with Automotive Refinish Channel | Locks in specification for 5-liter reusable formats with advanced barrier coatings as supplier panels narrow to 3-4 partners. |
Study Parameters
The analysis maps spray can, specialty can, reusable can, and disposable can sub-sectors, each validated through procurement directors at coating manufacturers, technical R&D leads at can converters, and logistics managers at industrial distributors. Primary interviews with these stakeholders combined with secondary validation from ECHA substance registration databases, EU packaging recovery scheme reports, and customs trade data. Bottom-up unit economics and top-down market sizing triangulate volume estimates across material and application dimensions.
Assumptions held fixed include REACH Article 33 disclosure protocol stringency and EU Green Deal packaging mandate timelines, while steel price volatility and polypropylene supply disruption scenarios were varied across sensitivity runs. Segmentation dimensions modeled include product type, material grade, application intensity, and sales channel structure. CAGRs derive from regression against residential renovation spending indices and industrial coatings output trends, with input from fluoropolymer lining adoption curves and multi-material recycling infrastructure development rates.
Stress conditions across tinplate price swings, refinery maintenance frequency, and BIS certification processing delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and baseline conditions. Macroeconomic contraction, regulatory timeline acceleration, or breakthrough monomaterial lining technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Road Marking Paint Market
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Bio-Based and Low VOC Paints Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Oman Paints and Coatings Market
Paints & Coatings
Paints and Coatings Additives Market
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
Global Aerosol Paints Market
Paints & Coatings
Automotive Paints Market
Paints & Coatings
India Floor Coatings Market
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
Paint and Coating Stripper Market
Paints & Coatings
Refinish Paint Market
Paints & Coatings
Asia-Pacific Paint Spray Guns Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
Automotive Paints and Coatings Market