
 Global Machined Seals Market | 2026-2036
Global Machined Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Machined Seals Market Foresight
Modular cartridge seal assemblies are repositioning buyer procurement patterns across energy and process industries. Trelleborg AB leverages its polymer compounding expertise to dominate niche elastomeric configurations for subsea applications. Freudenberg SE anchors European supply through backward integration into advanced fluoroelastomer materials. SKF competes by extending its rotating equipment service network into predictive seal monitoring.
Machined seals are precision-manufactured sealing devices engineered to tight tolerances, typically from metallic alloys, engineered polymers, or composite laminates, designed to prevent fluid leakage between static or dynamic mating surfaces in rotating equipment. These components function under extreme pressure, temperature, and chemical exposure conditions in pumps, compressors, and turbomachinery. Metallic seal configurations lead in high-temperature petrochemical applications where creep resistance and thermal stability determine service life. Non-metallic variants, particularly PTFE and PEEK compounds, represent the fastest-growing technology category as chemical processors seek corrosion-resistant alternatives to traditional metal seals. Composite segment margin pools concentrate in aerospace-derived fiber-reinforced designs that bridge the performance gap between pure metal and polymer solutions.
EPA emissions standards and the EU F-Gas Regulation are forcing seal manufacturers to eliminate fugitive methane and fluorinated gas leakage across valve and pump installations. China's SAMR enforces GB/T compliance for imported sealing materials used in critical pressure equipment, creating certification barriers for non-domestic suppliers. FDA food-contact regulations and ISO 21049 petroleum-natural gas standards further fragment compliance requirements across end-use sectors. Stakeholders must monitor evolving material restrictions and qualification protocols to sustain market access across regulated jurisdictions.
Market Dynamics
Modular cartridge seal architectures are compressing procurement cycles across energy and process sectors, forcing traditional component suppliers to bundle predictive monitoring and field service capabilities into hardware contracts.
Growth Catalysts
- EPA methane regulations:Fugitive emissions mandates for valve and pump installations are accelerating replacement schedules for legacy sealing systems in US upstream operations.
- Subsea infrastructure expansion:Deepwater field developments in Brazil and West Africa are generating demand for pressure-rated elastomeric seal configurations rated to 3,000-meter depths.
- Fluoroelastomer compounding advances:Next-generation FKM and FFKM compounds with enhanced chemical resistance are extending service intervals in sulfuric acid processing environments.
Market Restraints
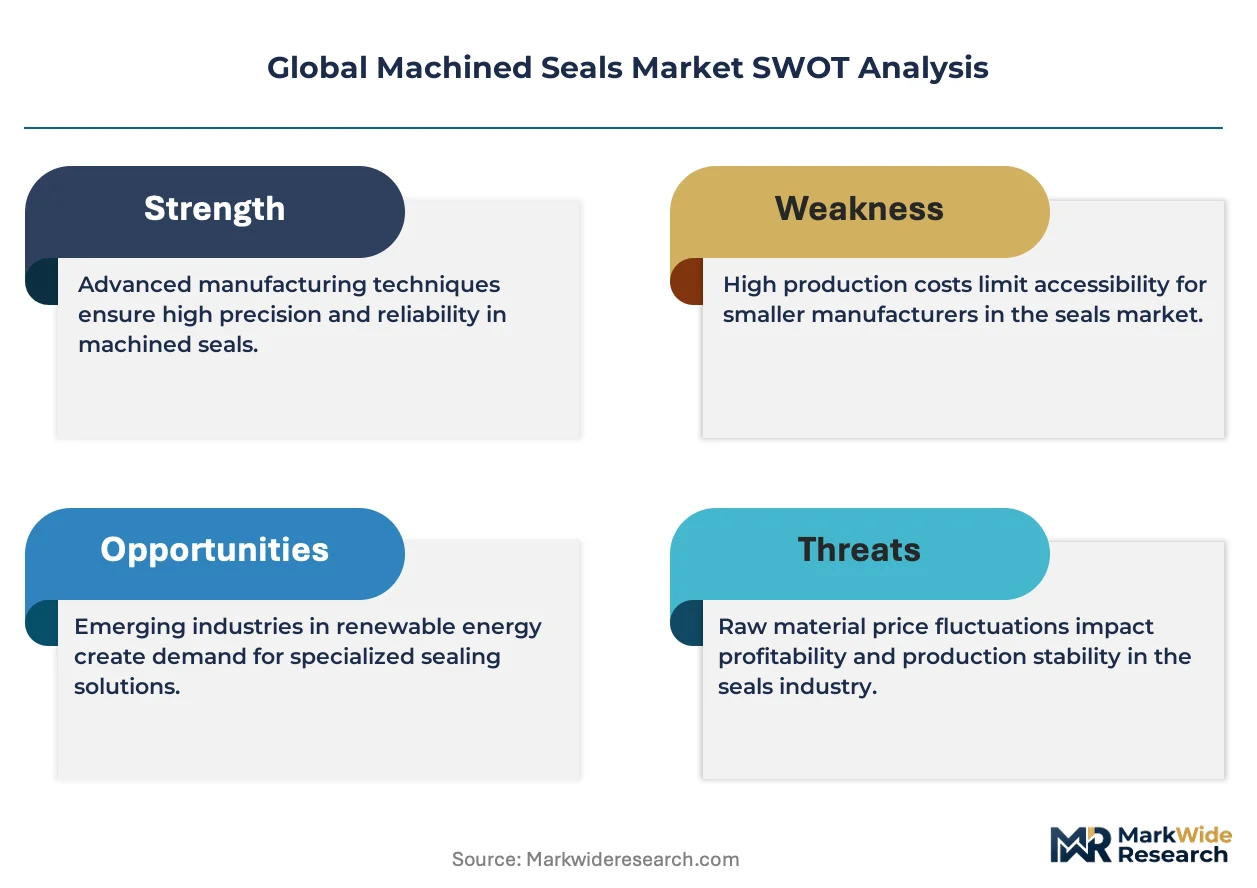
- Raw material concentration:Virgin PTFE resin supply concentrates among a handful of Chinese and US chemical producers, exposing converters to price volatility and allocation risk.
- REACH compliance costs:EU chemical registration requirements for novel seal compounds impose six-figure qualification expenses that disproportionately burden mid-tier manufacturers.
- Metal seal substitution ceiling:Cryogenic LNG applications below minus 200 degrees Celsius still require nickel-based superalloy configurations that polymer solutions cannot displace.
Strategic Opportunities
- India's petrochemical buildout:Reliance Industries and Indian Oil Corporation are expanding ethylene capacity, creating demand for high-temperature compressor seals in cracking furnace service.
- EU F-Gas phase-down:The 2030 refrigerant containment mandates are stimulating demand for low-permeation barrier seals in commercial HVAC scroll compressors.
- Digital twin convergence:Integration of seal wear models with asset performance management platforms is enabling predictive replacement scheduling for turbomachinery operators.
Industry Challenges
- Polymer tribology expertise gap:Compound formulation knowledge for extreme-pressure PTFE blends resides with a shrinking cohort of specialized chemists nearing retirement.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of API 682, ISO 21049, and China TS certification for a single product line extends time-to-revenue by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Machined Seals Market |
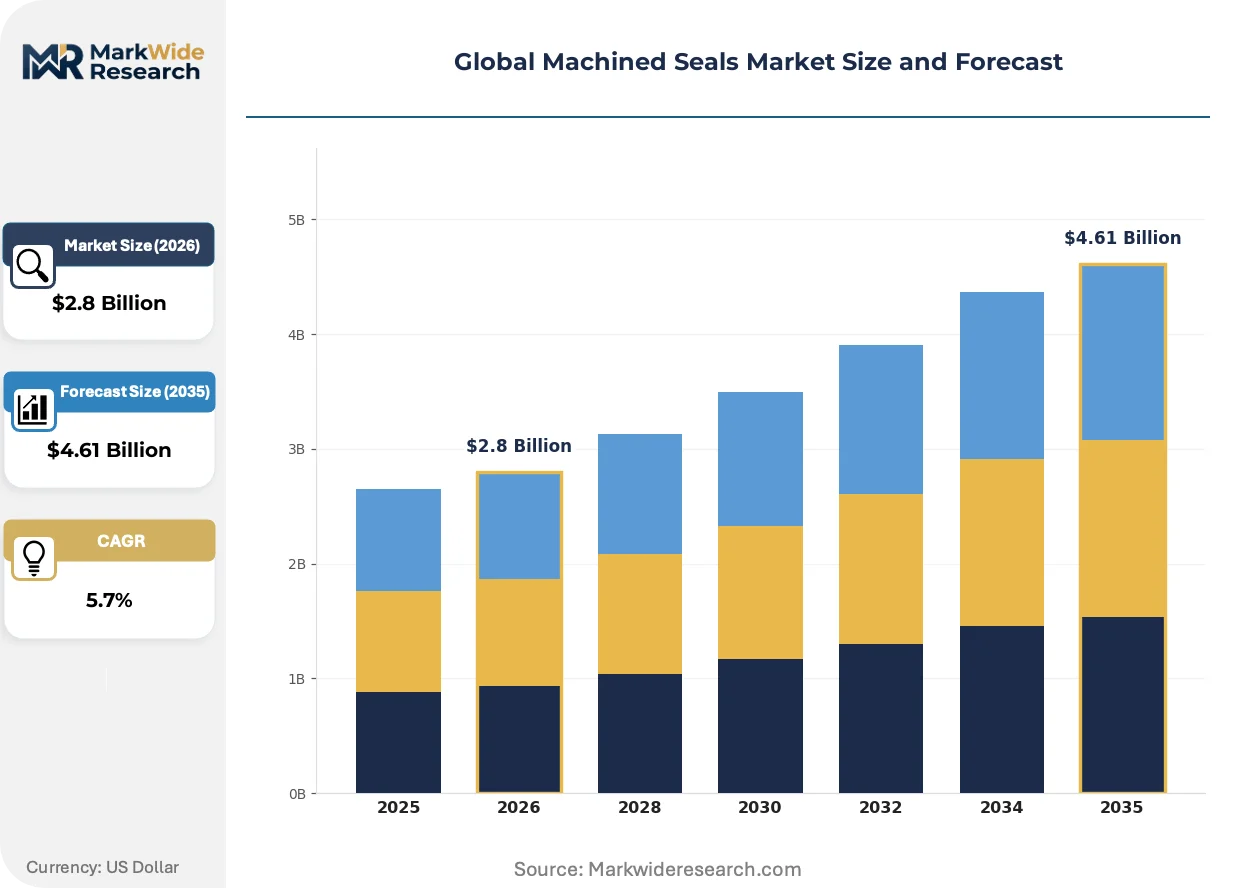
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic, Non-Metallic, Semi-Metallic, Composite Technology: Mechanical Face, Elastomeric, Piston, Gland, Magnetic Application: Pump Units, Compressors, Turbomachinery, Gearboxes, Hydraulic Systems End User: Power Generation, Petrochemical Plants, Marine Engineering, Chemical Processing |
| Companies Covered | Trelleborg AB, Freudenberg SE, SKF, Technetics Group, EnPro Industries, Flowserve Corporation, The Timken Company, Hi-Tech Seals, John Crane, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Machined Seals Market Shifts & Advancements
Intelligent sealing systems with embedded condition monitoring are redefining value capture models, shifting supplier economics from unit sales toward performance-based service agreements.
Laser-sintered metal seal geometries are automating production of complex labyrinth profiles previously requiring multi-axis machining. Turbomachinery OEMs in Germany and Japan are qualifying these additively manufactured configurations for intermediate-pressure steam applications. The technology is automating customization of seal face topography to match specific rotor dynamics, compressing prototype lead times from weeks to days.
China's GB/T 34525 standard for critical pressure equipment sealing materials is tightening material traceability requirements for imported compounds. SAMR enforcement actions against non-compliant suppliers have accelerated localization investments by European and Japanese seal manufacturers. The regulation is forcing dual-sourcing strategies that split production between domestic Chinese facilities and heritage plants in home markets.
Aftermarket service unbundling is fragmenting traditional distributor relationships in North American process industries. End-users in Texas and Louisiana refineries are contracting directly with seal manufacturers for inventory management and installation supervision, bypassing local distributors. This disintermediation concentrates in high-spend accounts with dedicated reliability engineering teams and multi-site procurement leverage.
Global Machined Seals Market Segmentation
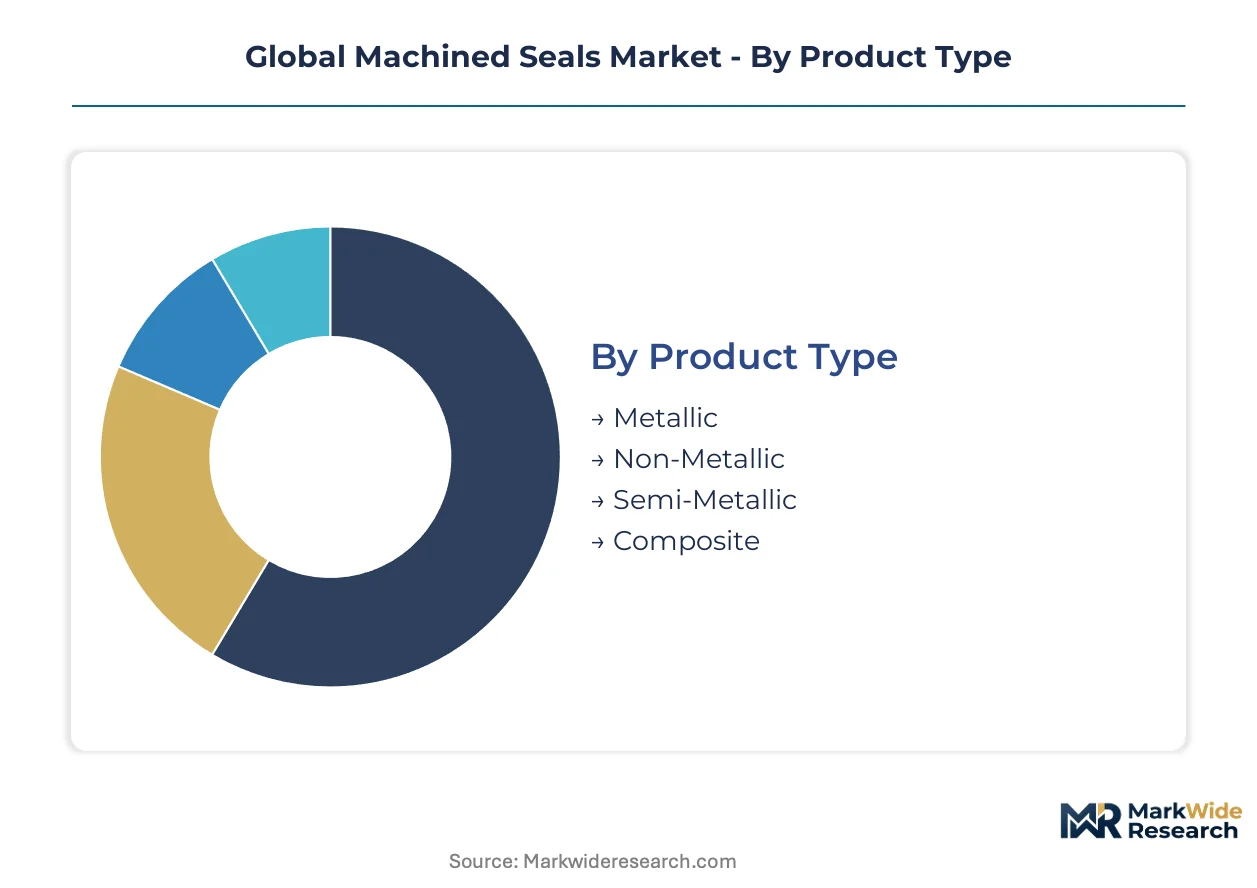
Segmentation in machined seals reflects divergent capital requirements across material systems and sealing architectures. Procurement decisions hinge on pressure-temperature ratings, chemical compatibility matrices, and lifecycle cost models rather than unit price alone.
Product Type:
Capital intensity peaks with metallic configurations requiring precision CNC machining of superalloy forgings and heat treatment infrastructure.
- Metallic:Nickel-based superalloy and stainless steel seals dominate high-temperature petrochemical cracking furnaces where creep resistance determines replacement intervals. German turbomachinery OEMs specify these for steam turbine applications above 500°C.
- Non-Metallic:PTFE and PEEK compounds command specialized polymer compounding and sintering equipment. Chemical processors in Louisiana and Rotterdam favor these for sulfuric acid service where metal corrosion accelerates failure.
- Semi-Metallic:Spiral-wound designs with graphite or PTFE fillers bridge cost-performance gaps in refinery valve applications.
- Composite:Fiber-reinforced laminates require autoclave curing and ply optimization expertise derived from aerospace supply chains.
Most installed capacity flows through Metallic seals. Expansion is steepest in Non-Metallic configurations.
Technology:
Application severity dictates technology selection, with face seal architectures commanding premium engineering margins in critical rotating equipment.
- Mechanical Face:Precision-lapped seal faces in cartridge assemblies prevent leakage in centrifugal pumps handling volatile hydrocarbons. API 682 compliance mandates govern procurement in Texas and Alberta upstream operations.
- Elastomeric:Molded and machined O-rings, lip seals, and custom profiles serve lower-pressure hydraulic circuits. FKM and FFKM compounds from Japanese suppliers dominate subsea Christmas tree installations off Brazil.
- Piston:Machined rings and packings seal reciprocating compressors in natural gas transmission stations.
- Gland:Compression packing sets remain cost-competitive in valve stem applications with lower cycle frequency.
- Magnetic:Ferrofluid seals enable hermetic rotary feedthroughs in semiconductor vacuum processing equipment.
Mechanical Face technology captures the highest service contract values. Magnetic seals are climbing the fastest as wafer fabrication capacity expands.
Application:
Duty cycle intensity varies dramatically across equipment categories, with continuous turbomachinery service demanding predictive maintenance integration.
- Pump Units:Centrifugal and positive displacement pumps in refining and chemical plants account for the largest seal consumption volume. EPA methane regulations are accelerating replacement of legacy packing in US upstream facilities.
- Compressors:Axial and centrifugal gas compressors in pipeline service require dry gas seal systems with filtration and monitoring subsystems.
- Turbomachinery:Steam and gas turbines in combined-cycle power plants specify labyrinth and brush seals for interstage pressure containment.
- Gearboxes:Industrial gear reducers utilize radial lip seals with PTFE excluders in mining and cement applications.
- Hydraulic Systems:Cylinder rod seals and piston seals in construction and agricultural equipment face contamination and pressure spike challenges.
Pump Units absorb the greatest seal volume. Turbomachinery commands the highest per-unit engineering service attach rates.
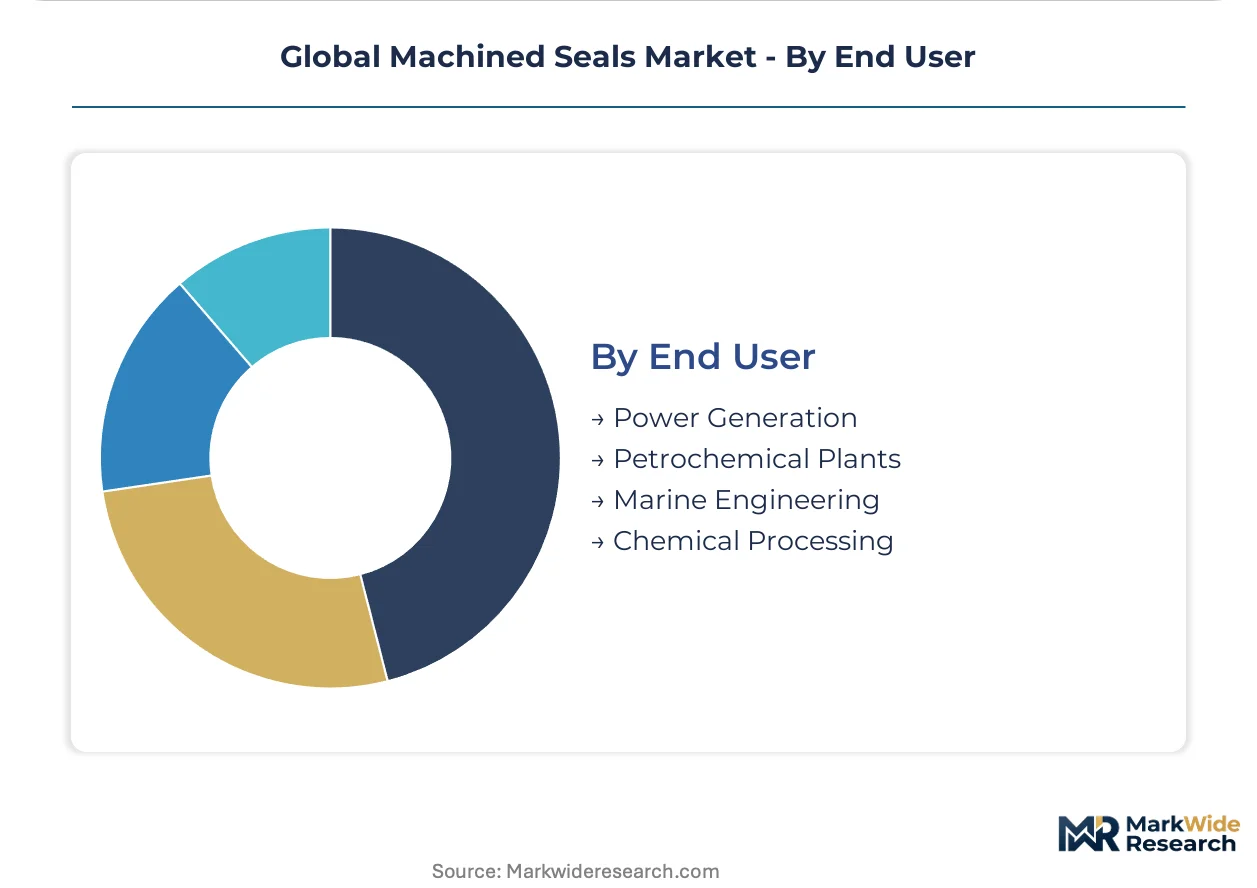
End User:
Reliability culture and total cost of ownership sophistication differentiate procurement patterns across vertical sectors.
- Power Generation:Combined-cycle gas turbine operators in Japan and Germany prioritize seal monitoring integration with asset management platforms. Rotating equipment availability targets of 95%+ justify premium seal configurations.
- Petrochemical Plants:Ethylene crackers and aromatics complexes in India and the US Gulf Coast drive demand for high-temperature metallic seals. Reliance Industries and Dow specify API-compliant cartridge assemblies for critical pumps.
- Marine Engineering:Propulsion shaft seals and stern tube systems for commercial shipping face IMO environmental compliance pressures.
- Chemical Processing:Specialty chemical manufacturers in Switzerland and Belgium specify FFKM compounds for aggressive solvent exposure.
Petrochemical Plants represent the dominant installed base. Power Generation is expanding most quickly as grid balancing capacity requirements grow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The machined seals industry traces its commercial roots to German precision engineering traditions of the early twentieth century, when industrial seal fabrication for turbomachinery first achieved standardized tolerances. Today, manufacturing and demand distribute across specialized industrial clusters on four continents.
United States
EPA methane regulations are accelerating replacement schedules for legacy sealing systems across Texas and Louisiana refineries. The Bureau of Safety and Environmental Enforcement enforces strict containment standards for offshore equipment. Houston anchors the largest concentration of petrochemical seal demand, with operators contracting directly with manufacturers for inventory management.
Germany
Turbomachinery OEMs in Baden-Württemberg and Bavaria specify high-temperature metallic seals for steam turbine applications exceeding 500°C. The KBA and federal environmental agencies enforce emissions compliance for rotating equipment. The Rhine-Ruhr industrial corridor concentrates demand from chemical processors seeking corrosion-resistant polymer alternatives.
China
SAMR enforcement of GB/T 34525 standards is tightening material traceability requirements for imported sealing compounds. The MIIT oversees industrial equipment safety certifications. Yangtze River Delta petrochemical complexes are driving localization investments by European and Japanese seal manufacturers seeking market access.
Japan
METI industrial policy supports advanced fluoroelastomer development for semiconductor and precision machinery applications. JIS standards govern material specifications for critical pressure equipment. The Chubu region around Nagoya anchors demand from automotive and aerospace manufacturing supply chains.
India
Reliance Industries and Indian Oil Corporation are expanding ethylene capacity, creating demand for high-temperature compressor seals in cracking furnace service. The BIS enforces conformity assessment for imported industrial materials. Gujarat's petrochemical corridor is emerging as the primary concentration of seal procurement from international suppliers.
Global Machined Seals Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive polymer compounding capabilities. Market concentration remains moderate, with a handful of European and North American groups commanding premium segments while regional specialists serve price-sensitive procurement. Three archetypes dominate: vertically integrated material-science conglomerates, rotating equipment service platforms, and niche subsea specialists. Capacity expansion and backward integration into advanced elastomer materials represent the primary competitive vectors.
Within the material-science tier, Trelleborg AB and Freudenberg SE exemplify European conglomerates with deep polymer formulation heritage. SKF represents the rotating equipment service platform model, extending bearing and maintenance networks into seal monitoring. These three occupy positions that reflect divergent strategic bets on technology versus service bundling.
| Leading Market Players |
|---|
| Trelleborg AB |
| Freudenberg SE |
| SKF |
| Technetics Group |
| EnPro Industries |
| Flowserve Corporation |
| The Timken Company |
| Hi-Tech Seals |
| John Crane |
| Others |
Supply & Pricing Matrix
Large petrochemical operators in the US Gulf Coast and Indian refining corridors negotiate multi-year framework agreements that compress supplier margins through volume guarantees and bundled service requirements. This procurement concentration forces tiered pricing stratification across premium API-certified cartridge assemblies, standard industrial configurations, and economy-grade compression packings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement dynamics. Premium tiers attach to API 682-compliant mechanical face seals with predictive monitoring integration, while economy segments serve low-cycle valve packing applications. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Chinese converters are flooding spot markets with generic PTFE compounds. Mid-tier refineries in Texas demonstrate highest price sensitivity, whereas Japanese power generators prioritize performance over unit cost.
Supply Chain Analysis
Remanufacturing flows for metallic seal faces and cartridge assemblies create secondary material loops that extend component lifecycles and buffer virgin superalloy demand. Primary manufacturing concentrates in Germany, Japan, and the United States for precision CNC machining of nickel-based forgings. Raw material dependencies draw from Chinese virgin PTFE resin, US fluoroelastomer feedstocks, and European specialty polymer additives. Single-source vulnerability concentrates in Chinese PTFE supply, where allocation risk spikes during export license reviews. Distribution runs through authorized service centers and direct OEM partnerships, bypassing traditional industrial distributors in high-spend accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance costs in the EU REACH framework run approximately triple those in India's BIS conformity system, creating arbitrage opportunities for manufacturers with dual-certified production footprints.
For Market Incumbents: Extend predictive monitoring capabilities into seal-as-a-service contracts before rotating equipment OEMs capture this attach rate. Consolidate position through backward integration into fluoroelastomer compounding to offset raw material price volatility from Chinese suppliers. Defend against disintermediation by embedding inventory management and installation supervision directly with Gulf Coast refinery accounts. For New Entrants and Emerging Players: The mid-tier price gap between premium API-certified seals and economy packings offers entry space for specialized polymer compounders with localized production. Target India's expanding ethylene capacity buildout, where Reliance Industries and Indian Oil Corporation seek qualified domestic suppliers for high-temperature compressor seals. Pursue certification-first go-to-market positioning, securing BIS and API compliance before commercial engagement. For Investors and Strategic Acquirers: Rotating equipment service platforms are the most active acquirer in this space, seeking seal monitoring capabilities to complete predictive maintenance portfolios. Long-term viability favors compounders with captive polymer formulation expertise over pure hardware manufacturers. Watch for inflection in SAMR enforcement intensity against non-compliant imports as signal for localization investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoroelastomer Compounding | Captive supply of FKM and FFKM materials insulates Freudenberg and Trelleborg from Chinese resin volatility. |
| Predictive Seal Monitoring Platform Launch | SKF's rotating equipment service network extends into condition-based replacement scheduling for turbomachinery operators. |
| Localized Production Investment in China | European manufacturers establish Yangtze River Delta facilities to satisfy GB/T 34525 traceability mandates. |
| API 682 Certification Acceleration | Mid-tier suppliers compress 18-month qualification timelines to capture EPA-driven replacement demand in US upstream. |
| Subsea Elastomeric Seal Qualification | Pressure-rated configurations for 3,000-meter depths unlock Brazilian and West African deepwater field developments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged seal design engineers at turbomachinery OEMs, procurement leads at petrochemical operators, aftermarket service directors, polymer compounding specialists, and regulatory compliance officers. Secondary validation drew from API certification registries, EPA enforcement databases, SAMR import inspection records, customs trade flows, and SEC filings of listed industrial conglomerates. Bottom-up demand modeling triangulated against top-down market sizing across material categories.
Segment-weighting approaches distributed value estimates across metallic, non-metallic, semi-metallic, and composite material systems, then cross-referenced against mechanical face, elastomeric, piston, gland, and magnetic technology architectures. End-use weightings incorporated pump unit, compressor, turbomachinery, gearbox, and hydraulic system duty cycles. CAGRs derived from regression analysis of historical replacement rates, regulatory compliance deadlines, and capital expenditure pipelines across the projection horizon. Industry-specific inputs included EPA methane rule implementation timelines and subsea field development sanctioning velocity.
The model assumes a particular technology adoption path; alternative pathways for laser-sintered metal seal geometries would alter the outlook if turbomachinery OEMs accelerate qualification beyond intermediate-pressure steam applications. Forecasts reflect base-case assumptions regarding REACH compliance cost trajectories and Chinese localization enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Gaskets and Seals Market
Industrial Materials
Middle East Activated Carbon Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Industrial Gaskets Market
Industrial Materials
Global Friction Materials Market
Industrial Materials
Wire Hoods Market
Industrial Materials
Isostatic Pressing Market
Industrial Materials
Argon Knife Market
Industrial Materials
Japan Engineering Plastics Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
Chalk Reel and Line Chalk Market
Industrial Materials
Mineral Wool Market
Industrial Materials
Precipitated Silica Market
Industrial Materials
UHP Graphite Electrode Market
Industrial Materials
Noise Reduction Plastic Gear Market
Industrial Materials
Compression Gas Spring Market