
 Italy Chocolate Market | 2026-2036
Italy Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Chocolate Market Insights
Premium household consumers are redrawing demand patterns away from mass-market gifting, pulling volume toward single-origin and bean-to-bar offerings. Ferrero International SA leverages its Piedmontese heritage and in-house hazelnut supply chains to dominate the gianduja segment. Venchi SpA competes through vertical integration from cocoa sourcing to flagship retail in Milan and Turin. Lindt & Sprüngli AG anchors the premium imported segment with disciplined Swiss manufacturing standards and controlled distribution.
Italy chocolate comprises cocoa mass, cocoa butter, sugar, and milk solids formulated through conching, tempering, and molding processes to achieve defined particle size below 30 microns for mouthfeel standards. Dark chocolate leads product type value pools due to higher cocoa content and health-positioned margins, while ruby chocolate represents the fastest-growing novelty segment driven by natural pink coloration without artificial additives. Specialty stores capture disproportionate margin share within distribution channels by curating regional craft labels and direct-provenance storytelling.
EFSA governs food contact materials and contaminant thresholds for cocoa products, while EU Green Deal sustainability frameworks mandate deforestation-free supply chain verification. The F-Gas Regulation restricts refrigerant gases in tempering and storage equipment, forcing capital upgrades among mid-sized processors. Stakeholders must monitor how EU Deforestation Regulation enforcement timelines reshape cocoa procurement costs and origin documentation requirements.
Market Dynamics
Italian chocolate processors face a structural squeeze between EU Deforestation Regulation compliance costs and premium consumer willingness to pay for traceable provenance. The F-Gas Regulation accelerates capital replacement cycles for tempering equipment across Piedmontese manufacturing clusters.
Growth Catalysts
- EU Deforestation Regulation:Mandatory geolocation verification for cocoa sourcing creates competitive moats for early-compliant processors with documented supply chains.
- Bean-to-bar microprocessing:Small-batch equipment proliferation enables regional craft labels to capture specialty store margins previously reserved for industrial scale.
- Northern industrial clusters:Concentrated expertise around Turin and Milan generates knowledge spillovers that reduce formulation R&D costs for adjacent processors.
Market Restraints
- Cocoa butter price volatility:Weather-driven West African supply disruptions transmit directly to Italian processor margins with limited hedging instruments.
- F-Gas equipment retrofit burden:Mid-sized tempering operations face stranded asset risk as hydrofluorocarbon-based systems require replacement before depreciation cycles complete.
- Artisanal labor scarcity:Traditional conching expertise concentrates among aging workforce cohorts with inadequate vocational pipeline replenishment.
Strategic Opportunities
- Sicilian organic cocoa cultivation:Experimental terroir development offers domestic provenance storytelling for premium positioning against imported bean dependence.
- Direct-to-consumer subscription channels:Monthly curated tasting boxes bypass wholesale margin compression while building recurring revenue stability.
- Ruby chocolate line extensions:Natural pink coloration without artificial additives captures novelty-seeking gifting segments unserved by conventional dark-milk-white portfolios.
Industry Challenges
- EFSA contaminant threshold compliance:Cadmium and lead testing protocols require laboratory infrastructure investments that fragment smaller processors.
- Legacy tempering system integration:Continuous flow automation retrofits conflict with batch-oriented facility layouts inherited from post-war industrial expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Chocolate Market |
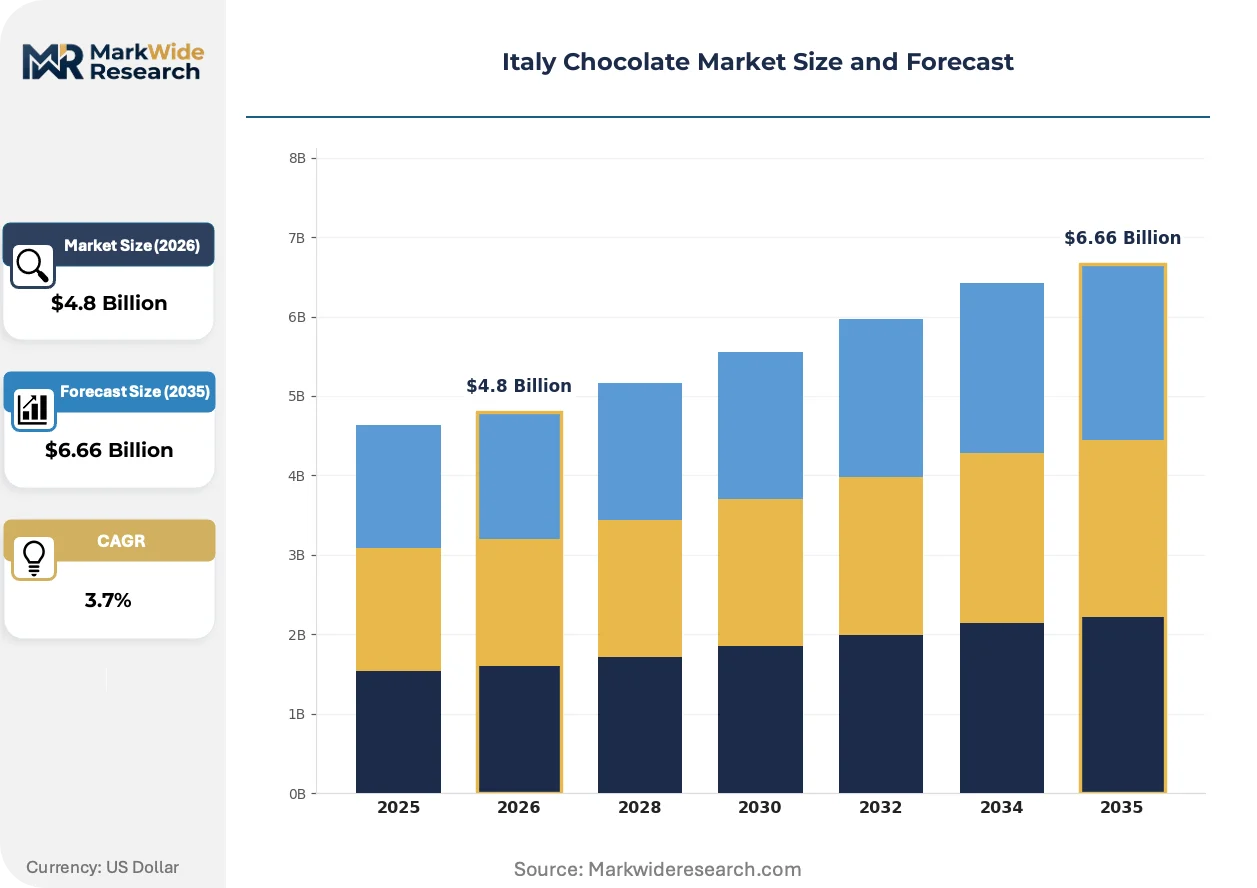
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate Distribution Channel: Retail Stores, Online Retail, Supermarkets, Specialty Stores Packaging Type: Bags, Bars, Boxes, Bulk End User: Consumers, Bakeries, Restaurants, Cafes |
| Companies Covered | Ferrero International SA, Lindt & Sprüngli AG, Venchi SpA, Nestlé SA, Mondelēz International Inc., Bauli SpA, ICAM SpA, Mars Incorporated, A. Loacker Spa/AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Chocolate Market Trends and Innovations
Premium consumption patterns are fragmenting demand away from standardized gifting formats toward personalized provenance narratives. Technology and regulation are jointly reshaping how Italian processors configure production and distribution.
Precision conching control systems utilizing real-time particle size monitoring are displacing empirical operator judgment in mouthfeel standardization. Mid-sized Turin processors adopt these sensors fastest, compressing quality variance that previously differentiated artisanal from industrial output. The technology is displacing traditional apprenticeship-based quality assurance with data-driven consistency protocols.
EFSA food contact material standards and EU Green Deal sustainability frameworks now mandate deforestation-free documentation across all cocoa-derived products. Italian importers must verify geolocation coordinates for 100% of sourced beans by enforcement timelines, forcing procurement system overhauls. Dark chocolate processors with established direct-origin relationships face lower compliance friction than traders reliant on spot-market sourcing.
Specialty store curation is capturing disproportionate margin share by replacing supermarket aisle anonymity with regional craft label storytelling. Milan and Turin flagship locations now function as provenance education venues where consumers pay premiums for bean-to-bar transparency. This channel shift concentrates volume among vertically integrated domestic processors while squeezing imported mass-market distributors.
Italy Chocolate Market Segmentation
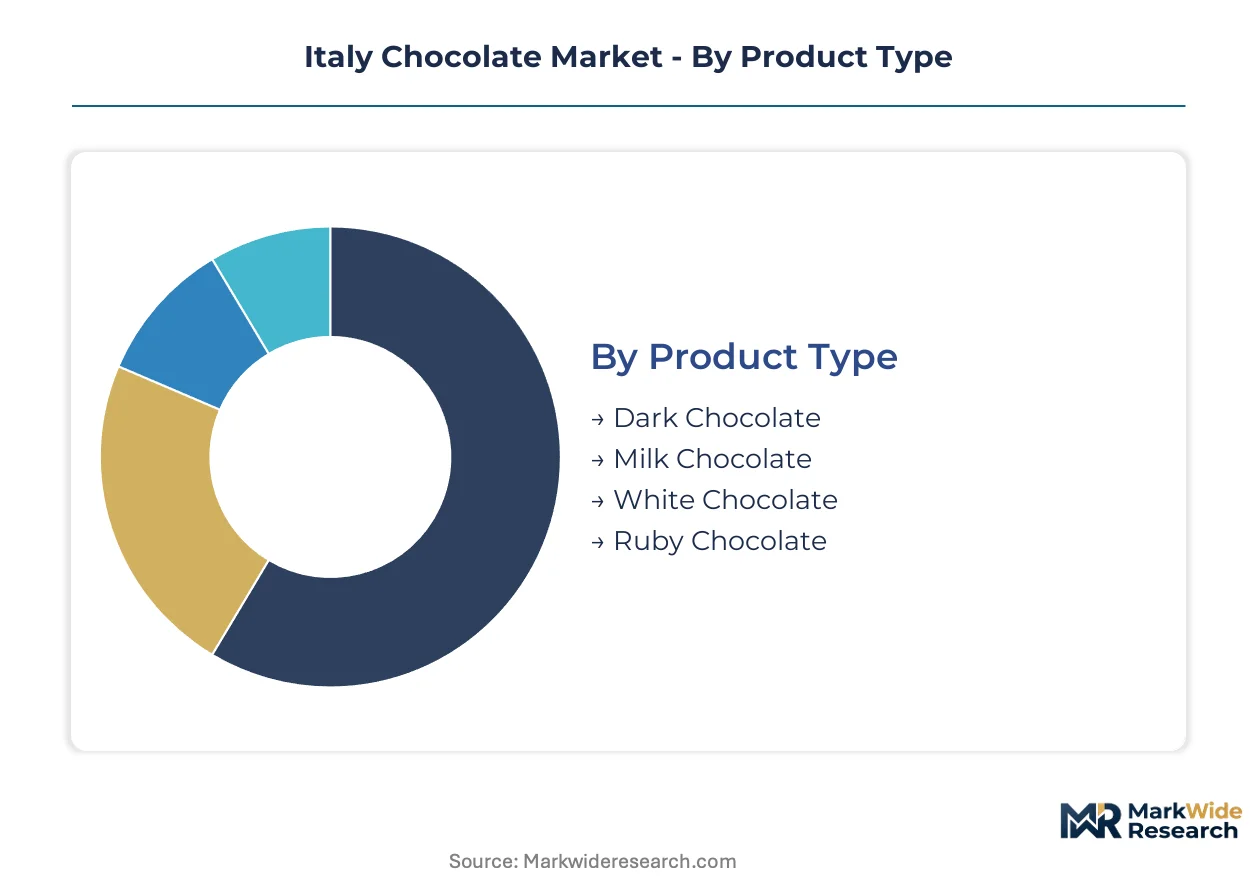
Segmentation in the Italian chocolate market reveals how premiumization pressures and regulatory compliance costs distribute unevenly across product formats and channels. Understanding these fault lines helps processors allocate capital toward defensible margin pools.
Product Type:
Substitution pressure from health-positioned alternatives and novel colorants reshapes which cocoa formulations retain pricing power.
- Dark Chocolate:Formulated with cocoa mass exceeding 50% and minimal milk solids, achieving particle size below 30 microns through extended conching. Northern industrial clusters around Turin concentrate demand for high-cocoa-content bars as EFSA contaminant thresholds favor processors with laboratory testing infrastructure.
- Ruby Chocolate:Derived from specific ruby cocoa beans through proprietary processing that releases natural pink anthocyanins without artificial additives. Specialty stores in Milan capture disproportionate margins from novelty-seeking gifting segments unserved by conventional portfolios.
- Milk Chocolate:Combines cocoa solids with elevated milk powder content for creamier mouthfeel profiles preferred in mass-market retail formats.
- White Chocolate:Cocoa butter-based formulation without cocoa mass, facing substitution from plant-based white alternatives in vegan-positioned channels.
Dark chocolate retains volume leadership; ruby chocolate holds the steepest expansion curve.
Distribution Channel:
Margin capture concentrates where provenance storytelling justifies price premiums above commodity benchmarks.
- Specialty Stores:Curated regional craft labels with direct bean-to-bar transparency command pricing power through educational flagship experiences. Milan and Turin locations function as provenance venues where consumers pay premiums for documented supply chains.
- Online Retail:Direct-to-consumer subscription channels bypass wholesale margin compression while building recurring revenue stability for vertically integrated processors.
- Supermarkets:Mass-market volume concentration with limited shelf space for premium artisanal entrants.
- Retail Stores:Conventional convenience-oriented outlets facing channel shift toward experiential specialty formats.
Specialty stores dominate margin extraction; online retail climbs fastest as logistics infrastructure matures.
Packaging Type:
Format economics align with occasion-based consumption patterns and gifting protocol expectations.
- Bars:Standard 100g format dominates daily consumption with established tempering line efficiency.
- Boxes:Assortment packaging for seasonal gifting occasions with highest per-gram pricing realization.
- Bags:Bite-sized portion formats targeting impulse purchase and on-premise cafe distribution.
- Bulk:Foodservice-scale supply for bakeries and restaurants with minimal packaging cost pass-through.
Bars maintain volume leadership; boxes sustain the steepest premium trajectory.
End User:
Application requirements fragment procurement specifications across consumer and commercial segments.
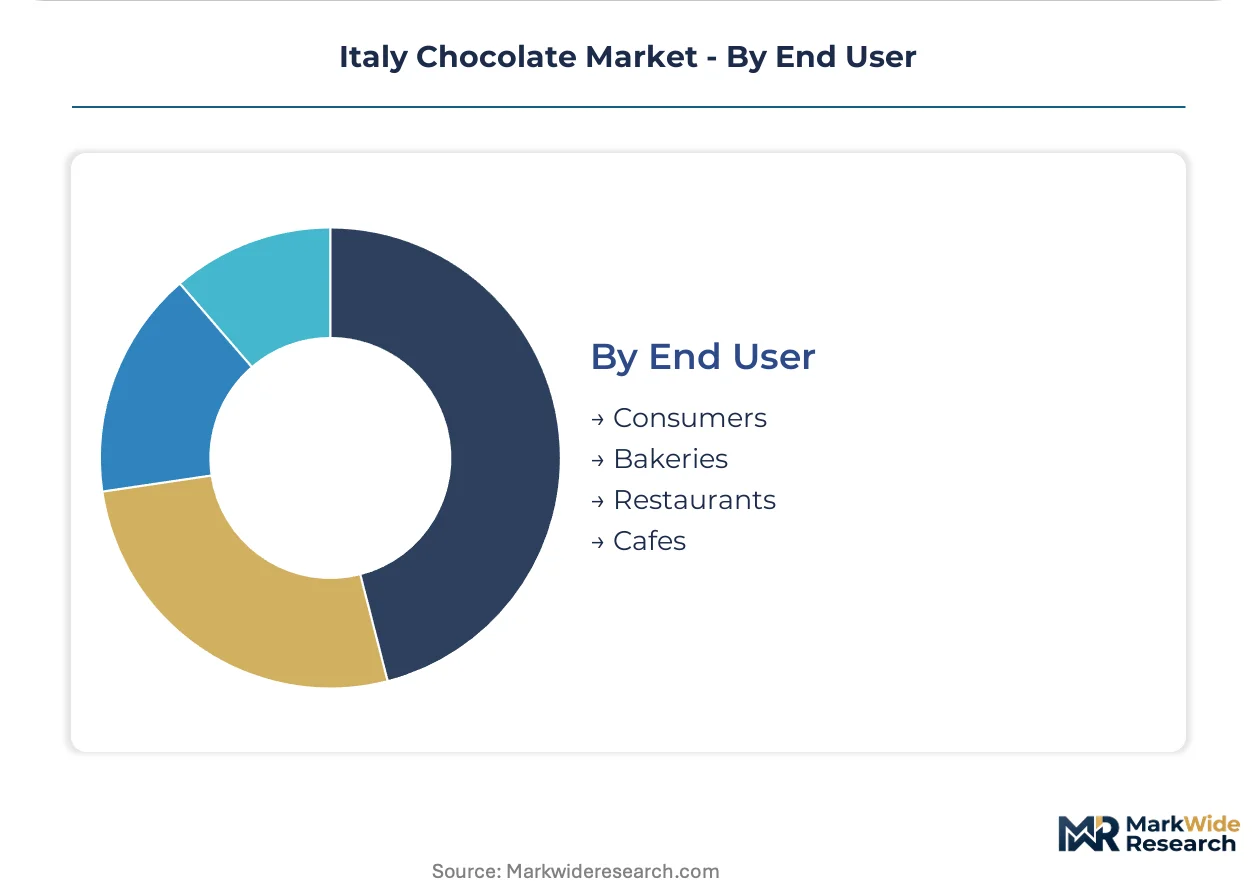
- Consumers:Household purchasers driving premium artisanal demand away from standardized gifting formats toward personalized provenance narratives.
- Bakeries:Commercial-scale cocoa butter and couverture requirements with consistent tempering behavior specifications.
- Restaurants:Plated dessert and petit four applications demanding precise melting point control.
- Cafes:Hot chocolate and mocha beverage formulations with soluble powder and liquid concentrate variants.
Consumers anchor volume demand; bakeries expand most quickly as artisanal pastry trends accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Genoa's Mediterranean container traffic underwrites Italy's cocoa import logistics, anchoring the country's role as Southern Europe's primary chocolate processing hub.
Piedmont
Turin-based gianduja heritage brands drive premium dark chocolate demand through protected geographical indication status. The F-Gas Regulation forces tempering equipment upgrades across Alessandria and Cuneo manufacturing corridors. Alba's hazelnut cooperative networks supply captive inputs to clustered processors along the Tanaro River valley.
Lombardy
Milan's specialty retail flagship density concentrates bean-to-bar provenance storytelling for affluent household consumers. EFSA food contact material standards mandate laboratory infrastructure investments among Como and Varese processors. The Brianza industrial zone hosts precision conching equipment suppliers serving adjacent chocolate manufacturers.
Veneto
Verona's wine tourism spillover generates experiential chocolate pairing demand in boutique hospitality channels. EU Deforestation Regulation geolocation verification requirements reshape Padua-based importer procurement systems. Vicenza's engineering firms manufacture continuous flow tempering lines for export to German and Swiss markets.
Emilia-Romagna
Bologna's foodservice distribution networks channel couverture supply to artisanal gelato and pastry sectors. The EU Green Deal sustainability framework mandates deforestation-free documentation for Modena and Parma processors sourcing West African beans. Rimini's hospitality trade shows anchor seasonal gifting format launches for boxed assortment producers.
Lazio
Rome's tourist retail corridors sustain duty-free chocolate volume for airport concession operators. EFSA contaminant threshold protocols for cadmium and lead require testing investments among Frascati and Tivoli microprocessors. Ciampino's logistics parks consolidate bulk cocoa butter warehousing for central Italian bakery supply.
Italy Chocolate Market Competitive Landscape
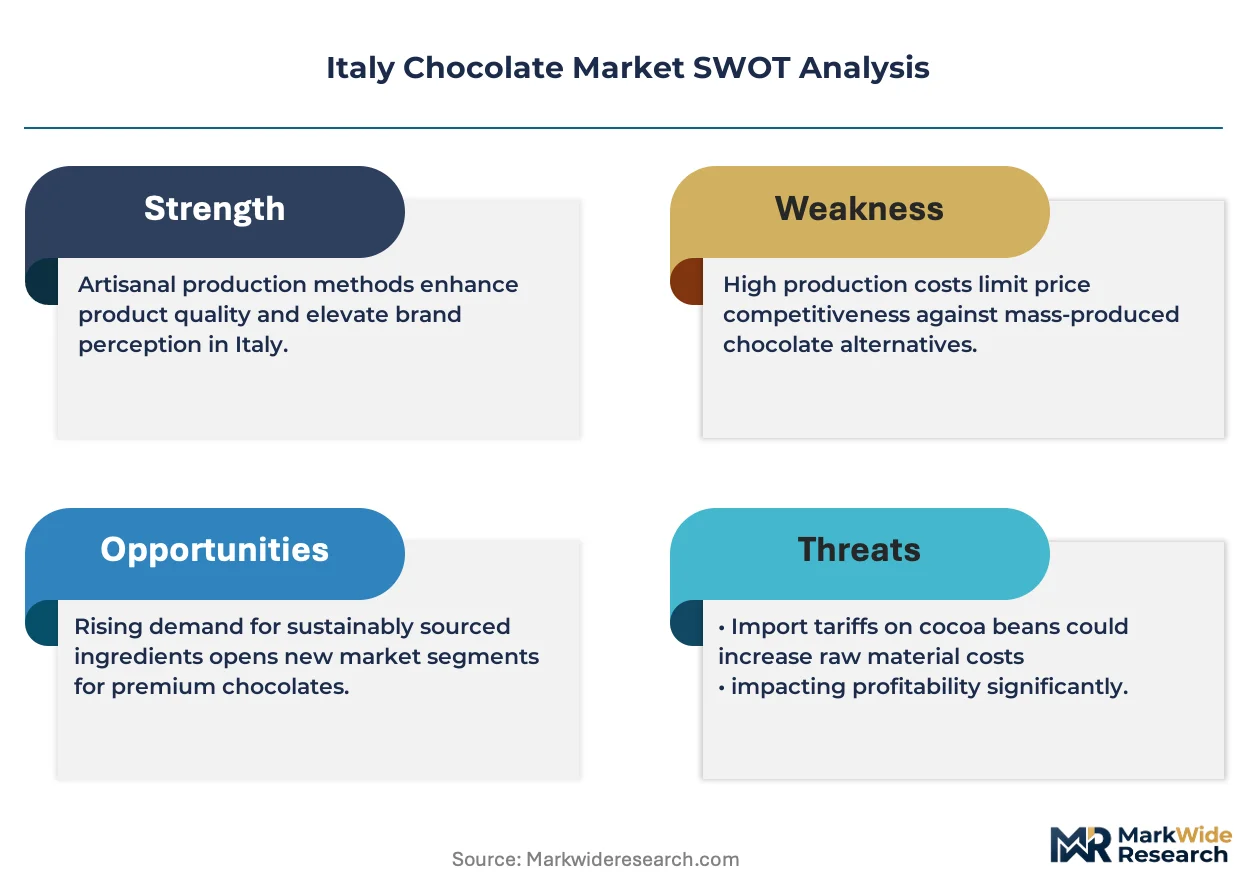
Concentration sits with heritage gianduja specialists and Swiss-imported premium anchors. The vendor base spans three tiers: vertically integrated Piedmontese houses with captive nut supply chains, disciplined Swiss manufacturers with controlled distribution, and multinational scale players with mass-market retail penetration. Strategic moves cluster around direct-origin sourcing partnerships and specialty retail footprint expansion.
Among heritage-anchored Piedmontese houses, Ferrero International SA and Venchi SpA exemplify the vertically integrated archetype with in-house supply chain control. Lindt & Sprüngli AG occupies the premium-imported tier with Swiss manufacturing discipline. These three anchors illustrate how provenance documentation and equipment standardization separate margin capture from commodity competition.
| Leading Market Players |
|---|
| Ferrero International SA |
| Lindt & Sprüngli AG |
| Venchi SpA |
| Nestlé SA |
| Mondelēz International Inc. |
| Bauli SpA |
| ICAM SpA |
| Mars Incorporated |
| A. Loacker Spa/AG |
| Others |
Pricing and Supply Chain Analysis
Ninety-day cocoa bean inventory cycles at Genoa port terminals concentrate purchasing power among processors with documented EU Deforestation Regulation compliance, compressing margins for spot-market buyers while rewarding early-certified operators with stable input costs. This lead-time structure ties pricing power directly to geolocation verification capabilities, separating premium-provenance processors from commodity traders.
Pricing Analysis
Volume-discount tiering separates single-origin craft labels from industrial gianduja houses and mass-market importers. Price differentiation rests on certification grade (EU organic, Fairtrade) and captive hazelnut supply from Alba cooperatives. Cost compression in the standard tier intensifies as West African supply disruptions transmit directly to cocoa butter costs. Mass-market supermarket buyers exhibit highest price sensitivity; specialty store consumers demonstrate lowest elasticity due to provenance storytelling premiums.
Supply Chain Analysis
Inventory concentration at Genoa and Rotterdam hubs feeds Italian tempering operations with 45-60 day processing buffers. Raw material dependencies center on Ivorian and Ghanaian cocoa mass, Piedmontese hazelnuts, and Sicilian almond variants. Single-source vulnerability sits with West African bean origins exposed to climate-driven harvest volatility. Distribution runs through Turin-Milan industrial clusters for domestic supply, with specialty retail flagships capturing margin-rich direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across provenance tiers creates white-space niches as household consumers abandon standardized gifting formats for bean-to-bar transparency. This demand shift rewards agile operators who can document supply chains faster than legacy processors retool procurement systems.
For Market Incumbents: Fortify gianduja heritage positioning through backward integration into Alba hazelnut cooperatives and precision conching automation that compresses quality variance. EFSA cadmium testing infrastructure investments defend against regulatory displacement of smaller competitors. Channel control through Milan-Turin flagship expansion captures specialty store margin migration away from supermarket concentration. For New Entrants and Emerging Players: Organic certification fast-tracks entry into Sicilian terroir development, the most penetrable premium segment against West African bean dependence. Target direct-to-consumer subscription channels with monthly tasting boxes that bypass wholesale margin compression. Ruby chocolate line extensions offer go-to-market differentiation through natural pink coloration without artificial additives. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EU Deforestation Regulation compliance costs will strand sub-scale processors without geolocation verification infrastructure. Acquisition targets cluster around vertically integrated craft labels with documented direct-origin relationships and precision tempering equipment. The signal to watch is enforcement timeline acceleration for geolocation documentation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| EU Deforestation Regulation Compliance | Geolocation verification infrastructure creates competitive moats against spot-market traders. |
| Precision Conching Automation | Real-time particle size monitoring displaces empirical judgment in Turin-Milan clusters. |
| Direct-to-Consumer Subscription Launch | Monthly tasting boxes bypass wholesale compression while building recurring revenue stability. |
| Sicilian Organic Cultivation Expansion | Domestic terroir development reduces West African bean dependence for provenance storytelling. |
| Ruby Chocolate Line Extension | Natural pink coloration captures novelty-seeking gifting segments unserved by conventional portfolios. |
Research Methodology
Cross-validation between primary interviews with chocolate processing executives and secondary customs trade data anchors the qualitative findings in observable import-export flows. Conversations with specialty store buyers, tempering equipment suppliers, and EFSA regulatory consultants combined with EU Green Deal framework documents, F-Gas Regulation implementation guidance, and Piedmontese agricultural cooperative disclosures. Bottom-up volume estimates from individual processor capacities triangulate against top-down cocoa butter import tonnage through Genoa port records.
Sensitivity analysis across cocoa price volatility bands and enforcement timeline scenarios tests forecast robustness over the projection horizon. Segmentation dimensions span product type (dark, milk, white, ruby), distribution channel (specialty, online, supermarket, retail), packaging format (bars, boxes, bags, bulk), and end-user application (household, bakery, restaurant, cafe). CAGRs derive from trend extrapolation adjusted for regulatory inflection points and equipment replacement cycle timing.
Decision-makers should treat outputs as directional under sustained EU Deforestation Regulation enforcement and stable West African supply assumptions; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
UK Chocolate Market
Confectionery
Chocolate Confectionery Market
Confectionery
United Arab Emirates Sugar Confectionery Market
Confectionery
Global Sugar Free Chewing Gums Market
Confectionery
CBD-Infused Confectionery Market
Confectionery
Salted Caramel Products Market
Confectionery
Sugar Free White Chocolate Market
Confectionery
Gum Base Candy Market
Confectionery
India Chocolate Market
Confectionery
Truffle Chocolate Market
Confectionery
Global Industrial Chocolate Market
Confectionery
United States and Europe Macarons Market
Confectionery
Caramel Market
Confectionery
Confectionery Fats Market
Confectionery
Europe Confectionery Market
Confectionery
Low-Fat Candy Market