
 Spain Food Sweetener Market | 2026-2036
Spain Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Food Sweetener Market Analytics
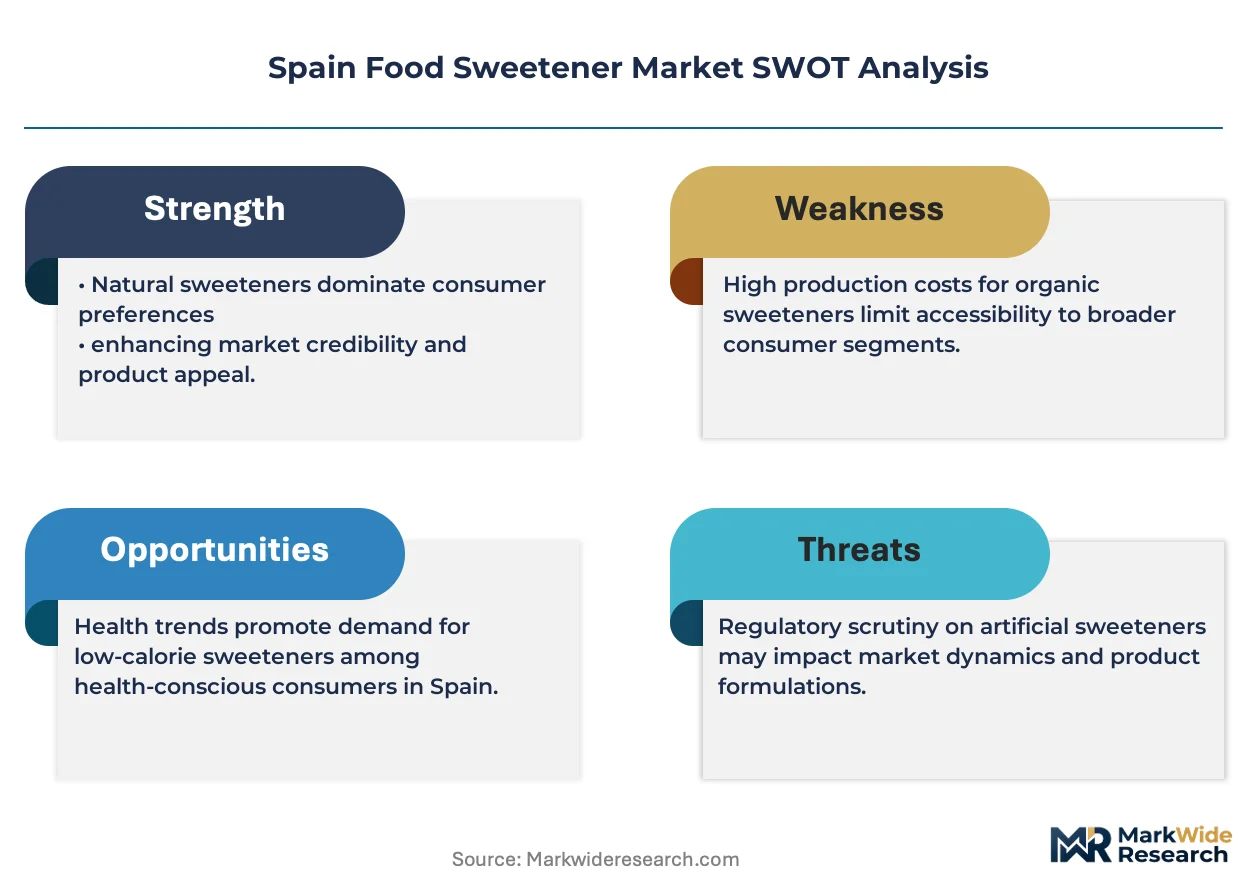
CE marking under EU food additive regulations is collapsing the supplier base as smaller importers struggle with compliance costs. Cargill Incorporated leverages its European ingredient network to sustain bulk supply contracts with Spanish beverage bottlers. Kerry Group PLC anchors its position through specialized sweetener systems for dairy applications. Tate & Lyle Plc competes on enzyme-based processing technology that reduces production variability.
Food sweeteners encompass caloric and non-caloric substances that impart sweetness to processed foods, typically measured by sucrose equivalence ratios ranging from 0.3 to 600 times sugar intensity depending on molecular structure. These compounds serve primarily to reduce caloric content while preserving palatability in mass-market packaged goods. Sugar retains dominant volume across the product type landscape despite steady share erosion from stevia in natural-positioned brands. High fructose corn syrup occupies a mature, cost-driven niche concentrated in carbonated soft drinks. The beverages end user segment generates the fastest structural expansion as manufacturers reformulate recipes ahead of tightened labeling requirements.
EFSA evaluates all novel sweetener approvals under EU Regulation 1333/2008, while Spain's AESAN enforces front-of-pack Nutri-Score compliance that penalizes high-sugar formulations. This dual regulatory architecture redirects R&D investment toward plant-derived alternatives with favorable scoring profiles. Stakeholders must monitor pending EFSA re-evaluations of aspartame and acesulfame K that could trigger abrupt formulation mandates.
Market Dynamics
Spain's front-of-pack Nutri-Score labeling mandate is compressing formulation timelines as beverage and dairy processors race to reformulate before enforcement deadlines tighten. This regulatory pressure is redrawing supplier relationships and R&D allocation across the Iberian Peninsula.
Growth Catalysts
- Nutri-Score Compliance Pressure:AESAN's enforcement of front-of-pack labeling under EU framework penalizes high-sugar formulations, forcing manufacturers toward alternative sweetener portfolios.
- Stevia Extraction Advances:Enzymatic bioconversion processes are lowering production costs for Reb M and Reb D glycosides, accelerating adoption in natural-positioned brands.
- Catalonia Processing Cluster:Dense concentration of food and beverage manufacturers around Barcelona creates localized demand pull and short logistics loops for ingredient suppliers.
Market Restraints
- CE Marking Compliance Costs:EU food additive regulations under 1333/2008 are collapsing the supplier base as smaller importers cannot sustain certification expenses.
- Sugar Price Volatility:Beet sugar harvest fluctuations in Castile-León create input cost instability for caloric sweetener formulations.
- Technical Blending Limitations:Stevia's lingering aftertaste requires complex bulking agent combinations that extend development cycles.
Strategic Opportunities
- Andalusia Citrus Applications:Underdeveloped juice processing infrastructure in southern Spain offers white space for specialized sweetener systems targeting reduced-sugar nectars.
- Clean Label Convergence:Pairing fermentation-derived sweeteners with upcycled fruit fibers addresses dual consumer demands for naturalness and sustainability.
- Direct-to-Manufacturer Platforms:Digital procurement channels are bypassing traditional distributor layers, enabling smaller ingredient innovators to access mid-tier processors.
Industry Challenges
- Reformulation Talent Scarcity:Food technologists skilled in sensory masking for high-intensity sweeteners command premium wages that strain mid-cap manufacturer budgets.
- EFSA Re-evaluation Uncertainty:Pending safety reviews of aspartame and acesulfame K create formulation planning paralysis as manufacturers delay long-term recipe commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Food Sweetener Market |
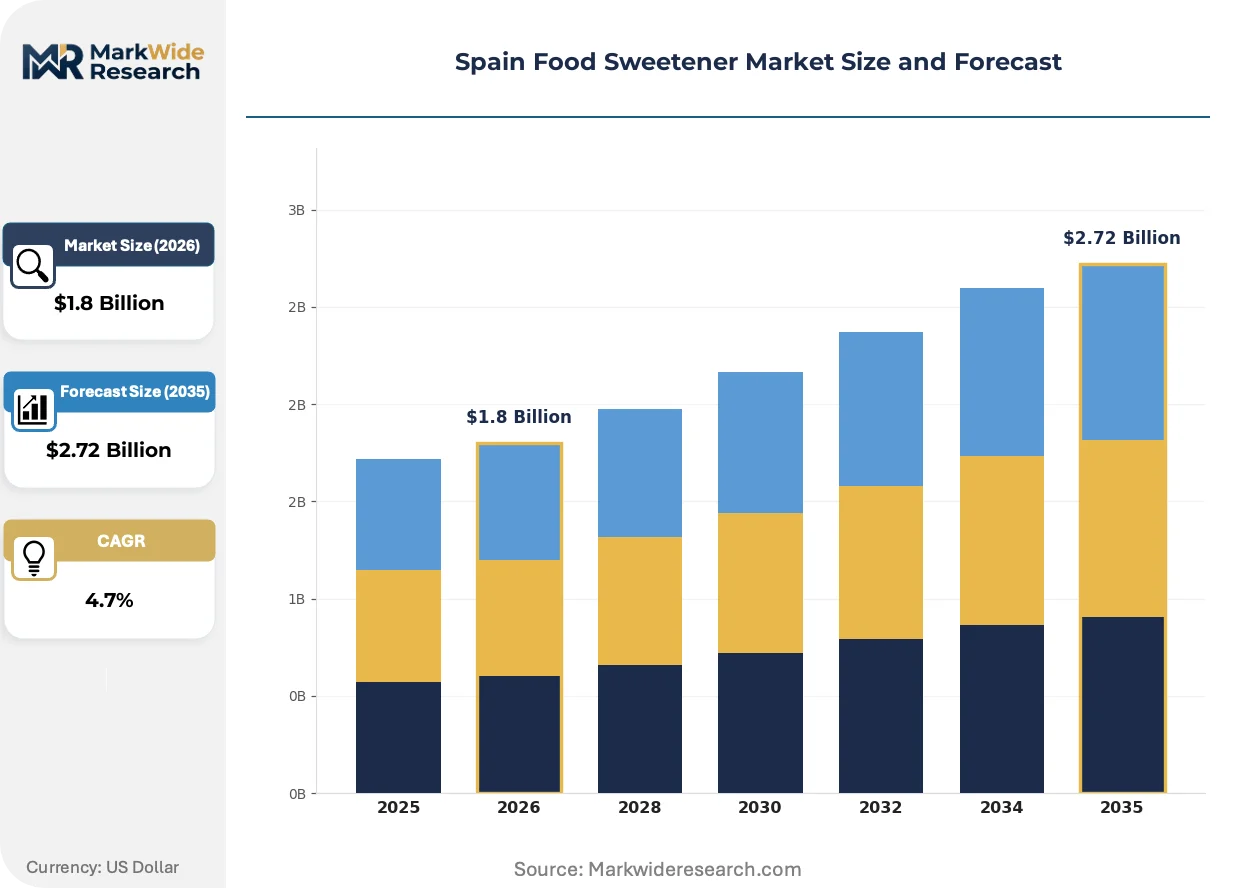
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sugar, High Fructose Corn Syrup, Stevia, Aspartame End User: Beverages, Bakery, Snacks, Dairy Application: Confectionery, Frozen Foods, Sauces, Dressings Packaging Type: Bulk, Sachets, Bottles, Pouches |
| Companies Covered | Tate & Lyle Plc, Cargill Incorporated, Archer Daniels Midland Company, DuPont, Ingredion Incorporated, PureCircle Limited, Tereos S A, Kerry Group PLC, Ajinomoto Co., Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Food Sweetener Market Evolving Landscape
Biotechnology and regulatory scoring systems are converging to reshape ingredient selection criteria, with fermentation-derived and plant-extracted alternatives gaining technical parity with legacy options.
Fermentation-based production of rare steviol glycosides is decomposing cost barriers that previously confined premium sweetness profiles to niche applications. Spanish beverage bottlers in the carbonated and functional drink segments are adopting these inputs at accelerated cadences. This biotechnology shift is compressing the price premium between natural-identical and extraction-derived sweeteners.
AESAN's alignment with EFSA guidance on novel food approvals is tightening the window for bringing new sweetener molecules to Spanish formulations. Industrial consequence includes extended safety study timelines and elevated dossier preparation costs for entrants. Dairy applications face the steepest compliance burden due to children's consumption patterns triggering enhanced scrutiny.
Spanish retailers are consolidating sweetener procurement through centralized technical specifications that favor suppliers with integrated formulation support. Mid-sized processors are losing direct supplier relationships as buying power concentrates in Madrid and Barcelona headquarters. This pattern is most visible in the private-label beverage segment where Carrefour and Mercadona dominate shelf space allocation.
Spain Food Sweetener Market Segmentation
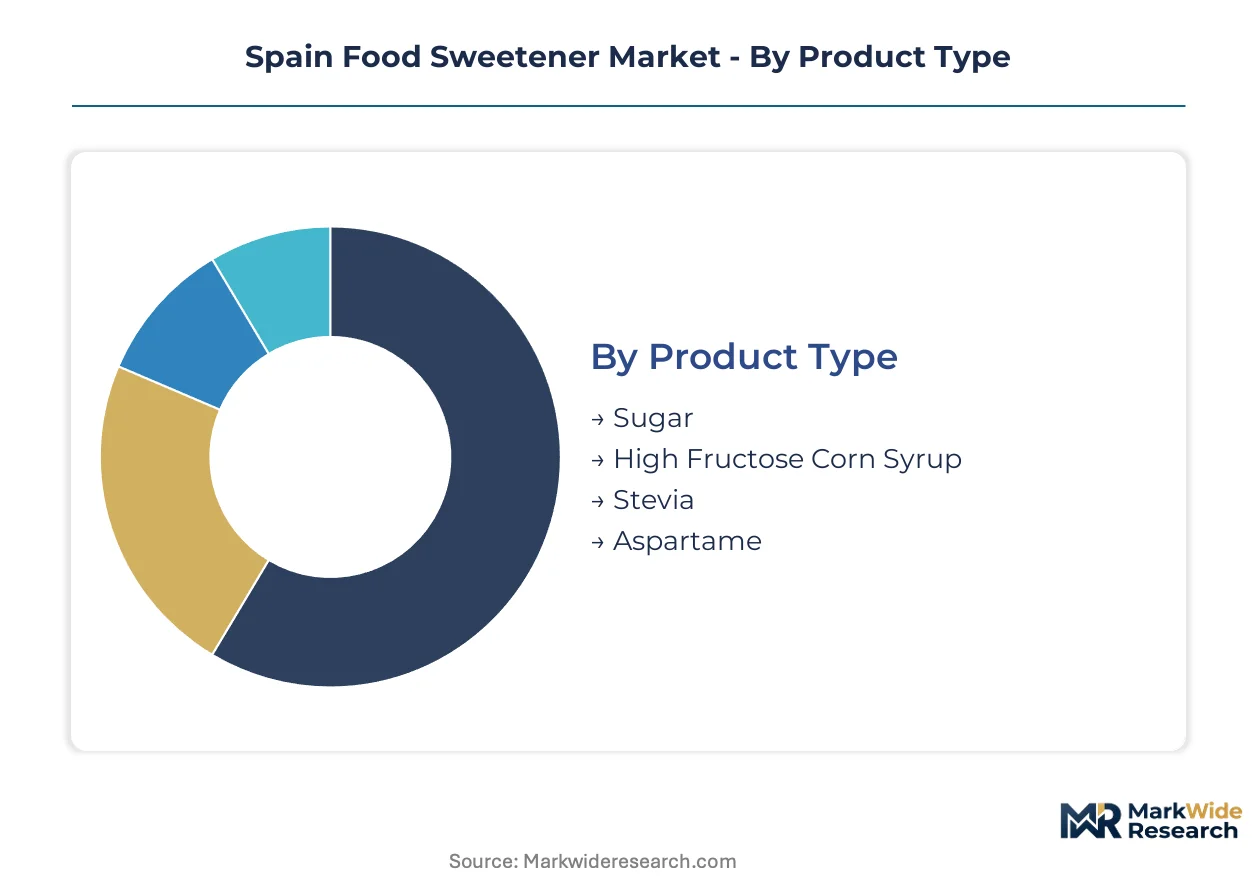
Sweetener procurement channels in Spain diverge sharply by segment, with industrial bulk contracts dominating commodity categories while specialty formats command premium distribution through technical service networks. Understanding these pathway distinctions enables suppliers to align formulation support with customer scale and application complexity.
Product Type:
Channel architecture varies by caloric positioning and regulatory status, with natural-identical sweeteners flowing through specialized ingredient distributors while commodity sugars leverage established agricultural supply chains.
- Sugar:Beet-derived sucrose from Castile-León refineries supplies standard-calorie formulations across mass-market beverage and bakery channels. Industrial processors in Catalonia's Barcelona corridor anchor volume demand through annual procurement contracts indexed to EU sugar regime prices.
- Stevia:Enzymatically produced Reb M and Reb D glycosides now achieve cost parity with synthetic alternatives in natural-positioned brands. Spanish beverage reformulation timelines compress as Nutri-Score labeling mandates accelerate adoption in carbonated and functional drink segments.
- High Fructose Corn Syrup:Cost-driven niche concentrated in legacy soft drink formulations with limited growth trajectory.
- Aspartame:Pending EFSA re-evaluation uncertainty constrains long-term procurement commitments despite established technical performance in dairy applications.
By volume, Sugar leads. By growth pace, Stevia is expanding most quickly.
End User:
Customer scale and technical sophistication determine service intensity, with multinational beverage bottlers demanding integrated formulation labs while regional bakeries prioritize cost-stable supply.
- Beverages:Carbonated soft drink and functional beverage manufacturers drive structural expansion as AESAN's Nutri-Score enforcement triggers aggressive reformulation campaigns. Leading bottlers in Madrid and Barcelona maintain captive R&D partnerships with sweetener suppliers.
- Dairy:Yogurt and flavored milk processors face enhanced regulatory scrutiny due to children's consumption patterns, elevating documentation requirements for novel sweetener approvals. Catalonia's dairy cluster concentrates technical talent for sensory masking applications.
- Bakery:Traditional caloric sweeteners dominate sponge and pastry applications where bulk functional properties resist substitution.
- Snacks:Energy bars and coated products represent emerging application territory for reduced-sugar positioning.
By installed capacity, Beverages dominates. By regulatory pressure intensity, Dairy faces the steepest compliance burden.
Application:
Heat stability and water activity requirements segment technical specifications, with thermally processed applications demanding specialized bulking agent combinations.
- Confectionery:Hard candies and gummies require precise control over crystallization kinetics and glass transition temperatures. Spanish producers in Valencia's traditional confectionery belt source hybrid sweetener systems combining bulk sugars with high-intensity modifiers.
- Frozen Foods:Ice cream and frozen dessert formulations exploit depressed freezing point properties of specific polyol blends. Andalusia's underdeveloped processing infrastructure limits regional supplier penetration despite growing consumer demand.
- Sauces:Viscosity and browning reactions constrain sweetener selection in tomato and condiment applications.
- Dressings:Emulsion stability requirements favor specific molecular weight distributions in reduced-calorie formulations.
By formulation complexity, Confectionery demands the most technical support. By white space availability, Frozen Foods offers the clearest expansion opportunity.
Packaging Type:
Logistics economics and contamination risk profile the procurement interface, with foodservice and industrial channels diverging on handling protocols and minimum order quantities.
- Bulk:Tanker and silo deliveries serve high-volume beverage bottlers and dairy processors with integrated manufacturing sites. Barcelona's port infrastructure enables direct import reception for multinational ingredient suppliers.
- Sachets:Single-serve hospitality and foodservice segments demand portion-controlled formats with extended shelf stability. Madrid's centralized distribution hubs consolidate procurement for national restaurant chains.
- Bottles:Liquid syrup concentrates target mid-tier manufacturers lacking bulk handling infrastructure.
- Pouches:Flexible formats address export-oriented processors and specialty ingredient blending operations.
By tonnage moved, Bulk commands the logistics network. By margin per kilogram, Sachets capture premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barcelona's port infrastructure anchors Iberian sweetener logistics, handling bulk ingredient imports for Catalonia's dense food processing corridor while Valencia and Bilbao terminals distribute refined products across southern and northern manufacturing belts.
Catalonia
Beverage reformulation campaigns in Barcelona's carbonated drink cluster drive concentrated demand for stevia glycosides and enzyme-processed alternatives. AESAN's Nutri-Score enforcement tightens formulation windows for processors headquartered in the region. The metropolitan manufacturing belt around Terrassa and Sabadell houses captive R&D partnerships between bottlers and ingredient suppliers.
Madrid
Centralized retail procurement at national headquarters concentrates buying power for private-label sweetener specifications. The country's national food safety regulator maintains dossier review facilities in the capital, extending approval timelines for novel dairy applications. Logistics platforms in the Madrid-Barcelona corridor enable just-in-time bulk deliveries to high-volume processors.
Andalusia
Underdeveloped juice processing infrastructure in Seville and Málaga provinces creates white space for specialized reduced-sugar nectar formulations. EU agricultural support programs subsidize citrus cultivation expansion in the Guadalquivir valley. Emerging food manufacturing zones near Córdoba attract ingredient distributors seeking proximity to southern consumer markets.
Valencia
Traditional confectionery producers in the autonomous community source hybrid sweetener systems combining bulk sugars with high-intensity modifiers for hard candy applications. The regional port authority handles molasses and raw sugar imports for refineries serving eastern bakery channels. Alicante's frozen dessert manufacturers exploit depressed freezing point properties of polyol blends for ice cream formulations.
Basque Country
Precision fermentation startups in Bilbao's biotech corridor pilot microbial production of rare steviol glycosides. Regional industrial policy prioritizes clean-label ingredient innovation through public-private research consortia. Vitoria-Gasteiz hosts technical service laboratories supporting dairy processors in sensory masking applications for high-intensity sweeteners.
Spain Food Sweetener Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology tiers, creating a bifurcated structure where scale-driven commodity suppliers coexist with application-focused service providers. The supplier base compresses under CE marking compliance burdens as smaller importers exit. Three archetypes dominate: multinational ingredient networks with integrated European logistics, specialized sweetener system formulators for dairy and beverage applications, and biotechnology-focused innovators in enzymatic glycoside production. Competitive moves concentrate on strategic partnerships with regional processors and portfolio diversification toward fermentation-derived alternatives.
Within the multinational network tier, Cargill Incorporated and Tate & Lyle Plc anchor positions through bulk supply contracts and processing technology licensing. Kerry Group PLC exemplifies the specialized formulator archetype, occupying a service-intensive position in dairy applications where sensory masking requirements elevate technical support demands. These three entities represent distinct competitive vectors—logistics scale, enzymatic processing capability, and integrated formulation support—that define rivalry dynamics across Catalonia's processing cluster and Madrid's centralized procurement channels.
| Leading Market Players |
|---|
| Tate & Lyle Plc |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| DuPont |
| Ingredion Incorporated |
| PureCircle Limited |
| Tereos S A |
| Kerry Group PLC |
| Ajinomoto Co., Inc. |
| Others |
Value Network & Pricing Analysis
Sixty-day inventory cycles at Barcelona's port terminals concentrate procurement leverage among high-volume beverage bottlers, compressing margins for mid-tier processors while rewarding scale-driven contract structures. This lead-time compression reinforces pricing power asymmetries between Catalonia's integrated manufacturers and southern Spain's fragmented dairy operations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and volume commitment. Premium tiers command positioning through EFSA novel food approvals and integrated formulation support, while economy segments compete on beet sugar spot pricing indexed to EU regime benchmarks. Cost compression in standard tiers is intensifying because Nutri-Score reformulation deadlines compress procurement timelines. Mid-cap dairy processors exhibit highest price sensitivity due to thin reformulation budgets, whereas multinational beverage bottlers prioritize technical service over unit cost.
Supply Chain Analysis
Inventory exposure concentrates in Castile-León beet refineries and enzymatic processing facilities in the Basque Country, creating geographic vulnerability to harvest volatility and biotechnology input scarcity. Raw material flows draw from Spanish sugar beet cultivation, imported stevia leaf from Paraguay and China, and fermentation feedstocks for rare glycoside production. Single-source vulnerability runs through specialized enzyme suppliers for Reb M bioconversion. Distribution feeds from Barcelona port infrastructure through captive logistics networks serving Catalonia's processing corridor, with secondary distribution via Madrid hubs penetrating central and southern markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Madrid-based retail procurement consolidation, with Carrefour and Mercadona's centralized technical specifications displacing direct supplier relationships for mid-tier processors. This consolidation fragments negotiating leverage among regional manufacturers.
For Market Incumbents: Compound formulation service capabilities into captive R&D partnerships with Barcelona beverage bottlers facing compressed Nutri-Score deadlines. Backward integration into enzymatic bioconversion capacity in the Basque Country secures supply continuity against specialty enzyme supplier concentration. Certification investment in EFSA dossier preparation for fermentation-derived glycosides creates switching costs that bind dairy processors facing children's consumption scrutiny.
For New Entrants and Emerging Players: Anchor in Andalusia's underdeveloped juice processing infrastructure where reduced-sugar nectar formulations lack established supplier relationships. Direct-to-manufacturer digital procurement platforms bypass Madrid distributor layers that exclude smaller innovators. White space concentrates in citrus applications where EU agricultural subsidies support cultivation expansion and local sweetener technical service remains sparse.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational ingredient parents divesting non-core commodity sweetener portfolios to focus on biotechnology platforms. Long-term viability hinges on fermentation-derived glycoside cost curves achieving parity with extraction methods. Acquisition candidates with captive EFSA approval pathways for novel dairy applications command defensive premiums. The signal to monitor is EFSA's aspartame re-evaluation timeline, which would trigger abrupt formulation migrations and supplier displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzymatic Processing | Cargill and Tate & Lyle secure Reb M supply continuity against single-source biotechnology bottlenecks. |
| EFSA Novel Food Dossier Investment | Kerry Group accelerates dairy application approvals ahead of pending aspartame safety reviews. |
| Direct-to-Manufacturer Platform Launch | Specialist innovators bypass Madrid distributor consolidation to access mid-tier Andalusian processors. |
| Captive R&D Partnership Expansion | Barcelona beverage bottlers lock in formulation support through exclusive technical service agreements. |
| Fermentation Capacity Buildout | Basque Country biotech startups pilot microbial production reducing rare glycoside cost premiums. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of AESAN enforcement directives, EFSA novel food approval databases, EU sugar regime price benchmarks, and customs trade flows for stevia leaf imports. Primary interviews engaged beverage reformulation directors at Catalonia bottlers, dairy sensory technologists, procurement leads at Madrid retail headquarters, and enzyme process engineers at Basque fermentation facilities. Secondary validation drew from trade association filings, port authority throughput statistics, and agricultural ministry harvest reports. Bottom-up demand modeling triangulates against top-down supply capacity assessments across the analysis window.
Segmentation dimensions modeled include product type hierarchy, end-user application intensity, regional processing cluster concentration, and packaging format logistics economics. CAGRs derive from installed capacity trajectories, reformulation timeline elasticity to Nutri-Score enforcement, and substitution elasticity between caloric and non-caloric alternatives. Forecast inputs incorporate beet sugar harvest variance in Castile-León, enzymatic bioconversion yield improvements, and retail private-label shelf space allocation shifts.
Decision-makers should treat outputs as directional under assumptions of sustained AESAN labeling enforcement and stable EFSA approval timelines; material deviation in regulatory stringency or safety review outcomes would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Gluten-Free Sugar Syrup Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
Glucose Syrup Market
Sweeteners
France Food Sweetener Market
Sweeteners
Europe Food Sweetener Market
Sweeteners
South America Low-Calorie Sweeteners Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
Global Stevia Sugar Blends Market
Sweeteners
Tagatose Market
Sweeteners
Refined Cane Sugar Market
Sweeteners
Middle East and Africa Plant-Derived and Synthetic Sugar Market
Sweeteners
Global Plant-Derived and Synthetic Sugar Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
Invert Sugar Market
Sweeteners
Cassava Syrup Market
Sweeteners
Low-Fat Sugar Market