
 UK Confectionery Market | 2026-2036
UK Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
UK Confectionery Market Insights
UK sugar reduction targets is broadening the cost-of-entry calculus for new confectionery entrants, forcing reformulation investments that favor scaled operators. Mondelez International Inc leverages its Cadbury manufacturing footprint to sustain volume leadership in chocolate. Mars Incorporated anchors its position through diversified snacking portfolios spanning confectionery and beyond. Ferrero International SA differentiates via premium hazelnut-chocolate specialization and controlled retail distribution.
UK confectionery comprises sugar-based or cocoa-derived food products formulated for sensory indulgence, typically containing specified thresholds of sucrose, glucose syrups, or cocoa mass processed through conching and tempering for texture stability. The category serves commercial purposes ranging from impulse retail purchases to seasonal gifting and food-service dessert integration. Chocolate commands the dominant value share within product type segmentation, while gummies represent the fastest-growing format driven by texture innovation and permissible indulgence positioning. Online shoppers within customer type segmentation are expanding at the fastest clip, though supermarkets still control the bulk of volume throughput across distribution channel segmentation.
The Food Standards Agency enforces compositional standards and labeling rules that directly shape permissible health claims and front-of-pack presentation. FSSAI-aligned import protocols and UK-specific plastic packaging taxes are forcing material transitions that alter cost structures for domestic producers. Trading standards bodies at the local authority level police weights, measures, and promotional compliance across retail channels. Stakeholders must monitor whether extended producer responsibility frameworks will mandate collection infrastructure investments that reshape competitive economics.
Market Dynamics
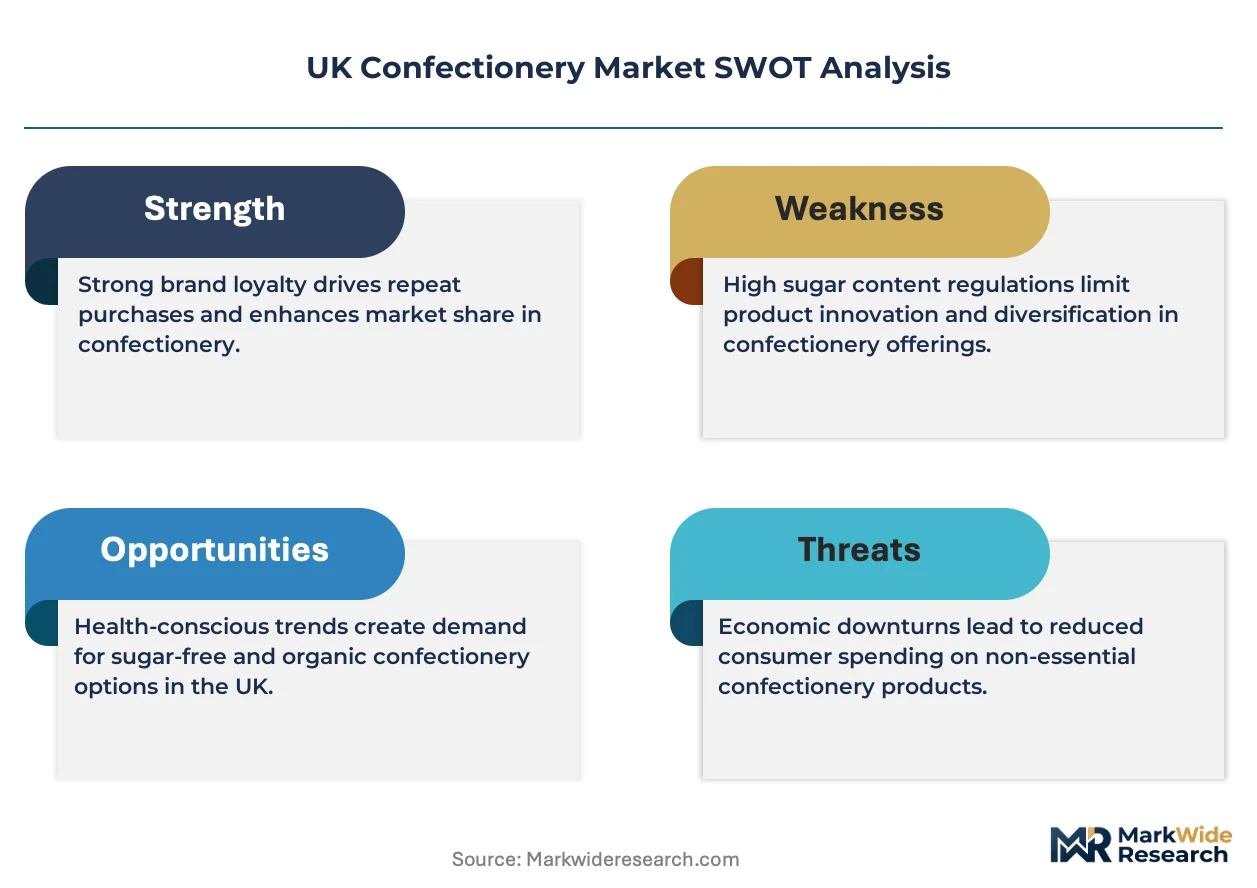
The UK government's sugar reduction targets are compressing formulation freedom across manufacturers, forcing capital-intensive reformulation programs that favor scaled operators with established R&D infrastructure and regulatory compliance capabilities.
Growth Catalysts
- Online subscription channels:Direct-to-consumer models bypass supermarket slotting fees and capture recurring revenue streams through curated premium assortments.
- Health-conscious formulations:Reduced-sugar and high-cocoa-mass recipes attract permissive indulgence positioning among metropolitan retail consumers.
- Plastic packaging taxes:Material transitions toward recyclable films and paper-based wraps create first-mover advantages for compliant producers.
Market Restraints
- Cocoa price volatility:Concentrated West African supply exposes margins to weather-driven commodity swings and currency fluctuations.
- Supermarket buyer concentration:Tesco, Sainsbury's, and Asda control bulk volume throughput, squeezing supplier negotiating leverage.
- Extended producer responsibility frameworks:Pending collection infrastructure mandates threaten capital allocation toward reverse logistics systems.
Strategic Opportunities
- England's metropolitan corridors:London, Manchester, and Birmingham concentrate affluent demographics receptive to premium hazelnut-chocolate and texture-innovation formats.
- Permissible indulgence positioning:Gummies with functional additives capture snacking occasions from traditional chocolate.
- Food Standards Agency labeling evolution:Front-of-pack presentation rules create differentiation space for clean-label claims.
Industry Challenges
- Conching and tempering expertise:Specialized process engineering talent scarcity constrains quality consistency at scale.
- Reformulation capex cycles:Sugar-reduction R&D demands multi-year investment horizons with uncertain consumer acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Confectionery Market |
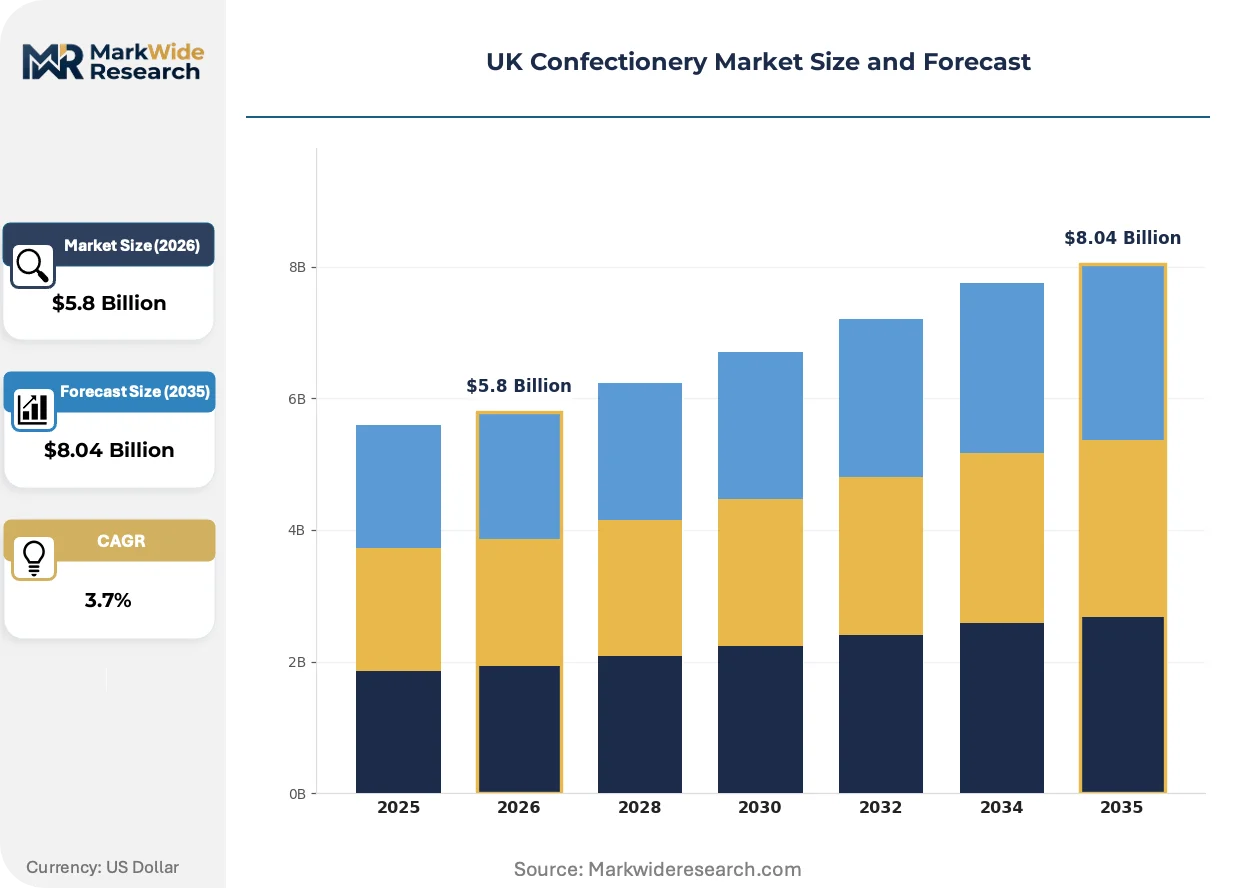
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.04 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Gummies, Hard Candy, Chewing Gum Customer Type: Retail Consumers, Food Service, Online Shoppers, Bulk Buyers Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops Price Tier: Premium, Mid-Range, Economy, Value Packs |
| Companies Covered | Mondelez International Inc, Mars Incorporated, Ferrero International SA, Nestlé SA, Chocoladefabriken Lindt & Sprüngli AG, HARIBO Holding GmbH & Co. KG, Swizzels Matlow Ltd, The Hershey Company, August Storck KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Confectionery Market Trends and Innovations
Texture innovation and permissible indulgence positioning are displacing traditional sweetness-centric formulation, while regulatory pressure on packaging materials accelerates material science investment across the supply base.
Precision fermentation-derived cocoa butter alternatives are integrating into premium chocolate lines to decouple supply from volatile agricultural commodity markets. Mid-tier manufacturers adopt these ingredients fastest to defend margin positions. The technology is integrating backward into formulation pipelines, compressing reliance on conventional cocoa processing infrastructure.
The Food Standards Agency's evolving front-of-pack labeling rules are tightening permissible health claim language and mandating clearer nutritional disclosure. Manufacturers face reformulation deadlines or promotional restriction. Chocolate segments with heritage brand equity are most affected, responding through reduced-portion formats and cocoa-mass concentration.
Subscription box curation is capturing gifting occasions previously served by seasonal retail. Direct-to-consumer platforms displace supermarket seasonal aisles for premium assortments. This shift concentrates most visibly in London and Southeast England, where urban density supports efficient last-mile fulfillment economics.
UK Confectionery Market Segmentation
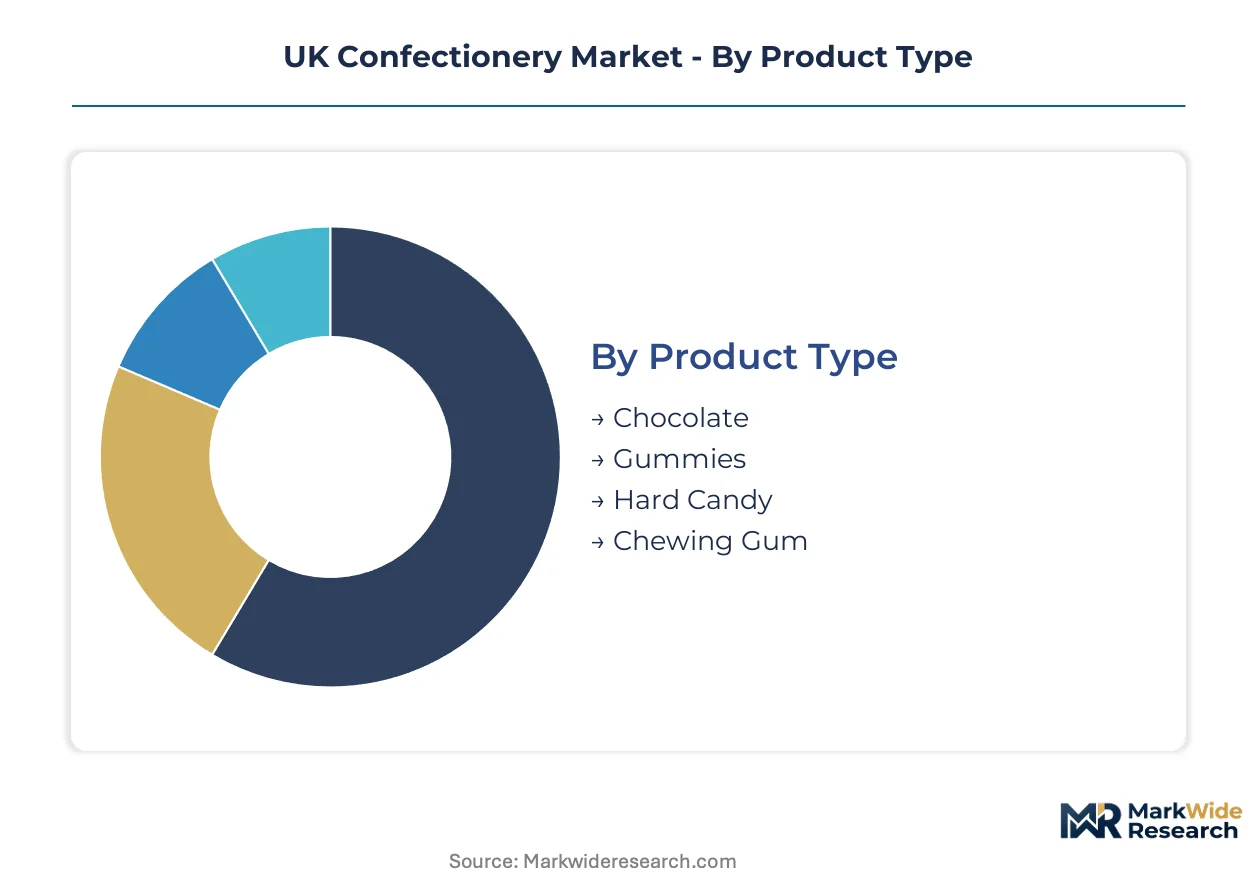
UK confectionery purchasing splits sharply across consumption occasion, channel economics, and permissible indulgence positioning. Manufacturers must align formulation investment and packaging format to the specific decision logic governing each segment interface.
Product Type:
Texture and cocoa concentration drive shelf placement and margin capture across manufacturing investment decisions.
- Chocolate:Cocoa mass processed through conching and tempering delivers texture stability and melt profiles that define quality perception. England's metropolitan retail corridors concentrate demand for high-cocoa-mass dark variants responding to sugar reduction pressures.
- Gummies:Gelatin or pectin-based matrices enable functional additive integration and texture innovation that captures snacking occasions from traditional formats. These formats are expanding most quickly within permissible indulgence positioning.
- Hard Candy:High-boiled sucrose or isomalt formulations serve long-duration consumption occasions and seasonal gifting with extended shelf stability.
- Chewing Gum:Polyol-based delivery systems for flavor and functional claims occupy impulse checkout placements with distinct regulatory status under Food Standards Agency compositional rules.
Chocolate leads on scale; gummies lead on momentum.
Customer Type:
Procurement authority and volume predictability determine pricing structure and relationship investment intensity.
- Retail Consumers:Individual purchasers responding to front-of-pack labeling and promotional mechanics drive volume throughput in supermarkets and convenience formats.
- Food Service:Dessert integration and portion-controlled formats for hospitality operators demand stable supply contracts and technical specification compliance.
- Online Shoppers:Direct-to-consumer subscription models bypass slotting fees and capture recurring revenue through curated premium assortments concentrated in London and Southeast England.
- Bulk Buyers:Institutional procurement for corporate gifting and event catering trades margin for volume commitment and customized packaging runs.
Retail consumers anchor volume throughput; online shoppers show steepest expansion trajectory.
Distribution Channel:
Physical density and fulfillment economics shape competitive access and working capital requirements.
- Supermarkets:Tesco, Sainsbury's, and Asda control bulk volume throughput and wield concentrated buyer leverage over supplier negotiations.
- Convenience Stores:Impulse-oriented smaller format placements capture immediate consumption occasions with higher per-unit margins.
- Online Retail:Last-mile fulfillment platforms concentrate in urban density corridors where subscription economics outperform traditional retail.
- Specialty Shops:Premium and heritage brand positioning in controlled retail environments supports hazelnut-chocolate specialization and gifting assortments.
Supermarkets dominate absolute volume; online retail demonstrates fastest share gain.
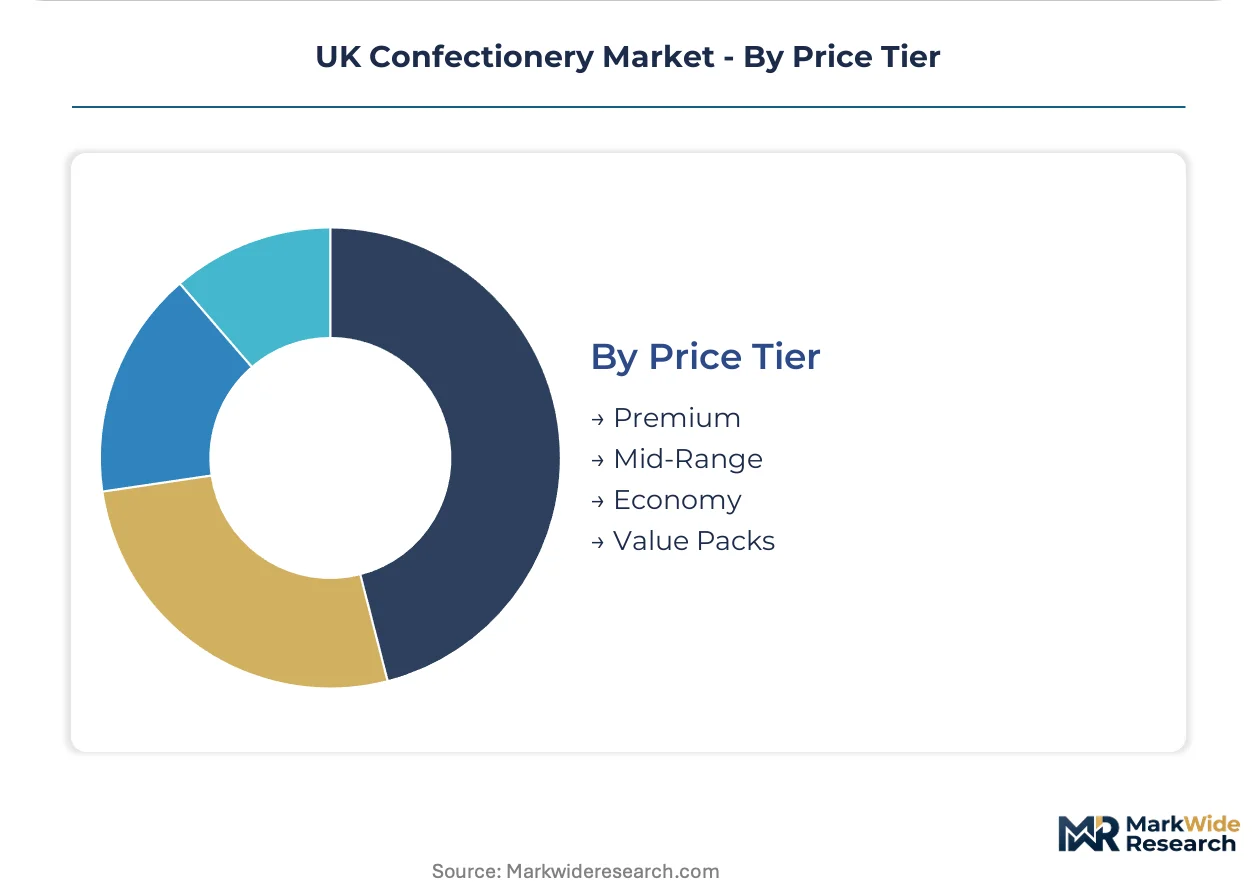
Price Tier:
Ingredient specification and packaging material investment separate competitive positioning layers.
- Premium:High-cocoa-mass recipes and precision fermentation-derived alternatives command metropolitan consumer willingness-to-pay for health-conscious formulations.
- Mid-Range:Balanced quality-positioning serves mainstream retail consumers through standard supermarket placements and promotional mechanics.
- Economy:Price-sensitive volume segments accept reformulated recipes and reduced portion formats under sugar reduction compliance pressures.
- Value Packs:Multi-unit bundling for household stockpiling and seasonal gifting concentrates in warehouse club and online subscription channels.
Mid-range captures widest demographic reach; premium shows strongest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Confectionery manufacturing talent clusters around England's metropolitan centers, with specialized process engineers concentrated in Birmingham, Manchester, and London's satellite production zones. This workforce concentration anchors formulation innovation and regulatory compliance capabilities across the UK market.
London and Southeast England
Affluent metropolitan consumers drive demand for premium hazelnut-chocolate assortments and subscription-box gifting formats. The Food Standards Agency's front-of-pack labeling rules mandate clearer nutritional disclosure across all retail placements. London's urban density supports efficient last-mile fulfillment economics for direct-to-consumer premium brands.
Midlands
Birmingham and Nottingham anchor industrial-scale chocolate manufacturing with established conching and tempering infrastructure. UK plastic packaging taxes force material transitions toward recyclable films that alter legacy cost structures. The region's engineering talent pool sustains reformulation programs responding to government sugar reduction targets.
North England
Manchester and Leeds concentrate mid-tier manufacturing serving supermarket private-label programs and promotional mechanics. Trading standards bodies at local authority levels police weights, measures, and retail compliance. Yorkshire-based facilities specialize in gummy texture innovation capturing permissible indulgence positioning.
Scotland
Edinburgh and Glasgow retail corridors show elevated demand for reduced-sugar and high-cocoa-mass dark variants. Extended producer responsibility frameworks threaten capital allocation toward collection infrastructure investments. Scottish manufacturing clusters focus on seasonal gifting formats and heritage brand positioning.
Wales
South Wales manufacturing zones supply economy-tier volume segments with reformulated recipes under sugar reduction compliance pressures. The Welsh Government's circular economy strategies intersect with UK-wide packaging material mandates. Cardiff retail channels concentrate impulse-oriented convenience store placements.
UK Confectionery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The UK confectionery sector exhibits moderate consolidation with three to five scaled operators controlling bulk volume throughput alongside numerous regional specialists. Strategic archetypes include diversified snacking portfolios, premium hazelnut-chocolate specialization, and texture-innovation gummy specialists. Dominant competitive moves encompass portfolio diversification into permissible indulgence formats and backward integration into controlled retail distribution.
Within the diversified conglomerate tier, Mondelez International Inc and Mars Incorporated exemplify scale-driven positions leveraging established manufacturing footprints and regulatory compliance infrastructure. Ferrero International SA occupies a focused specialist position anchored in premium hazelnut-chocolate segmentation and controlled retail distribution strategies. These three companies represent the primary competitive anchors shaping category dynamics across England's metropolitan corridors and online subscription channels.
| Leading Market Players |
|---|
| Mondelez International Inc |
| Mars Incorporated |
| Ferrero International SA |
| Nestlé SA |
| Chocoladefabriken Lindt & Sprüngli AG |
| HARIBO Holding GmbH & Co. KG |
| Swizzels Matlow Ltd |
| The Hershey Company |
| August Storck KG |
| Others |
Pricing and Supply Chain Analysis
ICCO daily cocoa price benchmarks cascade through UK confectionery supply chains into three distinct pricing strata. West African harvest volatility compresses margins at the economy tier while precision fermentation alternatives command premium positioning. Supermarket buyer concentration at Tesco, Sainsbury's, and Asda transmits slotting fee pressure backward into manufacturer cost structures.
Pricing Analysis
Ingredient-plus-packaging bundling separates subscription-box premiums from standard retail SKUs. Three-tier pricing structure across premium, standard, and economy levels reflects cocoa mass concentration and certification grade differentiation. Cost compression in the economy tier intensifies because sugar-reduction reformulation demands multi-year R&D investment. Food service buyers exhibit highest price sensitivity; online subscription shoppers show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Ivorian and Ghanaian cocoa bean supply. Manufacturing draws from West African origins, Brazilian sugar derivatives, and Malaysian palm oil derivatives. Commodity price volatility threatens margin stability across all tiers. Distribution runs through supermarket central distribution centers with direct-to-consumer platforms gaining last-mile efficiency in London urban density corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in UK confectionery rests on precision fermentation adoption decoupling premium tiers from agricultural commodity swings. Reformulation capex cycles favor scaled operators with captive R&D infrastructure.
For Market Incumbents: Deploy controlled retail distribution to defend premium positioning against direct-to-consumer insurgents. Backward integration into precision fermentation capacity secures supply certainty. Channel control investments at specialty shop placements protect hazelnut-chocolate margin pools from subscription-box erosion. For New Entrants and Emerging Players: Corporate gifting procurement managers represent an underserved buyer archetype with volume predictability and low switching costs. Yorkshire-based gummy texture innovation clusters offer penetrable white-space for permissible indulgence formats. Curated seasonal assortments through direct-to-consumer platforms bypass supermarket slotting barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier manufacturers adopting precision fermentation fastest to defend margin positions. Five-to-ten year viability hinges on regulatory compliance infrastructure and reformulation execution capability. Watch Food Standards Agency front-of-pack labeling rule enforcement timing as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Integration | Decouples premium chocolate supply from ICCO price volatility at West African origins. |
| Direct-to-Consumer Platform Launch | Bypasses Tesco, Sainsbury's, and Asda slotting fees in London metropolitan corridors. |
| Sugar-Reduction Reformulation Program | Aligns product portfolios with UK government reduction targets and FSA labeling rules. |
| Controlled Retail Distribution Expansion | Secures premium placement for hazelnut-chocolate assortments against subscription competition. |
| Packaging Material Transition | Complies with UK plastic packaging taxes through recyclable film and paper-based wraps. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with brand managers, category buyers at Tesco and Sainsbury's, channel sales heads, and supply planners informed demand-side dynamics. Secondary validation drew from Nielsen retail audit data, UK customs import records, Food Standards Agency regulatory filings, and Mondelez and Mars SEC disclosures. Bottom-up SKU-level volume builds triangulated against top-down category spend estimates.
Segment-weighting across product type, customer type, distribution channel, and price tier dimensions anchored the analytical framework. CAGRs were derived from trend extrapolation and diffusion curve modeling across the projection horizon. Cocoa price scenarios, sugar-reduction compliance timelines, and subscription channel adoption curves served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; online retail and premium price tier carry tighter precision than economy-tier volume estimates. Forecasts reflect documented assumptions about regulatory enforcement timing and consumer acceptance of reformulated recipes. Cocoa supply disruption, extended producer responsibility mandate acceleration, or precision fermentation cost breakthroughs could revise trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Chocolate Inclusions and Decorations Market
Confectionery
Cookie Dough Market
Confectionery
Confectionery Fats Market
Confectionery
Italy Chocolate Market
Confectionery
Green Tea Chocolate Market
Confectionery
North America Gummy Market
Confectionery
Middle East and Africa Premium Chocolate Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Europe Sugar Confectionery Market
Confectionery
Europe Chocolate Market
Confectionery
Bangladesh Candy Market
Confectionery
North America Confectionery Market
Confectionery
Chocolate Confectionery Market
Confectionery
Dark Chocolate Market
Confectionery
Middle East and Africa Chocolate Market
Confectionery
Low Calorie Nutella Market