
 Chocolate Powdered Drinks Market | 2026-2036
Chocolate Powdered Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Powdered Drinks Market Outlook
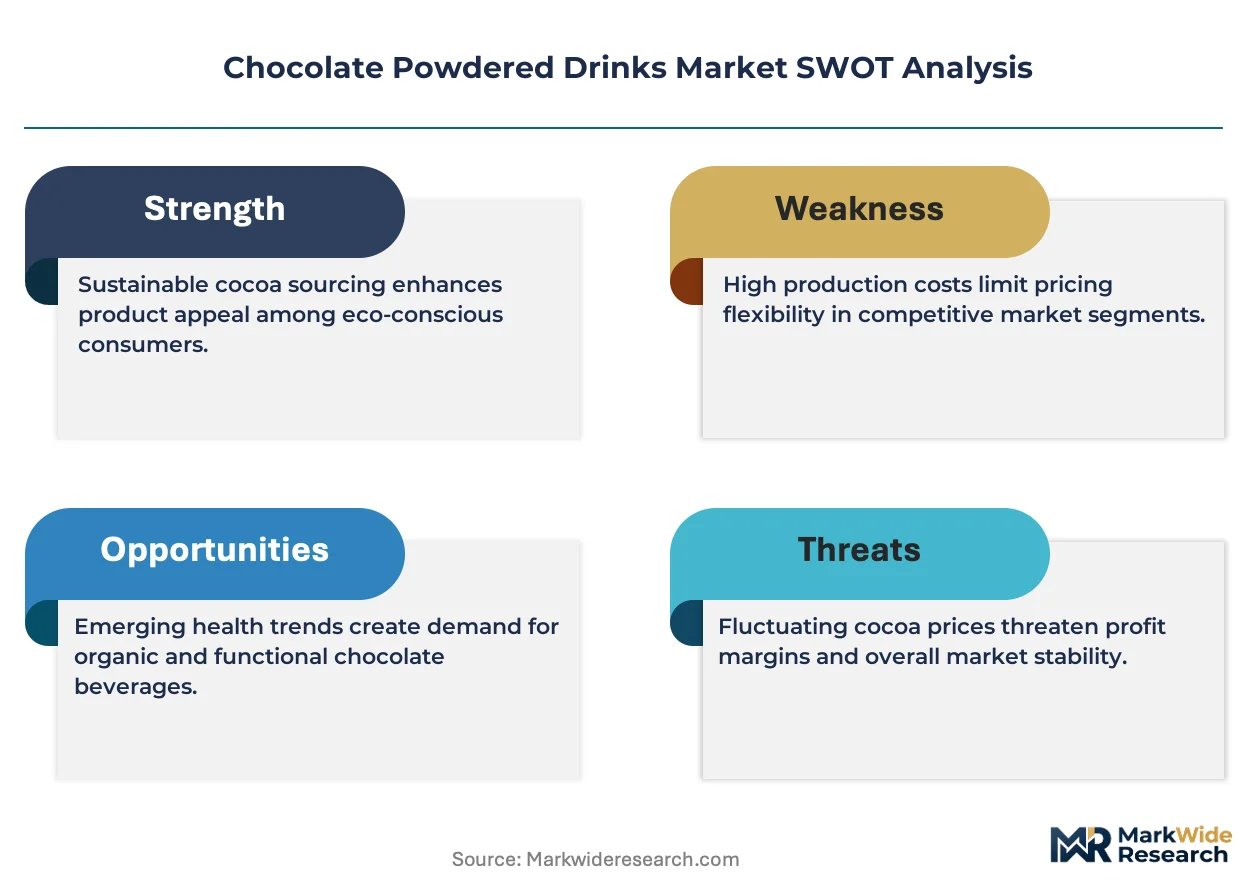
ISO 22000 certification for food safety management systems is unwinding competitive barriers for smaller regional blenders. Nestlé S.A. leverages its dairy sourcing network to sustain cost advantages in malted chocolate beverages. Mars Inc. anchors its position through cocoa supply chain control from West African cooperatives. The Hershey Company competes on confectionery brand equity extended into powdered drink formats.
Chocolate powdered drinks comprise cocoa solids, milk powder, sweeteners, and stabilizers processed through spray-drying or roller-drying to achieve instant solubility in water or milk. The formulation typically contains 15-30% cocoa powder by weight, with emulsifiers such as lecithin ensuring dispersion stability for hot and cold preparation. Instant chocolate mix dominates volume due to pantry-stock purchasing patterns among household end users. Organic chocolate powder captures expanding margin pools as EFSA and USDA organic certification commands shelf price premiums in European and North American retail channels. Sugar-free chocolate drink formulations accelerate fastest among health-positioned online consumers seeking glycemic-controlled alternatives.
FDA nutrition labeling rules and the EU's Farm to Fork Strategy under the EU Green Deal constrain permissible sugar content and mandate cocoa origin disclosures. EFSA health claims regulations limit how manufacturers market functional benefits, redirecting R&D investment toward clean-label stabilizers and natural sweetener systems. Stakeholders must monitor evolving front-of-pack warning label regimes in Latin America and Asia-Pacific, where Chile's black octagon system and India's FSSAI draft sugar thresholds signal convergent regulatory pressure that will reshape product architecture and regional launch priorities.
Market Dynamics
EFSA sugar disclosure mandates and front-of-pack warning label regimes are compressing formulation flexibility across European retail channels, forcing manufacturers to accelerate clean-label stabilizer adoption and natural sweetener substitution timelines.
Growth Catalysts
- Urban retail infrastructure expansion:Brazil, India, and Nigeria are witnessing accelerated supermarket and convenience store penetration, creating shelf access for instant chocolate mix formats among first-time household buyers.
- FSSAI draft sugar thresholds:India's proposed front-of-pack labeling is compelling domestic manufacturers to reformulate ahead of enforcement, generating demand for glycemic-controlled ingredient systems.
- Spray-drying equipment upgrades:Regional blenders in Southeast Asia are deploying advanced atomization technology to achieve particle size distributions matching multinational solubility standards.
Market Restraints
- Cocoa butter equivalent price volatility:Palm oil and shea butter feedstock costs fluctuate with Malaysian ringgit movements, compressing margin predictability for mid-tier producers.
- West African supply concentration:Côte d'Ivoire and Ghana account for dominant global cocoa bean output, exposing processors to weather-driven harvest variability and cooperative payment disruptions.
- EFSA health claims restrictions:Functional benefit marketing limitations constrain premium positioning for fortified chocolate powders targeting immunity or cognitive positioning.
Strategic Opportunities
- Organic certification arbitrage:USDA and EFSA organic standards command shelf price premiums in North American and European retail, rewarding early certification investments by regional blenders.
- E-commerce direct-to-consumer channels:Sugar-free and functional chocolate powder variants accelerate fastest through Amazon and specialty health platforms, bypassing traditional retail slotting fee barriers.
- EU Green Deal Farm to Fork alignment:Cocoa origin disclosure mandates create first-mover advantage for processors with verified traceability systems from cooperative to finished goods.
Industry Challenges
- ISO 22000 certification timelines:Smaller regional blenders face 12-18 month implementation cycles for food safety management documentation, delaying export market access.
- Clean-label stabilizer substitution:Removing synthetic emulsifiers while maintaining cold-water solubility requires reformulation expertise and sensory testing investment that exceeds R&D budgets of sub-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Powdered Drinks Market |
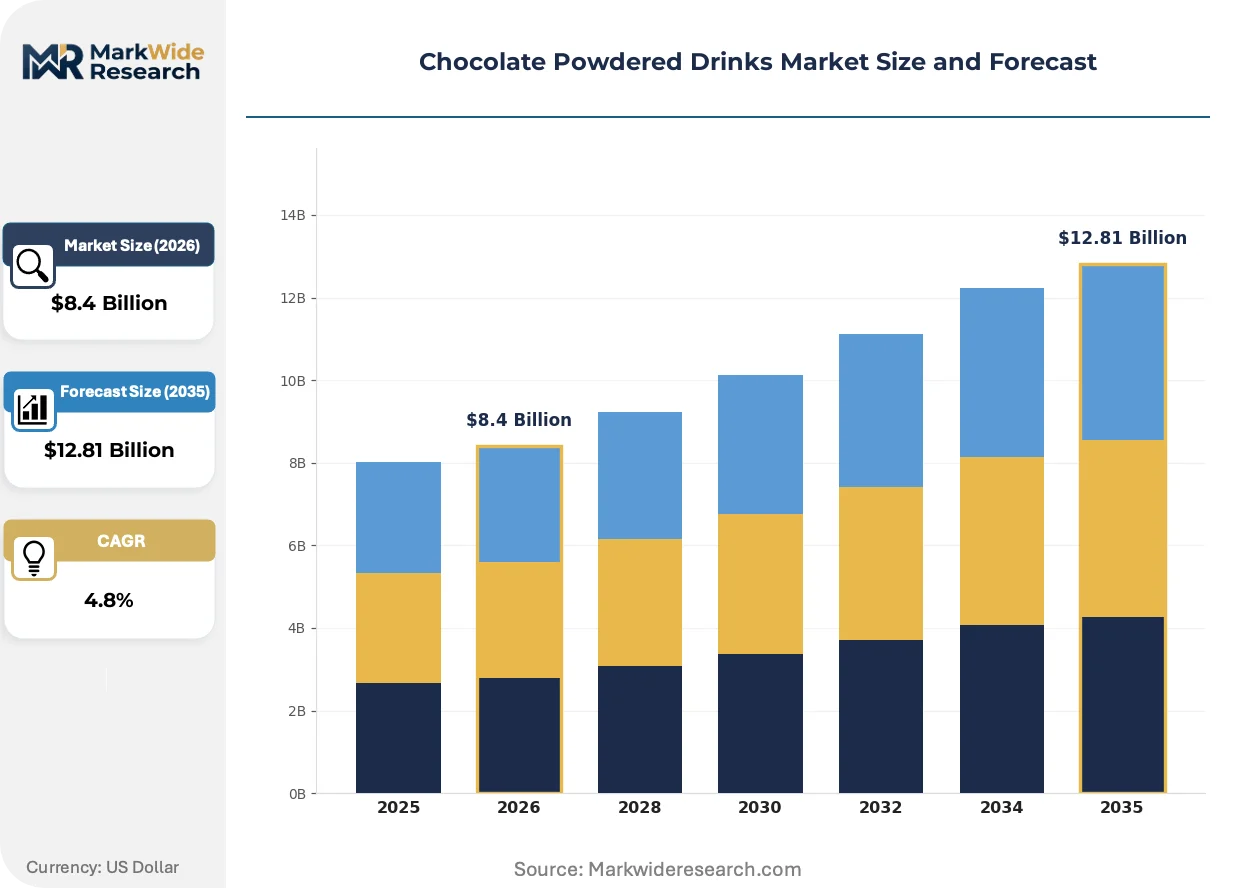
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.81 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Chocolate Mix, Organic Chocolate Powder, Sugar-Free Chocolate Drink, Malted Chocolate Beverage End User: Household, Foodservice, Retail Stores, Online Consumers Distribution Channel: Supermarkets, Convenience Stores, E-Commerce, Specialty Shops Price Tier: Premium, Mid-Range, Budget, Discounted |
| Companies Covered | Mondelez International, Nestlé S.A., Mars Inc., GlaxoSmithKline Plc, PepsiCo Inc., The Hershey Company, The Coca-Cola Company, Cargill Inc., Chocoladefabriken Lindt & Sprüngli AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Powdered Drinks Market Strategic Shifts
Processing technology and regulatory disclosure requirements are fragmenting competitive advantage sources, separating manufacturers with in-house spray-drying capabilities and verified supply chain traceability from commodity blenders.
Encapsulated natural sweetener systems are fragmenting traditional sugar-replacement strategies. Stevia and monk fruit glycoside microencapsulation protects flavor profiles during thermal processing. Health-positioned online consumers in Germany and the United Kingdom are adopting these formulations at pace. Premium private-label contracts now specify encapsulated systems as baseline requirements.
The EU Green Deal Farm to Strategy mandates cocoa origin disclosures on all packaged chocolate products sold in member states. Manufacturers must document cooperative source regions and deforestation compliance status. Organic and fair-trade certified chocolate powders face accelerated audit frequency. European retailers are delisting SKUs lacking blockchain-verified chain-of-custody documentation.
Pantry-stock purchasing patterns among household end users are compressing traditional brand loyalty cycles. Brazilian and Nigerian consumers trial private-label instant mixes during promotional periods and retain preference if solubility performance matches incumbents. E-commerce subscription models capture recurring revenue by locking in flavor-customized replenishment schedules. Direct-to-consumer channels in India report highest retention for malted chocolate variants with regional taste adaptations.
Chocolate Powdered Drinks Market Segmentation
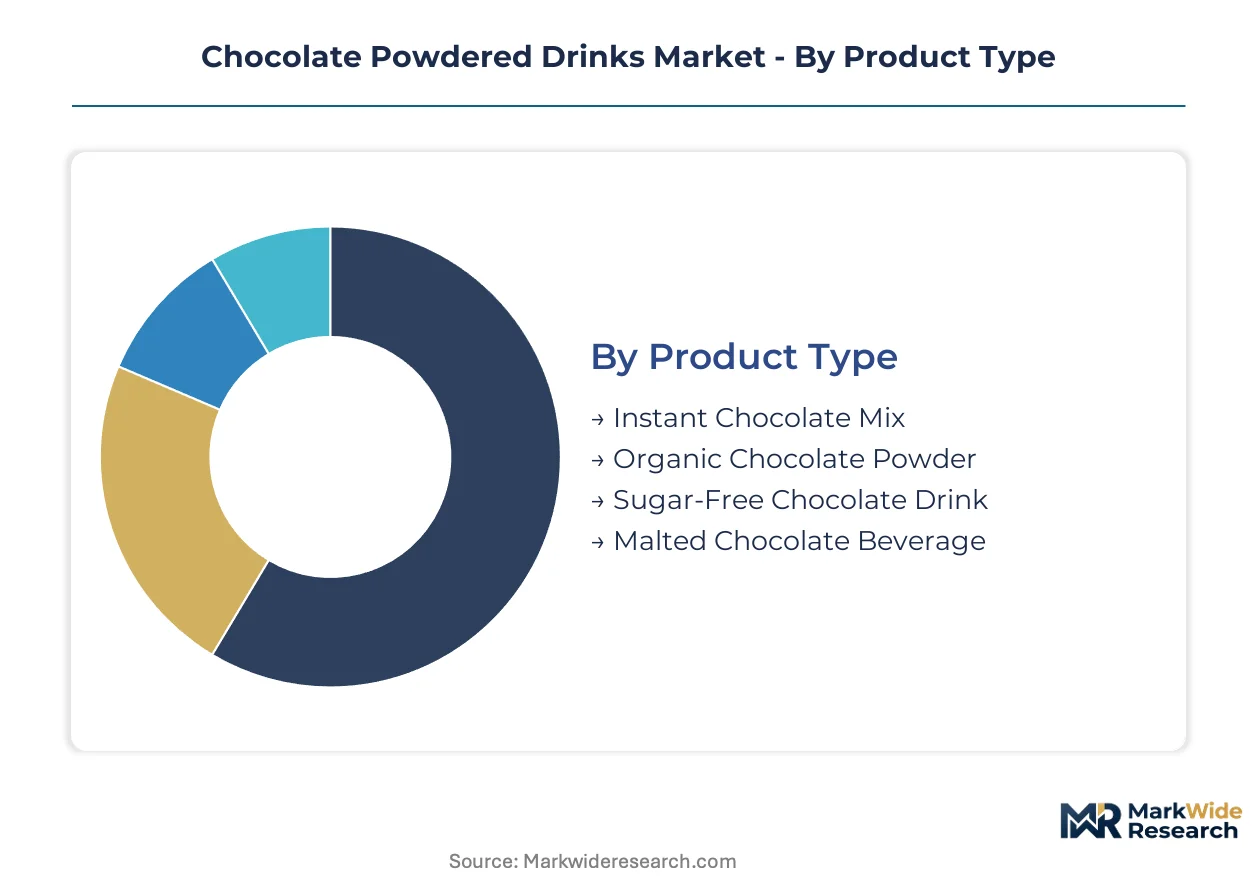
Regulatory disclosure mandates and clean-label preferences fragment the chocolate powdered drinks landscape into distinct competitive arenas. Each segment carries unique compliance burdens and margin structures that reshape manufacturer priorities across formulation, certification, and channel strategy.
Product Type:
EFSA sugar labeling thresholds and USDA organic certification requirements create divergent compliance cost structures across formulation categories.
- Instant Chocolate Mix:Spray-dried cocoa solids with 15-30% powder concentration deliver cold-water solubility through lecithin emulsification. Pantry-stock purchasing in Brazilian and Nigerian households sustains volume dominance despite compressed margins from private-label competition.
- Sugar-Free Chocolate Drink:Stevia and monk fruit glycoside formulations target glycemic-controlled diets through microencapsulated sweetener systems. German and UK online consumers accelerate adoption fastest as FSSAI draft thresholds signal broader regulatory convergence.
- Organic Chocolate Powder:EFSA and USDA certified variants command shelf price premiums in European and North American retail channels.
- Malted Chocolate Beverage:Dairy-forward formulations leverage malt extract for viscosity and regional taste adaptation in Indian direct-to-consumer channels.
Established volume favors instant chocolate mix; emerging adoption favors sugar-free chocolate drink.
End User:
Procurement authority and consumption occasion separate household pantry replenishment from commercial ingredient purchasing.
- Household:First-time buyers in urbanizing Brazil, India, and Nigeria drive instant format trial through supermarket shelf access. Promotional elasticity remains highest among this segment as solubility performance determines brand retention.
- Foodservice:Hot chocolate preparation in cafés and hospitality settings demands consistent dispersion stability across batch sizes. EFSA health claims restrictions constrain functional positioning for immunity or cognitive benefit marketing.
- Retail Stores:Private-label penetration accelerates through Brazilian and Nigerian promotional periods.
- Online Consumers:Subscription models lock recurring revenue through flavor-customized replenishment schedules.
Channel migration runs from retail stores toward online consumers; foodservice procurement stabilizes against household volatility.
Distribution Channel:
Slotting fee structures and traceability documentation requirements fragment access by producer scale and certification status.
- Supermarkets:Shelf placement in Brazilian and Nigerian urban centers creates first-mover advantage for instant mix formats. EU Green Deal origin disclosure mandates now require blockchain-verified documentation for continued listing.
- E-Commerce:Amazon and specialty health platforms bypass traditional retail barriers for sugar-free and functional variants. Highest retention rates concentrate in Indian malted chocolate subscriptions with regional taste profiles.
- Convenience Stores:Grab-and-go single-serve formats target impulse purchase occasions.
- Specialty Shops:Organic and fair-trade certified SKUs face accelerated audit frequency.
Supermarkets anchor mass-market volume; e-commerce climbs the fastest for premium-positioned variants.
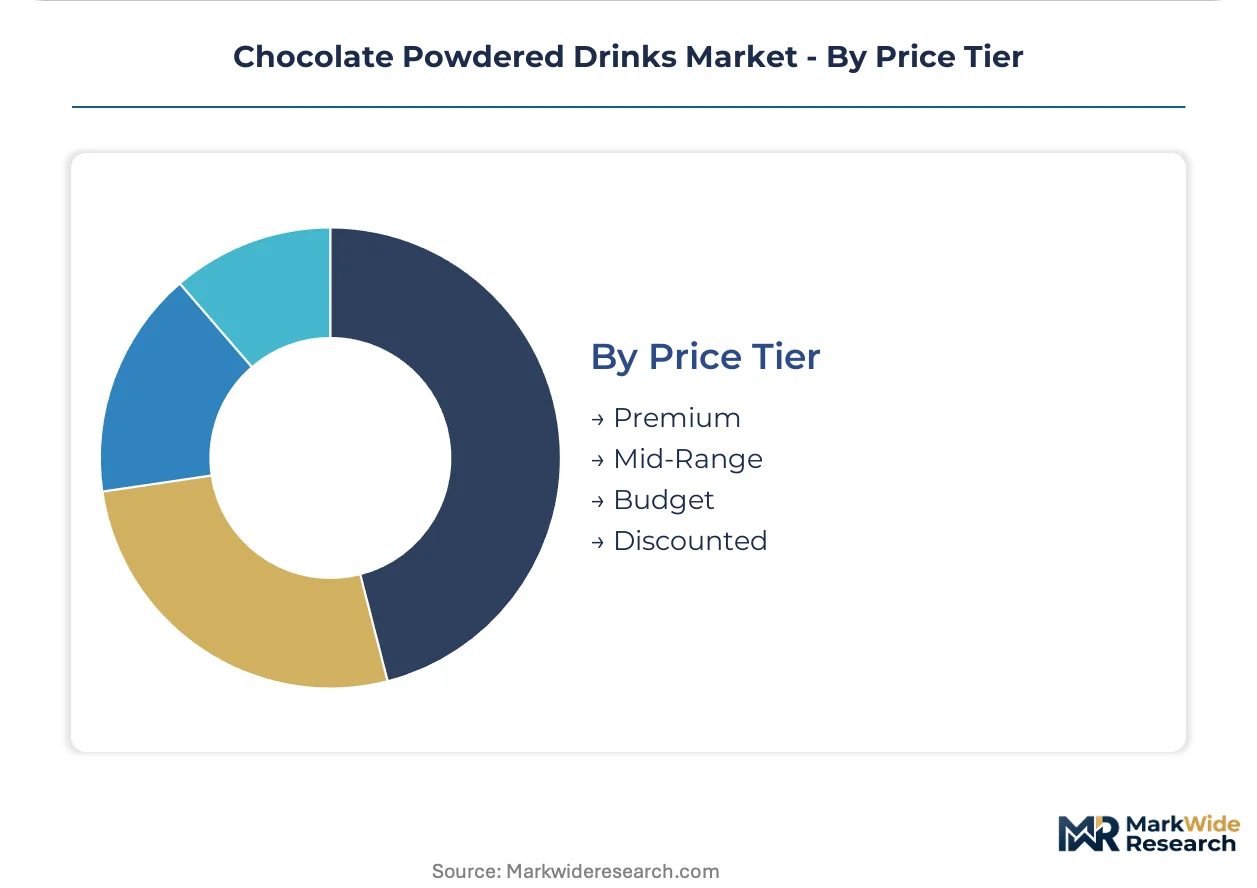
Price Tier:
Certification grade and ingredient specification stratify margin pools across accessible and premium positioning.
- Premium:Organic, fair-trade, and encapsulated sweetener formulations target health-positioned consumers in Germany and the UK. EFSA and USDA certification documentation justifies shelf price premiums above standard tiers.
- Mid-Range:Clean-label stabilizers and natural sweetener substitution balance reformulation cost against regulatory compliance. Indian manufacturers accelerate reformulation ahead of FSSAI draft sugar threshold enforcement.
- Budget:Synthetic emulsifier retention maintains cold-water solubility at lowest unit cost.
- Discounted:Promotional pricing captures trial among Brazilian and Nigerian first-time household buyers.
Mid-range captures reformulation investment flow; premium tier expands most quickly on certification arbitrage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household consumers in emerging economies anchor regional demand patterns, with urban retail infrastructure expansion in Brazil, India, and Nigeria creating first-time buyer access to instant chocolate mix formats. EFSA sugar disclosure mandates and FDA nutrition labeling rules reshape formulation priorities across developed markets, while FSSAI draft thresholds signal regulatory convergence in high-volume Asian markets.
Brazil
Supermarket and convenience store penetration in São Paulo and Rio de Janeiro accelerates pantry-stock purchasing among first-time household buyers. ANVISA front-of-pack labeling proposals align with Chile's black octagon system, pressuring reformulation timelines. Southeast Brazilian retail clusters drive private-label trial during promotional periods, with solubility performance determining brand retention.
India
FSSAI draft sugar thresholds compel domestic manufacturers to accelerate glycemic-controlled ingredient adoption ahead of enforcement. Maharashtra and Gujarat-based blenders deploy spray-drying equipment upgrades to match multinational solubility standards. Direct-to-consumer channels report highest retention for malted chocolate variants with regional taste adaptations in Mumbai and Ahmedabad metro areas.
Germany
Health-positioned online consumers in Berlin and Munich accelerate adoption of encapsulated stevia and monk fruit glycoside formulations. EFSA health claims restrictions constrain functional benefit marketing for immunity-positioned powders. Bavarian and North Rhine-Westphalian retail channels command shelf price premiums for USDA and EFSA organic certified variants.
Nigeria
Urban retail infrastructure expansion in Lagos and Abuja creates shelf access for instant chocolate mix formats among emerging middle-class households. The country's national food safety regulator is developing standards alignment with ISO 22000 certification requirements. Southwest Nigerian distribution clusters concentrate import-dependent supply chains, exposing processors to currency-driven input cost volatility.
United States
FDA nutrition labeling rules and USDA organic certification command shelf price premiums in East Coast and West Coast retail channels. E-commerce subscription models capture recurring revenue through flavor-customized replenishment schedules. Midwestern manufacturing clusters leverage dairy sourcing networks to sustain cost advantages in malted chocolate beverage production.
Chocolate Powdered Drinks Market Competitive Environment
Player mix skews toward multinational conglomerates with dairy and cocoa supply chain control, creating tiered competition between integrated processors and regional blenders. Consolidation pressures concentrate around spray-drying capability ownership and verified traceability documentation. Three archetypes dominate: cocoa supply chain controllers, dairy-forward malted beverage specialists, and clean-label stabilizer innovators. Competitive moves center on ISO 22000 certification acceleration and organic certification arbitrage for premium shelf positioning.
Among Switzerland-based multinationals, Nestlé S.A. and Chocoladefabriken Lindt & Sprüngli AG exemplify dairy and cocoa integration archetypes. The Hershey Company represents confectionery brand equity extension into powdered formats. These three occupy positions spanning premium certification tiers and mass-market volume channels, with each anchoring distinct competitive vectors around supply chain control, brand licensing, or formulation specialization.
| Leading Market Players |
|---|
| Mondelez International |
| Nestlé S.A. |
| Mars Inc. |
| GlaxoSmithKline Plc |
| PepsiCo Inc. |
| The Hershey Company |
| The Coca-Cola Company |
| Cargill Inc. |
| Chocoladefabriken Lindt & Sprüngli AG |
| Others |
Value Chain & Pricing Dynamics
Natural sweetener substitution for synthetic emulsifiers and refined sugar is redrawing procurement geography toward stevia cultivation zones in Paraguay and monk fruit processing clusters in southern China, compressing formulation economics for mid-tier blenders while amplifying cost advantages for integrated multinationals with captive agricultural sourcing.
Pricing Analysis
Cost-plus contracts with cocoa butter equivalent indexation to Malaysian palm oil futures dominate procurement between West African processors and European manufacturers. Three-tier pricing structure across organic certified, clean-label reformulated, and standard synthetic-stabilizer tiers separates shelf price bands by certification grade and solubility performance. Pricing pressure stems from private-label trial elasticity in Brazilian and Nigerian promotional windows. Budget-tier household buyers in emerging urban centers exhibit highest price sensitivity; premium organic subscribers in German e-commerce channels show lowest.
Supply Chain Analysis
Côte d'Ivoire and Ghana anchor global cocoa bean output, with Ecuador and Cameroon expanding marginal supply. Spray-drying equipment, lecithin emulsifiers, and malt extract feed from Chinese and Indian manufacturing clusters. Single-source vulnerability concentrates in West African cooperative payment systems and harvest variability. Distribution runs through Southeast Asian port consolidation for Asian markets and Rotterdam-Antwerp hubbing for European retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through ISO 22000 certification and EFSA organic compliance creates switching costs that lock retail shelf access.
For Market Incumbents: Fortify cooperative supply agreements in Côte d'Ivoire and Ghana through advance payment systems that secure harvest priority against emerging processor competition. Accelerate blockchain traceability documentation to meet EU Green Deal origin disclosure mandates before delisting thresholds activate. Certification investment in EFSA and USDA organic tiers anchors premium positioning against private-label encroachment. For New Entrants and Emerging Players: Lead with encapsulated natural sweetener formulations targeting glycemic-controlled online consumers in Germany and the United Kingdom where incumbent reformulation lags FSSAI convergence signals. E-commerce direct-to-consumer channels in India offer lowest slotting fee barriers for malted chocolate variants with regional taste adaptation. Specialty health platforms bypass supermarket consolidation. For Investors and Strategic Acquirers: Capital is best deployed toward regional blenders with spray-drying capability ownership and pending ISO 22000 certification completion, positioned for export market access acceleration. Long-term viability over a multi-year horizon hinges on clean-label stabilizer substitution completion ahead of regulatory enforcement waves. The signal to monitor is FSSAI final sugar threshold publication triggering reformulation capex spikes among sub-scale Indian manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Implementation | EU Green Deal origin disclosure mandates now require cooperative-to-finished-goods documentation for continued retail listing. |
| Encapsulated Sweetener System Adoption | Microencapsulated stevia and monk fruit glycosides protect flavor profiles during thermal processing for health-positioned variants. |
| Spray-Drying Equipment Upgrade | Advanced atomization technology achieves particle size distributions matching multinational solubility standards for regional blenders. |
| Direct-to-Consumer Channel Launch | E-commerce subscription models capture recurring revenue through flavor-customized replenishment schedules in Indian metro areas. |
| Organic Certification Arbitrage | USDA and EFSA organic standards command shelf price premiums in North American and European retail channels. |
Study Parameters
Initial hypotheses were tested against primary input from category buyers at Brazilian and Nigerian supermarket chains, spray-drying equipment procurement managers, and regulatory affairs leads at multinational beverage manufacturers, then refined through secondary validation against EFSA guidance documents, FSSAI draft notification records, and customs trade data for cocoa powder and malt extract shipments. Bottom-up volume modeling from individual country retail audits triangulated with top-down macroeconomic consumption elasticity frameworks.
Variance decomposition across the projection horizon isolates volume drivers by product type segmentation, distribution channel migration patterns, and regional regulatory cluster convergence. CAGRs derive from weighted average growth assumptions across household pantry replenishment cycles, foodservice batch preparation stability requirements, and online consumer subscription retention curves. Industry-specific forecast inputs include spray-drying capacity utilization rates and organic certification audit completion timelines.
The analysis sits within stated boundaries; outcomes outside EFSA enforcement consistency, FSSAI threshold finalization, or West African harvest stability would require recalibration. Forecasts reflect documented assumptions about regulatory implementation pacing and cooperative payment system reliability. Recalibration cycles align with material shifts in front-of-pack labeling regime adoption and encapsulated sweetener technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Coconut Milk Beverages Market
Beverages
Japan Kombucha Market
Beverages
Craft Soda Market
Beverages
Germany Probiotic Drinks Market
Beverages
Packaged Milkshake Market
Beverages
Beverage Cooler Market
Beverages
Ready to Drink Shakes Market
Beverages
Enzyme-Enabled Cold-Brew Concentrates Market
Beverages
Nitro-Infused Beverages Market
Beverages
Indonesia Bottled Water Market
Beverages
Hot Cocoa Mix Market
Beverages
Soft Serves Market
Beverages
Beverage Premix Market
Beverages
Birch Water Market
Beverages
Popping Bobas Market
Beverages
Saudi Arabia Bottled Water Market