
 Textured Butter Market | 2026-2036
Textured Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Textured Butter Market Outlook
European dairy technician availability is collapsing as aging master butter-makers retire without sufficient apprenticeship pipeline replacement, tightening craft-scale output capacity. Lactalis Ingredients leverages its vertically controlled cream sourcing across northwestern France to secure consistent fat-protein ratios for textured butter output. Arla Foods anchors Nordic supply through cooperative member farms with direct-to-manufacturer channel control. Fonterra Co-operative Group competes on ocean freight-advantaged bulk butteroil shipments that Oceania processors re-temper into textured formats for Asian bakery accounts.
Textured butter denotes churned dairy fat processed through controlled mechanical working, temperature cycling, and crystallization seeding to achieve specific plasticity, mouthfeel, and lamination performance in finished applications; typical specifications require 82-84% milk fat content with tempered solid fat indices between 15-25°C to ensure sheetability without oiling out. Spreadable butter occupies the broadest household penetration but carries thinner margin pools due to commodity pricing pressure and retailer private-label substitution. Compound butter, infused with herbs, spices, or wine reductions, commands premium positioning within food service channels where menu differentiation justifies higher procurement costs. Whipped butter, aerated with nitrogen injection, sustains niche growth in convenience-oriented North American retail.
FDA standards of identity in the United States mandate minimum 80% milk fat for butter labeling, while EFSA and national EU regulators enforce stricter compositional thresholds under dairy PDO frameworks that textured butter producers exploit for premium positioning. BIS certification requirements in India for imported dairy fats create non-tariff friction that shapes market access strategies for exporters targeting food manufacturer segments. Stakeholders must monitor evolving energy cost structures and carbon accounting rules that threaten to re-segment cost competitiveness between churning-intensive European supply and more mechanized Oceania processing routes.
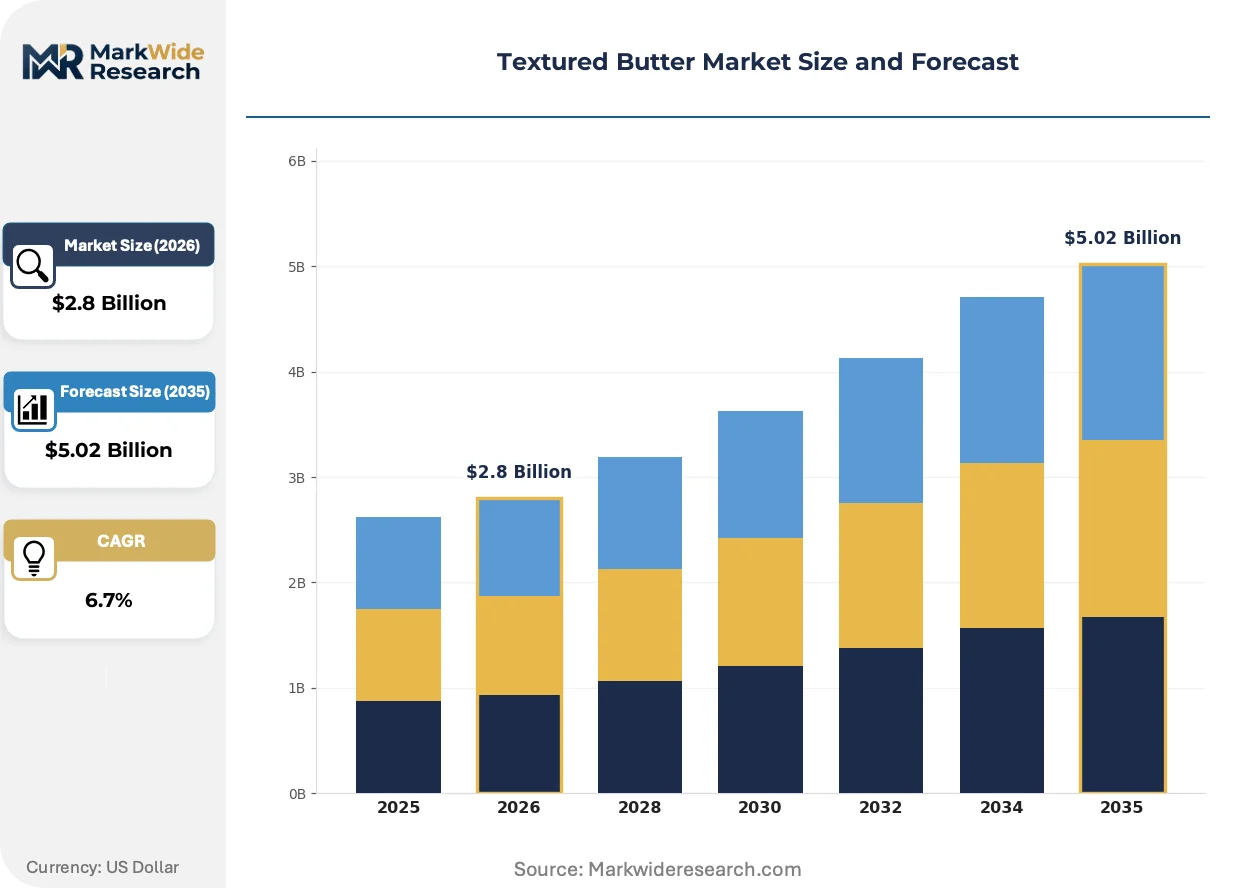
Market Dynamics
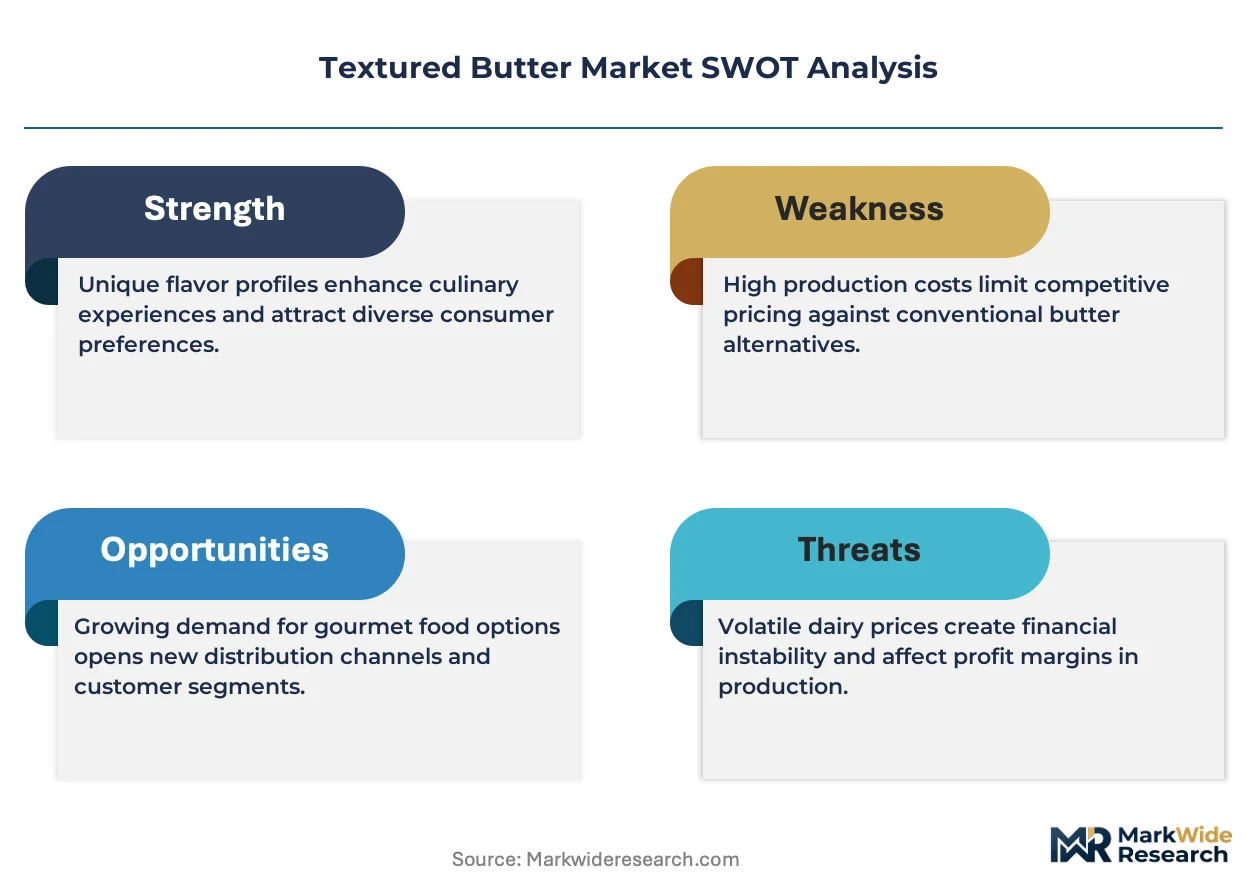
EU F-Gas Regulation phase-down schedules are compressing processor margins and accelerating capital rotation toward lower-energy churning equipment, reshaping competitive cost structures between European craft producers and mechanized Oceania supply routes.
Growth Catalysts
- Artisanal bakery chain expansion:Laminated dough specialists across France and Denmark are expanding procurement of specialty butter formats, creating dedicated supply contracts for textured product specifications.
- PDO framework exploitation:Protected designation of origin traditions in northwestern France anchor premium positioning, allowing producers to command price premiums through certified provenance claims under EFSA-enforced compositional thresholds.
- Energy-efficient tempering:Mechanical working and crystallization seeding technologies are reducing churning energy intensity, aligning processor investments with EU Green Deal carbon accounting requirements.
Market Restraints
- Cream supply concentration:Vertically controlled sourcing in northwestern France creates dependency on regional dairy cooperative structures, limiting alternative procurement for mid-scale processors.
- Master technician scarcity:Aging butter-maker retirements without apprenticeship pipeline replacement are tightening craft-scale output capacity, constraining batch consistency at traditional producers.
- BIS certification friction:India's Bureau of Indian Standards requirements for imported dairy fats create non-tariff barriers that shape exporter market access strategies for food manufacturer segments.
Strategic Opportunities
- Asian bakery re-tempering:Oceania bulk butteroil shipments offer freight-advantaged positioning for processors serving Japanese and South Korean laminated pastry accounts through localized tempering operations.
- Nitrogen injection niche:Whipped butter aeration technology addresses convenience-oriented North American retail channels seeking spreadability without oiling-out performance degradation.
- Compound butter premiumization:Herb, spice, and wine reduction infusions command food service procurement budgets where menu differentiation justifies higher input costs for laminated dough applications.
Industry Challenges
- Apprenticeship system collapse:Dairy technician training programs lack enrollment velocity to replace retiring master butter-makers, threatening batch-to-batch consistency in PDO-designated production zones.
- Carbon accounting integration:Processors must embed Scope 3 emissions tracking across cooperative member farm networks to maintain EU Green Deal compliance without eroding margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textured Butter Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whipped Butter, Spreadable Butter, Clarified Butter, Compound Butter Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Stores End User: Households, Food Services, Bakeries, Food Manufacturers Packaging Type: Sticks, Tubs, Pouches, Jars |
| Companies Covered | Lactalis Ingredients, Fonterra Co-operative Group, Arla Foods, Uelzena Group, Royal VIV Buisman, Lakeland Dairies, Michigan Milk Producers Association, Flechards SA, Land O'Lakes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textured Butter Market Strategic Shifts
Controlled mechanical working and temperature cycling protocols are displacing traditional batch methods, while regulatory carbon accounting and procurement consolidation reshape how textured butter moves from churn to laminated dough application.
Precision crystallization seeding is fragmenting the equipment supply base as specialized tempering systems enable smaller processors to achieve fat-protein consistency previously requiring master technician oversight. Mid-scale bakeries in Denmark and Belgium are adopting these systems fastest, compressing the premium historically commanded by PDO-certified French supply through reproducible plasticity metrics.
EU F-Gas Regulation phase-down schedules are forcing refrigeration-dependent churning operations toward ammonia-based cooling retrofits or geographic relocation. Equipment suppliers serving the dairy sector report order backlogs stretching eighteen months as processors race to avoid operational shutdowns, with French PDO producers facing the steepest compliance cliffs due to legacy facility age.
Direct-to-manufacturer channel control is consolidating procurement influence as cooperative member farms bypass traditional dairy auction systems. Nordic supply through vertically integrated structures now captures bakery chain contracts previously awarded through spot market purchasing, with laminated dough specialists in Sweden and Norway locking multi-year supply agreements to secure fat index consistency across seasonal variation.
Textured Butter Market Segmentation
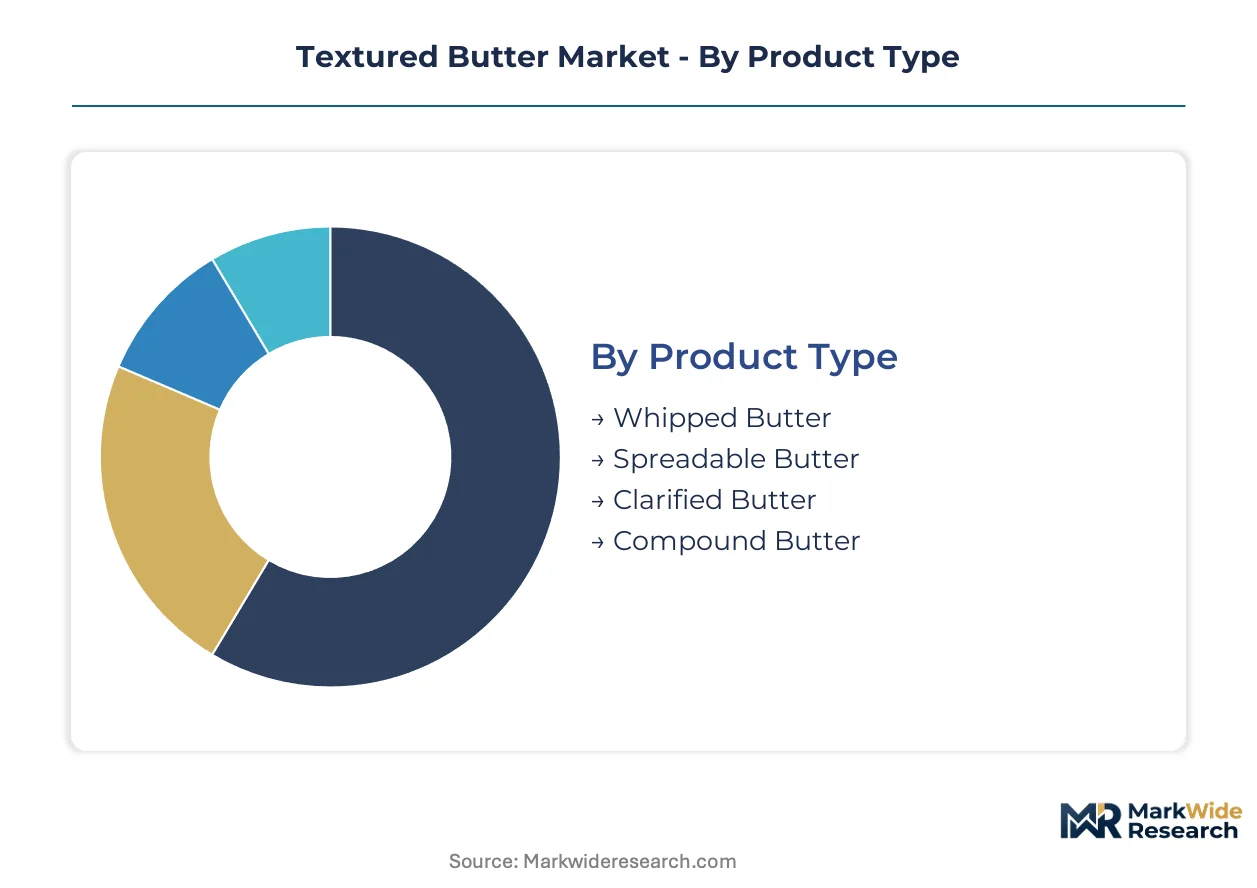
Segmentation in textured butter reveals how functional specifications diverge across procurement channels, with lamination performance requirements separating industrial bakery accounts from retail spreadability preferences. Each dimension carries distinct margin structures and regulatory exposure that reshape competitive positioning.
Product Type:
Substitution pressure from plant-based spreads and shortening alternatives concentrates most intensely on spreadable formats, while compound and clarified variants defend position through irreplicable flavor chemistry and thermal stability.
- Spreadable Butter:Aerated or tempering-modified dairy fat achieving scoopable consistency at refrigeration temperatures through controlled crystallization seeding. Household penetration in North America and Western Europe remains broad, though retailer private-label substitution erodes branded margin pools. Margarine and plant-oil spreads exert persistent price-pressure substitution in mass retail channels.
- Compound Butter:Churned fat infused with herbs, spices, wine reductions, or umami concentrates through post-churn mechanical working. Food service procurement in France and Denmark drives demand, where laminated dough applications and menu differentiation justify premium positioning against commodity butter alternatives.
- Whipped Butter:Nitrogen-injected aeration reducing density by 25-40% for spreadability without tempering infrastructure.
- Clarified Butter:Moisture and protein removal yielding 99%+ milk fat content for high-heat cooking stability.
Spreadable butter anchors the volume base while compound butter gains share at the steepest rate.
Distribution Channel:
Cost tier stratification separates premium specialty stores from high-volume supermarket procurement, with online channels fragmenting traditional price-band discipline through direct-to-consumer subscription models.
- Supermarkets:Dominant volume channel for household spreadable formats, characterized by slotting fee structures and private-label substitution pressure. Retail consolidation in France and Germany compresses supplier negotiation leverage.
- Specialty Stores:Curated procurement of PDO-certified French butter and small-batch compound variants. Premium positioning through provenance storytelling and laminated dough education for artisanal bakery customers.
- Online Retailers:Subscription-based replenishment and temperature-controlled logistics enabling direct access to regional specialty producers.
- Convenience Stores:Impulse-oriented single-serve and travel-size formats with limited SKU depth.
Supermarkets retain the volume anchor while specialty stores expand most quickly through provenance-premium positioning.
End User:
Application-driven specification divergence separates laminated dough performance requirements from household spreadability preferences, with food manufacturers imposing the strictest fat-index consistency standards.
- Bakeries:Laminated dough specialists in Denmark, France, and Belgium require precise solid fat indices between 15-25°C for sheetability without oiling out. Multi-year supply contracts with cooperative processors lock in seasonal fat-protein ratio consistency.
- Food Manufacturers:Industrial-scale procurement of bulk butteroil for re-tempering into textured formats, with Japanese and South Korean pastry processors representing freight-advantaged Oceania supply destinations.
- Households:Price-sensitive spreadability preference driving private-label substitution in mass retail.
- Food Services:Menu-differentiation procurement of compound butter for finishing sauces and plated applications.
Bakeries anchor volume through contract consolidation while food manufacturers climb fastest through Asian re-tempering demand.
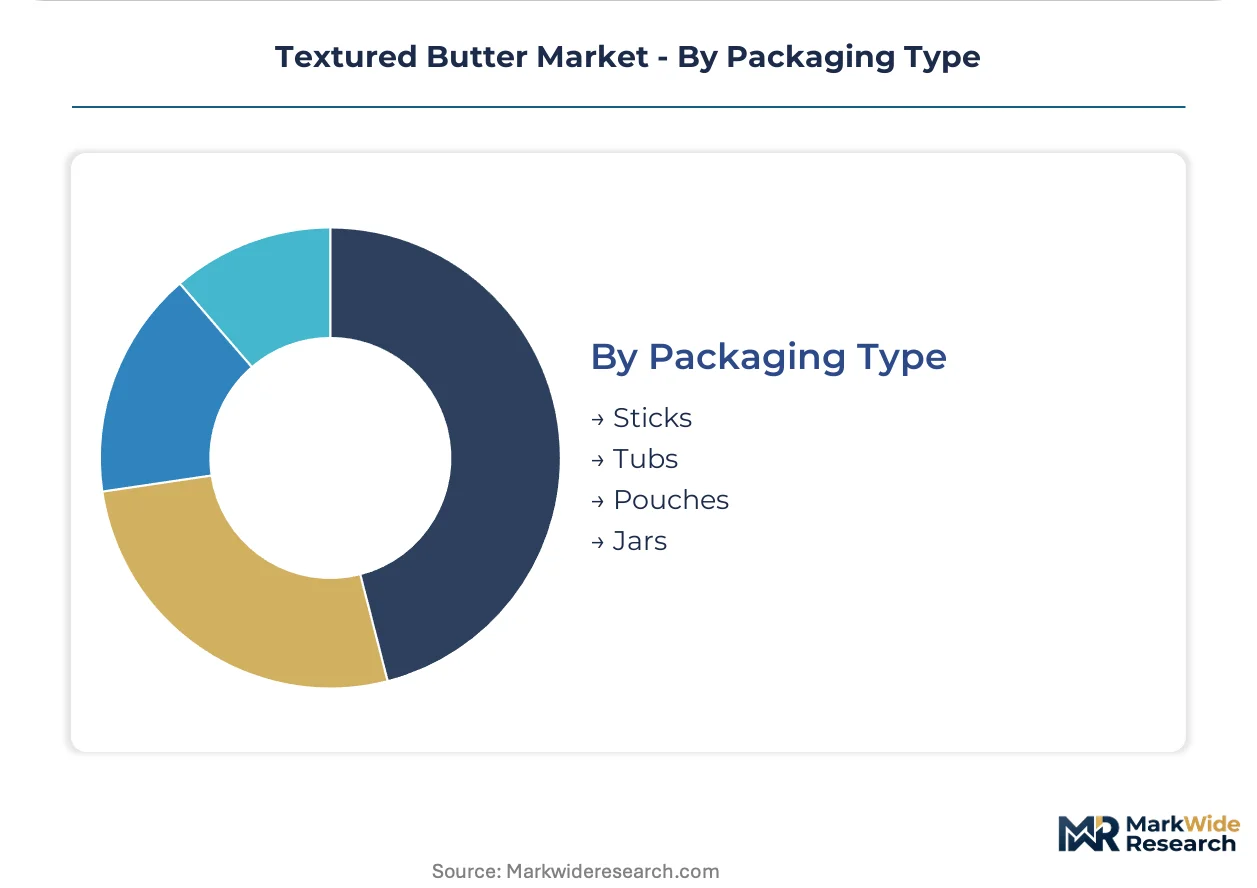
Packaging Type:
Supply concentration in northwestern France cooperative structures shapes packaging format availability, with stick formats dominating PDO-designated production and tubs enabling spreadable convenience positioning.
- Sticks:Standardized 113g and 250g formats for North American and European retail, optimized for lamination performance measurement and recipe standardization in professional bakery applications.
- Tubs:Wider-mouth containers for whipped and spreadable variants requiring scoop access. Convenience-oriented North American retail penetration sustains niche growth despite thinner margin structures.
- Pouches:Flexible format for food service bulk dispensing and industrial bakery pump systems.
- Jars:Premium positioning for compound butter with visible herb and spice inclusions.
Sticks defend the volume base while tubs expand through convenience-oriented channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA compositional thresholds under EU dairy frameworks anchor premium textured butter positioning, with northwestern France cooperative structures supplying laminated dough specialists across Denmark and Belgium through controlled fat-protein sourcing.
France
PDO-designated butter traditions in Normandy and Brittany drive procurement from artisanal bakery chains requiring sheetable fat indices. EU F-Gas Regulation phase-down schedules compress margins at legacy churning facilities in Isigny-sur-Mer. Master butter-maker retirements tighten batch consistency at craft-scale producers without apprenticeship pipeline replacement.
Denmark
Lamination performance specifications from Copenhagen and Aarhus bakery specialists concentrate demand for tempered solid fat indices between 15-25°C. Cooperative member farms bypass traditional dairy auction systems through direct-to-manufacturer channel control. Precision crystallization seeding adoption in mid-scale operations compresses premiums historically commanded by French PDO supply.
United States
FDA standards of identity mandating minimum 80% milk fat shape labeling requirements for spreadable and whipped formats in household retail. Nitrogen-injected aeration sustains niche growth in convenience-oriented channels despite private-label substitution pressure. Wisconsin and California dairy processing clusters serve North American laminated dough applications through bulk butteroil re-tempering operations.
Japan
Food manufacturers in Osaka and Tokyo impose strict fat-index consistency standards for laminated pastry production. Oceania bulk butteroil shipments offer freight-advantaged positioning for localized tempering into textured formats. MFDS-equivalent dairy fat regulations create compliance frameworks for imported butteroil reprocessing.
India
BIS certification requirements for imported dairy fats create non-tariff friction shaping exporter market access strategies for food manufacturer segments. Maharashtra and Gujarat processing clusters represent emerging demand for clarified butter formats in high-heat cooking applications. FSSAI enforcement of dairy product standards influences procurement decisions among industrial bakery accounts.
Textured Butter Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with precision tempering equipment specialists commanding premium positioning against bulk butteroil shippers competing on ocean freight economics. The vendor base organizes around three strategic archetypes: vertically integrated French cooperatives controlling northwestern cream sourcing, Oceania bulk exporters leveraging freight-advantaged positioning for Asian re-tempering, and North American dairy cooperatives serving continental spreadable demand. Competitive moves concentrate on cooperative member farm network consolidation and ammonia-based cooling retrofit investments to meet EU F-Gas compliance deadlines.
Within the vertically integrated cooperative tier, Lactalis Ingredients anchors northwestern French supply through captive cream sourcing across Normandy and Brittany dairy networks. Fonterra Co-operative Group exemplifies the Oceania bulk export archetype, with re-tempering operations in Japan and South Korea representing freight-optimized pathways to Asian laminated dough accounts. Arla Foods occupies the Nordic cooperative position, leveraging direct-to-manufacturer channel control across Danish and Swedish bakery chain procurement.
| Leading Market Players |
|---|
| Lactalis Ingredients |
| Fonterra Co-operative Group |
| Arla Foods |
| Uelzena Group |
| Royal VIV Buisman |
| Lakeland Dairies |
| Michigan Milk Producers Association |
| Flechards SA |
| Land O'Lakes |
| Others |
Value Chain & Pricing Dynamics
Multi-year offtake contracts between northwestern French cooperatives and Danish laminated dough specialists lock in cream supply access while anchoring price visibility against seasonal fat-protein ratio swings. These arrangements compress spot market liquidity and transfer margin volatility onto processors lacking backward integration into member farm networks.
Pricing Analysis
French PDO-certified butter commands substantial premiums over Oceania bulk butteroil in Japanese and South Korean procurement, with three-tier pricing structure across premium, standard, and economy levels separating protected designation provenance from re-tempered commodity supply. Price differentiation hinges on certification grade and volume scale, with artisanal bakery chains least sensitive and mass retail households most responsive to private-label substitution. Cost compression in spreadable formats is intensifying because retailer consolidation in France and Germany erodes supplier negotiation leverage.
Supply Chain Analysis
Strategic stockpiling of tempered inventory dominates bakery chain procurement, while just-in-time cream sourcing prevails among mid-scale processors lacking cooperative membership. Supply concentrates in France, New Zealand, and Denmark, drawing from cream, nitrogen injection equipment, and crystallization seeding technology inputs. Single-source vulnerability around northwestern French cooperative structures threatens batch consistency as master technician retirements accelerate. Distribution runs through direct-to-manufacturer channels bypassing traditional dairy auction systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical compression driven by EU F-Gas Regulation compliance investments that temporarily constrained craft-scale output capacity.
For Market Incumbents: Fortify cooperative member farm networks through ammonia-based cooling retrofits ahead of enforcement cliffs, while embedding Scope 3 emissions tracking to defend margin structures against carbon accounting integration costs. Priority rests on locking multi-year supply agreements with laminated dough specialists before precision crystallization seeding democratizes fat-index consistency. For New Entrants and Emerging Players: Differentiate on nitrogen-injected aeration technology for North American convenience retail, where whipped butter penetration remains underdeveloped relative to spreadable formats. White-space targets include Indian food manufacturer segments constrained by BIS certification friction, and Japanese re-tempering operations seeking freight-optimized Oceania butteroil alternatives. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated cooperatives controlling northwestern French cream sourcing, with long-term viability contingent on apprenticeship pipeline reconstruction. The signal to watch is enrollment velocity at dairy technician training programs, which indicates craft-scale output capacity sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia-Based Cooling Retrofit | French PDO producers avoid EU F-Gas Regulation operational shutdowns through equipment replacement. |
| Precision Crystallization Seeding Adoption | Danish mid-scale bakeries compress premiums historically commanded by French certified supply. |
| Direct-to-Manufacturer Channel Control | Nordic cooperative structures capture contracts previously awarded through spot market purchasing. |
| Scope 3 Emissions Tracking Integration | Processors maintain EU Green Deal compliance without eroding cooperative margin structures. |
| Nitrogen Injection Capacity Expansion | North American retailers address convenience-oriented spreadability demand without oiling-out degradation. |
Study Parameters
A standing panel of dairy processing technologists, cooperative procurement managers, laminated dough specialists, and food manufacturer R&D directors provided ongoing calibration against secondary validation from customs records, EU dairy framework filings, F-Gas Regulation compliance databases, and SEC disclosures from listed dairy cooperatives. Bottom-up volume triangulation across product type, distribution channel, end user, and packaging format segments converged with top-down macroeconomic anchoring.
Outputs were stress-tested against external benchmarks including EFSA compositional threshold enforcement patterns and Oceania bulk butteroil freight rate indices. Segmentation dimensions spanned product functionality, procurement channel structure, application performance requirements, and regional regulatory clusters. CAGRs were derived from trend extrapolation moderated by technician availability constraints and energy cost trajectory assumptions.
Material uncertainties — master butter-maker retirement velocity, ammonia equipment delivery backlogs, and BIS certification timeline shifts — sit outside the modeled envelope. Forecasts reflect assumptions about cooperative network stability and carbon accounting rule finalization. Revision becomes warranted when apprenticeship enrollment crosses thresholds sufficient to replace retiring craft-scale technicians.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Colombia Dairy Market
Dairy Products
Global Goat Cheese Market
Dairy Products
Europe Cheese Market
Dairy Products
Ready-To-Use Cheese Market
Dairy Products
Argentina Whey Protein Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Germany Dairy Market
Dairy Products
Butter and Margarine Market
Dairy Products
Global Fresh Milk Market
Dairy Products
Smoked Cheese Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Global Yogurt Market
Dairy Products
Probiotic Fermented Milk Market
Dairy Products
Cheese Concentrate Market
Dairy Products
Cultured Whey Products Market
Dairy Products
North America Dairy Market