
 Functional Soda Market | 2026-2036
Functional Soda Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Soda Market Insights
Multi-source ingredient procurement is expanding across the functional soda value chain as brands hedge against supply volatility in natural sweetener and prebiotic fiber markets. Olipop leverages its vertically integrated digestive health platform to sustain premium positioning in prebiotic formulations. Poppi anchors its growth through fruit-forward flavor innovation with clinically backed apple cider vinegar positioning. Coca-Cola competes by extending its distribution infrastructure into functional sub-brands through incubator-style portfolio management.
Functional soda denotes carbonated beverages fortified with bioactive compounds including prebiotic fibers, electrolyte minerals, plant proteins, or botanical extracts, typically manufactured via cold-fill aseptic processing to preserve probiotic viability and volatile aromatic compounds. These formulations serve metabolic support, hydration optimization, or cognitive performance enhancement for health-motivated consumers. Prebiotic and electrolyte product types command the deepest margin pools as consumers prioritize gut microbiome balance and workout recovery over basic refreshment. E-commerce and health food store distribution channels outpace conventional supermarket velocity, reflecting channel-specific shopper missions where discovery and education drive conversion.
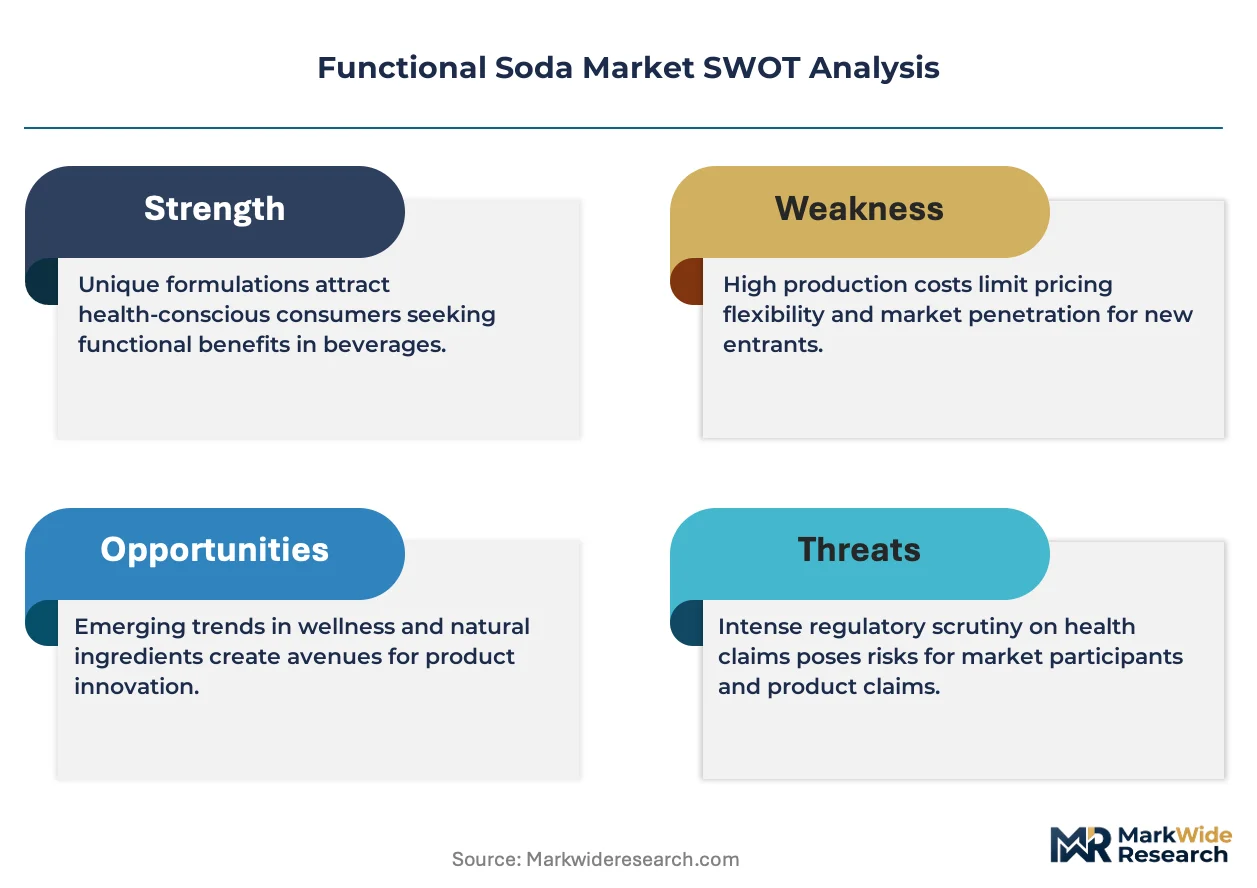
FDA nutrition labeling requirements and EFSA health claim substantiation protocols constrain permissible marketing language around digestive and immune benefits, forcing reformulation investments and clinical study commitments. The EU Green Deal packaging directives and emerging US state-level extended producer responsibility laws are accelerating transitions to aluminum can and recycled PET formats. Stakeholders must monitor evolving regulatory thresholds for added sugar taxation and front-of-package warning labels that could reclassify certain functional positioning claims.
Market Dynamics
Clean-label formulation mandates under FDA and EFSA frameworks are compressing R&D timelines while forcing simultaneous clinical substantiation investments, creating a dual-compliance burden that favors well-capitalized operators with captive research infrastructure.
Growth Catalysts
- Prebiotic fiber demand:Gut microbiome awareness among health-motivated consumers in the United States and Germany is pulling functional formulations into mainstream beverage repertoires. Cold-fill aseptic processing advances now preserve volatile bioactive compounds through distribution.
- EU Green Deal packaging directives:Aluminum can and recycled PET mandates are accelerating format transitions that align with premium positioning strategies. Extended producer responsibility laws in California and New York mirror these thresholds.
- Electrolyte fortification:Post-workout recovery occasions are expanding beyond fitness enthusiasts into daily hydration routines. Japan's functional beverage culture provides formulation templates now adapted for Western palates.
Market Restraints
- Natural sweetener supply volatility:Stevia and monk fruit concentrate sourcing faces climate-driven harvest variability across Southeast Asian growing regions. Brands hedge through multi-year offtake agreements with plantation networks.
- EFSA health claim substantiation:Digestive benefit marketing language requires human intervention studies costing substantial capital per approved claim. Smaller operators lack resources to build compliant evidence portfolios.
- Refrigerated distribution infrastructure:Probiotic viability requirements limit ambient-channel expansion into conventional vending and convenience retail. Cold-chain density concentrates in coastal metropolitan corridors.
Strategic Opportunities
- Cognitive performance positioning:Nootropic botanical extracts represent an underdeveloped white space adjacent to established gut-health and hydration claims. Adaptogen combinations from traditional Chinese medicine pharmacopeia offer differentiation vectors.
- Direct-to-subscription models:E-commerce discovery channels bypass slotting-fee barriers that supermarket distribution imposes on emerging brands. Personalized flavor profiling based on microbiome testing data creates recurring revenue architecture.
- US state-level sugar taxation:Front-of-package warning label proposals in California and New York create competitive openings for zero-sugar functional alternatives. Reformulation investments now anticipate rather than react to these thresholds.
Industry Challenges
- Clinical study design complexity:FDA substantiation requirements for structure-function claims demand placebo-controlled trials with biomarker endpoints. Recruitment timelines for gut microbiome intervention studies extend development cycles.
- Flavor-mask engineering:Prebiotic fibers and botanical extracts introduce off-notes that require sophisticated encapsulation or bitter-blocking technologies. Sensory panels must validate acceptability across demographic cohorts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Soda Market |
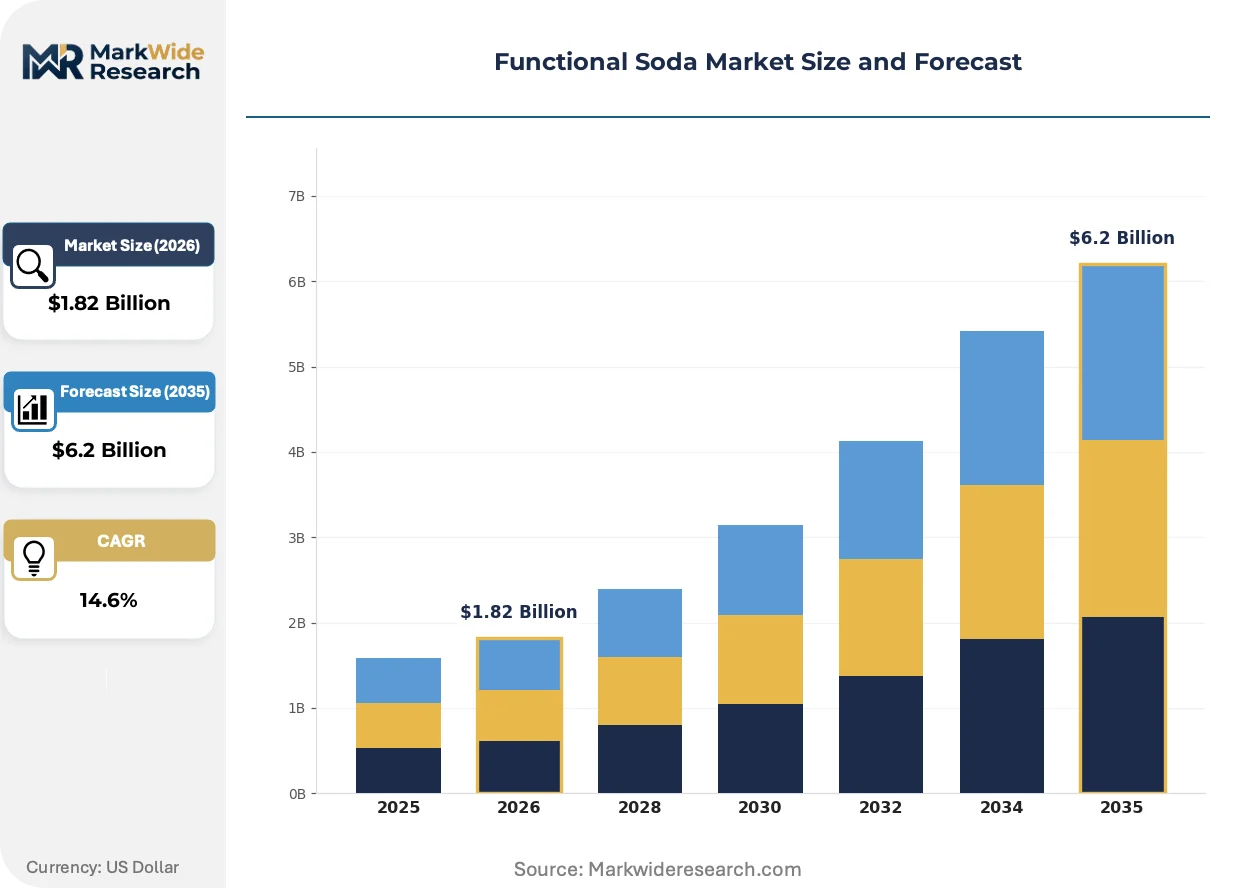
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $6.2 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prebiotic, Electrolyte, Protein, Herbal End User: Health Enthusiasts, Athletes, Busy Professionals, Families Distribution Channel: Supermarkets, Health Food Stores, E-commerce, Convenience Stores Flavor Profile: Berry, Citrus, Tropical, Spicy |
| Companies Covered | Olipop, Poppi, Culture Pop, De La Calle, XOXO, PepsiCo, Coca-Cola, Keurig Dr Pepper, Suntory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Soda Market Trends and Innovations
Formulation science and distribution architecture are converging to redefine how functional benefits reach consumers, with cold-chain logistics and bioactive preservation technologies enabling new product formats.
Microencapsulation technology is unifying probiotic stability with extended shelf-life requirements. Beverage manufacturers in the United States and Germany are adopting lipid-based or alginate-shell delivery systems at accelerating rates. This convergence is compressing the viability gap between refrigerated and ambient distribution channels.
EFSA's evolving guidance on prebiotic health claims is tightening evidentiary standards for gut microbiome marketing. The regulation forces reformulation investments toward specific fiber types with established fermentation profiles. German and French operators face the steepest compliance curves given their reliance on legacy botanical positioning.
Discovery-driven purchasing is displacing habitual brand loyalty in functional beverage categories. Health food stores and specialized e-commerce platforms are capturing trial occasions that supermarkets previously dominated. This behavioral shift concentrates in urban centers across the United States and Japan where education-intensive shopping missions prevail.
Functional Soda Market Segmentation
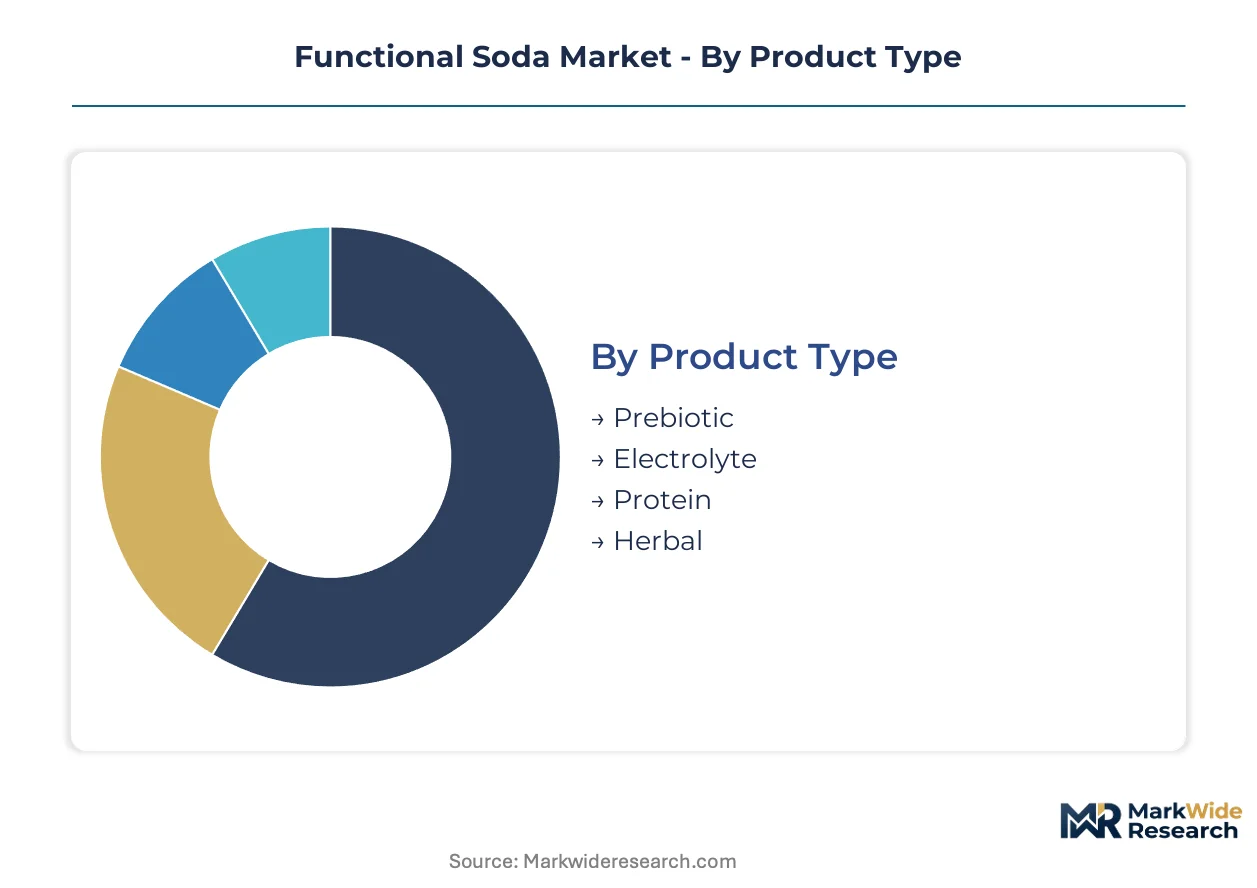
Segmentation in functional soda markets reveals how regulatory burden, distribution economics, and sensory preference intersect to determine viable product-market fit. Each dimension carries distinct compliance thresholds and margin architecture that shape competitive positioning.
Product Type:
FDA structure-function claims and EFSA health claim substantiation protocols impose tiered evidentiary requirements across formulation categories, with digestive and metabolic benefit assertions demanding the most rigorous clinical portfolios.
- Prebiotic:Formulations incorporating inulin, chicory root fiber, or resistant dextrin require cold-fill aseptic processing to preserve volatile fermentation substrates. Demand concentrates among health enthusiasts in Germany and the United States where gut microbiome awareness drives premium willingness-to-pay despite refrigeration infrastructure constraints.
- Electrolyte:Sodium, potassium, and magnesium fortification targets post-workout recovery and daily hydration optimization with ambient-stable formulations. Athletes and busy professionals in Japan and the United States adopt these as functional alternatives to conventional sports drinks, bypassing cold-chain limitations that constrain probiotic formats.
- Protein:Plant-derived protein isolates from pea or rice sources serve meal-replacement occasions with higher viscosity profiles requiring specialized carbonation techniques.
- Herbal:Botanical extracts including adaptogens and nootropics face varying regulatory classification across jurisdictions, with some jurisdictions treating certain botanicals as novel food ingredients requiring pre-market approval.
Leading the category by volume: Prebiotic. Growing fastest: Electrolyte.
End User:
Customer archetypes diverge sharply in purchase frequency, channel preference, and price sensitivity, with subscription economics favoring high-engagement segments over transactional household buyers.
- Health Enthusiasts:Early adopters with above-average category knowledge who drive trial velocity through health food store and direct-to-consumer channels. These consumers validate ingredient provenance claims and sustain premium pricing through education-intensive shopping missions concentrated in coastal United States metropolitan corridors.
- Athletes:Performance-oriented buyers seeking electrolyte replenishment and recovery optimization with format preferences shaped by training schedules and portability requirements. Demand clusters around fitness-dense urban centers in Germany and Japan where functional beverage culture has mature retail infrastructure.
- Busy Professionals:Convenience-driven purchasers prioritizing grab-and-go availability and cognitive performance positioning over deep ingredient scrutiny.
- Families:Volume buyers seeking healthier alternatives to conventional sodas for household consumption, exhibiting higher price elasticity and supermarket channel preference.
Highest engagement by subscription metrics: Health Enthusiasts. Steepest expansion trajectory: Athletes.
Distribution Channel:
Channel economics determine which formulation types achieve viable unit economics, with slotting fees and refrigeration requirements filtering product-market fit.
- Supermarkets:Mass-market reach with high slotting-fee barriers that favor established brands with scale economics. These channels prioritize ambient-stable formats with extended shelf life, limiting probiotic and fresh-pressed botanical introductions.
- Health Food Stores:Discovery-oriented environments where education-intensive shopping missions support premium positioning and ingredient transparency claims. Staff recommendation dynamics and sampling programs accelerate trial for emerging brands with clinical substantiation.
- E-commerce:Direct-to-consumer models bypass slotting fees and enable personalized subscription architectures with microbiome-based flavor profiling as an emerging loyalty mechanism.
- Convenience Stores:Impulse-driven velocity favoring single-serve formats with immediate consumption cues and minimal refrigeration dependency.
Deepest margin pool: Health Food Stores. Gaining share fastest: E-commerce.
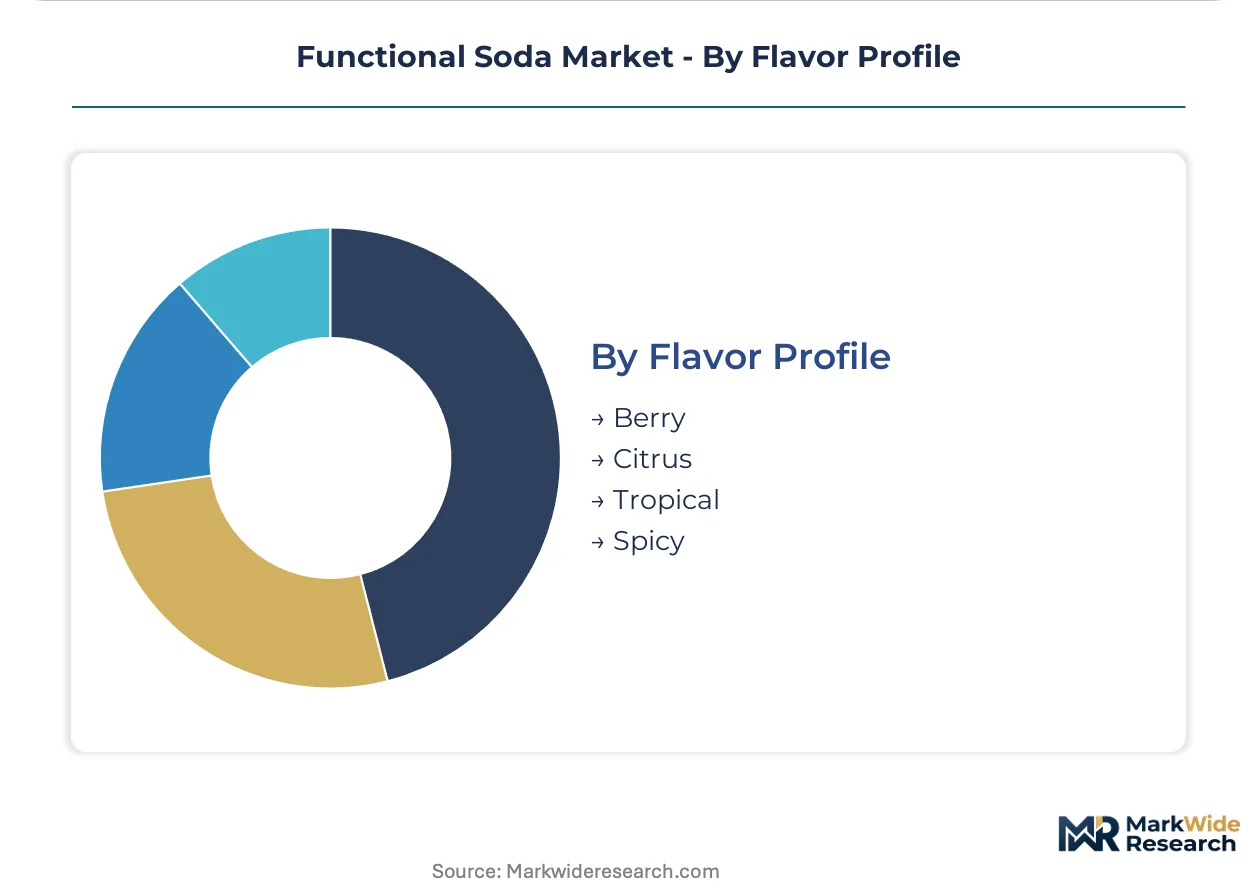
Flavor Profile:
Sensory engineering requirements vary by flavor family, with botanical off-notes and fiber-induced texture challenges demanding differentiated masking technologies.
- Berry:Anthocyanin-rich formulations from blueberry, acai, or elderberry sources carry color stability challenges under light exposure but enjoy broad demographic acceptance. These profiles dominate prebiotic applications where fermentation-associated off-notes require robust flavor masking.
- Citrus:Natural acidity from lemon, lime, or yuzu provides inherent preservation benefits and compatibility with electrolyte mineral fortification without excessive bitter-blocking investment.
- Tropical:Mango, pineapple, and passionfruit profiles target younger demographics with higher sweetness expectations, requiring careful stevia or monk fruit calibration to maintain clean-label positioning.
- Spicy:Ginger, turmeric, and chili-infused variants occupy niche positioning with functional ingredient overlap but limited mainstream acceptance due to polarizing sensory profiles.
Widest formulation application: Citrus. Most challenging technical profile: Spicy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stevia and monk fruit plantations in Southeast Asian highlands supply natural sweetener feedstock that anchors functional soda formulation economics across major consumption markets.
United States
Health-conscious millennials in coastal metropolitan corridors drive prebiotic and electrolyte adoption through health food stores and direct-to-consumer channels. FDA structure-function claim requirements shape permissible marketing language around digestive benefits. Brooklyn and Austin clusters host emerging brand incubators that leverage microbiome-testing personalization for subscription retention.
Germany
Gut microbiome awareness among fitness-oriented consumers pulls functional formulations into mainstream beverage repertoires with above-average premium willingness-to-pay. EFSA health claim substantiation protocols demand rigorous clinical evidence portfolios for digestive benefit assertions. Berlin and Munich retail ecosystems concentrate cold-chain infrastructure that supports probiotic viability requirements.
Japan
Mature functional beverage culture provides electrolyte fortification templates now adapted for Western export markets with ambient-stable formulations. METI guidelines on food-with-function-claims create precedent for evidence-based positioning that influences global regulatory discourse. Tokyo and Osaka metropolitan areas sustain the highest per-capita consumption density for cognitive performance and recovery-oriented products.
United Kingdom
Clean-label preferences among urban professionals accelerate zero-sugar alternative adoption ahead of potential front-of-package warning label implementations. Competition and Markets Authority scrutiny of health claims parallels EFSA evidentiary standards. London health food retail clusters and Manchester-based direct-to-consumer fulfillment centers anchor distribution architecture for emerging brands.
Canada
Cross-border formulation trends from the United States penetrate Canadian markets with adapted labeling for Health Canada natural health product regulations. Provincial extended producer responsibility laws in British Columbia and Ontario accelerate aluminum can and recycled PET transitions. Toronto and Vancouver metropolitan areas concentrate refrigerated distribution density for probiotic formats.
Functional Soda Market Competitive Landscape
Global majors compete with regional champions across distribution infrastructure and formulation credibility, creating a tiered structure where scale advantages clash with agility premiums. The vendor base separates into multinational beverage conglomerates with captive retail networks, vertically integrated digestive health specialists, and fruit-forward flavor innovators with clinical positioning. Dominant competitive moves include incubator-style portfolio management through strategic partnerships and cold-chain infrastructure investments that expand addressable retail occasions.
Within the vertically integrated digestive health tier, Olipop anchors premium prebiotic positioning through captive research infrastructure. Poppi exemplifies the fruit-forward flavor innovation archetype with clinically backed ingredient claims. Coca-Cola occupies the scale-driven conglomerate position, extending distribution reach through functional sub-brand incubation. These three represent distinct strategic vectors—formulation depth, sensory differentiation, and channel density—that define competitive intensity across consumption occasions.
| Leading Market Players |
|---|
| Olipop |
| Poppi |
| Culture Pop |
| De La Calle |
| XOXO |
| PepsiCo |
| Coca-Cola |
| Keurig Dr Pepper |
| Suntory |
| Others |
Pricing and Supply Chain Analysis
Private-equity-backed functional soda specialists have consolidated regional bottling networks across the United States and Germany, tightening procurement discipline while extracting pricing power through captive cold-chain infrastructure investments that smaller operators cannot replicate.
Pricing Analysis
Warranty and service bundling remains largely unbundled in functional soda, with clinical substantiation and microbiome-testing personalization treated as premium add-ons rather than standard inclusions. Three-tier pricing structure across premium, standard, and economy levels separates clinically validated prebiotic formulations from basic electrolyte fortification and private-label alternatives. Price differentiation hinges on certification tier—EFSA-approved health claims command substantial premiums over FDA structure-function positioning—and vertical integration into captive research infrastructure. Cost compression in the standard tier is intensifying because multi-source sweetener procurement has eroded brand loyalty. Health enthusiasts exhibit the lowest price sensitivity, while family household buyers demonstrate steep elasticity that forces promotional intensity in supermarket channels.
Supply Chain Analysis
Domestic-content mandates under the EU Green Deal and emerging US state-level extended producer responsibility laws are reshaping sourcing toward regional aluminum smelters and recycled PET converters. Supply concentrates in Thailand and Vietnam for stevia and monk fruit extraction, with secondary processing hubs in the United States and Germany for flavor encapsulation and aseptic filling. Raw material dependencies center on Southeast Asian natural sweetener harvests, chicory root fiber from Belgian and French agricultural cooperatives, and electrolyte mineral salts from Chilean and Australian extraction operations. Single-source vulnerability in Southeast Asian sweetener supply creates exposure to climate-driven harvest variability. Distribution runs through refrigerated third-party logistics networks concentrated in coastal metropolitan corridors, with ambient-stable electrolyte formats bypassing cold-chain limitations through conventional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional soda markets are transitioning from probiotic viability constraints toward microencapsulation-enabled ambient distribution, with lipid-shell and alginate-based preservation technologies displacing legacy refrigerated-only formats across the value chain.
For Market Incumbents: To counter private-label erosion in standard-tier electrolyte segments, incumbents should deepen backward integration into captive prebiotic fiber processing and secure multi-year offtake agreements with Southeast Asian sweetener plantation networks. Cold-chain infrastructure expansion into secondary metropolitan corridors protects premium positioning against ambient-format challengers. For New Entrants and Emerging Players: Enter via cognitive performance positioning with nootropic botanical extracts, the most penetrable white space adjacent to saturated gut-health claims. Target health food store discovery channels with adaptogen combinations from traditional Chinese medicine pharmacopeia, leveraging staff recommendation dynamics and sampling programs to bypass slotting-fee barriers that supermarket distribution imposes. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated digestive health specialists with captive research infrastructure in Germany and the United States, where EFSA and FDA compliance burdens have compressed valuations for clinical-substantiation-deficient operators. Long-term viability centers on microbiome-testing personalization platforms that create recurring revenue architecture. Watch for inflection signals in California and New York state-level sugar taxation implementations that would reclassify competitive positioning for zero-sugar alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Adoption | Lipid-shell delivery systems preserve probiotic viability through ambient distribution channels. |
| Direct-to-Consumer Subscription Launch | Microbiome-based flavor profiling creates recurring revenue architecture bypassing slotting fees. |
| Clinical Substantiation Investment | EFSA-approved health claims command premium pricing over basic FDA structure-function positioning. |
| Sustainable Packaging Transition | Aluminum can and recycled PET formats align with EU Green Deal extended producer responsibility mandates. |
| Nootropic Botanical Line Extension | Adaptogen combinations from traditional Chinese medicine pharmacopeia target underdeveloped cognitive performance positioning. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with functional beverage brand managers, category buyers at health food retailers, cold-chain logistics operators, and clinical research directors at prebiotic fiber suppliers. FDA structure-function claim databases, EFSA health claim substantiation registers, and EU Green Deal packaging directive implementation reports provided regulatory validation. Bottom-up volume modeling across formulation types triangulated against top-down category spend estimates from Nielsen retail audit data and direct-to-consumer subscription platform disclosures.
Granularity-level modeling operated at the intersection of product type, distribution channel, and end-user archetype, with separate treatment of refrigerated versus ambient supply chain economics across the projection horizon. CAGRs were derived from segment-level growth rate convergence analysis incorporating price elasticity differentials between health enthusiast and family household buyer segments. Forecast inputs included stevia and monk fruit harvest variability indices, cold-chain infrastructure density metrics by metropolitan corridor, and regulatory implementation timelines for front-of-package warning label proposals.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated sugar taxation implementations or sustained Southeast Asian sweetener supply disruptions. Forecasts reflect documented assumptions regarding EFSA health claim approval timelines, microbiome-testing technology adoption curves, and aluminum can recycling rate improvements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
Europe Functional Water Market
Functional Food and Beverage
Low-Fat and Low Protein Diet Market
Functional Food and Beverage
Vegan Protein Bars Market
Functional Food and Beverage
Vegan Brain Food Market
Functional Food and Beverage
Spain Probiotic Drinks Market
Functional Food and Beverage
Global Functional Proteins Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Botanical Infusions Market
Functional Food and Beverage
Grape Skin–Carob Synergy Antioxidant Systems Market
Functional Food and Beverage
Tobacco Alternative Gum Market
Functional Food and Beverage
Saudi Arabia Protein Bar Market
Functional Food and Beverage
Europe Health Drinks Market
Functional Food and Beverage
Middle East and Africa Protein Bar Market