
 Europe Confectionery Market | 2026-2036
Europe Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Confectionery Market Foresight
Buyer concentration among European supermarket chains is hardening, pressuring confectionery suppliers to secure shelf space through long-term listings and promotional commitments. Ferrero Group leverages its vertically integrated hazelnut supply to sustain margin control across premium chocolate lines. Mondelēz International anchors its position through scale manufacturing in Bournville and Toblerone facilities, while Haribo GmbH & Co. KG differentiates via specialized gummy texture formulations that dominate the sugar confectionery aisle.
Europe confectionery comprises sugar-based and cocoa-based products formulated through conching, tempering, or starch molding processes, with specifications typically requiring cocoa butter content above 20 percent for chocolate classification and moisture below 3 percent for shelf-stable hard candies. Chocolate occupies the largest value pool due to raw material premiums and gifting rituals, while gummies register the fastest structural expansion driven by adult-oriented functional and sour flavor extensions. Health-conscious consumers represent an emerging segment force, with sugar-free and natural-flavor variants capturing disproportionate innovation investment from established manufacturers.
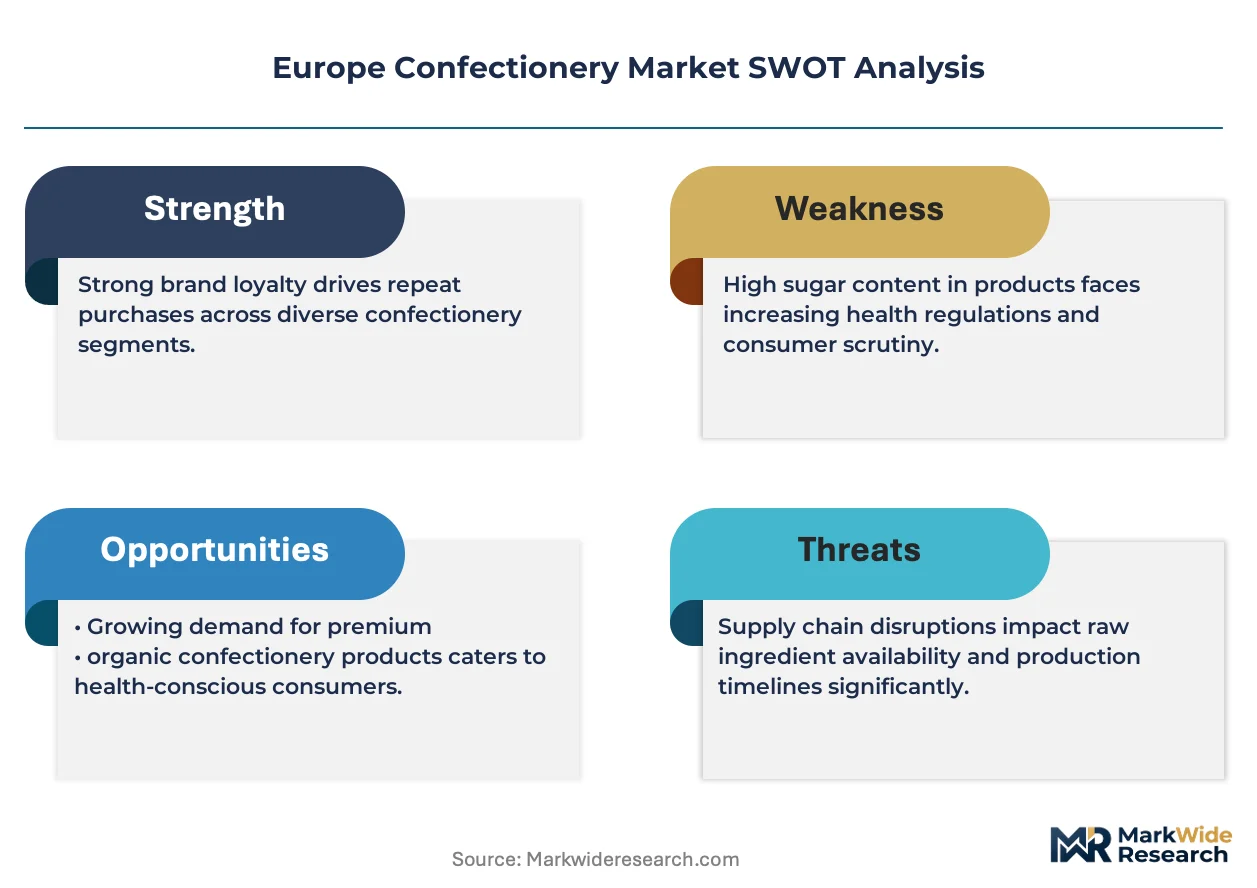
EFSA nutrition claims regulation and EU Green Deal farm-to-fork targets constrain permitted sugar levels and mandate clearer front-of-pack labeling, directly shaping new product development cycles across the continent. REACH chemical safety standards and ECHA food contact material rules further govern packaging substrates and additive approvals, raising compliance costs for cross-border suppliers. Stakeholders must monitor evolving EU-wide sugar tax harmonization proposals and decide whether to front-run reformulation investments or absorb margin compression from delayed adaptation.
Market Dynamics
EFSA sugar-reduction mandates and EU Green Deal farm-to-fork targets are forcing wholesale reformulation across European confectionery portfolios, compressing margins while opening premium positioning for compliant innovators.
Growth Catalysts
- EU Green Deal labeling rules:Front-of-pack nutritional scoring systems are accelerating clean-label product launches as manufacturers race for shelf space in German and French retail chains.
- Adult functional gummy expansion:Vitamin-infused and adaptogen-enriched formats are capturing new consumption occasions beyond traditional children's segments.
- Belgian and Swiss cocoa processing clusters:Concentrated bean-to-bar infrastructure in these geographies sustains supply security for heritage chocolate brands.
Market Restraints
- Cocoa butter price volatility:Weather-driven supply disruptions in West African growing regions transmit directly to European chocolate manufacturers' input cost structures.
- REACH compliance burdens:ECHA food contact material rules for packaging substrates raise qualification costs and extend new product introduction timelines.
- Plant-based fat substitution limitations:Technical barriers to replicating cocoa butter's crystallization behavior constrain clean-label reformulation depth.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania present whitespace for premium chocolate distribution expansion as disposable incomes converge with Western European levels.
- Sugar tax harmonization tailwinds:Proposed EU-wide fiscal measures would level the competitive playing field and reward early reformulation investments.
- Direct-to-consumer subscription channels:Curated gifting boxes bypass concentrated retail gatekeepers and capture higher margin per unit.
Industry Challenges
- Confectionery technologist scarcity:Specialized expertise in starch molding and tempering process control is retiring faster than training pipelines replenish.
- Clean-label certification timelines:Organic and Fairtrade verification processes extend launch schedules by 12-18 months.
- Legacy ERP integration friction:Reformulation tracking systems struggle to interface with modern traceability platforms demanded by EU Green Deal transparency rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Confectionery Market |
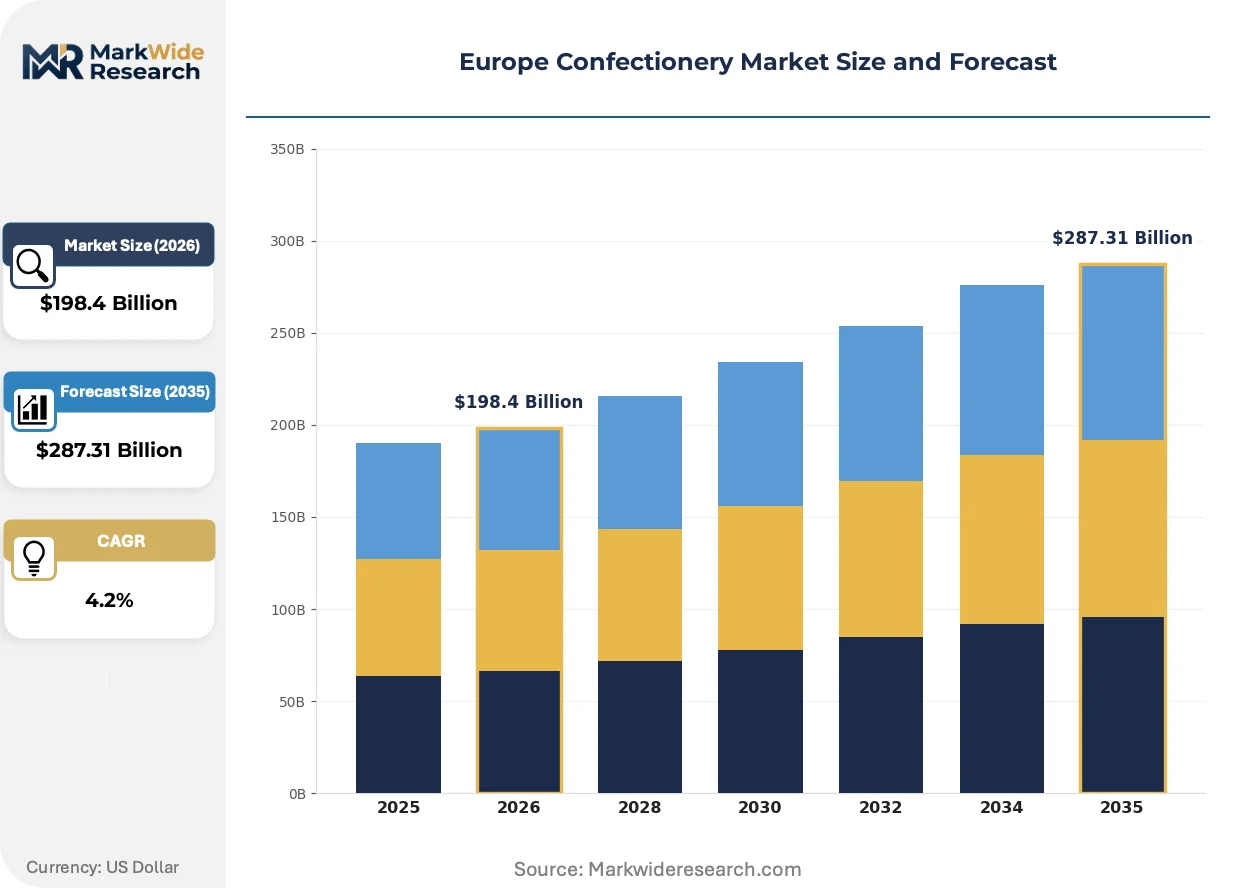
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $287.31 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Gummies, Hard Candy, Lollipops Consumer Segment: Children, Adults, Premium Buyers, Health-Conscious Consumers Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Convenience Stores Ingredients: Sugar, Cocoa, Gelatin, Natural Flavors |
| Companies Covered | Nestlé SA, Haribo GmbH & Co. KG, Ferrero Group, August Storck, Perfetti Van Melle, Mars Incorporated, Chocoladefabriken Lindt & Sprüngli AG, Cloetta AB, Mondelēz International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Confectionery Market Shifts & Advancements
European confectionery is pivoting toward precision fermentation and upcycled ingredients as regulatory pressure and consumer scrutiny converge on supply chain transparency.
Precision fermentation-derived cocoa butter alternatives are electrifying premium chocolate formulation pipelines. Mid-tier manufacturers in the Netherlands and Denmark are piloting these lipids at commercial scale. The technology is electrifying cost structures for bean-to-bar entrants previously locked out by commodity cocoa futures volatility.
EFSA nutrition claims regulation revisions are tightening permissible health assertions on confectionery packaging. Manufacturers must now substantiate gut health and immunity benefits through clinical trials rather than ingredient association. Sugar-free hard candy segments in Germany face the steepest reformulation burden as existing portfolios lose compliant label status.
Corporate gifting procurement is consolidating through centralized platform contracts rather than decentralized regional buying. Foodservice distributors are losing share to specialized B2B confectionery curators with customization capabilities. This pattern is most pronounced in London and Paris financial services verticals where ESG reporting requirements favor traceable supply chains.
Europe Confectionery Market Segmentation
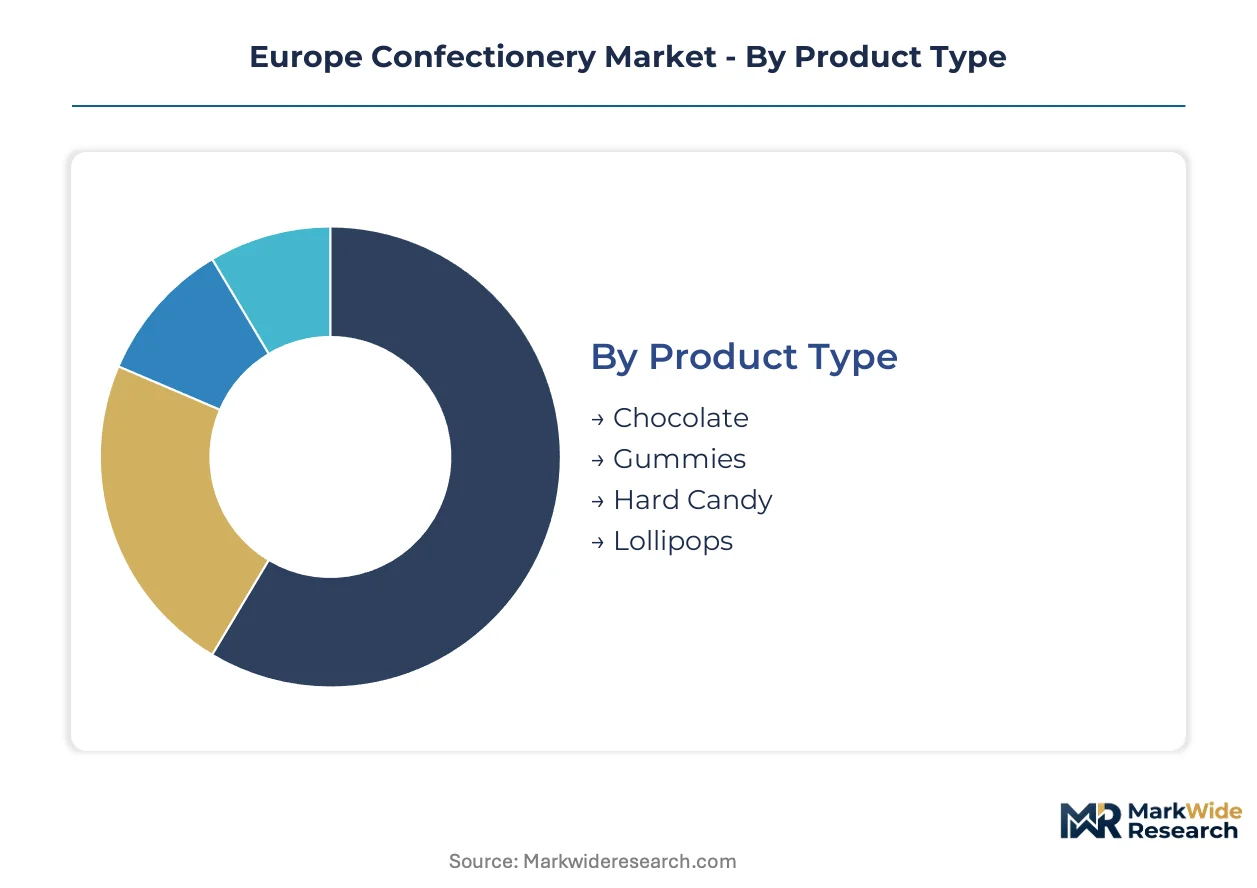
Segmentation in European confectionery reveals how regulatory pressure and consumption rituals split value pools across distinct technical and commercial boundaries. Manufacturers must align formulation investments with channel-specific margin structures while navigating EFSA compliance tiers that vary by product category.
Product Type:
Standalone chocolate formats operate as finished goods for direct consumption, while gummies and hard candies embed functional ingredients into matrix-delivery systems for targeted release profiles.
- Chocolate:Cocoa butter content above 20 percent defines legal classification under EU standards, with conching duration determining texture premiums. German and Swiss heritage brands concentrate demand here, though EFSA sugar-reduction timelines are compressing permissible formulations and forcing rapid clean-label transitions.
- Gummies:Starch-molded or deposited gelatin matrices enable vitamin infusion and adaptogen delivery beyond traditional confectionery occasions. Adult functional extensions in the Netherlands and Denmark are climbing the fastest as precision fermentation reduces input cost volatility for mid-tier entrants.
- Hard Candy:Glass-phase sugar matrices with moisture below 3 percent ensure shelf stability across extended distribution cycles. Sugar-free variants face steep reformulation burdens under evolving nutrition claim rules.
- Lollipops:Amorphous sugar structures on stick formats target children's segments with extended consumption duration. Belgian and French manufacturers dominate heritage positioning in this niche.
Chocolate leads volumes today; gummies are gaining share fastest.
Consumer Segment:
Premium buyers and health-conscious consumers concentrate in Northwestern European urban centers where disposable income and regulatory awareness intersect most sharply.
- Children:Traditional sugar confectionery occasions anchored by seasonal gifting rituals and parental purchase decisions. German retail chains maintain the deepest promotional calendars targeting this demographic.
- Adults:Functional and sour flavor extensions capture new consumption moments beyond legacy children's positioning. Swiss and Belgian bean-to-bar curators concentrate demand here.
- Premium Buyers:Gifting-oriented purchasers prioritizing traceable supply chains and heritage provenance for corporate procurement. London and Paris financial services verticals show the steepest platform consolidation.
- Health-Conscious Consumers:Sugar-free and natural-flavor variant adopters driving disproportionate innovation investment from established manufacturers. EFSA front-of-pack labeling rules accelerate their decision criteria.
Adult segments dominate value capture; health-conscious consumers show the steepest expansion trajectory.
Distribution Channel:
Channel concentration determines margin structure, with supermarket gatekeepers extracting promotional commitments that specialty and direct channels bypass.
- Supermarkets:Concentrated buyer power across German and French retail chains demands long-term listing agreements and shelf-space fees. Ferrero and Mondelēz anchor positions through scale manufacturing commitments.
- Specialty Stores:Curated bean-to-bar and heritage brand exposure with higher margin per unit but limited geographic reach. Swiss and Belgian cocoa processing clusters supply this tier preferentially.
- Online Retailers:Subscription gifting boxes bypass retail gatekeepers and capture ESG-compliant procurement from corporate buyers. Haribo texture differentiation translates poorly to this channel.
- Convenience Stores:Impulse-oriented single-serve formats with compressed margin structures and localized inventory turnover. Eastern European expansion targets this channel for premium chocolate whitespace.
Supermarkets command volume leadership; online retailers expand most quickly.
Ingredients:
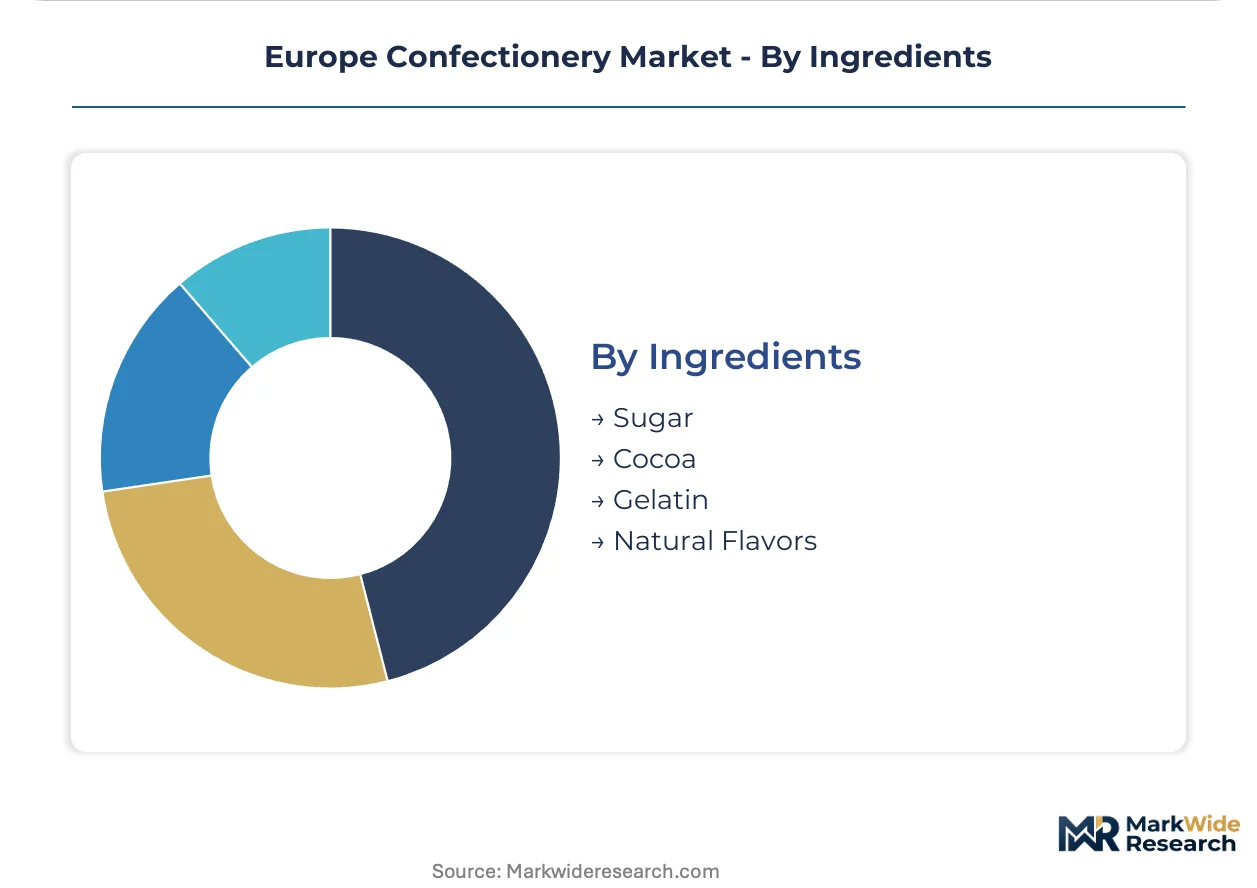
Raw material specifications determine regulatory compliance tier and clean-label certification eligibility across European portfolios.
- Sugar:Primary caloric and structural contributor facing maximum pressure from EU Green Deal farm-to-fork reduction targets. German hard candy portfolios face the steepest reformulation timelines.
- Cocoa:Butter and liquor fractions defining chocolate legal status and premium positioning. West African supply disruptions transmit directly to European manufacturer cost structures.
- Gelatin:Protein gelling agent enabling gummy texture profiles with bovine or porcine sourcing options. ECHA REACH compliance raises qualification costs for cross-border suppliers.
- Natural Flavors:Clean-label alternatives to synthetic additives requiring 12-18 month organic verification timelines. Danish and Dutch precision fermentation pilots reduce dependency on commodity extraction.
Cocoa anchors value concentration; natural flavors climb fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the largest confectionery consumption base in Europe, while Switzerland concentrates the highest per-capita chocolate expenditure. The regional landscape fragments between volume-driven Northern markets and premium-oriented Alpine clusters. EFSA regulatory harmonization is compressing formulation variance across national borders.
Germany
Supermarket chain concentration drives supplier dependence on promotional calendars and long-term listing agreements. The country's sugar tax debates under EU Green Deal farm-to-fork targets are accelerating reformulation timelines for hard candy portfolios. Cologne and Hamburg anchor distribution infrastructure for pan-European logistics.
Switzerland
Heritage bean-to-bar infrastructure sustains premium positioning among adult gifting segments. Swissmedic food safety standards and EFSA front-of-pack labeling rules constrain permitted health claims on functional chocolate variants. Zurich and Geneva clusters concentrate cocoa processing technology and corporate procurement platforms.
Belgium
Confectionery technologist expertise in starch molding and tempering processes supports specialized gummy and praline production. REACH compliance for food contact materials raises packaging qualification costs for cross-border suppliers. Brussels and Liège processing facilities supply heritage brands across European duty-free channels.
United Kingdom
Corporate gifting procurement consolidation favors traceable supply chains meeting ESG reporting requirements. The country's divergence from EU labeling harmonization creates dual-compliance burdens for manufacturers serving both markets. London financial services verticals drive platform-based B2B confectionery curation.
Netherlands
Precision fermentation pilots for cocoa butter alternatives are reducing input cost volatility for mid-tier chocolate entrants. ECHA chemical safety standards govern additive approvals and packaging substrate selection. Amsterdam and Rotterdam logistics hubs facilitate bean-to-bar distribution across Northwestern Europe.
Europe Confectionery Market Competitive Landscape
Swiss and Belgian producers anchor the premium heritage tier; German and Italian specialists hold volume manufacturing positions. The vendor base stratifies across three structural layers: multinational scale manufacturers, mid-tier regional brands, and artisanal bean-to-bar curators. Dominant competitive moves include backward integration into hazelnut and cocoa supply chains, plus direct-to-consumer subscription channel development bypassing retail gatekeepers.
Within the multinational scale tier, Mondelēz International and Nestlé SA exemplify manufacturing concentration across Bournville and continental European facilities. Ferrero Group represents upstream control strategies through captive hazelnut supply. These three anchors occupy positions shaped by EFSA compliance investments and EU Green Deal transparency requirements.
| Leading Market Players |
|---|
| Nestlé SA |
| Haribo GmbH & Co. KG |
| Ferrero Group |
| August Storck |
| Perfetti Van Melle |
| Mars Incorporated |
| Chocoladefabriken Lindt & Sprüngli AG |
| Cloetta AB |
| Mondelēz International |
| Others |
Supply & Pricing Matrix
EU Green Deal farm-to-fork targets gate qualified supply and premium-tier pricing access by mandating sugar-reduction compliance and front-of-pack transparency before manufacturers can secure shelf space in German and French retail chains. EFSA nutrition claims regulation creates a bifurcated market where reformulation investments translate directly into pricing power or margin compression.
Pricing Analysis
Capacity additions in Eastern European processing facilities are reshaping price floors for standard-tier chocolate and gummy segments. Three-tier pricing structure across premium, standard, and economy levels differentiates by cocoa butter content and clean-label certification status. Price differentiation stems from EFSA compliance tier and heritage brand provenance. Cost compression in sugar confectionery is intensifying because German hard candy portfolios face steep reformulation timelines. Health-conscious consumers in Swiss and Belgian urban centers show least price sensitivity, while Eastern European convenience channel buyers remain most responsive to promotional discounting.
Supply Chain Analysis
Freight cost volatility from West African cocoa ports to Antwerp and Rotterdam processing hubs is compressing margins for bean-to-bar entrants lacking long-term offtake agreements. Supply concentrates in Côte d'Ivoire, Ghana, and Cameroon for cocoa beans, with Germany, Switzerland, and Belgium hosting downstream conching and tempering infrastructure. Raw material portfolios draw from cocoa butter, hazelnut paste, and precision fermentation-derived lipid alternatives. Single-source vulnerability in West African growing regions exposes European manufacturers to weather-driven supply disruptions. Distribution runs through centralized supermarket procurement platforms in Germany and France, with specialty stores and direct-to-consumer subscription channels capturing higher-margin gifting occasions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe confectionery operates as a stable compounder where regulatory harmonization under EFSA and EU Green Deal mandates drives steady portfolio reformulation and premium-tier growth.
For Market Incumbents: Deploy backward integration into hazelnut and cocoa supply chains to defend margin control against commodity price volatility. Anchor shelf space through long-term listing agreements with German and French retail chains while accelerating clean-label certification timelines to outpace EFSA sugar-reduction mandates. Threats from precision fermentation entrants and sugar tax harmonization proposals demand preemptive reformulation investment. For New Entrants and Emerging Players: Capture whitespace in Polish and Romanian premium chocolate distribution as disposable incomes converge with Western European levels. Functional gummy segments in the Netherlands and Denmark offer the most penetrable entry point given adult-oriented vitamin and adaptogen demand expansion. A direct-to-consumer subscription go-to-market angle bypasses concentrated retail gatekeepers and captures ESG-compliant corporate procurement. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier regional brands with heritage positioning because EFSA compliance costs are driving consolidation among sub-scale players unable to absorb certification timelines. Long-term viability frames around 5-10 year holding periods as sugar tax harmonization and front-of-pack labeling rules reshape competitive dynamics. Acquisition targets should show bean-to-bar infrastructure or specialized gummy texture capabilities. Watch for EU-wide sugar tax legislation as the inflection signal for reformulation-leader premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hazelnut Supply | Ferrero Group's captive Turkish hazelnut orchards insulate margin control against commodity volatility. |
| Precision Fermentation Scale-Up | Dutch and Danish pilots reduce cocoa butter dependency and unlock premium positioning for mid-tier entrants. |
| Direct-to-Consumer Subscription Launch | Curated gifting boxes capture ESG-compliant corporate procurement from London financial services verticals. |
| Clean-Label Certification Investment | Organic and Fairtrade verification extends launch timelines but secures shelf space in German retail chains. |
| Eastern European Distribution Expansion | Poland and Romania convenience channel penetration captures premium chocolate whitespace as incomes converge. |
Research Methodology
Bottom-up confectionery consumption modeling reconciled against top-down cocoa processing capacity tracking forms the analytical core of this study. Primary interviews with brand managers at heritage chocolate houses, category buyers at German and French supermarket chains, supply planners at hazelnut processing cooperatives, and regulatory affairs leads navigating EFSA compliance were cross-validated against secondary sources including EU customs records, EFSA nutrition claim filings, and SEC 10-K disclosures from listed confectionery manufacturers. This dual approach ensures demand-side validation against supply-side constraints.
Input-output matrices across product type, consumer segment, distribution channel, and ingredient sourcing tier drive the projection framework. Segmentation dimensions modeled include chocolate legal classification by cocoa butter content, functional gummy versus traditional confectionery positioning, supermarket versus specialty versus online channel mix, and clean-label certification status. CAGRs were derived through trend extrapolation against regulatory milestone timing and income convergence patterns in Eastern European markets. Cocoa futures volatility indices and EFSA reformulation timeline assumptions inform scenario-weighted outputs across the projection horizon.
Underlying measurement precision varies by segment; chocolate value pools carry tighter precision than emerging functional gummy categories where adoption curves remain less established. Forecasts reflect assumptions around EFSA enforcement consistency, EU sugar tax harmonization progression, and West African supply stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Macarons Market
Confectionery
Coffee Gummy Market
Confectionery
Functional Confectionery Market
Confectionery
Fruit Jellies Market
Confectionery
Chocolate Hazelnut Spread Market
Confectionery
UK Compound Chocolate Market
Confectionery
Sugar-Free Chocolate Market
Confectionery
Truffle Chocolate Market
Confectionery
Crunchy Chocolate Market
Confectionery
United States Chocolate Market
Confectionery
Asia Pacific Sugar Confectionery Market
Confectionery
UK Confectionery Market
Confectionery
Asia-Pacific Sugar Free Mints Market
Confectionery
Asia-Pacific Compound Chocolate Market
Confectionery
Sugar-Free Gumballs Market
Confectionery
Japan Chocolate Market