
 United States and Europe Macarons Market | 2026-2036
United States and Europe Macarons Market Size, Share, and Industry Trends Forecast 2026-2036
United States and Europe Macarons Market Analytics
The United States and Europe macarons category is pivoting on a widening gap between artisan-crafted premium tiers and machine-produced commodity lines, with the former commanding shelf space in flagship boutiques and the latter penetrating supermarket channels. Ladurée Paris leverages its heritage manufacturing methods and iconic retail presence to sustain price premiums across Paris, London, and New York flagships. Dana's Bakery competes through American flavor innovation, occupying a distinct niche with salted caramel and peanut butter varieties that diverge from classical French formulations.
Macarons are delicate meringue-based confections composed of almond flour, egg whites, and sugar, with ganache or buttercream filling; precise moisture control and macaronage technique determine shell texture and foot development, making production highly sensitive to ambient humidity and temperature. The vegan segment is expanding fastest as egg-white substitutes achieve structural parity, while classic variants still dominate value pools in European heritage markets. Specialty stores capture the highest margins per unit, though online channels are scaling volume through subscription gifting and corporate customization programs.
The U.S. FDA enforces allergen labeling and facility registration requirements that shape formulation choices and cross-contamination protocols for almond-based production. The EU's REACH framework and EFSA food additive evaluations constrain synthetic coloring use, pushing brands toward plant-derived alternatives. Stakeholders must monitor evolving clean-label expectations and dual-jurisdiction compliance costs as the transatlantic market matures.
Market Dynamics
The United States and Europe macarons market is bifurcating between heritage artisan production and automated manufacturing, with regulatory divergence on allergen labeling and synthetic additives forcing dual-track compliance investments across transatlantic supply chains.
Growth Catalysts
- EU REACH framework:Restrictions on synthetic food colorants accelerate plant-derived pigment adoption, creating premium positioning for clean-label formulations in French and German retail channels.
- Specialty coffee chains:Starbucks and independent roasters now merchandise macarons as signature pairings, expanding consumption occasions beyond traditional patisserie visits into daily ritual contexts.
- Vegan meringue substitutes:Aquafaba and potato protein technologies achieve structural parity with egg whites, unlocking allergen-free and plant-based segments previously excluded from the category.
Market Restraints
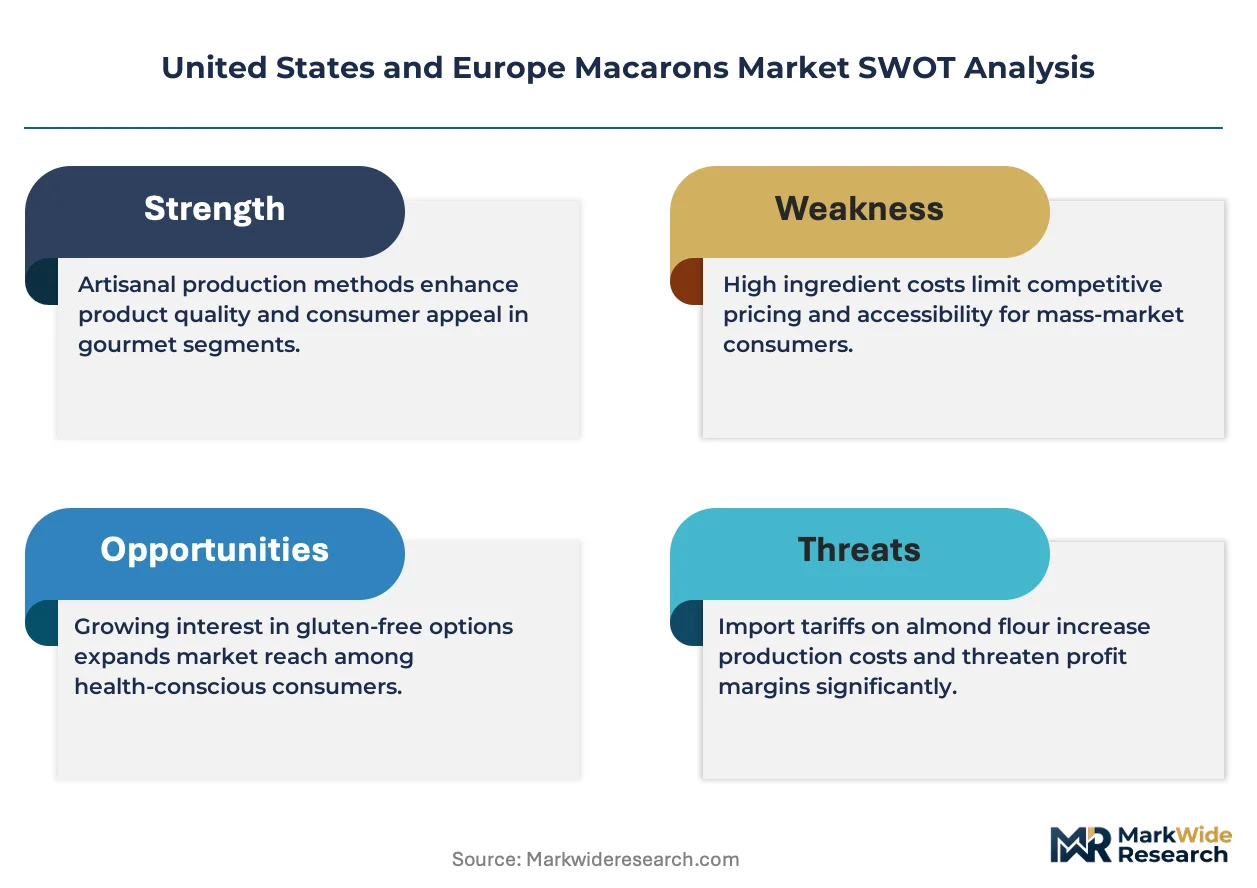
- Almond flour price volatility:California drought cycles and Mediterranean harvest variability compress margins for producers dependent on premium blanched almond supply.
- Humidity-controlled production:Precise ambient moisture requirements limit facility location flexibility and inflate real estate costs in high-humidity coastal markets.
- US FDA Food Safety Modernization Act:Preventive controls and facility registration mandates impose disproportionate compliance burdens on small-batch importers without domestic manufacturing presence.
Strategic Opportunities
- Eastern European retail penetration:Poland and Czech Republic markets show underdeveloped premium confectionery infrastructure relative to Western European saturation levels.
- Corporate customization programs:B2B channels for branded macaron assortments in hospitality and technology sectors remain nascent compared to established European corporate gifting norms.
- Subscription gifting platforms:Direct-to-consumer monthly delivery models bypass traditional retail slotting fees while capturing recurring revenue streams.
Industry Challenges
- Macaronage technique scarcity:Skilled pastry chefs capable of consistent shell development and foot formation command premium wages amid limited formal training pipeline expansion.
- Cross-contamination protocols:Almond-based production facilities face complex segregation requirements to serve nut-allergic consumer segments without dedicated plant investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States and Europe Macarons Market |
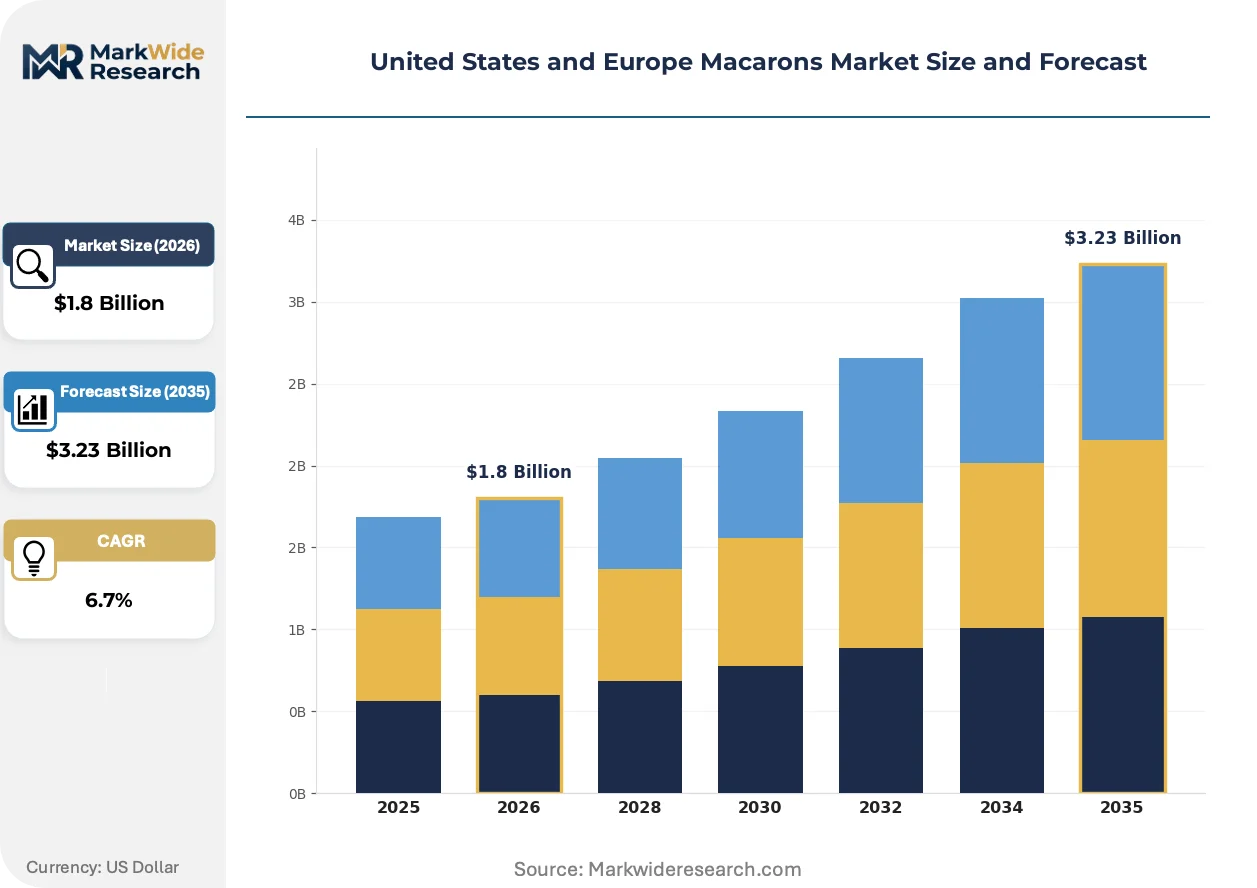
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Vegan, Gluten-Free, Filled Flavor Profile: Chocolate, Pistachio, Raspberry, Vanilla Distribution Channel: Online, Retail, Food Service, Specialty Stores Packaging Type: Boxed, Wrapped, Bulk, Gift Pack |
| Companies Covered | Ladurée Paris, Pierre Hermé Paris, Dana's Bakery, Chantal Guillon, Dalloyau, Jean-Paul Hévin, La Maison du Chocolat, Olivia Macaron, Richart, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States and Europe Macarons Market Evolving Landscape
Production technology and regulatory chemistry standards are converging to reshape formulation transparency and manufacturing scale economics across the transatlantic macarons category.
Precision humidity control systems are absorbing capital investment priority from traditional equipment upgrades. Automated climate chambers with real-time moisture sensing enable consistent macaronage in variable ambient conditions. Boutique producers in Paris and New York are adopting these systems to defend artisan positioning while reducing weather-dependent spoilage rates.
EFSA food additive evaluations are tightening permitted synthetic dye concentrations in EU-bound products. Manufacturers reformulate with spirulina, beetroot, and turmeric extracts to maintain visual differentiation. The shift compresses shelf-life stability and narrows color palettes, forcing design-led brands toward natural aesthetic positioning.
Corporate procurement departments now specify macaron assortments for client entertainment and employee recognition programs. Hospitality distributors and specialty food brokers are consolidating volume previously fragmented across individual retail purchases. This concentration is most visible in London and Manhattan, where financial and professional services firms maintain standing catering contracts.
United States and Europe Macarons Market Segmentation
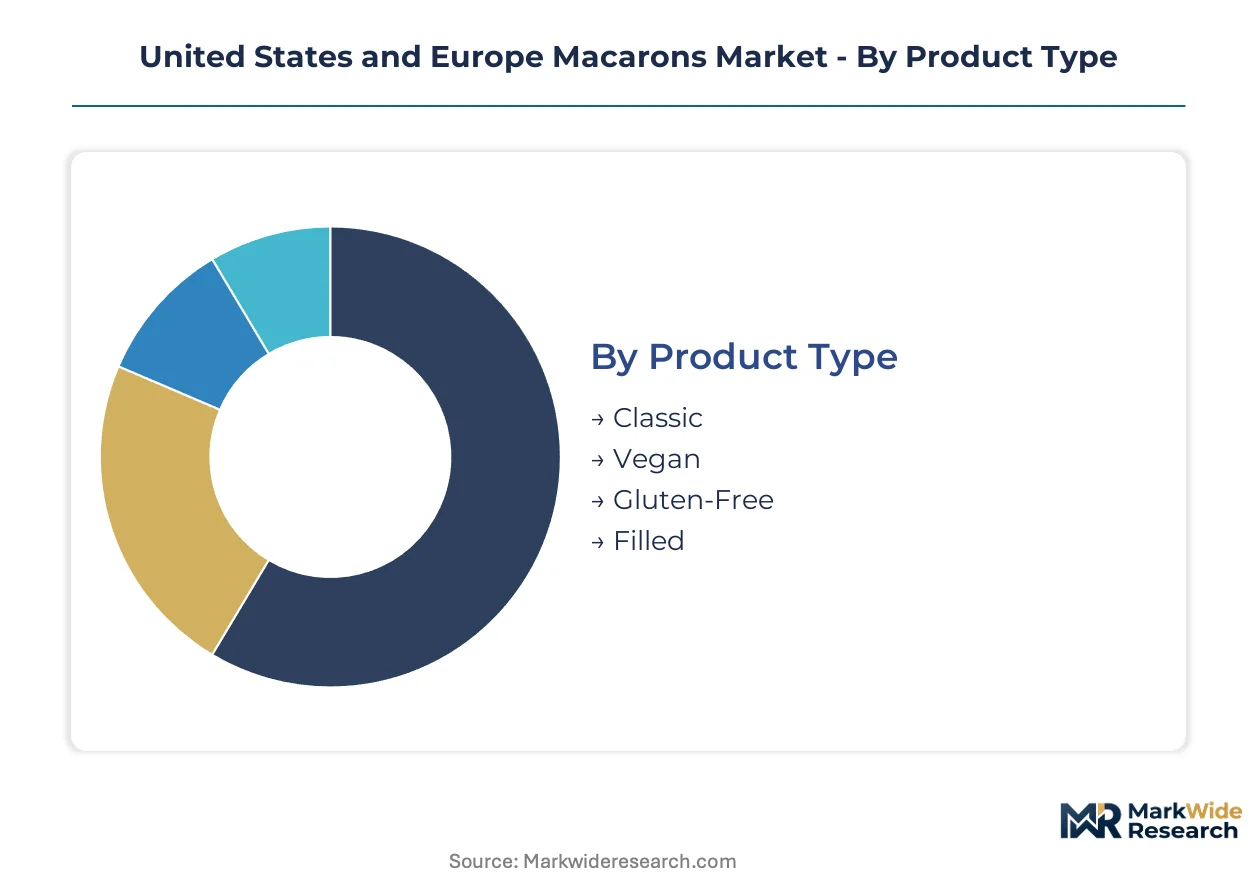
Macarons segmentation reveals how formulation choices, flavor positioning, and channel access create distinct compliance and margin profiles across the transatlantic market. Understanding these divides helps manufacturers allocate capital between heritage craft investments and scalable automation.
Product Type:
Classic formulations require only standard FDA facility registration and EU hygiene package compliance, while Vegan and Gluten-Free segments trigger additional allergen segregation audits and novel ingredient safety assessments under EFSA and FDA preventive controls frameworks.
- Classic:Traditional almond flour, egg white, and sugar meringue shells with buttercream or ganache fillings define the reference standard. Demand concentrates in Paris Île-de-France and New York metropolitan flagships where heritage positioning supports price premiums. French AOP almond sourcing and precise macaronage technique create entry barriers for commodity producers.
- Vegan:Aquafaba, potato protein, and other egg-white substitutes achieve structural parity while eliminating animal derivatives. This segment is climbing fastest in London and Berlin specialty channels as clean-label expectations intensify; EFSA novel food consultations add 12-18 month formulation lead times for new binding agents.
- Gluten-Free:Certified gluten-free almond flour and segregated production lines serve celiac and wheat-sensitive consumers. FDA gluten-free labeling rules and EU Regulation 828/2014 mandate strict cross-contamination thresholds below 20 ppm.
- Filled:Dual-layer or injected fillings with jams, curds, or caramel cores extend shelf-life complexity. Moisture migration between shell and filling requires modified atmosphere packaging and accelerated stability testing protocols.
Classic sits at the top of the volume ranking, with Vegan climbing the fastest.
Flavor Profile:
Flavor selection drives raw material sourcing geography and seasonal procurement patterns, with nut-based variants facing distinct mycotoxin testing requirements under EU contaminants regulation and FDA guidance for tree nuts.
- Chocolate:Cocoa butter and single-origin chocolate ganache formulations dominate corporate gifting assortments. Demand concentrates in London financial district and Manhattan hospitality channels where dark chocolate intensity signals premium positioning.
- Pistachio:Sicilian and Iranian pistachio pastes carry elevated aflatoxin monitoring burdens under EU 2010/165/EU and FDA import alerts. Supply concentration in Mediterranean harvest zones creates price volatility during drought cycles.
- Raspberry:Lyophilized fruit powders and seedless coulis provide color stability without synthetic dyes. This segment gains share fastest as EFSA synthetic color restrictions push brands toward plant-derived alternatives.
- Vanilla:Bourbon and Tahitian vanilla bean specifications anchor classic assortments. Madagascar supply disruptions and extract purity standards under FDA flavor regulations sustain input cost pressure.
Chocolate maintains volume leadership across both regions, while Raspberry is expanding most quickly on clean-label momentum.
Distribution Channel:
Channel selection determines customer acquisition economics and regulatory touch density, with direct-to-consumer platforms facing state-level cottage food law variability in the US and distance-selling food regulations in the EU.
- Online:Subscription models and corporate customization portals bypass retail slotting fees. E-commerce fulfillment requires insulated cold-chain logistics and FDA food facility registration for interstate shipping compliance.
- Retail:Supermarket and hypermarket placement demands UPC coding, nutritional paneling, and retailer-specific quality audits. This channel captures the highest absolute volume in French and German grocery consolidation.
- Food Service:Hospitality distributors supply hotels, restaurants, and catering operations with thaw-and-serve or fresh-delivered programs. HACCP alignment and liability insurance requirements filter small-batch producers.
- Specialty Stores:Flagship boutiques and patisserie counters sustain artisan positioning and gross margins. Real estate costs in prime Paris, London, and New York locations constrain footprint expansion.
Retail holds the volume advantage, though Online is gaining share fastest on subscription model adoption.
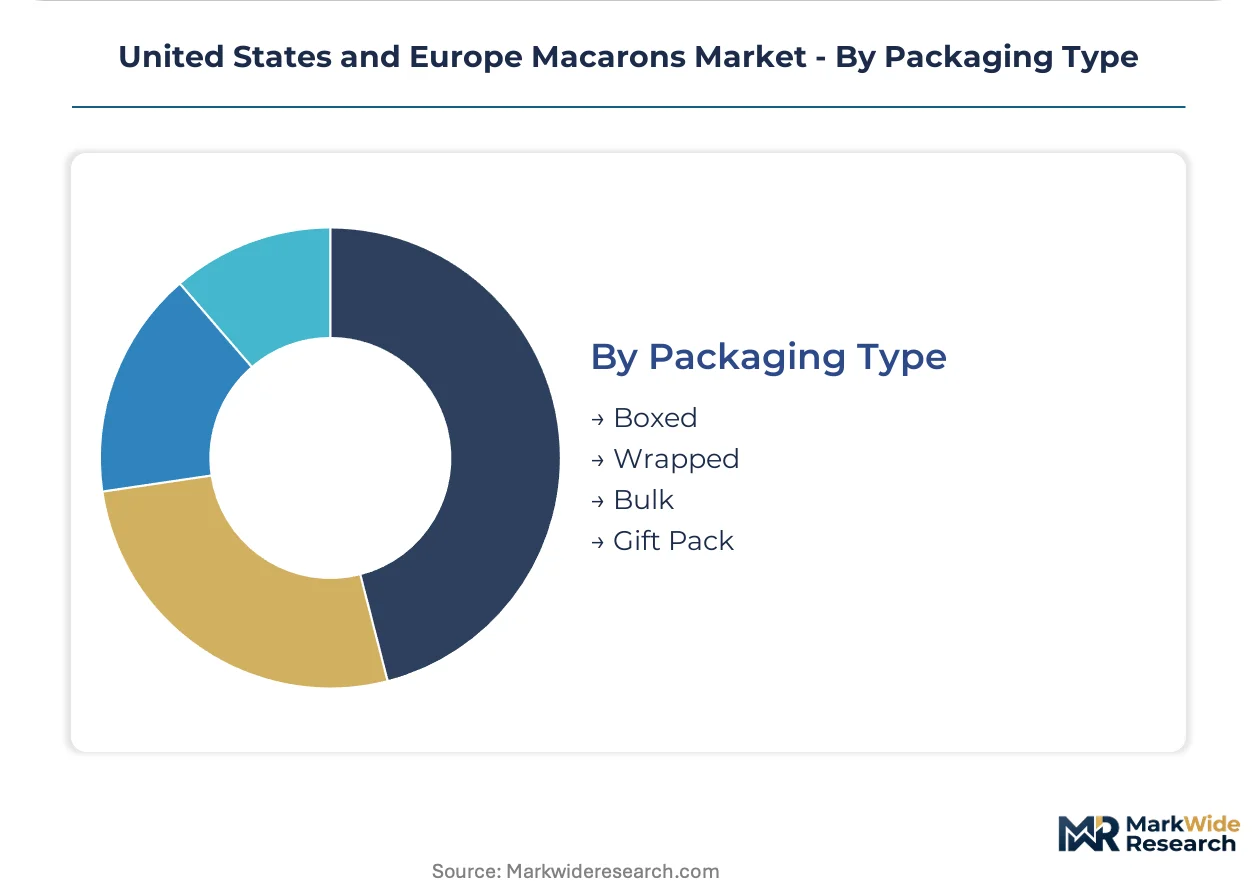
Packaging Type:
Packaging format shapes shelf-life extension capabilities and gift occasion positioning, with single-serve wrapped formats triggering distinct labeling minima under FDA Fair Packaging and Labeling Act and EU Food Information to Consumers Regulation.
- Boxed:Rigid presentation cases with molded trays protect shell integrity during transport. Corporate procurement departments in London and Manhattan specify branded box assortments for client entertainment.
- Wrapped:Individual flow-wrapped units extend ambient shelf life through moisture barrier films. This format is expanding most quickly in convenience retail and grab-and-go coffee chain placements.
- Bulk:Unpackaged display trays for patisserie counter service minimize packaging cost but compress holding time to 24-48 hours. French hygiene code requirements govern open-display temperature controls.
- Gift Pack:Seasonal and occasion-themed assortments with ribbon closures and personalized messaging command price premiums. EU packaging waste directives and extended producer responsibility schemes add compliance overhead.
Boxed formats lead by volume, with Gift Pack showing the steepest expansion trajectory on corporate and holiday gifting concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France commands heritage premium pricing that American producers rarely match, while the United States accelerates flavor experimentation and direct-to-consumer channel development. Both markets face divergent regulatory pressures on synthetic additives and allergen disclosure.
France
Haute pâtisserie traditions sustain Île-de-Paris flagship density, with Ladurée and Pierre Hermé anchoring Champs-Élysées and Saint-Germain-des-Prés retail gravity. ANSM enforces strict allergen labeling under EU Regulation 1169/2011, requiring full ingredient traceability for almond-based production. Lyon and Bordeaux secondary markets are expanding boutique presence as regional tourism recovers.
United States
Specialty coffee chains and boutique hotels in Manhattan and Los Angeles drive consumption occasion expansion beyond traditional dessert contexts. FDA Food Safety Modernization Act preventive controls mandate facility registration and hazard analysis for all interstate almond flour processors. Brooklyn and San Francisco artisan clusters compete on American flavor innovation rather than French heritage replication.
United Kingdom
London financial district corporate gifting programs concentrate volume through hospitality distributors serving law firms and asset managers. EFSA evaluations of synthetic food colorants push Mayfair and Notting Hill boutiques toward spirulina and beetroot-derived palettes. Manchester and Edinburgh secondary markets show underdeveloped premium confectionery infrastructure relative to capital saturation.
Germany
Berlin vegan specialty channels accelerate fastest in Europe as aquafaba meringue substitutes achieve structural parity with egg-white formulations. REACH framework restrictions on titanium dioxide and azo dyes force reformulation investments across EU-exporting facilities. Munich and Hamburg maintain conservative classic flavor preferences that lag Berlin's plant-based experimentation.
Italy
Milan fashion district retail placement elevates macarons as luxury accessory purchases alongside leather goods and eyewear. EU Regulation 828/2014 gluten-free certification requirements filter small-batch producers without segregated almond flour supply chains. Rome and Florence tourism-dependent boutiques face seasonality compression that Milan's corporate client base avoids.
United States and Europe Macarons Market Competitive Landscape
Top-tier vendors anchor heritage patisserie positioning, while mid-scale American innovators and private-label supermarket suppliers compete on accessibility and flavor novelty. The vendor base stratifies across three archetypes: French heritage houses with flagship retail estates, American flavor specialists with direct-to-consumer scale, and European hospitality distributors with corporate B2B concentration. Consolidation pressure operates through boutique acquisition by luxury conglomerates and vertical integration into almond flour milling.
Among French heritage houses, Ladurée Paris and Pierre Hermé Paris exemplify the flagship retail archetype, occupying positions defined by macaronage technique mastery and prime real estate concentration in Paris, London, and New York. Dana's Bakery represents the American flavor innovation vector, diverging from classical formulations through salted caramel and peanut butter varieties that target subscription gifting and corporate customization channels. These three anchors illustrate how geographic origin and formulation philosophy segment competitive positioning across the transatlantic market.
| Leading Market Players |
|---|
| Ladurée Paris |
| Pierre Hermé Paris |
| Dana's Bakery |
| Chantal Guillon |
| Dalloyau |
| Jean-Paul Hévin |
| La Maison du Chocolat |
| Olivia Macaron |
| Richart |
| Others |
Value Network & Pricing Analysis
Corporate procurement departments in London financial services and Manhattan hospitality sectors anchor contract-based volume commitments that sustain premium pricing tiers for heritage producers while compressing margins for supermarket private-label suppliers.
Pricing Analysis
Gift-box bundling versus individual unit sales creates the primary pricing architecture divergence. Three-tier pricing structure across flagship boutique, specialty retail, and mass-market supermarket levels separates Ladurée Paris positioning from Dana's Bakery accessibility and private-label economy tiers. Price differentiation rests on macaronage technique certification and almond flour provenance rather than flavor complexity alone. Cost compression in commodity channels is intensifying because California almond harvest variability and Mediterranean supply disruptions feed raw material volatility. Supermarket private-label buyers exhibit highest price sensitivity, while corporate hospitality procurement shows lowest elasticity due to occasion-based gifting requirements.
Supply Chain Analysis
Cold-chain logistics costs for ambient humidity-controlled transport absorb disproportionate margin share in transatlantic distribution. Almond flour supply concentrates in California, Spain, and Italy, with Sicilian pistachio paste and Madagascar vanilla bean dependencies adding geographic complexity. Production draws from premium blanched almond milling, egg-white powder processing, and plant-derived colorant extraction as core input streams. Single-source vulnerability in California almond supply creates exposure to drought-driven price spikes. Distribution runs through hospitality distributors, specialty food brokers, and direct-to-consumer subscription platforms as downstream pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States and Europe macarons market compounds steadily as specialty coffee chain penetration converts daily ritual occasions into incremental consumption moments beyond traditional patisserie visits.
For Market Incumbents: Extend flagship retail estate concentration in Paris Île-de-France and New York metropolitan zones to defend artisan positioning against automated manufacturing encroachment. Deepen backward integration into almond flour milling to insulate margin structures from California harvest volatility. Prioritize aquafaba meringue R&D investment to capture vegan segment acceleration before formulation patents consolidate. For New Entrants and Emerging Players: Capture underdeveloped corporate customization channels in Eastern European hospitality markets where premium confectionery infrastructure lags Western saturation. Target Poland and Czech Republic B2B gifting programs through hospitality distributor partnerships rather than retail slotting fee competition. Lead with American flavor innovation positioning—salted caramel, peanut butter variants—to differentiate from French heritage replication. For Investors and Strategic Acquirers: Luxury conglomerates with existing patisserie holdings are the most active acquirer in this space, seeking boutique brand assets for portfolio premiumization. Five-to-ten-year viability hinges on clean-label transition execution and plant-based formulation scalability. Monitor EFSA novel food consultation timelines for aquafaba and potato protein binding agents as inflection indicators for vegan segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | EFSA synthetic dye restrictions force spirulina and beetroot pigment adoption across EU-bound production lines. |
| Direct-to-Consumer Subscription Launch | Monthly delivery models bypass retail slotting fees while capturing recurring revenue in corporate gifting segments. |
| Precision Humidity Control Investment | Automated climate chambers reduce weather-dependent spoilage rates in Paris and New York boutique production. |
| Eastern European Distribution Expansion | Poland and Czech Republic hospitality channels show underdeveloped premium confectionery infrastructure relative to Western markets. |
| Vegan Meringue Technology Licensing | Aquafaba and potato protein patents unlock allergen-free segments previously excluded from almond-egg formulations. |
Research Methodology
Multiple input streams — executive interviews with heritage patisserie brand managers, specialty coffee chain procurement officers, and hospitality distributor category buyers; secondary validation through FDA facility registration databases, EFSA food additive evaluation records, and EU customs trade flows; plus Nielsen retail audit data and Circana channel tracking — were reconciled through bottom-up production volume modeling and top-down demand segmentation triangulation.
Data-stream reconciliation across the projection horizon applied discrete modeling for classic, vegan, gluten-free, and filled product type segments alongside flavor profile, distribution channel, and packaging format dimensions. CAGRs were derived from segmented volume trajectory analysis calibrated against almond flour price indices and specialty coffee chain expansion pipelines. Humidity-controlled production capacity constraints and EFSA novel food consultation timelines fed industry-specific forecast adjustments.
California drought recurrence, REACH framework colorant restriction tightening, and aquafaba supply scale limitations are the dominant revision risks that could compress forecast ranges. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Gummy Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Caramel Chocolate Market
Confectionery
Sugar Free Candy Market
Confectionery
Low-Calorie Chocolate Market
Confectionery
Middle-East and Africa Compound Chocolate Market
Confectionery
South America Chocolate Market
Confectionery
North-American Industrial Chocolate Market
Confectionery
Chocolate Couverture Market
Confectionery
Cookie Dough Market
Confectionery
India Industrial Chocolate Market
Confectionery
Global Confectionery Market
Confectionery
Low Calorie Treats Market
Confectionery
Gummy Candy Market
Confectionery
Low-Fat Sweets Market
Confectionery
Bangladesh Candy Market