
 Asia-Pacific Compound Chocolate Market | 2026-2036
Asia-Pacific Compound Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Compound Chocolate Market Outlook
Indonesia's cocoa processing corridor is rewriting regional supply dynamics as new grinding capacity comes online. Cargill Incorporated leverages its integrated bean-to-bar infrastructure across Southeast Asian port zones. The Barry Callebaut Group anchors premium compound formulations through specialized technical service centers. Fuji Oil Holdings Co., Ltd. dominates tropical-fat substitution chemistry that underpins cost-efficient regional production.
Asia-Pacific compound chocolate denotes a cocoa butter equivalent-based confectionery material formulated with vegetable fats, typically containing 5-35% cocoa solids, designed for coating, molding, and enrobing applications where thermal stability and snap control matter. Milk Compound leads volume consumption across industrial bakeries seeking consistent melt profiles in warm climates. Coatings command margin concentration due to technical complexity in fat bloom resistance and viscosity tuning for high-speed enrobing lines.
FSSAI standards in India, GB standards administered by SAMR in China, and Japan's Food Sanitation Act collectively govern vegetable fat labeling, trans-fat limits, and cocoa content claims that determine market access. MEE environmental compliance requirements in China add wastewater and emissions thresholds that shape plant location decisions. Stakeholders must monitor evolving palm oil sustainability certifications and their intersection with national food safety regimes to secure long-term supply contracts.
Market Dynamics
Indonesia's cocoa processing corridor expansion is redistributing regional grinding capacity as Malaysian and Singaporean port infrastructure captures transshipment flows. This geographic rebalancing compresses logistics costs for compound chocolate manufacturers serving Southeast Asian confectionery clusters.
Growth Catalysts
- India FSSAI Reformulation Mandates:India's Food Safety and Standards Authority is enforcing stricter vegetable fat labeling and trans-fat thresholds, compelling manufacturers to upgrade compound chocolate formulations and creating demand for technical service partnerships.
- Indonesian Cocoa Grinding Scale-Up:New processing capacity in Sulawesi and East Java is shortening supply chains for cocoa butter equivalents, reducing import dependency for regional compound chocolate producers.
- Tropical Fat Substitution Chemistry:Advances in palm kernel oil and shea stearin fractionation are enabling cost-efficient thermal stability in warm-climate applications without cocoa butter price exposure.
Market Restraints
- Palm Oil Sustainability Certification Fragmentation:RSPO, ISPO, and national Indonesian standards create overlapping compliance burdens that inflate raw material verification costs for compound chocolate manufacturers.
- MEE Environmental Thresholds:China's Ministry of Ecology and Environment wastewater and emissions requirements constrain plant siting options in coastal manufacturing zones, extending permitting timelines.
- Cocoa Butter Equivalent Price Volatility:Tropical vegetable fat markets exhibit supply concentration in Malaysian and Indonesian processing clusters, exposing buyers to weather-driven input cost swings.
Strategic Opportunities
- Vietnamese Industrial Bakery Expansion:Ho Chi Minh City and Hanoi food manufacturing corridors are scaling bread and pastry production, creating unmet demand for milk compound coatings with consistent warm-climate performance.
- Japan Clean-Label Convergence:METI guidance on processed food transparency is opening premium positioning for compound chocolates with simplified ingredient declarations and reduced additive content.
- SAMR GB Standard Harmonization:China's State Administration for Market Regulation is consolidating vegetable fat labeling rules, reducing formulation complexity for pan-Asia product portfolios.
Industry Challenges
- Specialized Fat Chemist Scarcity:Compound chocolate formulation requires expertise in lipid crystallization and polymorphism control that outpaces Southeast Asian technical training pipeline output.
- Multi-Jurisdiction Certification Overlap:Simultaneous FSSAI, GB, and Japan Food Sanitation Act compliance creates documentation bottlenecks that delay new product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Compound Chocolate Market |
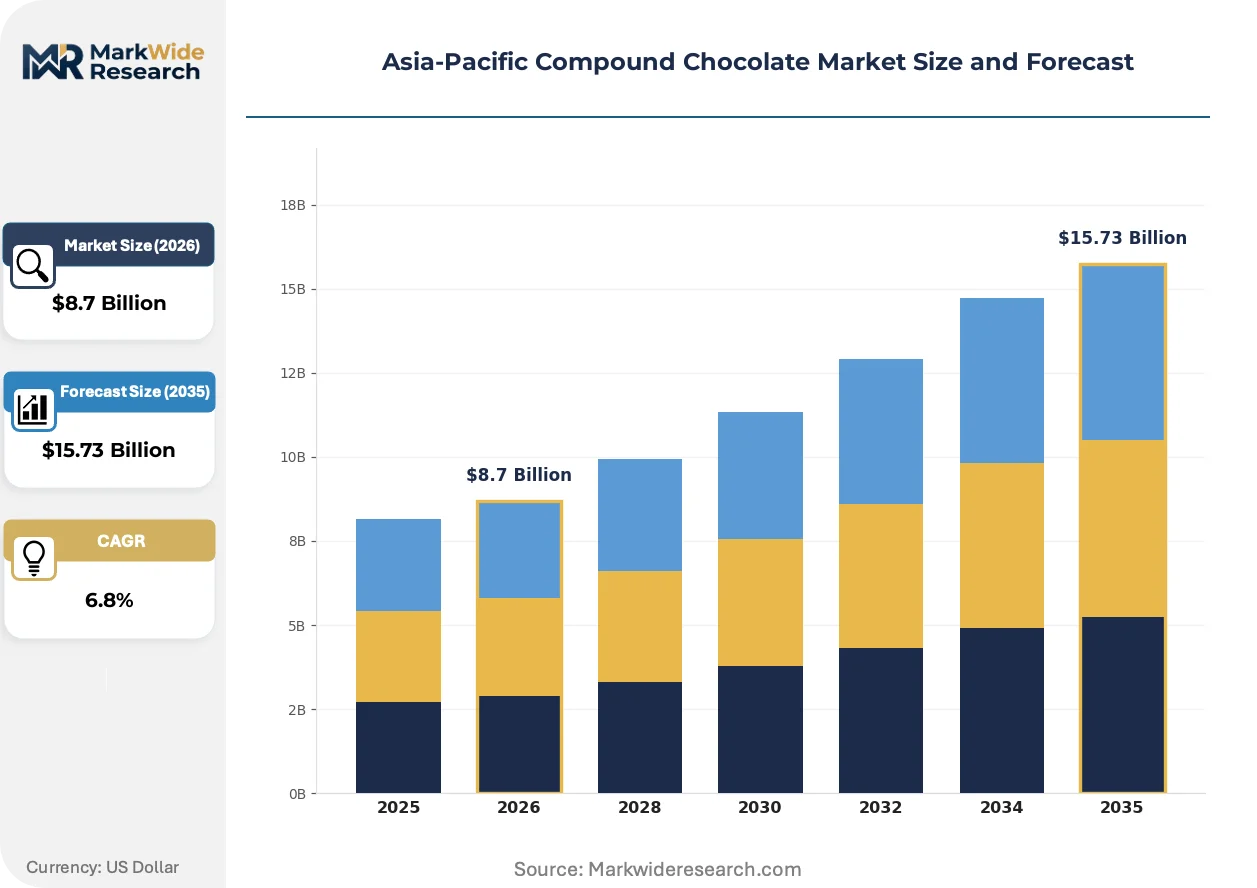
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Compound, Milk Compound, White Compound, Combined Compound Form: Chunks, Coatings, Liquids, Bars End User: Bakeries, Confectioneries, Ice Cream Manufacturers, Retailers Packaging Type: Bags, Boxes, Sachets, Bulk |
| Companies Covered | Cargill Incorporated, Puratos Group NV, The Barry Callebaut Group, Fuji Oil Holdings Co., Ltd., Aalst Wilmar Pte Ltd, Nestlé S.A., ADM, Palsgaard, Blommer Chocolate Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Compound Chocolate Market Strategic Shifts
Digital formulation platforms are compressing product development cycles as regional manufacturers seek faster response to seasonal confectionery demand. This technological infusion is reshaping how compound chocolate recipes are tested, validated, and scaled.
Enzymatic interesterification is virtualizing traditional chemical modification processes for vegetable fat structuring. Industrial bakeries in Thailand and the Philippines are adopting enzyme-treated palm fractions at accelerating rates. This biological processing route is virtualizing cost structures while delivering equivalent snap and bloom resistance.
China's SAMR is tightening GB 28050 nutrition labeling enforcement for prepackaged foods containing vegetable fats. Compound chocolate imports now face heightened scrutiny on saturated fat disclosure and serving-size standardization. Premium coating manufacturers are responding with reformulated recipes that reduce declared saturated fat content per 100g.
Confectionery procurement teams are consolidating supplier relationships to secure volume commitments with fixed-price tropical fat clauses. Regional distributors serving Indonesian and Vietnamese bakery chains are being displaced by direct mill relationships. This concentration is most visible in Malaysia's Port Klang logistics hub where integrated compound chocolate suppliers now operate captive technical service laboratories.
Asia-Pacific Compound Chocolate Market Segmentation
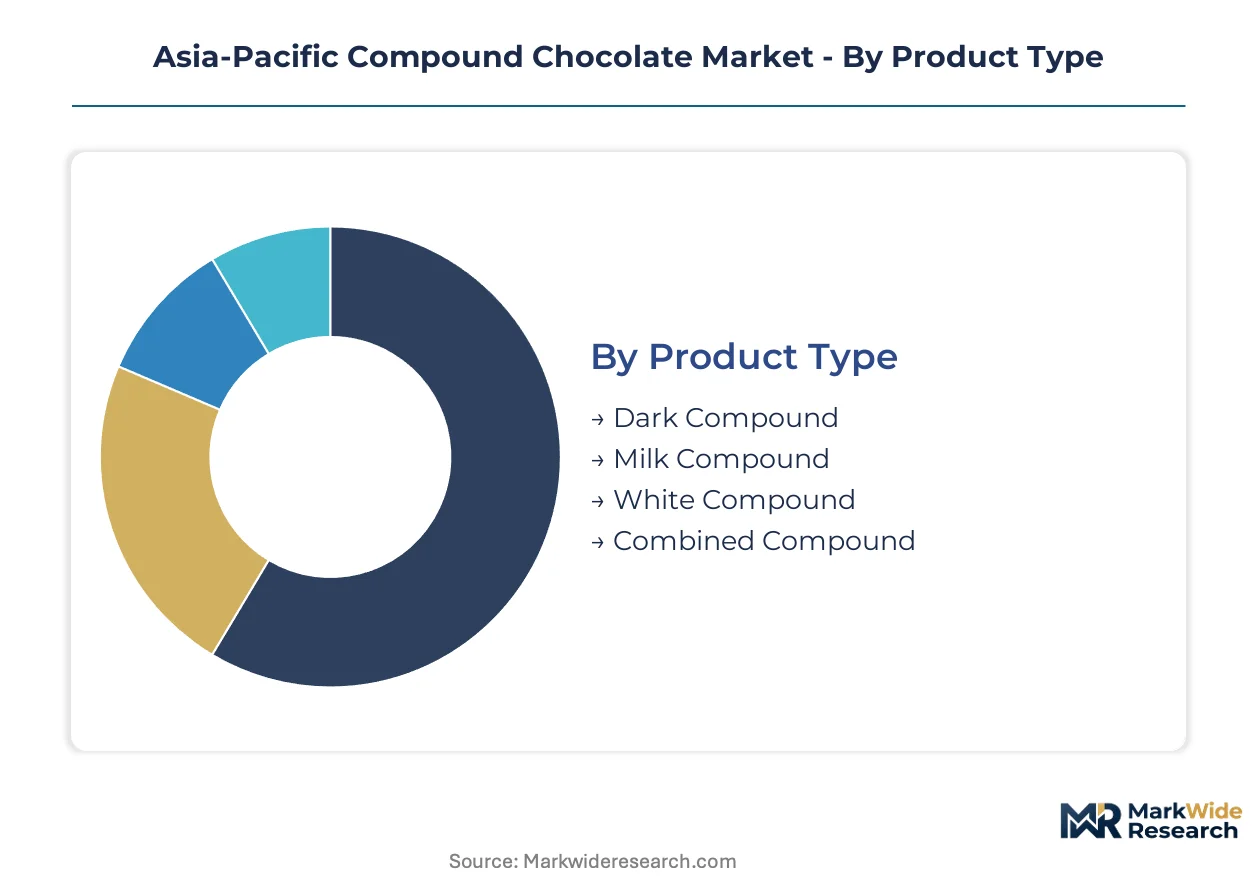
Compound chocolate formulation varies sharply across thermal stability requirements, processing equipment compatibility, and finished product aesthetics. Segmentation in this market reflects divergent cost structures between premium cocoa butter equivalents and tropical fat substitutions, alongside distinct supply chain configurations for industrial versus artisanal end-users.
Product Type:
Cost tier differentiation separates commodity formulations from premium-positioned alternatives, with cocoa butter equivalent ratios and vegetable fat provenance driving price positioning.
- Milk Compound:Formulated with 5-15% cocoa solids, milk powder, and palm kernel oil or shea stearin fractions to deliver consistent snap and melt profiles in warm climates. Industrial bakeries across Indonesia's Java corridor and Vietnam's Ho Chi Minh City manufacturing zones specify this grade for bread and pastry coatings where thermal stability outweighs cocoa intensity.
- Dark Compound:Contains 15-35% cocoa solids with reduced sugar profiles, appealing to confectionery manufacturers seeking bittersweet flavor notes without cocoa butter price exposure. India's FSSAI trans-fat thresholds are pushing reformulation toward enzymatically interesterified palm fractions in this tier.
- White Compound:Cocoa butter-free formulation relying entirely on vegetable fat matrices and dairy solids for color and texture, serving decorative applications and premium ice cream inclusions across Japan and South Korea.
- Combined Compound:Blended dark-milk or milk-white formulations engineered for specific viscosity and bloom resistance targets, typically supplied to contract manufacturers with proprietary recipe requirements.
Milk Compound holds installed capacity. Dark Compound is rotating up the share rankings.
Form:
Application-driven processing requirements dictate form selection, with enrobing line speeds and tempering equipment compatibility determining specification.
- Coatings:Engineered for high-speed enrobing with precise viscosity control and fat bloom resistance through controlled polymorphism in palm stearin-cocoa butter equivalent blends. Thailand's industrial bakery sector and Philippine confectionery clusters drive specification complexity here.
- Chunks:Sized for mechanical dispensing in cookie and muffin production, with moisture resistance critical for shelf-stable inclusion performance. Australian and New Zealand bakery ingredient distributors specify chunk geometry standards that regional manufacturers now adopt.
- Liquids:Pre-tempered or untempered pumpable formats for continuous dosing systems, prevalent in ice cream variegate and frozen dessert applications across Malaysia's Port Klang processing hub.
- Bars:Solid format for artisanal re-melting and small-batch confectionery operations, with Singapore and Hong Kong specialty chocolate shops representing concentrated demand.
Coatings dominate industrial procurement volumes. Chunks are climbing the fastest as bakery automation spreads.
End User:
Customer type segmentation reveals divergent technical service requirements, with large-scale industrial users demanding formulation partnership versus transactional supply for smaller operators.
- Bakeries:Span industrial bread plants to artisanal patisseries, with compound chocolate specification hinging on oven spring compatibility and glaze stability under display case humidity. Indonesia's expanding bakery chain networks are consolidating supplier relationships around technical service capabilities.
- Confectioneries:Require precise snap control and mold release properties for praline and bar production, with Japanese and South Korean manufacturers leading clean-label formulation demands.
- Ice Cream Manufacturers:Specify low-melting-point variants with fat crystal structures engineered for freeze-thaw stability, a segment expanding with Vietnam's dairy processing investments.
- Retailers:Private-label compound chocolate programs for supermarket bakery counters and seasonal confectionery, with China's SAMR GB 28050 labeling enforcement reshaping ingredient declaration requirements.
Bakeries command the largest volume commitments. Ice Cream Manufacturers are expanding most quickly.
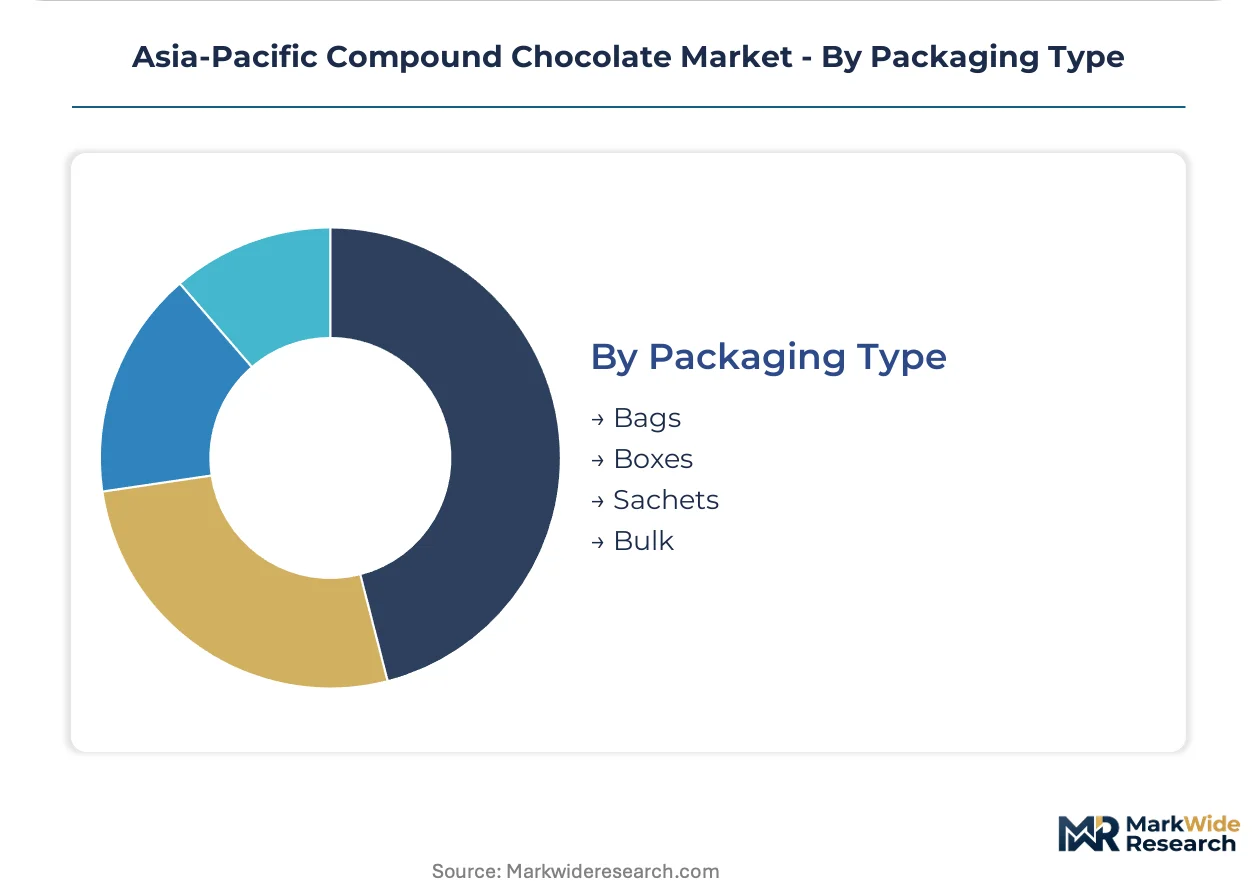
Packaging Type:
Supply concentration in Malaysian and Indonesian processing corridors shapes packaging economics, with bulk formats favored by integrated manufacturers and unitized packaging serving fragmented distribution networks.
- Bulk:Tanker or intermediate bulk container delivery for high-volume compound chocolate users with captive melting and tempering infrastructure, prevalent across Southeast Asian port zone manufacturing.
- Bags:Multi-layer laminated sacks for industrial scale-down with moisture and oxidation barrier properties, standard for mid-tier bakery and confectionery procurement.
- Boxes:Rigid packaging for chunk and bar formats protecting physical integrity through distribution, specified by premium-positioned confectionery ingredient distributors.
- Sachets:Single-serve or small-batch retail formats for artisanal re-melting and foodservice portion control, gaining traction in Japan's specialty baking supply channels.
Bulk captures the steepest volume share. Sachets are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grinding capacity concentrates in Indonesian port zones, redistributing regional supply chains as Malaysian transshipment infrastructure captures cocoa butter equivalent flows. This geographic rebalancing compresses logistics costs for compound chocolate manufacturers serving Southeast Asian confectionery clusters.
Indonesia
Sulawesi and East Java cocoa processing corridors are shortening supply chains for regional compound chocolate producers. The Indonesian Sustainable Palm Oil (ISPO) certification mandates reshape raw material verification protocols for manufacturers operating in these zones. Surabaya's industrial port zone anchors new technical service laboratories serving bakery and confectionery clusters across Java.
China
Industrial bakery expansion in Yangtze River Delta and Pearl River Delta manufacturing corridors drives specification demand for warm-climate stable coatings. SAMR-administered GB standards on vegetable fat labeling and GB 28050 nutrition disclosure enforcement reshape import compliance requirements. Shanghai's Port Klang-linked logistics hub concentrates compound chocolate distribution for pan-Asia product portfolios.
India
FSSAI trans-fat thresholds and vegetable fat labeling mandates compel reformulation upgrades across milk and dark compound tiers. Maharashtra and Gujarat food manufacturing corridors scale bread and pastry production, creating volume demand for consistent melt-profile coatings. Mumbai's industrial bakery supplier networks consolidate around technical service partnerships for formulation compliance.
Vietnam
Ho Chi Minh City and Hanoi food manufacturing corridors expand bread and pastry output, generating unmet demand for milk compound with warm-climate performance. The country's national food safety administration tightens prepackaged food labeling alignment with regional standards. Dong Nai province's industrial zones attract compound chocolate suppliers establishing direct mill relationships with bakery chains.
Japan
METI guidance on processed food transparency opens premium positioning for compound chocolates with simplified ingredient declarations. Kansai and Chubu manufacturing regions lead clean-label formulation specification for confectionery applications. Osaka's specialty baking supply channels drive sachet-format demand for artisanal re-melting operations.
Asia-Pacific Compound Chocolate Market Competitive Environment
Integrated bean-to-bar operators and specialized tropical-fat chemists split the market between scale-driven supply security and formulation technical service. The vendor base concentrates around Southeast Asian port zones where captive grinding infrastructure and technical laboratories co-locate. Three archetypes dominate: integrated agricultural processors with backward control over cocoa supply, specialized lipid technology houses with polymorphism expertise, and diversified food ingredient conglomerates with cross-category distribution reach. Capacity expansion in Indonesian processing corridors and enzymatic interesterification technology licensing represent the dominant competitive moves reshaping cost structures.
Among integrated agricultural processors, Cargill Incorporated and ADM exemplify the archetype of operators leveraging captive bean-to-bar infrastructure across port zones. Fuji Oil Holdings Co., Ltd. occupies a distinct position within the specialized lipid technology tier, its name signaling dominance in tropical-fat substitution chemistry that underpins regional production economics. The Barry Callebaut Group anchors the premium formulation segment through technical service center deployment, representing the diversified specialist archetype that bridges industrial scale with application-specific expertise.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Puratos Group NV |
| The Barry Callebaut Group |
| Fuji Oil Holdings Co., Ltd. |
| Aalst Wilmar Pte Ltd |
| Nestlé S.A. |
| ADM |
| Palsgaard |
| Blommer Chocolate Company |
| Others |
Value Chain & Pricing Dynamics
Surabaya's industrial port zone concentrates new grinding capacity that compresses logistics costs for compound chocolate manufacturers while amplifying pricing power for integrated processors serving Southeast Asian bakery clusters. FSSAI trans-fat mandates and ISPO certification requirements feed into formulation cost structures that differentiate premium from standard tiers.
Pricing Analysis
FSSAI vegetable fat labeling dictates the pricing tier structure across milk and dark compound segments. Three-tier pricing structure across premium, standard, and economy levels separates ISPO-certified formulations from conventional palm fractions and commodity cocoa butter equivalents. Cost compression in the economy tier is intensifying because Indonesian grinding capacity expansion shortens supply chains for regional buyers. Industrial bakeries in Vietnam and Indonesia exhibit highest price sensitivity, while Japanese confectioneries tolerate premium positioning for clean-label declarations.
Supply Chain Analysis
Export-control regimes on enzymatic interesterification technology limit equipment flows to regional processors, constraining capacity expansion timelines. Supply concentrates in Indonesia, Malaysia, and Singapore, with cocoa butter equivalents and palm kernel stearin as critical inputs. Single-source vulnerability runs through Sulawesi cocoa processing corridors exposed to El Niño weather patterns. Distribution runs through Port Klang and Surabaya logistics hubs where integrated suppliers operate captive technical laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific compound chocolate sits in early-cycle expansion as Vietnamese and Indonesian bakery automation accelerates adoption of warm-climate stable coatings. Reformulation mandates across India and China create sustained demand for technical service partnerships.
For Market Incumbents: Pre-empt margin erosion in commodity milk compound by locking long-term offtake agreements with Vietnamese bakery chains before grinding capacity fully ramps. Anchor premium positioning through backward integration into Sulawesi cocoa processing corridors. Invest in enzymatic interesterification licensing to capture cost advantages as FSSAI trans-fat thresholds tighten. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's Ho Chi Minh City manufacturing corridor where milk compound demand outpaces local supply. Target white-space in sachet-format distribution for Japan's artisanal baking channels. Lead with technical service partnerships rather than price competition to differentiate from entrenched port-zone operators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized lipid technology houses with polymorphism expertise over commodity grinders. Five-to-ten year viability hinges on enzymatic processing capabilities and clean-label formulation pipelines. Watch for ISPO-RSPO certification convergence as inflection signal for raw material cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Interesterification Licensing | Captures cost advantages as FSSAI and GB standards tighten trans-fat thresholds. |
| Backward Integration into Sulawesi Grinding | Secures captive cocoa butter equivalent supply for Surabaya-based compound production. |
| Technical Service Laboratory Expansion | Locks bakery chain relationships through formulation partnership in Vietnam and Indonesia. |
| ISPO-Aligned Certification Investment | Opens premium positioning for EU-facing confectionery export channels. |
| Sachet Format Distribution Partnership | Accesses Japan's specialty baking supply channels through Osaka-based distributors. |
Study Parameters
A spread of perspectives from compound chocolate plant managers, bakery procurement leads, tropical fat R&D directors, and Port Klang logistics operators converged on the working assumptions. Primary interviews with Indonesian grinding facility engineers and Vietnamese bakery chain technical buyers combined with secondary validation from FSSAI regulatory filings, SAMR GB standard updates, and Indonesian customs trade data. Bottom-up volume modeling triangulated against top-down cocoa butter equivalent consumption estimates.
Demand-supply balance dynamics anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type tier, end-use industry, form specification, and regional regulatory cluster. CAGRs derived from weighted average of historical grinding capacity expansion rates and projected bakery automation penetration. Industry-specific inputs incorporated enzymatic processing adoption curves and palm oil sustainability certification trajectories.
Sensitivities concentrate around FSSAI enforcement intensity and El Niño-driven cocoa butter equivalent price swings. Forecasts reflect assumptions on regulatory harmonization timelines and grinding capacity commissioning schedules. Material shifts in ISPO-RSPO certification equivalence or Sulawesi port infrastructure investment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Europe Premium Chocolate Market
Confectionery
Non-Chocolate Candy Market
Confectionery
Low Calorie Keto Desserts Market
Confectionery
Middle East Chocolate Market
Confectionery
Xylitol Lollipops Market
Confectionery
Jellies and Gummies Market
Confectionery
North America Chocolate Market
Confectionery
Chocolate Hazelnut Spread Market
Confectionery
Low Calorie Nutella Market
Confectionery
Confectionery Fats Market
Confectionery
China Chocolate Market
Confectionery
Middle-East and Africa Compound Chocolate Market
Confectionery
Sugar Confectionery Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Sugar Free White Chocolate Market
Confectionery
Europe Dark Chocolate Market