
 North America Dark Chocolate Market | 2026-2036
North America Dark Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dark Chocolate Market Intelligence
Premium single-origin certification is bifurcating the North America dark chocolate landscape into traceable artisan supply and mass-market fortified offerings. Lindt & Sprungli AG sustains Swiss heritage positioning through controlled bean-to-bar narratives in North American duty-free and specialty retail. The Hershey Company leverages century-old American distribution infrastructure to dominate mainstream grocery and convenience channels. Mondelez International, Inc. navigates dual portfolio demands by balancing Cadbury heritage formulations with emerging dark chocolate extensions.
North America dark chocolate comprises confectionery products containing cocoa solids, cocoa butter, and minimal dairy, typically with cocoa percentages ranging from fifty to ninety percent by weight, manufactured through roasting, grinding, conching, and tempering processes for direct consumption and foodservice ingredient applications. Organic and fair trade product type segments command disproportionate shelf space margins in specialty retail despite smaller absolute volumes. Bar packaging leads household pantry penetration while chip and powder formats anchor bakery and restaurant procurement workflows. Online retail distribution channels are capturing incremental growth from subscription and gifting occasions previously concentrated in supermarkets.
FDA nutrition labeling mandates and USDA organic certification standards govern product claims and market access across United States retail channels, while Health Canada food labeling regulations enforce bilingual disclosure requirements affecting cross-border packaging strategies. The FDA's evolving stance on added sugar declarations and California's Proposition 65 heavy metal testing protocols for cocoa imports are tightening compliance thresholds for new entrants. Stakeholders must monitor dual regulatory tracks as state-level clean-label legislation diverges from federal harmonization timelines.
Market Dynamics
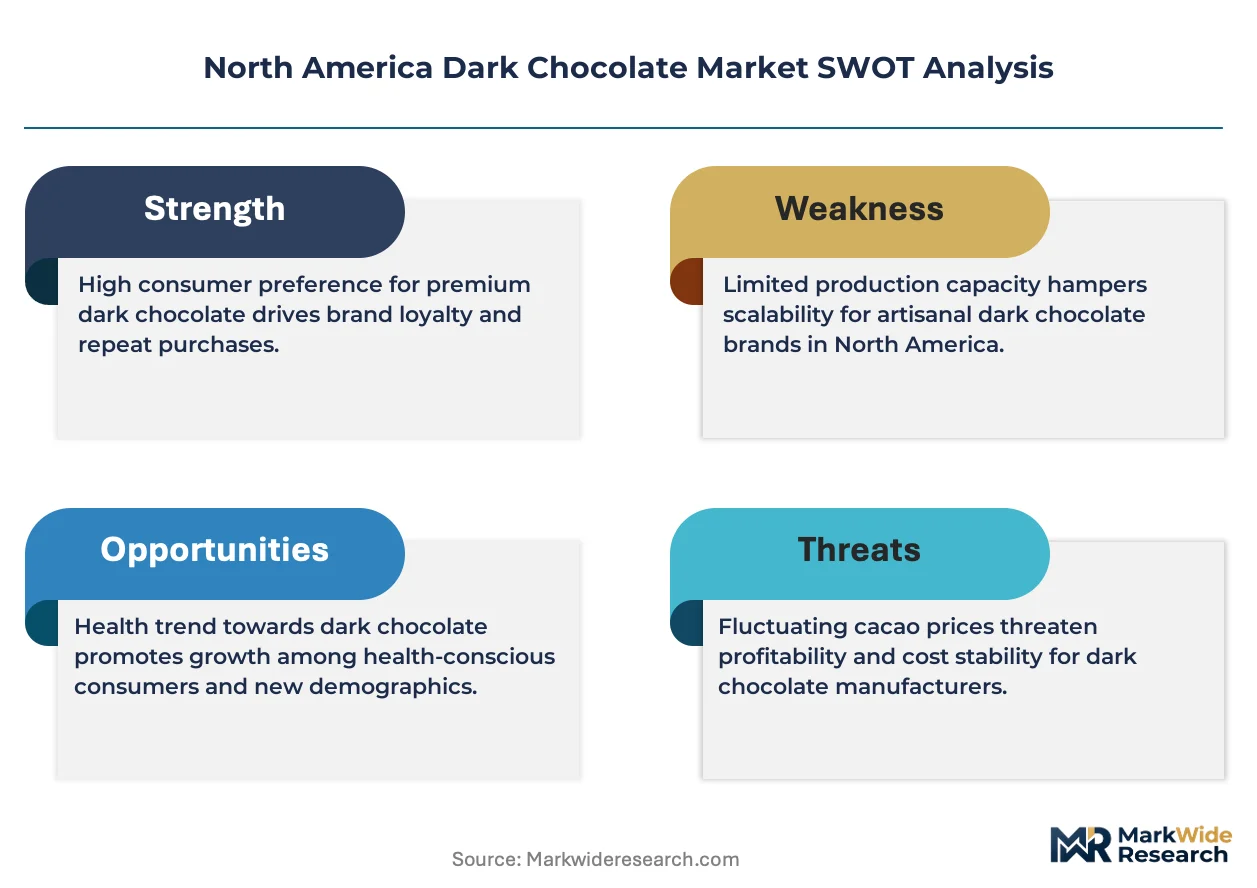
California's Proposition 65 heavy metal testing protocols are forcing cocoa importers to reconfigure supply chains and absorb elevated compliance costs, compressing margins for new entrants while advantaging established processors with captive laboratory infrastructure.
Growth Catalysts
- Specialty Foodservice Expansion:Artisan bakeries and third-wave cafés across California and Toronto are incorporating single-origin dark chocolate into premium dessert menus, driving ingredient-grade procurement volumes.
- USDA Organic Certification:Clean-label mandates from retailers are compelling manufacturers to reformulate around certified organic cocoa butter and unrefined cane sugar, opening shelf space premiums.
- Bean-to-Bar Processing:Small-batch roasting and conching equipment is democratizing craft production, enabling regional producers to bypass commodity cocoa brokers.
Market Restraints
- Cocoa Butter Price Volatility:Weather disruptions in West African growing regions transmit directly to North American input costs, squeezing formulations above seventy percent cocoa solids.
- Dual-Track Regulatory Burden:FDA added sugar disclosure timelines diverge from California's heavy metal testing mandates, forcing parallel packaging runs and compliance systems.
- Mass-Market Substitution:Fortified milk chocolate with elevated cocoa percentages captures price-sensitive households seeking dark chocolate flavor profiles at lower price points.
Strategic Opportunities
- Subscription Commerce:Direct-to-consumer tasting clubs bypass conventional retail slotting fees, capturing gifting occasions and repeat purchase loyalty in urban Canadian and US markets.
- Functional Ingredient Convergence:Adaptogenic botanicals and probiotic cultures are integrating into dark chocolate matrices, creating wellness-positioned confectionery hybrids.
- Health Canada Bilingual Mandates:Cross-border packaging standardization for Canadian market entry creates economies of scale for US processors willing to front-load translation and dual-label design.
Industry Challenges
- Conching Expertise Scarcity:Master chocolatier training programs have not scaled with craft production growth, creating bottlenecks in flavor development and quality consistency.
- Prop 65 Compliance Timelines:Laboratory certification for lead and cadmium testing extends new product launch windows by four to six months, delaying seasonal assortment rotations.
- Legacy ERP Integration:Lot traceability requirements for single-origin claims strain inventory management systems designed for commodity cocoa sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dark Chocolate Market |
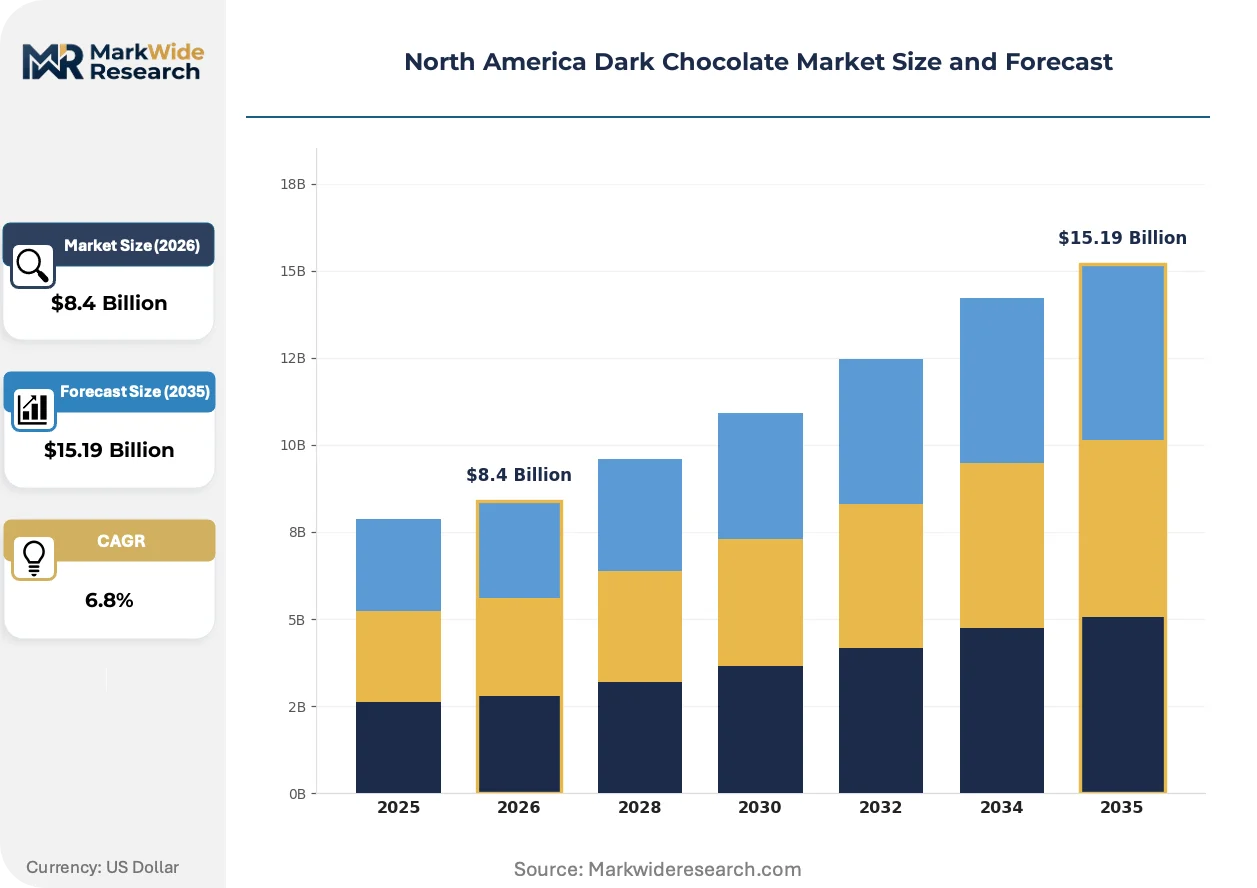
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Sugar-Free, Fair Trade, Premium End User: Retail Consumers, Restaurants, Cafés, Bakeries Packaging Type: Bar, Chips, Powder, Bulk Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Export |
| Companies Covered | Nestle S.A., Lindt & Sprungli AG, The Hershey Company, Ghirardelli Chocolate Company, The Barry Callebaut Group, Mondelez International, Inc., Ferrero International S.A., Godiva Chocolatier, Mars, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dark Chocolate Market Strategic Shifts & Innovations
Precision fermentation and cellular agriculture are beginning to intersect with cocoa processing, while regulatory disclosure mandates and direct-to-consumer channel experimentation are compressing traditional value chain structures.
Precision fermentation-derived cocoa butter is miniaturizing the artisan production footprint by eliminating dependency on tropical commodity supply chains. Specialty manufacturers in Brooklyn and Portland are piloting these ingredients for limited releases. The technology is compressing the geographic span between raw material generation and finished product assembly.
FDA's evolving added sugar disclosure requirements are forcing reformulation transparency across all cocoa percentage tiers. Manufacturers must now reconcile subjective taste profiles with objective nutritional labeling thresholds. Premium segments are responding by emphasizing cocoa mass content over total sugar reduction.
Direct-to-consumer tasting subscriptions are displacing conventional supermarket gifting occasions among affluent urban households. Specialty retailers in Vancouver and Austin are pivoting toward experiential in-store sampling to defend foot traffic. This behavioral shift is most visible in coastal metropolitan markets with established craft food cultures.
North America Dark Chocolate Market Segmentation
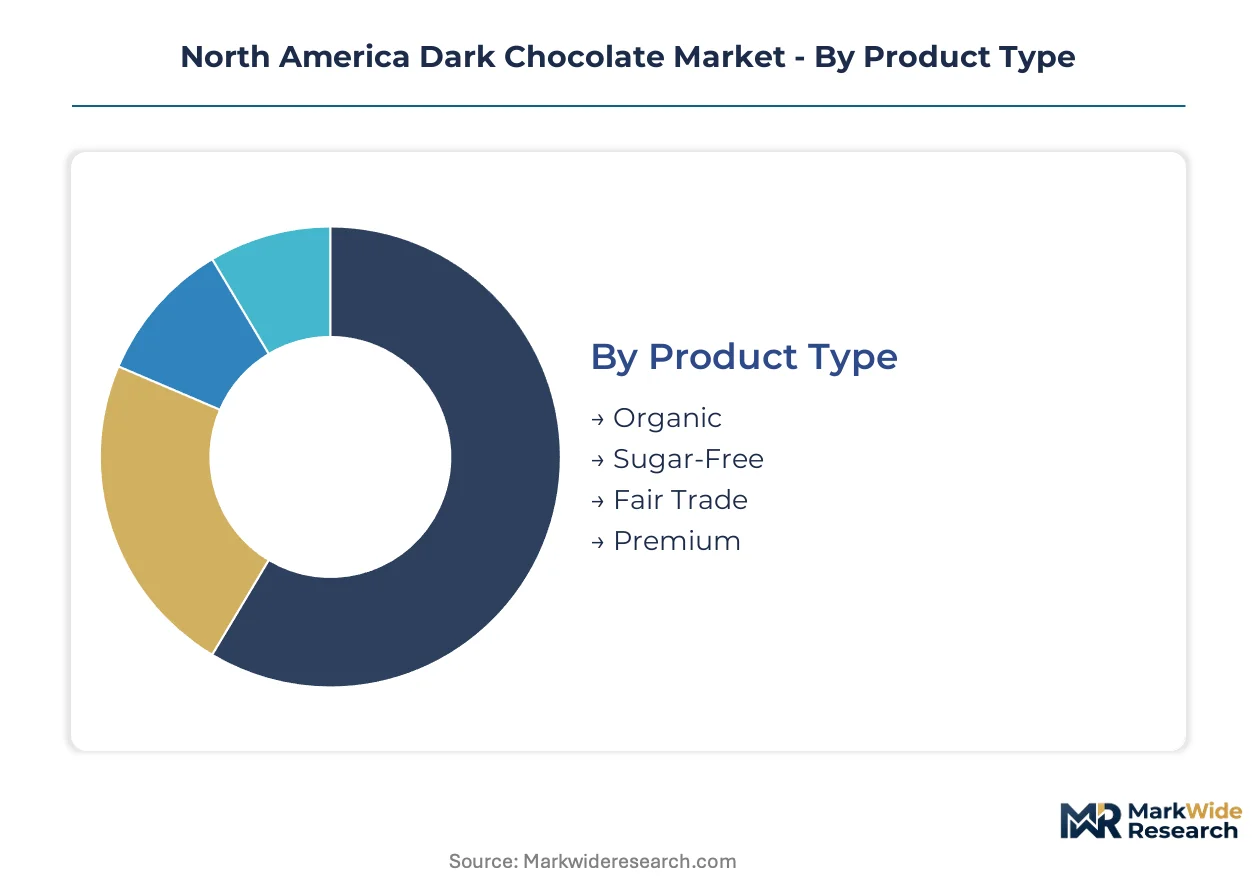
Dark chocolate segmentation in North America reflects divergent channel economics and regulatory pressures. Product certifications and packaging formats map to distinct margin structures across retail and foodservice verticals.
Product Type:
Channel mix varies sharply by certification tier, with organic and fair trade commanding specialty retail premiums while sugar-free penetrates mass-market health aisles.
- Organic:USDA-certified formulations using pesticide-free cocoa beans and unrefined sweeteners. California's craft chocolate cluster and Toronto's specialty food corridor drive disproportionate procurement volumes as clean-label mandates from retailers compel shelf space allocation.
- Premium:Single-origin and bean-to-bar products with elevated cocoa percentages and traceable supply chains. Artisan bakeries and third-wave cafés across Vancouver and Austin anchor ingredient-grade demand through direct distributor relationships.
- Sugar-Free:Alternative sweetener formulations targeting diabetic and ketogenic dietary protocols. Mass-market grocery penetration concentrates in US Midwest and Southeast regions with established health-conscious retail formats.
- Fair Trade:Certified ethical sourcing premiums appeal to coastal metropolitan consumers with demonstrated willingness to pay for supply chain transparency. Limited releases through specialty retailers maintain price integrity.
Premium dominates installed base. Organic is where expansion concentrates.
End User:
Application requirements fragment procurement patterns, with foodservice demanding ingredient-grade consistency and retail prioritizing packaging differentiation.
- Retail Consumers:Direct consumption through supermarket and online channels, with gifting occasions driving seasonal assortment depth. Subscription commerce models in urban Canadian and US markets capture repeat purchase loyalty.
- Restaurants:Dessert menu integration requiring tempering-stable formulations and consistent cocoa butter crystallization. High-volume metropolitan establishments in New York and Los Angeles specify single-origin provenance for menu storytelling.
- Cafés:Beverage and pastry applications demanding rapid-melt characteristics for mocha and hot chocolate preparations. Third-wave coffee culture in Portland and Montreal anchors specialty procurement workflows.
- Bakeries:Chip and powder format consumption for cookie, brownie, and ganache production. Regional craft bakeries in California's Bay Area prioritize fair trade certifications for consumer-facing ingredient disclosures.
Retail Consumers anchor volume scale. Restaurants are climbing the fastest.
Packaging Type:
Format selection correlates with end-use processing requirements and shelf-life specifications across temperature-controlled supply chains.
- Bar:Standardized portion control for direct consumption and pantry storage. Household penetration peaks in US Northeast and Canadian urban corridors with established premium chocolate retail infrastructure.
- Chips:Industrial-scale bakery and confectionery manufacturing inputs. Automated dispensing compatibility drives specification standardization across North American commercial baking operations.
- Powder:Beverage and sauce applications requiring rapid hydration and suspension stability. Hot chocolate and mocha preparations in foodservice channels specify alkalized processing for color consistency.
- Bulk:Foodservice and commercial manufacturing procurement with customized tempering profiles. Restaurant chains and contract manufacturers negotiate direct supply agreements bypassing retail markup structures.
Bar formats dominate household penetration. Chips are gaining share fastest.
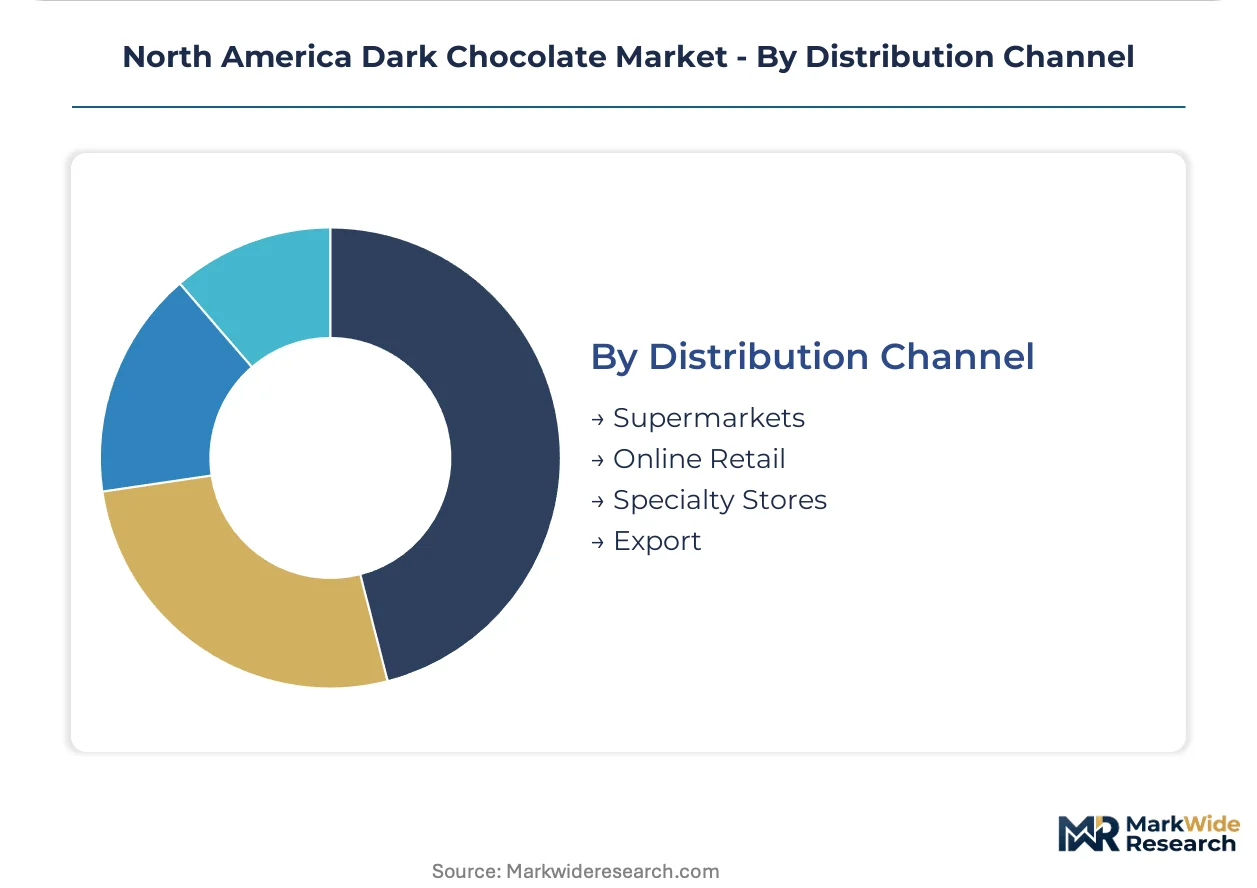
Distribution Channel:
Channel economics determine margin capture, with direct-to-consumer models compressing traditional retail slotting fee burdens.
- Supermarkets:Mass-market penetration through national grocery chains with standardized planogram placement. Seasonal display allocations concentrate in fourth-quarter gifting periods.
- Online Retail:Subscription and gifting occasion capture with personalized assortment curation. Direct-to-consumer tasting clubs bypass conventional retail infrastructure in affluent urban markets.
- Specialty Stores:Curated single-origin and craft product presentation with educated staff consultation. In-store sampling programs in Vancouver and Austin defend foot traffic against digital displacement.
- Export:Cross-border shipment to adjacent markets with harmonized regulatory frameworks. Health Canada bilingual labeling requirements influence packaging standardization for US processors.
Supermarkets anchor volume throughput. Online Retail shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest and Southeast consumers demonstrate pronounced price elasticity, while coastal metropolitan buyers absorb premiums for single-origin certifications. This demand bifurcation shapes regional distribution strategies and channel investments across the continent.
United States
California's craft chocolate cluster drives single-origin procurement volumes through specialty retailers and third-wave cafés. FDA added sugar disclosure mandates and Proposition 65 heavy metal testing protocols tighten compliance thresholds for new entrants. Brooklyn and Portland anchor precision fermentation pilots that eliminate tropical cocoa dependency.
Canada
Toronto's specialty food corridor concentrates fair trade and organic demand among affluent urban households. Health Canada bilingual labeling requirements enforce French-English packaging standards that influence cross-border production runs. Vancouver specialty retailers defend foot traffic through experiential in-store sampling programs.
Mexico
Traditional chocolate consumption patterns persist in southern states while northern border regions adopt US-influenced premium positioning. COFEPRIS food safety regulations govern import protocols for finished confectionery products. Mexico City metropolitan area anchors domestic craft production scaling efforts.
North America Dark Chocolate Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the North America dark chocolate market. Consolidated mass-market infrastructure dominates grocery and convenience channels while fragmented craft producers capture specialty retail premiums. Three archetypes define competitive positioning: heritage multinationals with century-old distribution networks, mid-scale organic specialists with certified supply chains, and bean-to-bar artisans with traceable single-origin narratives. Dominant competitive moves include portfolio diversification into functional ingredient convergence and direct-to-consumer channel bypass of conventional retail slotting structures.
Within the heritage multinational tier, Nestle S.A. and The Hershey Company occupy positions defined by scale-driven distribution infrastructure and American market penetration. Lindt & Sprungli AG represents Swiss-origin premium positioning through controlled bean-to-bar narratives in duty-free and specialty retail channels. These three entities exemplify divergent strategic archetypes: mass-market volume leadership, premium heritage positioning, and controlled vertical integration from cocoa sourcing through finished goods.
| Leading Market Players |
|---|
| Nestle S.A. |
| Lindt & Sprungli AG |
| The Hershey Company |
| Ghirardelli Chocolate Company |
| The Barry Callebaut Group |
| Mondelez International, Inc. |
| Ferrero International S.A. |
| Godiva Chocolatier |
| Mars, Inc. |
| Others |
Cost & Logistics Intelligence
Bean-to-bar processing scale economies in California and Toronto clusters compress per-unit production costs while elevating quality consistency thresholds, simultaneously concentrating supply relationships among established processors and raising price floors for artisan-tier entrants lacking captive laboratory infrastructure for Proposition 65 compliance.
Pricing Analysis
FDA added sugar disclosure mandates dictate the pricing tier structure across North American dark chocolate channels, separating premium single-origin certifications from mass-market fortified formulations. Three-tier pricing structure across premium, standard, and economy levels reflects cocoa percentage gradients and organic certification status. Cost compression in the premium tier is intensifying because California heavy metal testing extends new product launch windows. Midwest and Southeast retail consumers demonstrate highest price sensitivity, while coastal metropolitan buyers absorb premiums for traceable supply chain narratives.
Supply Chain Analysis
Inventory lead times for single-origin cocoa bean procurement extend four to six months under Proposition 65 laboratory certification requirements. West African growing regions, Ecuador, and Peru anchor raw material sourcing for North American processors. Cocoa butter, cane sugar, and alkalized cocoa powder constitute critical input dependencies. Single-source vulnerability concentrates in West African supply corridors exposed to weather disruption. Distribution runs through specialty retail and direct-to-consumer channels bypassing conventional supermarket slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity characterizes this market as subscription commerce and precision fermentation technologies create viable niches outside heritage multinational dominance.
For Market Incumbents: Consolidate distribution infrastructure around dual-label packaging standardization for Health Canada compliance, capturing cross-border economies of scale. Deepen backward integration into captive cocoa butter processing to buffer West African price volatility. Defend against bean-to-bar entrants by accelerating seasonal assortment rotations despite Prop 65 laboratory bottlenecks. For New Entrants and Emerging Players: USDA organic certification fast-tracks shelf space access in California's craft chocolate cluster and Toronto's specialty food corridor. White-space concentration appears in functional ingredient convergence combining adaptogenic botanicals with dark chocolate matrices. Direct-to-consumer tasting subscriptions offer the most penetrable go-to-market angle for bypassing established retail slotting fee barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation ingredient specialists with laboratory-scale production capabilities. Long-term viability over a five-to-ten year window hinges on eliminating tropical commodity dependency through cellular agriculture scale-up. Acquisition target archetype: regional craft producers with established single-origin narratives and compliant laboratory infrastructure. Signal to monitor: FDA finalization of added sugar disclosure timelines as inflection point for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Bean-to-Bar Processing Scale-Up | Captive roasting and conching infrastructure insulates against cocoa butter price volatility from West African supply disruptions. |
| Precision Fermentation Pilot Programs | Brooklyn and Portland laboratories demonstrate cellular agriculture pathways eliminating tropical commodity dependency. |
| Dual-Label Packaging Standardization | French-English bilingual compliance opens Health Canada market access for US processors with front-loaded translation investment. |
| Direct-to-Consumer Subscription Launch | Urban Canadian and US tasting clubs bypass conventional retail slotting fees while capturing repeat purchase loyalty. |
| Functional Ingredient Convergence | Adaptogenic and probiotic integration creates wellness-positioned confectionery hybrids commanding specialty retail premiums. |
Research Approach
Operator-level perspectives from bean-to-bar chocolatiers, specialty retailer category managers, third-wave café procurement leads, and foodservice distributor sales directors anchored the qualitative base. Primary interview insights combined with secondary validation from FDA labeling guidance documents, USDA organic certification databases, Health Canada food labeling regulations, and California Office of Environmental Health Hazard Assessment Proposition 65 protocols. Bottom-up volume triangulation across product type, end user, packaging format, and distribution channel segments reconciled with top-down market sizing.
Sensitivity analysis tested forecast robustness across cocoa price volatility scenarios and regulatory compliance timeline variations. Segmentation dimensions modeled include certification tier, cocoa percentage band, channel economics, and regional adoption patterns throughout the forecast period. CAGRs derived from installed base growth rates adjusted for premium segment share capture and foodservice expansion trajectories. Forecast inputs incorporated Proposition 65 enforcement intensity and precision fermentation technology maturation curves.
Decision-makers should treat outputs as directional under assumptions of sustained FDA labeling harmonization and stable West African supply conditions; material deviation would warrant model refresh. Specific risk factors include California heavy metal testing protocol expansion, cocoa butter price spike duration, and subscription commerce churn rate elevation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Xylitol Lollipops Market
Confectionery
Low-Calorie Dark Chocolate Market
Confectionery
Global Confectionery Market
Confectionery
Sugar-Free Sweets Market
Confectionery
Italy Chocolate Market
Confectionery
North America Gummy Market
Confectionery
Low Calorie Treats Market
Confectionery
Africa Compound Chocolate Market
Confectionery
South America Compound Chocolate Market
Confectionery
Europe Caramel Chocolate Market
Confectionery
Low Calorie Hard Candy Market
Confectionery
Premium Chocolate Market
Confectionery
Global Sugar Free Chewing Gums Market
Confectionery
North-American Industrial Chocolate Market
Confectionery
Middle East and Africa Premium Chocolate Market
Confectionery
Vegan Candies Market