
 Durian Chocolate Market | 2026-2036
Durian Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Durian Chocolate Market Analysis
Ingredient sourcing and in-house pulp processing is reconfiguring margin distribution across the value chain. Beryl's Chocolate & Confectionery Sdn. Bhd leverages integrated durian orchards in Pahang to secure Musang King supply consistency. Benns Chocolate anchors its positioning through single-origin cocoa partnerships that complement durian's volatile flavor profile. Mao Shan Wang dominates the premium tier by controlling cultivar-specific labeling and limited-batch releases.
Durian chocolate fuses Theobroma cacao derivatives with freeze-dried or fresh durian pulp, typically maintaining 15-25% fruit content by mass to balance sulfuric volatility against cocoa butter stability; manufacturers employ conching temperatures below 50°C to preserve volatile esters. Dark chocolate formulations lead product type positioning due to higher cacao bitterness masking durian's pungency, while milk chocolate segments attract entry-level consumers through cream-buffered palatability. The gifting use case captures disproportionate margin as premium packaging and seasonal availability create price inelasticity.
Malaysia's JAKIM halal certification and Thailand's FDA food safety standards govern cross-border ingredient traceability and processing hygiene. ASEAN harmonized food standards are reducing technical barriers for inter-regional distribution but require adaptive reformulation for moisture-content thresholds. Stakeholders must monitor cultivar patent disputes and climate-driven harvest volatility as strategic inputs for capacity planning and supplier diversification.
Market Dynamics
Ingredient sourcing proximity is collapsing the traditional separation between durian orchards and chocolate manufacturing, forcing processors to co-locate with Pahang and Johor cultivation clusters to secure Musang King supply consistency.
Growth Catalysts
- ASEAN Harmonized Food Standards:Cross-border moisture-content thresholds are reducing technical barriers for inter-regional distribution between Thailand and Malaysia.
- Freeze-drying technology:Low-temperature dehydration below 50°C is preserving volatile sulfuric esters that previously degraded during conventional processing.
- Bangkok metropolitan concentration:Dense urban gifting culture is creating price-inelastic demand for premium seasonal packaging formats.
Market Restraints
- Fresh pulp spoilage rates:Durian's 72-hour post-harvest window forces expensive cold-chain logistics or reliance on lower-margin freeze-dried alternatives.
- JAKIM halal certification complexity:Malaysia's traceability requirements for cross-border ingredient sourcing add compliance layers that smaller processors cannot absorb.
- Single-origin cocoa dependency:Cacao butter stability requirements tie formulations to specific terroir partnerships with limited supplier pools.
Strategic Opportunities
- Indonesia underpenetration:Sumatra and Sulawesi durian cultivation zones lack integrated chocolate processing infrastructure, creating first-mover whitespace.
- E-commerce direct-to-gifting:Lunar New Year and Hari Raya seasonal peaks bypass traditional retail markups through platform-integrated fulfillment.
- EU Novel Food authorization pathway:Freeze-dried durian's stabilized shelf-life positions the ingredient for European specialty chocolate inclusion pending EFSA safety clearance.
Industry Challenges
- Volatile ester retention expertise:Conching temperature control requires specialized technicians scarce outside established Thai and Malaysian processing centers.
- Cultivar patent enforcement gaps:Musang King and Mao Shan Wang varietal claims create licensing disputes that disrupt supplier contracting.
- Reformulation for moisture thresholds:Cross-border distribution demands adaptive recipes that preserve texture across divergent ASEAN national standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Durian Chocolate Market |
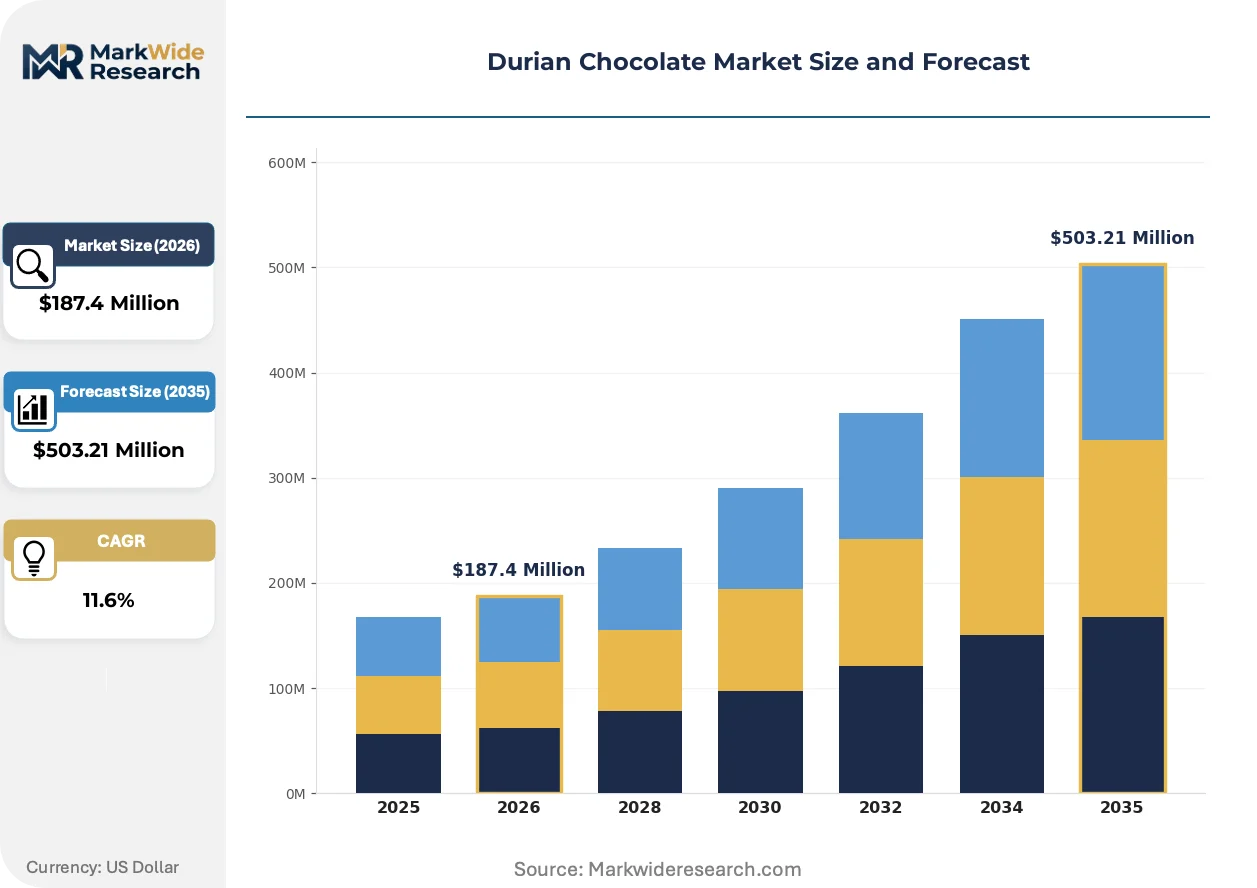
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Compound Chocolate Use Case: Gifting, Culinary Use, Direct Consumption, Baking Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Food Service Customer Type: Retail Consumers, Wholesalers, Restaurants, Chocolatiers |
| Companies Covered | Beryl's Chocolate & Confectionery Sdn. Bhd, Azaib Holdings Sdn. Bhd, Benns Chocolate, Durian Chocolate Co, Mao Shan Wang, Harriston, MK Durian Harvests Sdn. Bhd., Durians & Chocolates, Chocolate Monggo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Durian Chocolate Market Emerging Trajectories
Processing technology and certification frameworks are converging to reshape how durian chocolate moves from orchard to packaged gift, with implications for margin capture and geographic expansion.
Low-temperature conching is collapsing the traditional tradeoff between flavor preservation and production throughput. Artisanal manufacturers in Thailand's Chanthaburi province are adopting sub-50°C processing lines that retain volatile sulfur compounds previously lost to heat degradation. This technology is compressing the quality gap between small-batch craft production and industrial scale, enabling regional brands to challenge established gifting incumbents on sensory fidelity.
Malaysia's JAKIM halal certification requirements are tightening traceability mandates for cross-border ingredient sourcing. Processors must now document orchard-level provenance and handling protocols to maintain certification validity for export-bound production. Thai manufacturers serving Malaysian distribution channels are responding by integrating backward into Pahang cultivation partnerships, converting compliance burden into supply security.
Gifting procurement is fragmenting across channel types as e-commerce platforms capture seasonal peak demand previously concentrated in duty-free and hotel retail. Direct-to-consumer fulfillment during Lunar New Year and Hari Raya periods is displacing traditional wholesale relationships, particularly among younger buyers in Bangkok and Singapore. This shift is most visible in premium tier products where packaging customization and delivery timing matter more than shelf presence.
Durian Chocolate Market Segmentation
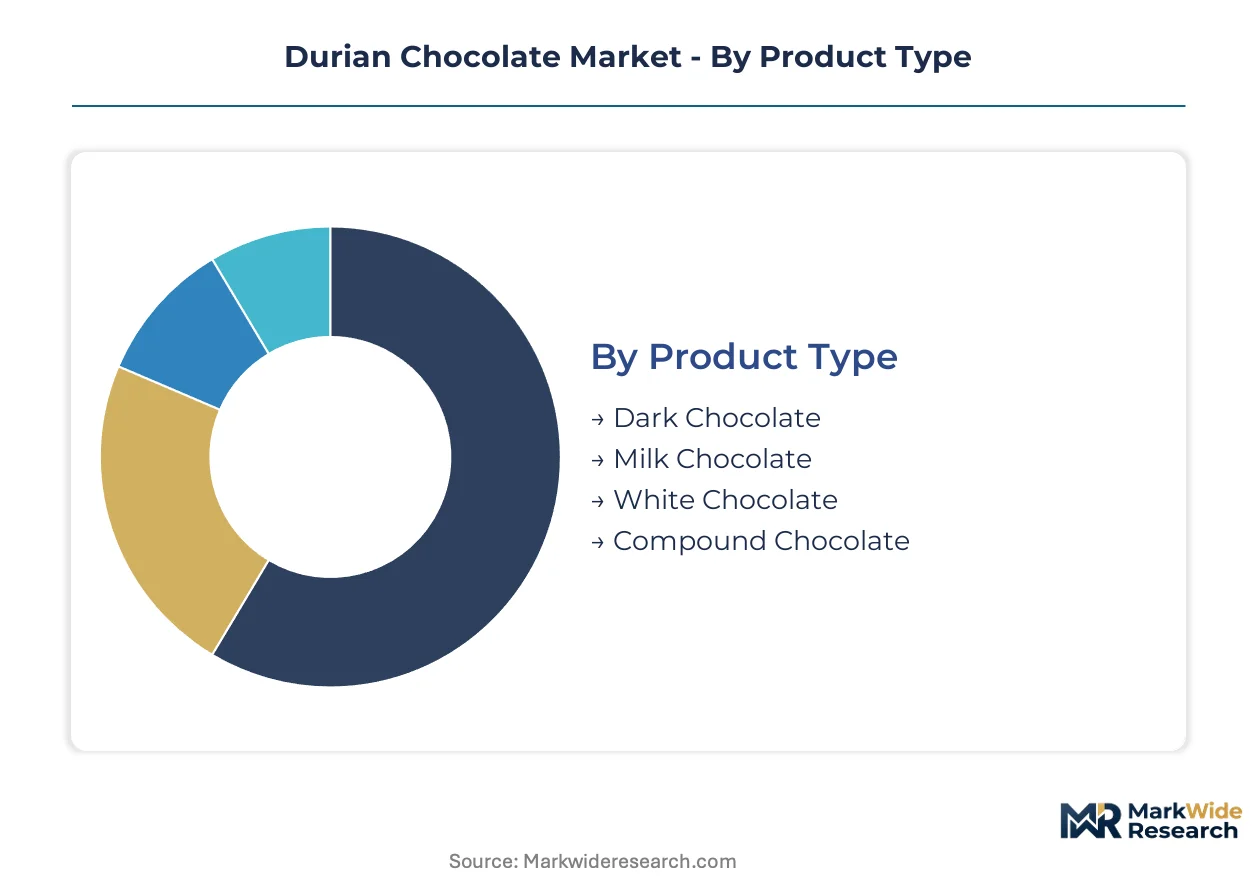
Durian chocolate manufacturers configure production lines around specific cacao-durian ratios and thermal profiles that vary sharply across product tiers. Segmentation reveals where margin concentrates and which demand pockets justify dedicated formulation investments.
Product Type:
Cost tier differentiation separates artisanal positioning from mass-market accessibility through cacao percentage and processing intensity.
- Dark Chocolate:Formulations with 70% cacao content or higher leverage bitterness to mask sulfuric volatility. Bangkok's premium gifting corridor absorbs disproportionate volume during Lunar New Year peaks.
- Milk Chocolate:Cream-buffered palatability attracts entry-level consumers in Johor Bahru's retail clusters. Lower cacao ratios reduce ingredient cost but demand precise conching temperature control to prevent dairy-durian flavor clash.
- White Chocolate:Cocoa butter base without cacao solids requires aggressive sulfuric ester masking through vanilla adjuncts. Limited to seasonal limited-batch releases.
- Compound Chocolate:Vegetable fat substitutions displace cocoa butter for price-sensitive food service applications. Malaysia's institutional catering channels drive procurement.
Dark chocolate holds installed capacity. Milk chocolate is rotating up the share rankings.
Use Case:
Application context determines packaging format, shelf-life engineering, and margin capture potential across the value chain.
- Gifting:Premium packaging and seasonal availability create price inelasticity. Direct-to-consumer platforms during Hari Raya displace traditional duty-free retail in Singapore.
- Culinary Use:Restaurant dessert applications in Bangkok's fine-dining sector demand consistent pulp texture for plating precision. Chefs specify freeze-dried granule size down to 2mm tolerance.
- Direct Consumption:Impulse purchases concentrate in airport retail and hotel gift shops. Single-serve formats dominate.
- Baking:Industrial users in Malaysia's commercial bakery sector require moisture-calibrated inclusions that withstand 180°C oven temperatures without volatile compound degradation.
Gifting commands absolute margin premiums. Culinary use is climbing the fastest as chef endorsements validate quality positioning.
Distribution Channel:
Volume throughput and customer acquisition cost diverge sharply between physical and digital fulfillment architectures.
- Online Stores:Platform-integrated fulfillment captures seasonal gifting peaks without retail markup absorption. Cold-chain logistics partnerships with third-party delivery networks enable fresh pulp variants previously restricted to physical retail.
- Supermarkets:Mass-market penetration in Thailand's Big C and Tesco Lotus chains requires standardized bar formats and halal certification compliance for cross-aisle placement.
- Specialty Stores:Curated assortments in Bangkok's Siam Paragon and Kuala Lumpur's Pavilion Mall justify premium pricing through sensory sampling infrastructure.
- Food Service:B2B procurement from restaurant groups and hotel chains demands bulk packaging and extended payment terms that strain working capital.
Specialty stores hold installed capacity. Online stores are expanding most quickly as platform economics reshape seasonal demand capture.
Customer Type:
Customer sophistication and order scale determine supplier relationship structures and technical service requirements.
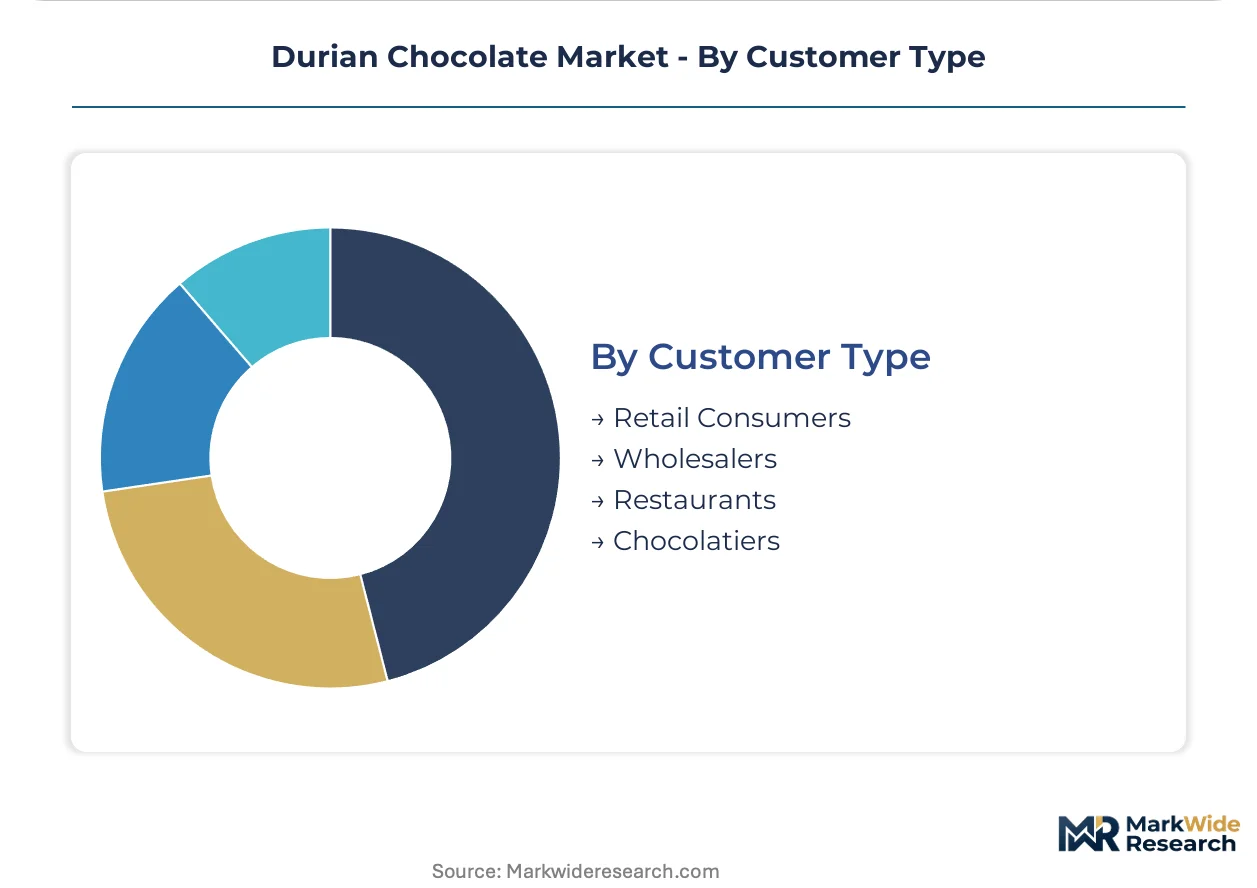
- Retail Consumers:Individual purchasers respond to cultivar-specific labeling and origin storytelling. Mao Shan Wang and Musang King varietal claims drive willingness-to-pay differentiation.
- Wholesalers:Regional distributors in ASEAN markets require reformulation flexibility to meet divergent national moisture-content thresholds.
- Restaurants:Bangkok's Michelin-recognized establishments source through direct orchard partnerships that bypass conventional distribution layers.
- Chocolatiers:Artisanal producers in Thailand's Chanthaburi province demand small-batch pulp processing with cultivar segregation to maintain single-origin positioning.
Retail consumers hold installed capacity. Chocolatiers are gaining share fastest as craft production scales through technology transfer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gifting demand in Bangkok exhibits near-perfect price inelasticity during Lunar New Year peaks, while Johor Bahru's retail corridors show sharp volume sensitivity to promotional depth. This elasticity gradient shapes where manufacturers anchor premium versus mass-market production lines.
Thailand
Bangkok's metropolitan gifting culture absorbs disproportionate premium volume during seasonal windows, with direct-to-consumer platforms capturing peak demand previously routed through duty-free retail. Thailand's FDA food safety standards govern cross-border ingredient traceability for export-bound production. Chanthaburi province hosts artisanal manufacturers adopting sub-50°C conching lines that narrow the quality gap between craft and industrial scale.
Malaysia
Johor Bahru's retail clusters drive milk chocolate procurement for entry-level consumers, while Pahang's integrated orchard-processing infrastructure secures Musang King supply consistency for premium tiers. JAKIM halal certification mandates orchard-level provenance documentation that Thai manufacturers must satisfy for Malaysian distribution access. The Pahang-Johor corridor is collapsing traditional separation between durian cultivation and chocolate manufacturing through co-located processing investments.
Singapore
Duty-free and hotel gift shop channels concentrate impulse purchases, though e-commerce platforms are displacing wholesale relationships among younger buyers during Hari Raya peaks. The country's national food safety regulator enforces strict import hygiene standards that filter supplier eligibility. Orchard Road's specialty retail infrastructure justifies premium positioning through sensory sampling investments that online channels cannot replicate.
Indonesia
Sumatra and Sulawesi durian cultivation zones remain substantially underpenetrated by integrated chocolate processing infrastructure, creating whitespace for first-mover capacity investments. The country's national food and drug regulator oversees import clearance for cross-border ingredient movements. Jakarta's emerging premium retail corridors show early gifting demand traction that could anchor regional distribution expansion if cold-chain partnerships mature.
Vietnam
Ho Chi Minh City's metropolitan consumer base demonstrates growing appetite for ASEAN-sourced specialty confectionery, though domestic durian chocolate manufacturing remains nascent. The country's national food safety authority administers certification frameworks for imported processed foods. Da Lat's highland durian cultivation zones offer potential upstream integration points if processing infrastructure follows plantation investment patterns.
Durian Chocolate Market Vendor Landscape
Vertically integrated orchard operators and specialist confectioners split the market into distinct capability camps. The vendor base concentrates around two strategic poles: those controlling cultivar-specific supply chains and those commanding premium retail channel access. Orchard-integrated manufacturers and craft chocolatiers represent the dominant archetypes, with contract processors occupying a residual middle tier. Competitive moves center on backward integration into Pahang cultivation partnerships and technology licensing for low-temperature conching systems.
Within the orchard-integrated tier, Beryl's Chocolate & Confectionery Sdn. Bhd and MK Durian Harvests Sdn. Bhd. exemplify the model of captive Musang King supply, while Benns Chocolate occupies a position emphasizing single-origin cocoa partnerships that complement volatile durian flavor profiles. These three companies anchor contrasting strategic approaches to ingredient security and premium positioning.
| Leading Market Players |
|---|
| Beryl's Chocolate & Confectionery Sdn. Bhd |
| Azaib Holdings Sdn. Bhd |
| Benns Chocolate |
| Durian Chocolate Co |
| Mao Shan Wang |
| Harriston |
| MK Durian Harvests Sdn. Bhd. |
| Durians & Chocolates |
| Chocolate Monggo |
| Others |
Supply Flow & Price Mechanics
The Bangkok-Johor Bahru freight corridor's cold-chain cost dynamics compress margins for fresh pulp variants while amplifying price premiums for freeze-dried alternatives, concentrating supply control among orchard-integrated processors and fragmenting downstream price differentiation across gifting versus retail tiers.
Pricing Analysis
Gifting packaging and seasonal fulfillment services drive lifetime value capture in this market. Three-tier pricing structure across premium cultivar-specific, standard single-origin, and economy compound chocolate levels segments buyer willingness-to-pay. Price differentiation rests on JAKIM halal certification tier and Musang King cultivar labeling authority. Cost compression in milk chocolate entry tiers is intensifying because Johor Bahru retail clusters absorb promotional depth. Culinary procurement through Bangkok's fine-dining sector shows least price sensitivity; impulse airport retail exhibits highest.
Supply Chain Analysis
Thailand's FDA cross-border ingredient traceability requirements and Malaysia's JAKIM halal documentation mandates function as de facto export controls limiting unqualified processor participation. Supply concentrates in Thailand's Chanthaburi province, Malaysia's Pahang-Johor corridor, and Singapore's re-export hub. Raw material dependencies include single-origin cocoa butter from specific terroirs, Musang King pulp with 72-hour harvest windows, and nitrogen-flush packaging films. Single-source vulnerability around Pahang orchard partnerships creates concentration risk. Distribution runs through e-commerce platform-integrated fulfillment during seasonal peaks, with specialty retail anchoring year-round premium placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freeze-drying technology sub-50°C represents a high-growth disruption vector, with ASEAN harmonized food standards creating regulatory inflection that collapses quality gaps between craft and industrial scale.
For Market Incumbents: Pre-empt craft challenger encroachment by locking Pahang orchard partnerships through long-term offtake structures rather than spot procurement. Secure JAKIM halal certification for export-bound production lines before Thai competitors complete backward integration. Channel control through direct-to-consumer platform integration during Hari Raya and Lunar New Year peaks defends margin position against retail markup displacement. For New Entrants and Emerging Players: Pursue Indonesia's Sumatra and Sulawesi cultivation zones where integrated chocolate processing infrastructure remains absent. Target Jakarta's emerging premium retail corridors through cold-chain logistics partnerships that enable fresh pulp differentiation. A chef endorsement go-to-market angle leverages Bangkok fine-dining validation to establish quality positioning before consumer brand recognition. For Investors and Strategic Acquirers: Carve-out targets emerge from Malaysian plantation conglomerates with underutilized downstream processing assets and Thai duty-free retail operators seeking manufacturing integration. Long-term viability centers on cultivar patent enforcement clarity and climate adaptation investment across the analysis window. Monitor EFSA Novel Food authorization progress for freeze-dried durian as European market access inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pahang Orchards | Captive Musang King supply secures JAKIM traceability compliance and cultivar-specific labeling rights. |
| Sub-50°C Conching Technology Licensing | Low-temperature processing lines narrow craft-industrial quality gaps for regional brand challengers. |
| E-Commerce Platform Partnership | Direct-to-consumer fulfillment during Hari Raya peaks bypasses traditional retail markup absorption. |
| EU Novel Food Authorization Pathway | EFSA clearance for freeze-dried durian unlocks European specialty chocolate inclusion whitespace. |
| Halal Certification Investment | JAKIM compliance enables cross-border distribution into Malaysia's premium gifting segments. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with durian orchard operators, chocolate manufacturing executives, and JAKIM certification officers; and secondary validation through Thailand FDA regulatory filings, Malaysia's Department of Standards documentation, ASEAN food harmonization protocols, and customs trade records. Bottom-up volume modeling triangulated against top-down value chain assessments.
Forecast inputs span product type segmentation across dark, milk, white, and compound chocolate tiers; use case differentiation between gifting, culinary, direct consumption, and baking applications; and distribution channel dynamics through online, supermarket, specialty retail, and food service pathways. CAGRs derive from growth driver quantification across the projection horizon, incorporating freeze-drying technology adoption curves and halal certification penetration rates.
Sensitivities concentrate around cultivar patent dispute resolutions, climate-driven harvest volatility, and EFSA Novel Food authorization timing. Forecasts reflect documented assumptions on ASEAN regulatory harmonization progress and cold-chain logistics partnership maturation. Material shifts in Musang King supply concentration or JAKIM traceability mandate enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
North America Chocolate Market
Confectionery
Truffle Chocolate Market
Confectionery
United Arab Emirates Sugar Confectionery Market
Confectionery
Milk Chocolate Market
Confectionery
Jellies and Gummies Market
Confectionery
Chocolate Couverture Market
Confectionery
United States and Europe Macarons Market
Confectionery
South America Compound Chocolate Market
Confectionery
United States Chocolate Market
Confectionery
Germany Chocolate Market
Confectionery
Low-Calorie Candy Market
Confectionery
Europe Caramel Chocolate Market
Confectionery
Africa Compound Chocolate Market
Confectionery
North America Sugar-Free Chewing Gum Market
Confectionery
United States Caramel Chocolate Market
Confectionery
Vegan Chocolate Confectionery Market