
 Cocoa and Chocolate Market | 2026-2036
Cocoa and Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Cocoa and Chocolate Market Analysis
West African cocoa grinding capacity is expanding as processors build facilities closer to origin to reduce logistics costs and improve bean freshness. Barry Callebaut leverages its integrated supply chain from bean sourcing to chocolate couverture to sustain margin capture across multiple price tiers. Cargill anchors its competitive position through direct farmer partnership programs that secure traceable certified cocoa volumes. Mars competes aggressively in the snacking segment with sustained investment in sustainable cocoa certification schemes.
Cocoa and chocolate comprise processed cacao bean derivatives including cocoa liquor, cocoa butter, cocoa powder, and finished chocolate products containing defined percentages of cocoa solids; the primary commercial purpose centers on flavor delivery, texture modification, and functional ingredient applications across food systems. Chocolate bars occupy the largest value share among product types due to established consumer purchasing frequency and premiumization trends in dark chocolate offerings. Cocoa powder demonstrates structural growth momentum as clean-label baking demand rises among food manufacturers and artisan bakeries seeking intense cocoa flavor without added fat content.
The FDA maintains standards of identity for chocolate products in the United States, while the EU enforces the Deforestation Regulation requiring geolocation traceability for cocoa imports into European markets. Food manufacturers must navigate diverging compliance frameworks that elevate documentation costs but simultaneously create market access barriers for non-compliant suppliers. Stakeholders should monitor evolving sustainability disclosure requirements and origin certification premiums as decisive variables in procurement strategy and supplier selection.
Market Dynamics
The EU Deforestation Regulation mandates geolocation traceability for all cocoa entering European markets, forcing processors to restructure sourcing documentation and supplier qualification protocols from bean origin through finished product.
Growth Catalysts
- Bean-to-bar traceability mandates:The EU Deforestation Regulation creates compliance-driven demand for certified sustainable cocoa, expanding the addressable market for verified supply chains.
- Artisan bakery channel expansion:Specialty patisseries and craft bakeries require high-cocoa-mass couverture with defined flavor profiles, pulling premium processing capacity.
- West African grinding infrastructure:Origin-country processing investments reduce freight costs and preserve volatile aromatics, shifting value capture toward Côte d'Ivoire and Ghana.
Market Restraints
- Input cost volatility:Cocoa butter prices fluctuate with weather patterns in the Guinean forest belt, compressing margin predictability for chocolate manufacturers.
- Supply concentration risk:Over sixty percent of global bean output originates in Côte d'Ivoire and Ghana, creating systemic exposure to regional political instability and crop disease.
- Regulatory friction:Divergent FDA and EU standards of identity for chocolate products force dual formulation runs, elevating production complexity.
Strategic Opportunities
- Underpenetrated origin processing:Indonesia and Ecuador offer untapped grinding capacity expansion with favorable tariff positions for Asian market access.
- Functional ingredient applications:Cocoa flavanol extraction for nutraceuticals opens pharmaceutical and dietary supplement channels beyond conventional confectionery.
- Direct-to-patisserie distribution:Bypassing traditional wholesale intermediaries allows processors to capture service premiums through technical consulting and recipe co-development.
Industry Challenges
- Certification timeline compression:The EU Deforestation Regulation's full implementation deadline pressures traders to complete supplier audits and geolocation mapping across fragmented smallholder networks.
- Flavor chemist scarcity:Specialized expertise in cocoa fermentation science and roast profile optimization concentrates among aging European and North American professionals, constraining product innovation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocoa and Chocolate Market |
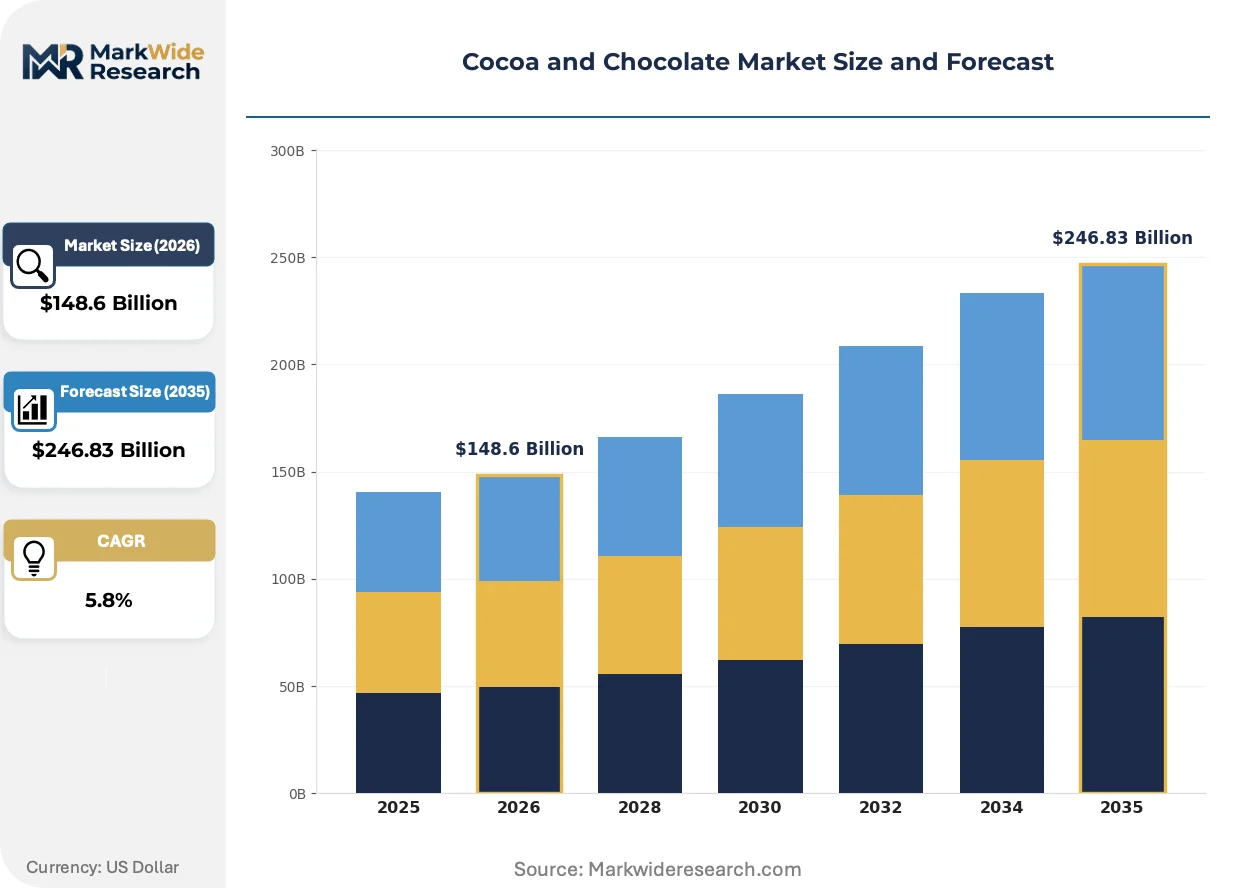
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $246.83 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cocoa Powder, Chocolate Bars, Chocolate Spreads, Baking Chocolate End User: Retail Consumers, Food Manufacturers, Bakeries, Confectioneries Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Form: Solid, Liquid, Powder, Coated |
| Companies Covered | Barry Callebaut, Cargill, Mondelez International, Mars, Nestlé, Ferrero, Hershey Company, Olam, ECOM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocoa and Chocolate Market Emerging Trajectories
Processing technology and regulatory disclosure requirements are compressing traditional supply chain tiers while pulling new functionality from cocoa beyond conventional confectionery applications.
Fermentation control systems using sensor arrays and machine learning algorithms is integrating into post-harvest operations at cooperative and estate levels. Medium-scale processors in Ecuador and Madagascar deploy these technologies to standardize flavor precursors and reduce batch variation. The technology is integrating quality assurance directly into origin infrastructure, reducing reliance on European and North American re-processing.
The EU Deforestation Regulation's geolocation and due diligence requirements impose documentary burdens on all cocoa traders supplying European food manufacturers. Compliance costs concentrate among smaller importers lacking dedicated sustainability departments. Mid-tier chocolate brands face the steepest adaptation curve as they requalify entire supplier bases before the enforcement window closes.
Buyer consolidation among multinational confectionery groups has compressed supplier rosters, favoring processors with integrated sustainability certification and regional grinding presence. Artisan chocolate makers and specialty roasters now source directly from origin cooperatives through transparent trade platforms, disintermediating traditional commodity brokers. This channel bifurcation is most visible in North American and Western European urban markets where provenance storytelling commands retail price premiums.
Cocoa and Chocolate Market Segmentation
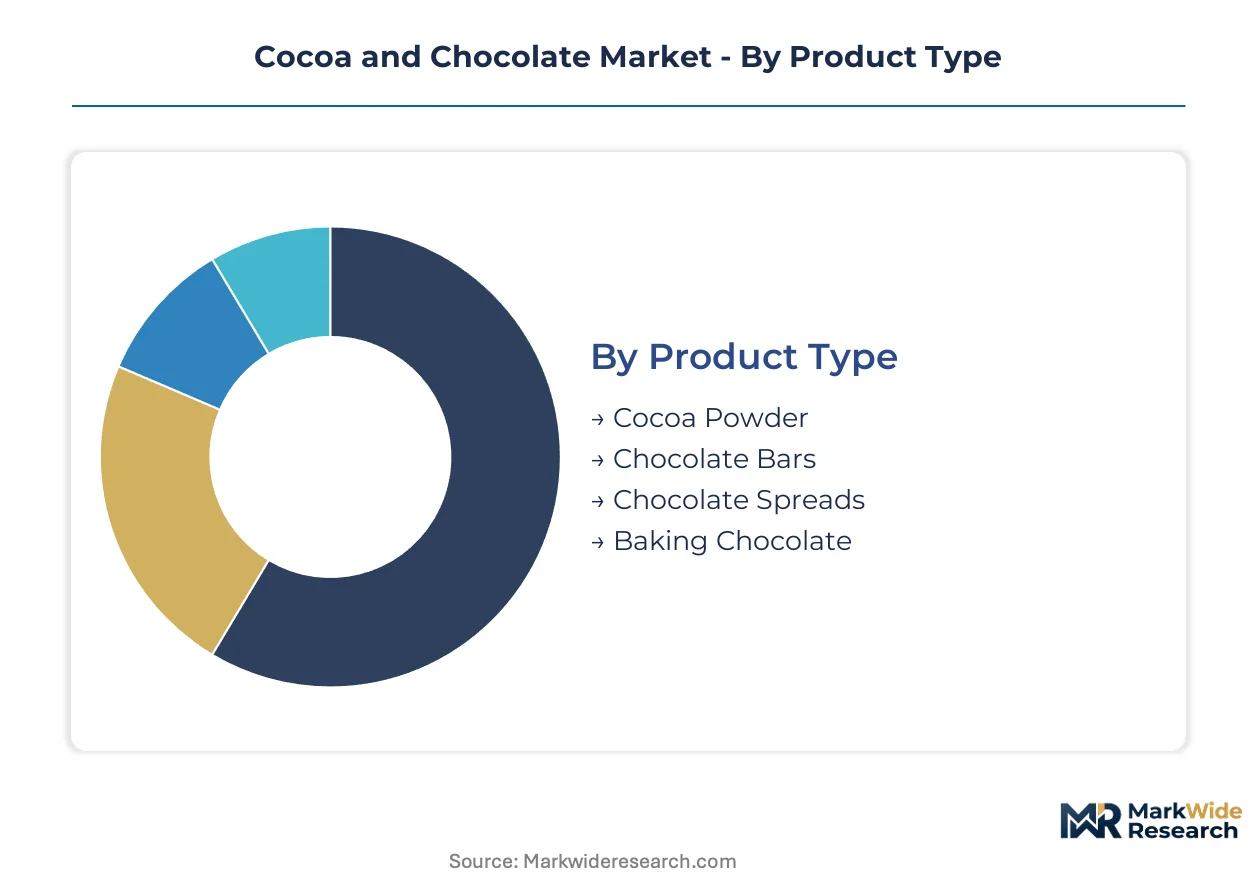
Segmentation in the cocoa and chocolate market reveals distinct margin architectures and procurement behaviors across product formats and buyer categories. Understanding these divides enables processors to align capacity investments with the diverging requirements of commodity-scale food manufacturers versus premium artisan channels.
Product Type:
Volume concentrates in mass-market formats while premiumization reshapes the high-cocoa-mass tier.
- Chocolate Bars:Finished chocolate products containing defined cocoa solids percentages, ranging from milk chocolate standards to high-cocoa dark formulations. North American and Western European retail shelves favor portion-controlled single-serve bars, with dark chocolate variants commanding shelf-space expansion due to clean-label positioning and elevated cacao content claims.
- Cocoa Powder:Press cake-derived powder with fat content typically ranging from 10-24%, classified by alkalization level and color intensity. Food manufacturers in the United States and Germany source natural and Dutch-processed grades for bakery and beverage applications where intense cocoa flavor without added fat is specified.
- Chocolate Spreads:Emulsified cocoa-fat-sugar suspensions with defined viscosity and spreadability parameters. European breakfast culture sustains baseline demand while Asian market penetration remains formulation-dependent.
- Baking Chocolate:Unsweetened or minimally sweetened chocolate mass with high cocoa liquor content, sold in block or chip form. Artisan bakeries in France and Belgium specify origin-designated couverture for tempering applications.
Today's leader: Chocolate Bars. Tomorrow's challenger: Cocoa Powder.
End User:
Procurement sophistication varies sharply between price-takers in commodity channels and specification-drivers in premium segments.
- Food Manufacturers:Industrial-scale buyers purchasing cocoa liquor, butter, and powder for formulated products including ice cream, biscuits, and ready-to-drink beverages. CPG companies in the United States negotiate annual contracts with fixed-price or futures-linked structures, prioritizing supply security over origin traceability for standard-grade inputs.
- Retail Consumers:Individual purchasers selecting finished chocolate products through retail and digital channels. Japanese and Swiss consumers demonstrate the highest per-capita spending on premium dark chocolate with single-origin labeling.
- Bakeries:Artisan and commercial operations requiring tempering-stable couverture with defined crystallization properties. French and Belgian patisseries specify Grand Cru designations and vintage harvests for entremets and bonbon production.
- Confectioneries:Chocolate-focused manufacturers producing pralines, truffles, and enrobed items. Swiss and Italian producers maintain in-house conching capabilities while sourcing base liquor from West African processors.
Food Manufacturers dominate tonnage. Bakeries expand most quickly on a value-per-kilogram basis.
Distribution Channel:
Channel selection determines margin capture and brand control intensity for processors.
- Supermarkets:Mass retail including hypermarkets and grocery chains carrying mainstream chocolate brands and private-label alternatives. German and UK retailers operate sophisticated own-brand chocolate programs with direct sourcing from West African grinders.
- Online Retail:Direct-to-consumer and marketplace platforms enabling subscription models and limited-edition releases. North American craft chocolate makers leverage Shopify and Amazon for national distribution without wholesale intermediaries.
- Specialty Stores:Fine food retailers, chocolate boutiques, and department store confectionery counters. Paris and Tokyo maintain the densest concentration of single-origin bean-to-bar specialists with in-house roasting.
- Wholesale:Foodservice distributors and ingredient suppliers serving manufacturers and foodservice operators. Dutch and Belgian wholesalers aggregate volumes for redistribution across European processing clusters.
Supermarkets anchor volume. Online Retail gains share fastest in premium segments.
Form:
Physical state dictates handling infrastructure and application flexibility across the value chain.
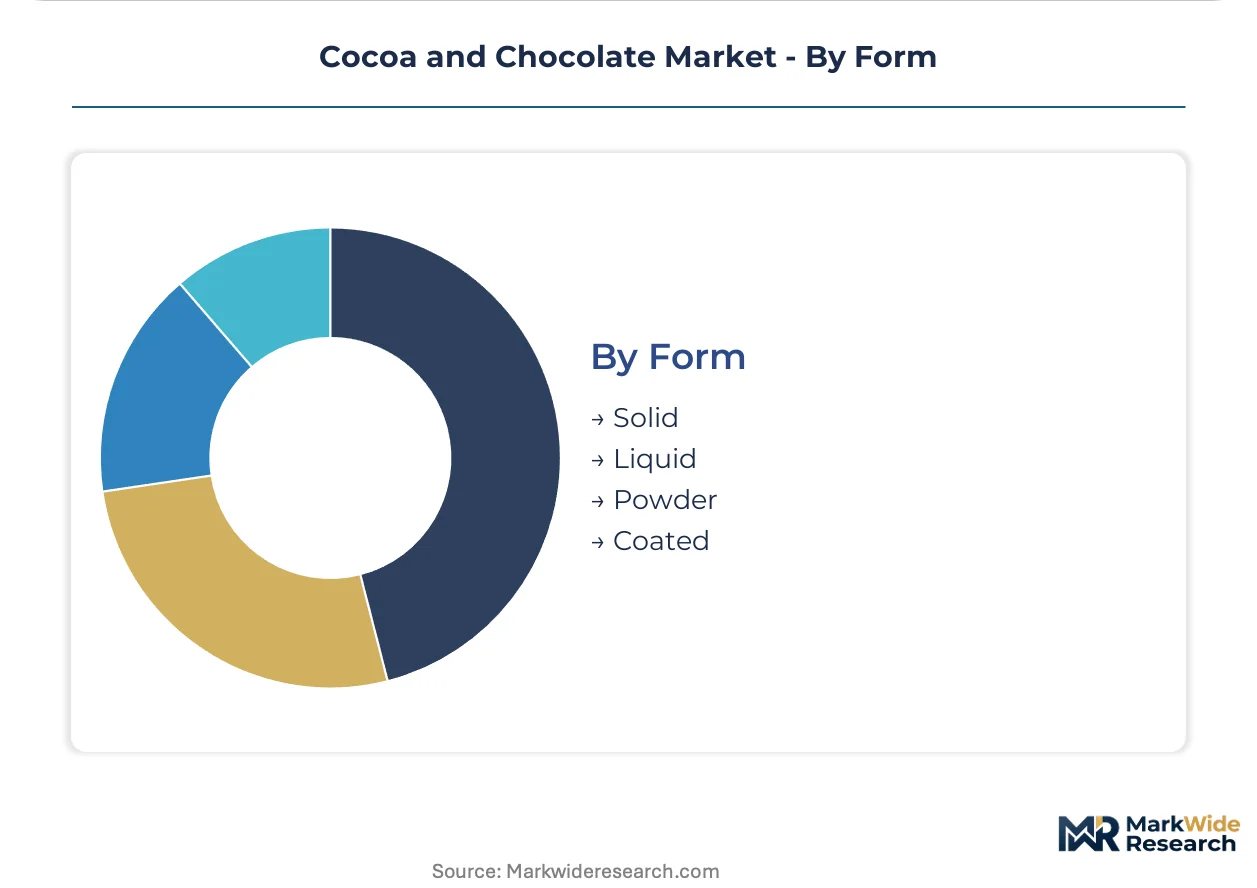
- Solid:Tempered chocolate in block, button, or bar form requiring controlled melting for industrial or artisan use. Standard inventory format for European couverture houses supplying chocolatiers.
- Liquid:Bulk-delivered chocolate mass maintained in molten state through heated tanker or silo systems. Industrial bakeries in the United States and Germany favor liquid delivery for continuous enrobing lines.
- Powder:Spray-dried or ground cocoa products for dry blending in bakery, dairy, and beverage applications. Instant drink manufacturers in Japan and Brazil specify agglomerated powder for cold-water solubility.
- Coated:Center-filled or enrobed products including dragées, nuts, and dried fruits in chocolate shell. Swiss and Italian specialists dominate this value-added tier with proprietary panning technology.
Solid form leads industrial procurement. Coated products climb fastest on value-added metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping cocoa processing geography as compliance-cost differentials between the EU Deforestation Regulation zone and non-EU markets redirect investment flows toward origin-country grinding capacity.
Côte d'Ivoire
Abidjan and San-Pédro anchor West Africa's largest grinding cluster as processors build facilities to capture value at origin. The country's investment promotion agency offers tax holidays for cocoa processing ventures exceeding defined capital thresholds. Industrial zones around Abidjan now host multiple bean-to-liquor operations supplying European couverture houses.
Ghana
Tema and Takoradi concentrate grinding infrastructure serving both regional African markets and export-oriented chocolate manufacturers. The Ghana Cocoa Board maintains quality premiums through regulated fermentation standards and buyer licensing systems. Processing investments from multinational traders are expanding local butter and powder output for Asian confectionery markets.
Germany
Cologne and Hamburg maintain Europe's densest chocolate manufacturing concentration despite rising compliance burdens from the EU Deforestation Regulation. The Federal Office for Agriculture and Food enforces due diligence documentation requirements that elevate procurement costs for mid-tier processors. Industrial bakeries in Bavaria and North Rhine-Westphalia drive specialized couverture demand for premium pastry applications.
United States
Pennsylvania and Illinois host major chocolate manufacturing clusters serving retail and foodservice channels. FDA standards of identity for chocolate products diverge from EU definitions, forcing dual-formulation production for exporters. Chicago-area processors supply liquid chocolate through heated tanker systems to industrial bakeries across the Midwest.
Indonesia
South Sulawesi and East Java offer expanding grinding capacity with favorable tariff access to ASEAN and Chinese markets. The country's national standards body certifies cocoa processing facilities for export eligibility to regulated markets. Makassar-based operations are scaling powder and butter production for instant beverage manufacturers in Japan and South Korea.
Cocoa and Chocolate Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue traceability-certified premium positioning through direct farmer partnerships and origin-country processing investments. The market structures around three tiers: integrated bean-to-bar multinationals, regional grinding specialists, and artisan craft chocolate makers. Strategic archetypes include sustainability-certification leaders, origin-proximity processors, and flavor-profile specialists. Competitive moves concentrate on backward integration into West African grinding assets and geographic diversification toward Southeast Asian supply bases.
Within the integrated processing tier, Barry Callebaut and Cargill represent archetypes of supply-chain control spanning bean sourcing through finished couverture. Mars occupies a position exemplifying sustained investment in sustainable certification schemes and snacking-segment concentration. These three entities anchor competitive dynamics through divergent approaches to farmer partnership depth, regional grinding presence, and end-market specialization.
| Leading Market Players |
|---|
| Barry Callebaut |
| Cargill |
| Mondelez International |
| Mars |
| Nestlé |
| Ferrero |
| Hershey Company |
| Olam |
| ECOM |
| Others |
Supply Flow & Price Mechanics
The EU Deforestation Regulation gates both qualified supply and premium-tier pricing access by mandating geolocation traceability and due diligence documentation for all cocoa entering European markets. Compliance costs concentrate among smaller traders lacking dedicated sustainability departments, while certified-origin beans command measurable premiums over conventional grades in procurement auctions.
Pricing Analysis
Distributor margins compress as bean-to-bar traceability mandates elevate documentation costs through the value chain. Three-tier pricing structure across premium, standard, and economy levels differentiates certified single-origin lots from bulk West African grades and industrial commodity inputs. Price differentiation stems from certification level and volume scale, with artisan bakeries least price-sensitive and mass-market food manufacturers most responsive to input cost shifts. Cost compression in the standard tier is intensifying because mid-tier brands face the steepest adaptation curve for supplier requalification.
Supply Chain Analysis
Origin-country grinding mandates in Côte d'Ivoire and Ghana are reshaping sourcing patterns by incentivizing local butter and powder production through tax holidays and regulated quality premiums. The supply chain draws from West African bean output, Southeast Asian processing capacity in Indonesia, and European couverture manufacturing in Germany and Switzerland. Raw material dependencies center on cocoa liquor, cocoa butter, and cocoa powder grades. Single-source vulnerability concentrates in the Guinean forest belt where political instability and crop disease threaten systemic disruption. Distribution runs through wholesale intermediaries serving industrial bakeries, direct-to-patisserie channels for artisan accounts, and mass retail for finished chocolate products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cocoa and chocolate market represents a late-cycle quality story as demand shifts toward high-cocoa-mass dark chocolate with single-origin labeling and clean-label positioning across North American and Western European retail shelves.
For Market Incumbents: Deepen backward integration into West African grinding assets to capture origin premiums and reduce freight exposure. Expand fermentation control technology deployment at cooperative levels to standardize flavor precursors. Certification investment serves as the critical lever against emerging entrant competition in the traceability-certified tier.
For New Entrants and Emerging Players: Begin with direct-to-patisserie distribution in underpenetrated North American urban markets where provenance storytelling commands retail price premiums. Target specialty store channels with subscription-based limited-edition releases. The most penetrable segment remains artisan bakery supply, with technical consulting and recipe co-development as the primary go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for regional grinding specialists with established EU Deforestation Regulation compliance infrastructure because certification timeline compression disadvantages fragmented smallholder-dependent traders. The long-term viability window favors processors with integrated sustainability certification and origin-country processing presence. Watch for inflection signals in cocoa butter price volatility relative to Asian confectionery demand growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origin Grinding | Captures value at source in Abidjan and San-Pédro while reducing logistics exposure. |
| Direct-to-Patisserie Distribution Launch | Bypasses wholesale intermediaries to capture service premiums through technical consulting. |
| Fermentation Control Technology Deployment | Integrates quality assurance at Ecuador and Madagascar cooperative levels using sensor arrays. |
| Sustainability Certification Program | Secures EU Deforestation Regulation compliance for continued European market access. |
| Functional Ingredient Extraction Capacity | Opens pharmaceutical and nutraceutical channels beyond conventional confectionery applications. |
Methodological Framework
Bottom-up food manufacturer and bakery channel modeling reconciled against top-down cocoa grinding capacity tracking forms the analytical core of this study. Primary interviews with cocoa traders, cooperative managers, chocolate manufacturing procurement leads, and patisserie supply coordinators combined with secondary validation from customs records, FDA standards of identity documentation, EU Deforestation Regulation implementation guidance, and industry association processing statistics. Triangulation between supply-side facility audits and demand-side procurement pattern analysis ensures dimensional consistency across volume and value estimates.
Historical trendline analysis established baseline growth trajectories across the projection horizon. The analytical framework models segmentation dimensions including product type, end user category, distribution channel, and physical form. CAGRs derive from fitted trend extrapolation adjusted for regulatory implementation timelines and origin-country infrastructure investment cycles. Forecast inputs incorporate cocoa butter price volatility patterns and certified cocoa premium trajectories observed in procurement auction data.
Several conditions sit outside the modeled scope, including abrupt political disruptions in West African origin countries, novel crop disease emergence, and fundamental reformulation of FDA chocolate standards of identity. Forecasts reflect assumptions about EU Deforestation Regulation enforcement consistency and sustained Asian confectionery demand growth. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
India Chocolate Market
Confectionery
Low Calorie Treats Market
Confectionery
Bangladesh Candy Market
Confectionery
South America Chocolate Market
Confectionery
Xylitol Lollipops Market
Confectionery
Low Calorie Nutella Market
Confectionery
United States and Europe Macarons Market
Confectionery
Salted Caramel Products Market
Confectionery
North America Chocolate Market
Confectionery
United States Chocolate Market
Confectionery
Europe Sugar Confectionery Market
Confectionery
Real and Compound Chocolate Market
Confectionery
India Industrial Chocolate Market
Confectionery
Macarons Market
Confectionery
North America Compound Chocolate Market
Confectionery
Chocolate Couverture Market